
 Coconut Milk Derivatives Market | 2026-2036
Coconut Milk Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Milk Derivatives Market Outlook
Buyer concentration in food manufacturing is decoupling from traditional dairy supply chains as plant-based formulators diversify their vendor bases. Thai Agri Foods Public Company Limited anchors procurement relationships across Southeast Asian processing hubs. McCormick & Company leverages its spice and flavor infrastructure to control distribution of coconut-derived ingredients in North American retail channels. Danone S.A. specializes in dairy-alternative formulations that compete directly with conventional milk derivatives on ingredient labels.
Coconut milk derivatives comprise the extracted, processed, and standardized outputs from mature coconut endosperm, including lipid-rich cream, spray-dried powder, concentrated protein suspensions, and refined oil fractions with specific fatty acid profiles. These derivatives serve as functional emulsifiers, texturizers, and flavor carriers across formulated food systems. Coconut cream dominates margin pools in foodservice and industrial channels due to its higher fat content and premium positioning in curry and dessert applications. Coconut powder occupies the fastest-expanding segment as spray-drying technology improves solubility for beverage and bakery manufacturers seeking shelf-stable alternatives.
Food Standards Australia New Zealand (FSANZ) and the FDA enforce allergen labeling and import sanitation standards that shape product specifications for coconut derivatives entering regulated markets. The EU Green Deal's deforestation-free supply chain requirements are forcing exporters to document provenance and sustainable harvesting practices. Stakeholders must monitor evolving certification thresholds for organic and fair-trade claims as retail buyers harden procurement criteria.
Market Dynamics
The EU Green Deal's deforestation-free supply chain mandates are compressing procurement timelines for coconut derivatives, forcing exporters to document provenance while food manufacturers scramble to certify alternative sourcing before enforcement deadlines.
Growth Catalysts
- EU F-Gas Regulation:Tightening processing standards for imported coconut derivatives accelerates investment in low-emission spray-drying infrastructure across Southeast Asian processing hubs.
- Plant-based dairy alternatives:Food manufacturers are diversifying vendor bases away from conventional dairy supply chains, creating dedicated procurement lanes for coconut-derived emulsifiers and texturizers.
- Spray-drying technology:Solubility improvements in coconut powder production unlock beverage and bakery applications previously blocked by shelf-stability limitations.
Market Restraints
- Input cost volatility:Mature coconut endosperm supply fluctuates with monsoon patterns in Thailand and the Philippines, compressing margin pools for cream processors.
- Supply concentration risk:Processing gravity centers on Southeast Asian clusters, exposing buyers to port congestion and climate-induced harvest variability.
- Allergen labeling friction:FDA and FSANZ sanitation standards require redundant testing protocols that extend import clearance timelines for unstandardized shipments.
Strategic Opportunities
- Organic certification tailwinds:Retail buyers are hardening procurement criteria around fair-trade claims, creating premium positioning for documented sustainable harvesting practices.
- Convergence of lipid fractionation and precision fermentation:Hybrid processing routes enable customized fatty acid profiles for functional food applications.
- Direct-to-manufacturer channels:Foodservice operators are bypassing traditional ingredient distributors to secure volume contracts with Thai and Filipino processors.
Industry Challenges
- Skill gaps in spray-drying optimization:Formulated food systems require precise particle size distribution that few operators can consistently achieve.
- Capex intensity for deforestation traceability:Blockchain-enabled provenance systems demand upfront investment that mid-scale exporters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Milk Derivatives Market |
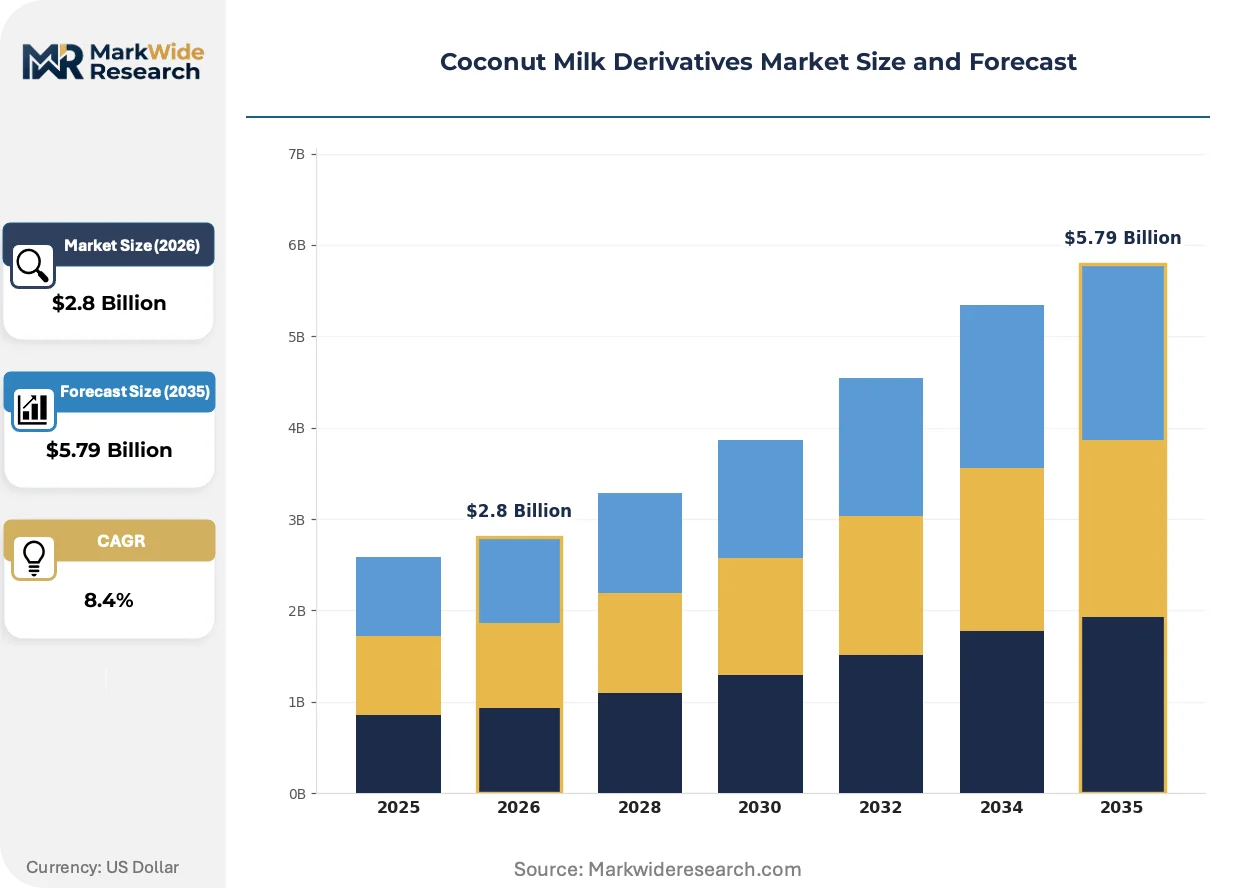
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Cream, Coconut Powder, Coconut Concentrate, Coconut Oil Application: Dairy Alternatives, Bakery Products, Ice Cream, Beverages End User: Food Manufacturers, Restaurants, Retailers, Households Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | McCormick & Company, Inc., Vita Coco, Thai Agri Foods Public Company Limited, Nestlé S.A., Goya Foods, Inc., Theppadungporn Coconut Co., Ltd., Danone S.A., Thai Coconut Public Company Limited, Celebes Coconut Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Milk Derivatives Market Strategic Shifts
Processing technology and regulatory documentation requirements are restructuring competitive advantage in coconut derivatives, with spray-drying advances and supply chain transparency systems emerging as the primary battlegrounds for differentiation.
Spray-drying equipment with integrated lipid encapsulation is overtaking conventional drum-drying for coconut powder production. Beverage manufacturers in North America and Europe are adopting these powders at accelerated pace due to improved cold-water solubility. The technology is overtaking legacy drying methods in margin-sensitive applications where reconstitution speed determines formulation viability.
EU Green Deal deforestation-free requirements are forcing exporters to deploy satellite-verified traceability systems. Thai and Filipino processors must now document harvest coordinates and chain-of-custody records before customs release. Coconut cream and oil fractions face the strictest scrutiny, with organic-certified supply chains adapting faster than conventional counterparts.
Food manufacturers are consolidating vendor relationships around processors with integrated quality laboratories. Direct technical collaboration replaces spot-market purchasing for curry and dessert applications. This pattern is most visible in European retail channels, where private-label buyers demand batch-level fatty acid specifications.
Coconut Milk Derivatives Market Segmentation
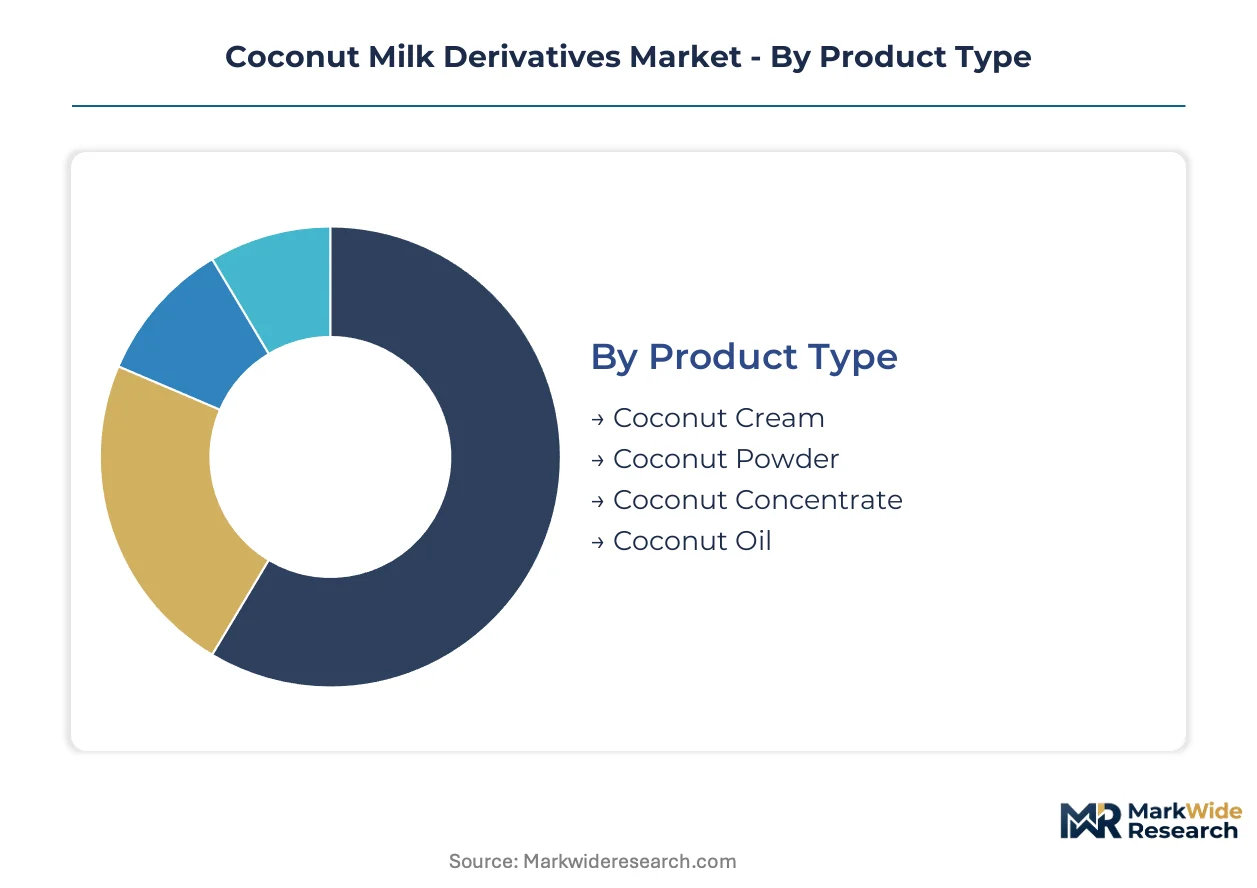
Coconut milk derivatives fragment across four dimensions that determine margin capture and procurement complexity. Product specifications dictate processing investment requirements while application channels shape shelf-life and formulation standards. End-user concentration and distribution reach complete the value chain architecture.
Product Type:
Buyers in this category differentiate by fat content requirements and reconstitution behavior in formulated food systems.
- Coconut Cream:Lipid-rich emulsion extracted from mature coconut endosperm with 20-25% fat content serves as the functional base for curry sauces and dessert formulations. Foodservice operators in Thailand and the Philippines anchor procurement volume due to traditional cuisine dependencies and established supply relationships with regional processors.
- Coconut Powder:Spray-dried particulate with encapsulated lipid fractions enables shelf-stable beverage and bakery applications previously blocked by reconstitution failures. North American and European manufacturers are accelerating adoption as cold-water solubility improvements from Thai processing hubs unlock ready-to-drink formulation viability.
- Coconut Concentrate:Reduced-moisture suspension with standardized solids content supports industrial-scale dairy alternative production.
- Coconut Oil:Refined lipid fraction with specific fatty acid profiles serves cosmetic and specialized food applications.
Volume sits with Coconut Cream; growth tilts toward Coconut Powder.
Application:
Formulation requirements in this category range from thermal stability for UHT processing to freeze-thaw tolerance for frozen dessert systems.
- Dairy Alternatives:Plant-based milk and yogurt formulations compete directly with conventional dairy on ingredient labels. Danone S.A. and specialized formulators in Europe drive specification tightening around protein content and emulsion stability.
- Bakery Products:Coconut powder substitutes for dairy solids in gluten-free and vegan formulations where moisture retention and crumb structure determine product acceptance.
- Ice Cream:Coconut cream provides fat structure and flavor carrier functions in premium frozen dessert segments.
- Beverages:Ready-to-drink applications demand instant solubility that only advanced spray-drying infrastructure can deliver consistently.
Revenue concentrates in Dairy Alternatives; steepest expansion trajectory appears in Beverages.
End User:
Procurement scale and technical collaboration intensity separate stakeholders in this category.
- Food Manufacturers:Industrial buyers specify batch-level fatty acid profiles and demand integrated quality laboratories from vendor partners. Direct technical collaboration replaces spot-market purchasing for high-volume formulations.
- Restaurants:Foodservice operators bypass traditional distributors to secure volume contracts with Thai and Filipino processors, concentrating procurement in Southeast Asian supply clusters.
- Retailers:Private-label buyers harden procurement criteria around organic certification and deforestation-free documentation under EU Green Deal mandates.
- Households:Consumer-packaged goods purchases through retail channels show sensitivity to fair-trade claims and sustainable harvesting verification.
Contract value aggregates with Food Manufacturers; margin expansion favors Restaurants.
Distribution Channel:
Channel selection in this category reflects buyer urgency, order scale, and certification documentation requirements.
- Online Retail:Direct-to-consumer platforms enable specialty and organic-certified product access for households and small-scale food manufacturers seeking documented provenance.
- Supermarkets:Mass retail channels consolidate volume for standardized coconut cream and powder SKUs with established brand recognition.
- Specialty Stores:Ethnic grocery and health food retailers curate premium and organic-certified derivatives for formulation-conscious buyers.
- Wholesalers:Traditional distribution intermediaries serve restaurants and mid-scale manufacturers with consolidated procurement from Southeast Asian processing hubs.
Throughput dominates in Supermarkets; channel share gains fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food manufacturers in Thailand and the Philippines anchor procurement volume for coconut milk derivatives, while North American and European buyers accelerate specification tightening around deforestation-free documentation and spray-drying quality standards.
Thailand
Traditional curry and dessert applications sustain foodservice demand across Bangkok and central plains processing zones. The Thai Industrial Standards Institute enforces TISI certification for export-grade coconut cream and powder specifications. Samut Sakhon and Ratchaburi provinces concentrate spray-drying infrastructure upgrades as processors invest in cold-water solubility capabilities for beverage export contracts.
Philippines
Dairy-alternative formulators in Quezon City and Cebu procurement offices specify batch-level fatty acid profiles for industrial-scale production. The Bureau of Agriculture and Fisheries Standards mandates hazard analysis protocols for coconut derivative exports under the Food Safety Act. Davao Region and Southern Tagalog clusters expand organic-certified harvesting documentation to satisfy EU Green Deal traceability requirements.
United States
Beverage manufacturers in California and New York Metro accelerate coconut powder adoption for ready-to-drink plant-based formulations. FDA allergen labeling enforcement shapes import sanitation standards and redundant testing protocols for Southeast Asian shipments. Los Angeles and Chicago distribution hubs consolidate volume for foodservice operators bypassing traditional ingredient distributors.
Germany
Private-label buyers in Hamburg and Munich harden procurement criteria around organic certification and satellite-verified provenance systems. EU F-Gas Regulation compliance deadlines compress processing investment timelines for imported derivatives. Bavarian and North Rhine-Westphalia food manufacturers integrate quality laboratories into vendor relationships for direct technical collaboration on emulsion stability specifications.
Indonesia
Cosmetic and specialized food applications drive demand for refined coconut oil fractions in Jakarta and Surabaya formulation centers. The National Agency of Drug and Food Control enforces halal certification and import documentation standards for derivative exports. Sulawesi and Sumatra processing clusters face pressure to deploy blockchain-enabled chain-of-custody records under tightening EU deforestation-free mandates.
Coconut Milk Derivatives Market Competitive Environment
Southeast Asian producers anchor one tier; North American and European specialists hold distribution and formulation expertise in retail and foodservice channels. The vendor base concentrates around integrated processing hubs in Thailand and the Philippines, with mid-scale exporters struggling to finance traceability infrastructure. Three archetypes dominate: vertically integrated plantation-to-powder operators, flavor-house distributors controlling retail shelf placement, and dairy-alternative formulators competing on ingredient label positioning. Competitive moves center on M&A for spray-drying capacity and strategic partnerships for deforestation-free certification documentation.
Within the integrated processing tier, Thai Agri Foods Public Company Limited and Thai Coconut Public Company Limited represent plantation-to-distribution operators with captive supply relationships across Southeast Asian hubs. McCormick & Company anchors North American retail channel control through spice and flavor infrastructure leverage. Danone S.A. occupies the dairy-alternative formulation specialist position, competing directly with conventional milk derivatives on ingredient labels in European and North American markets.
| Leading Market Players |
|---|
| McCormick & Company, Inc. |
| Vita Coco |
| Thai Agri Foods Public Company Limited |
| Nestlé S.A. |
| Goya Foods, Inc. |
| Theppadungporn Coconut Co., Ltd. |
| Danone S.A. |
| Thai Coconut Public Company Limited |
| Celebes Coconut Corporation |
| Others |
Value Chain & Pricing Dynamics
Food manufacturers consolidating procurement around Southeast Asian processing hubs command volume-based contract structures that compress spot-market premiums for coconut cream and powder. Their specification tightening around EU Green Deal documentation and spray-drying quality standards forces tiered pricing separation between certified and conventional supply chains.
Pricing Analysis
Volume concentrates in standardized coconut cream contracts for foodservice channels, while margin pools shift toward premium coconut powder grades with cold-water solubility certification. Price differentiation hinges on organic certification status and spray-drying infrastructure investment levels. Pricing pressure stems from monsoon-driven raw material volatility in Thai and Filipino supply zones. Small-scale bakery formulators show highest price sensitivity; multinational dairy-alternative manufacturers absorb premium tiers for documented provenance.
Supply Chain Analysis
Freight costs from Thai and Filipino port clusters to North American and European destinations consume disproportionate margin share for mid-scale exporters lacking consolidated shipment volumes. Geographic supply concentration centers on Thailand, the Philippines, and Indonesia for mature coconut endosperm extraction. Processing draws from monsoon-dependent harvest cycles, refined oil fractionation equipment, and spray-drying infrastructure. Single-source vulnerability runs through Bangkok and Manila port chokepoints. Distribution feeds from processor-direct contracts for food manufacturers, with wholesale intermediaries serving smaller foodservice operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coconut milk derivatives market functions as a vertical-integration race where backward control over spray-drying capacity and deforestation-verified harvesting documentation determines competitive survival. Players capturing upstream processing assets and downstream formulation partnerships secure durable margin positions.
For Market Incumbents: Cement procurement lock-ins with Thai and Filipino processors before EU Green Deal enforcement deadlines harden supply access. Acquire spray-drying optimization capabilities to defend against precision-fermentation substitutes in dairy-alternative formulations. Integrated quality laboratories anchor direct technical collaboration with multinational food manufacturers. For New Entrants and Emerging Players: Specialty beverage formulators in North American and European markets represent the most penetrable buyer archetype for documented organic-certified coconut powder. Bypass wholesale distribution entirely through processor-direct e-procurement platforms. Target online retail channels with transparent satellite-verified provenance as the go-to-market wedge. For Investors and Strategic Acquirers: The window for entry favors vertically integrated plantation-to-powder operators with captive Southeast Asian supply bases. Long-term viability rests on deforestation-traceability infrastructure that outlasts regulatory enforcement waves. Watch EU customs clearance data for organic-certified shipments as the inflection signal for premium supply scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Spray-Drying Capacity Expansion | Thai processors deploying cold-water solubility equipment capture North American beverage contract migrations. |
| Backward Integration into Harvest Documentation | Plantation-level satellite verification satisfies EU Green Deal chain-of-custody mandates before enforcement deadlines. |
| Direct-to-Manufacturer Channel Development | Foodservice operators in California and New York Metro bypass distributors for volume contracts with Filipino processors. |
| Organic Certification Program | Fair-trade and sustainable harvesting documentation unlocks premium positioning with European private-label buyers. |
| Hybrid Processing Partnership | Convergence with precision-fermentation specialists enables customized fatty acid profiles for functional food applications. |
Study Parameters
Independent corroboration across primary interviews with coconut processing plant managers, food manufacturer procurement leads, and retail category buyers underwrites the qualitative findings in this study. Secondary validation draws from Thai Industrial Standards Institute certification records, EU F-Gas Regulation compliance filings, FDA import sanitation documentation, and customs trade data for Southeast Asian coconut derivative shipments. Bottom-up volume estimates from processing hub capacity and top-down demand aggregation from end-use application segments complete the triangulation.
Comparable historical reference periods anchored the forecast window to pre-pandemic baseline demand and post-regulatory-shift adjustment phases across the modeling period. Segmentation dimensions include product type, application channel, end-user scale, and regional regulatory cluster. CAGRs derive from slope analysis of normalized growth trajectories against input cost indices and technology adoption curves. Forecast inputs incorporate spray-drying capacity buildout timelines and EU deforestation-free enforcement progression.
Revisions become necessary when monsoon pattern disruption, port congestion escalation, or precision-fermentation substitution acceleration materialize beyond modeled scenarios. Forecasts reflect documented assumptions about regulatory enforcement timing and technology cost curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
North America Non-Dairy Milk Market
Dairy Alternatives
Europe Non-Dairy Yogurt Market
Dairy Alternatives
Almond Milk Market
Dairy Alternatives
Coconut Milk Market
Dairy Alternatives
Cheese Analogue Market
Dairy Alternatives
Vegan Butter Market
Dairy Alternatives
Saudi Arabia Dairy Alternatives Market
Dairy Alternatives
United States Coffee Creamer Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
A2 Ice Cream Market
Dairy Alternatives
Non-Dairy Cheese Market
Dairy Alternatives
Soy Milk Powder Market
Dairy Alternatives
United States Non-Dairy Milk Market
Dairy Alternatives
Japan Dairy Alternatives Market
Dairy Alternatives
Germany Non-Dairy Milk Market