
 North America Microencapsulation Market | 2026-2036
North America Microencapsulation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Microencapsulation Market Insights
Specialty chemical distribution is fragmenting across North America as microencapsulation formulations demand tighter technical support and just-in-time raw material flows. BASF SE leverages its polymer science portfolio to anchor supply relationships with pharmaceutical formulators seeking controlled-release coatings. Balchem Corporation sustains manufacturing scale in nutritional encapsulation, while Encapsys LLC specializes in custom core-shell architectures for agricultural and industrial clients.
Microencapsulation encloses active substances within protective matrices or shells, typically ranging from one to one thousand micrometers in diameter, using processes such as spray drying, coacervation, or fluidized bed coating to achieve timed release, taste masking, or environmental protection. Coating systems dominate pharmaceutical applications where precise dissolution profiles determine therapeutic efficacy, while spray drying technology leads in food and beverage applications due to its cost efficiency at commercial scale. Matrix systems capture expanding demand in agricultural chemicals as manufacturers seek to stabilize volatile pesticides against UV degradation and moisture.
FDA bioequivalence standards for complex generics and EPA pesticide formulation rules jointly elevate the technical bar for new encapsulation entrants seeking market access across the United States. Health Canada's PMMA and Mexico's national pharmaceutical regulator impose parallel stability and safety testing requirements that shape cross-border product registration strategies. Stakeholders must monitor how evolving ESG disclosure obligations and state-level chemical restriction frameworks in California and New York reshape material selection and process chemistry decisions.
Market Dynamics
Pharmaceutical formulators across the United States and Canada are consolidating procurement around fewer encapsulation technology suppliers capable of meeting FDA bioequivalence documentation requirements for complex generics.
Growth Catalysts
- EPA pesticide formulation rules:Manufacturers stabilize volatile agrochemical actives against UV degradation and moisture loss, expanding matrix encapsulation demand across the Corn Belt and California Central Valley.
- Controlled-release coatings:Precision dissolution profiles for oncology and CNS therapeutics drive coating system adoption among contract development and manufacturing organizations clustered in Massachusetts and North Carolina.
- Spray drying cost efficiency:Food and beverage processors in the Midwest achieve commercial-scale flavor encapsulation at unit economics superior to coacervation alternatives.
Market Restraints
- Specialty polymer input volatility:Ethylene-vinyl acetate and cellulose derivative prices fluctuate with petrochemical feedstock markets, compressing margin predictability for toll manufacturers.
- Equipment supply concentration:Fluidized bed coating system production concentrates among German and Swiss original equipment manufacturers, extending North American lead times to 18-24 months.
- Regulatory fragmentation:Divergent stability testing protocols between FDA, Health Canada PMRA, and Mexico's national pharmaceutical regulator multiply registration costs for cross-border product launches.
Strategic Opportunities
- Mexico pharmaceutical manufacturing:Nearshoring initiatives by US-based formulators create demand for localized encapsulation capacity to serve NAFTA-integrated supply chains.
- Nutraceutical gummy matrices:Probiotic and omega-3 oil encapsulation within pectin and gelatin shells opens white space beyond traditional tablet and capsule formats.
- California SB 54 compliance:Extended producer responsibility mandates for plastic packaging drive R&D investment in biodegradable shell materials derived from alginate and chitosan.
Industry Challenges
- Process analytical technology integration:Real-time release testing requirements demand capital-intensive PAT sensor deployment that mid-scale contract manufacturers struggle to finance.
- Cross-functional formulation expertise:Scarce talent pools combining polymer science, pharmacokinetic modeling, and regulatory documentation constrain expansion timelines for service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Microencapsulation Market |
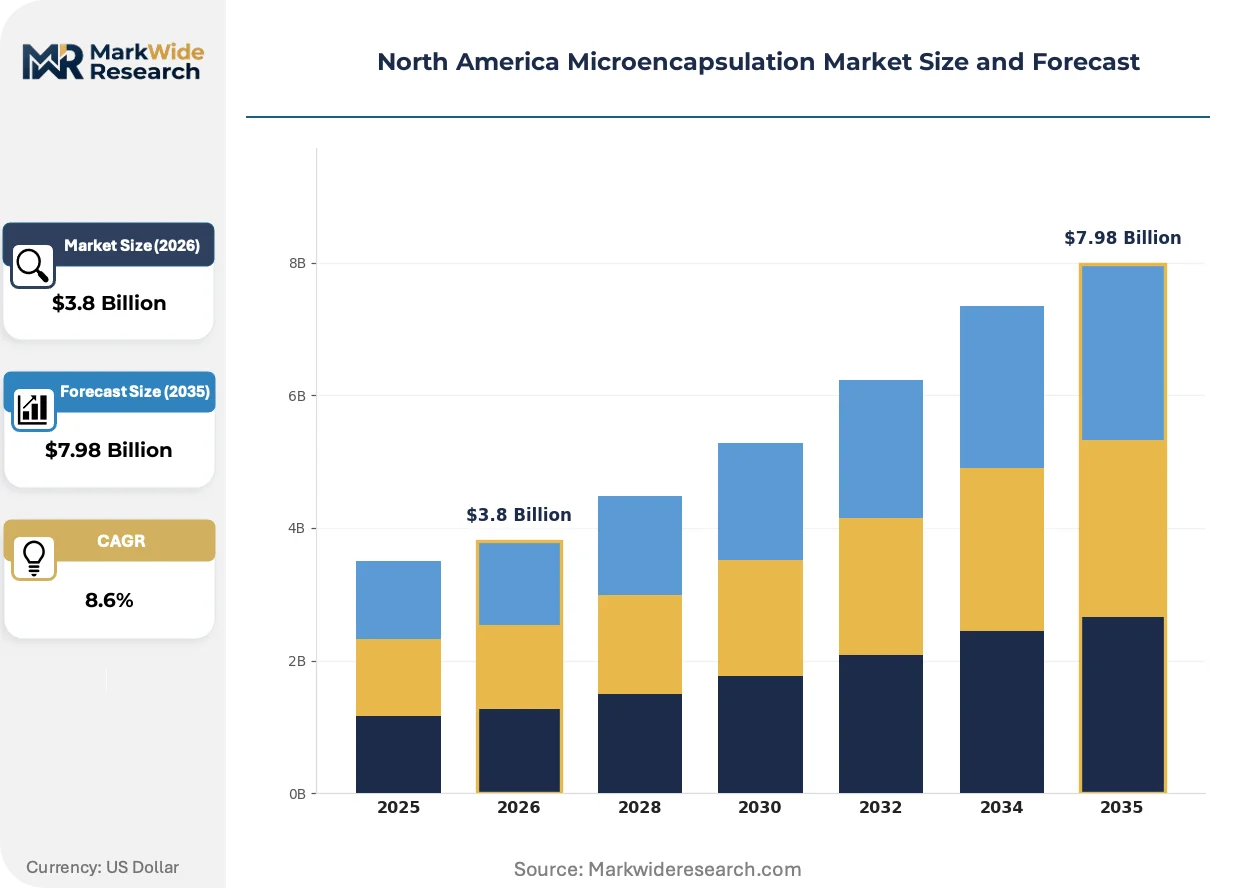
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
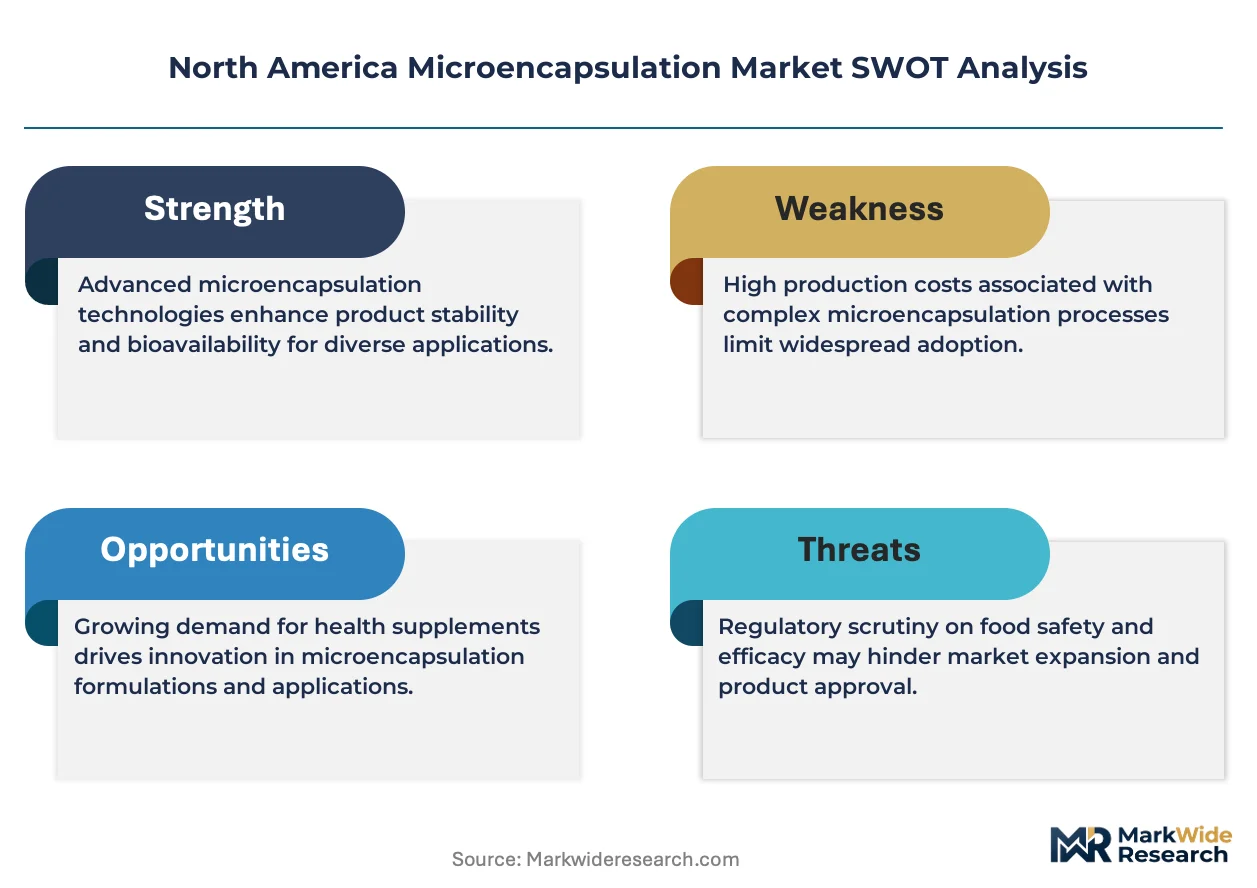
| Segmentation | Application: Pharmaceuticals, Food & Beverages, Cosmetics, Agricultural Chemicals Type: Matrix System, Coating System, Combination System, Microfluidics Material: Polymers, Lipids, Carbohydrates, Inorganic Compounds Technology: Spray Drying, Coacervation, Fluidized Bed Coating, Electrospraying |
| Companies Covered | BASF SE, Balchem Corporation, Encapsys LLC, AVEKA Group, Lycored, Capsulae, Ronald T. Dodge Company, Evonik Industries AG, Reed Pacific, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Microencapsulation Market Trends and Innovations
Active ingredient protection architectures are pivoting from passive barrier functions toward responsive release mechanisms triggered by physiological or environmental conditions.
Electrohydrodynamic spraying is migrating from laboratory-scale academic research into pilot production facilities at agricultural chemical companies seeking sub-micron shell thickness control. Bayer Crop Science and Syngenta field stations in California's Central Valley have installed commercial-scale equipment. This precision is compressing the performance gap between synthetic polymer coatings and higher-cost lipid-based alternatives.
Health Canada PMRA updated its data requirements for microencapsulated pesticide formulations in 2023, mandating leaching studies for groundwater protection assessments. Formulators must now submit 12-month environmental fate data previously exempt for conventional formulations. Agricultural chemical registrants are responding by front-loading encapsulation stability testing into earlier development phases.
Procurement patterns among US generic pharmaceutical sponsors are compressing supplier qualification timelines from 24 months to 14 months as FDA complex generic approval queues lengthen. Sponsors now prioritize encapsulation partners with pre-validated coating platforms rather than custom development programs. This behavioral shift concentrates volume among established toll manufacturers with documented bioequivalence study track records.
North America Microencapsulation Market Segmentation
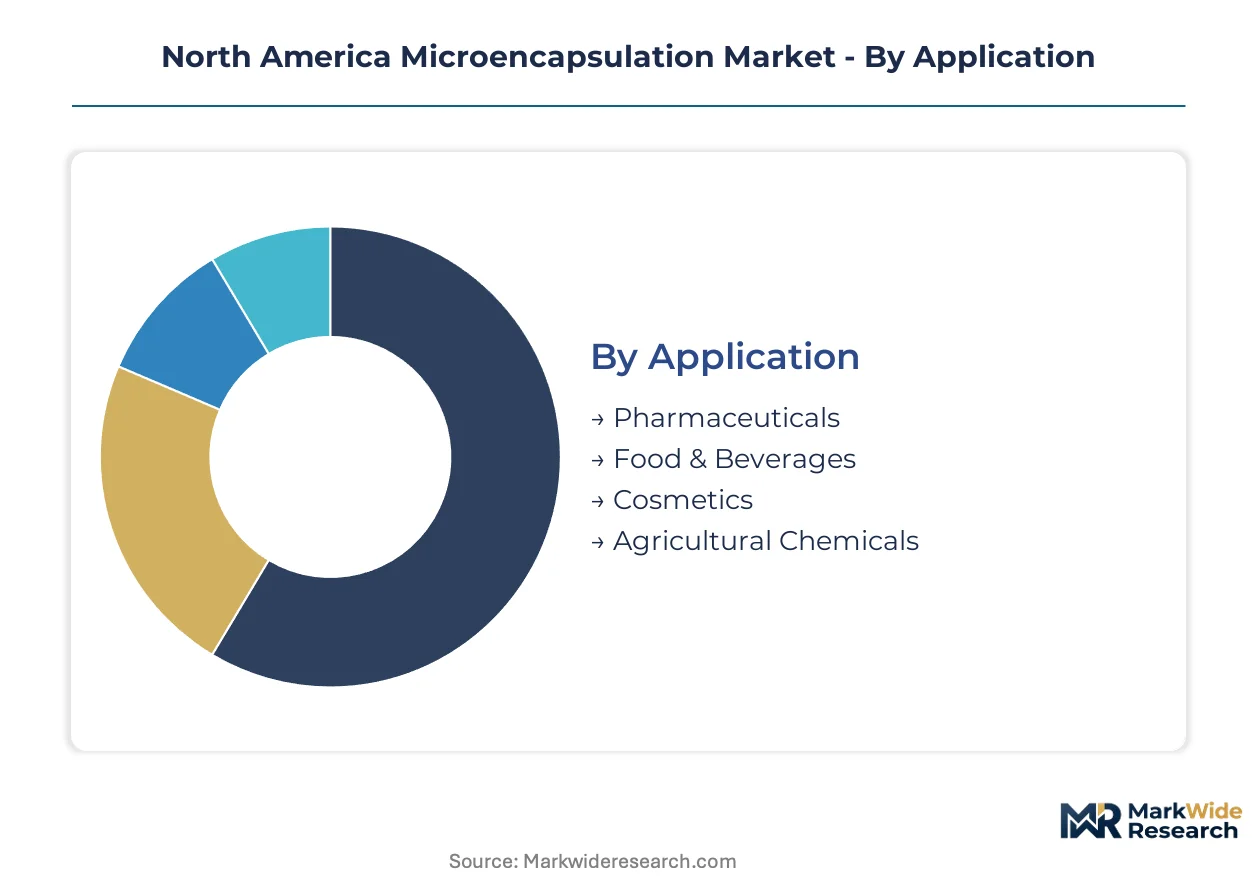
Microencapsulation technology serves divergent performance requirements across North American end-use sectors, from FDA-regulated dissolution profiles to EPA-mandated environmental stability. Segment boundaries reflect distinct technical specifications, material cost structures, and regulatory documentation burdens that shape supplier selection criteria.
Application:
Pharmaceutical formulators, food processors, and agrochemical manufacturers each impose incompatible release kinetics and shell durability specifications on encapsulation partners.
- Pharmaceuticals:Controlled-release coatings for oncology and CNS therapeutics demand precise dissolution profiles validated through FDA bioequivalence studies. Massachusetts and North Carolina contract development organizations concentrate procurement among toll manufacturers with pre-validated coating platforms.
- Food & Beverages:Spray-dried flavor encapsulation dominates Midwest processing facilities where unit economics favor cost efficiency over coacervation alternatives. Taste masking and oxidative stability drive matrix system selection for volatile oil protection.
- Cosmetics:Encapsulated retinol and vitamin C formulations require sub-micron shell thickness for dermal penetration without irritation. California formulators prioritize biodegradable shell materials to align with SB 54 extended producer responsibility mandates.
- Agricultural Chemicals:Matrix systems stabilize volatile pesticides against UV degradation across the Corn Belt and California Central Valley. Health Canada PMRA leaching study requirements now mandate 12-month environmental fate data for encapsulated formulations.
The dominant share belongs to Pharmaceuticals, while Agricultural Chemicals is closing the gap fastest.
Type:
Structural architecture determines release mechanism precision, manufacturing capital intensity, and raw material cost exposure across North American production networks.
- Matrix System:Active ingredients dispersed throughout carrier material provide sustained release through diffusion-controlled kinetics. Agrochemical manufacturers favor this architecture for UV and moisture protection of volatile pesticides.
- Coating System:Core-shell designs achieve zero-order release profiles critical for FDA-approved complex generics. Fluidized bed coating equipment concentrates among German and Swiss OEMs, extending North American lead times to 18-24 months.
- Combination System:Hybrid architectures merge matrix dispersion with functional coating layers for multi-stage release. Nutraceutical gummy formats exploit this approach for probiotic and omega-3 oil stabilization.
- Microfluidics:Precision droplet generation enables monodisperse particle size distribution for advanced pharmaceutical applications. California and Massachusetts research clusters pilot commercial-scale adoption.
Coating System commands the largest installed base, though Matrix System is expanding most quickly in agricultural applications.
Material:
Shell composition directly determines biodegradability credentials, barrier performance, and vulnerability to petrochemical feedstock price volatility.
- Polymers:Ethylene-vinyl acetate and cellulose derivatives dominate pharmaceutical coating applications where mechanical integrity and dissolution predictability are paramount. Ethylene-vinyl acetate price fluctuation compresses margin predictability for toll manufacturers.
- Lipids:Phospholipid and triglyceride shells provide biocompatible barriers for sensitive actives in parenteral and topical delivery. Higher raw material costs limit penetration beyond premium therapeutic categories.
- Carbohydrates:Alginate and chitosan alternatives gain traction as California SB 54 compliance drives R&D investment in biodegradable packaging solutions. Pectin matrices serve expanding nutraceutical gummy formats.
- Inorganic Compounds:Silica and calcium carbonate shells offer thermal stability for high-temperature processing applications. Limited functional versatility constrains adoption outside specialty industrial uses.
Polymers retain the dominant material position, while Carbohydrates is gaining share fastest on sustainability tailwinds.
Technology:
Process selection balances capital expenditure requirements, particle size precision, and scale-up feasibility across diverse North American manufacturing footprints.
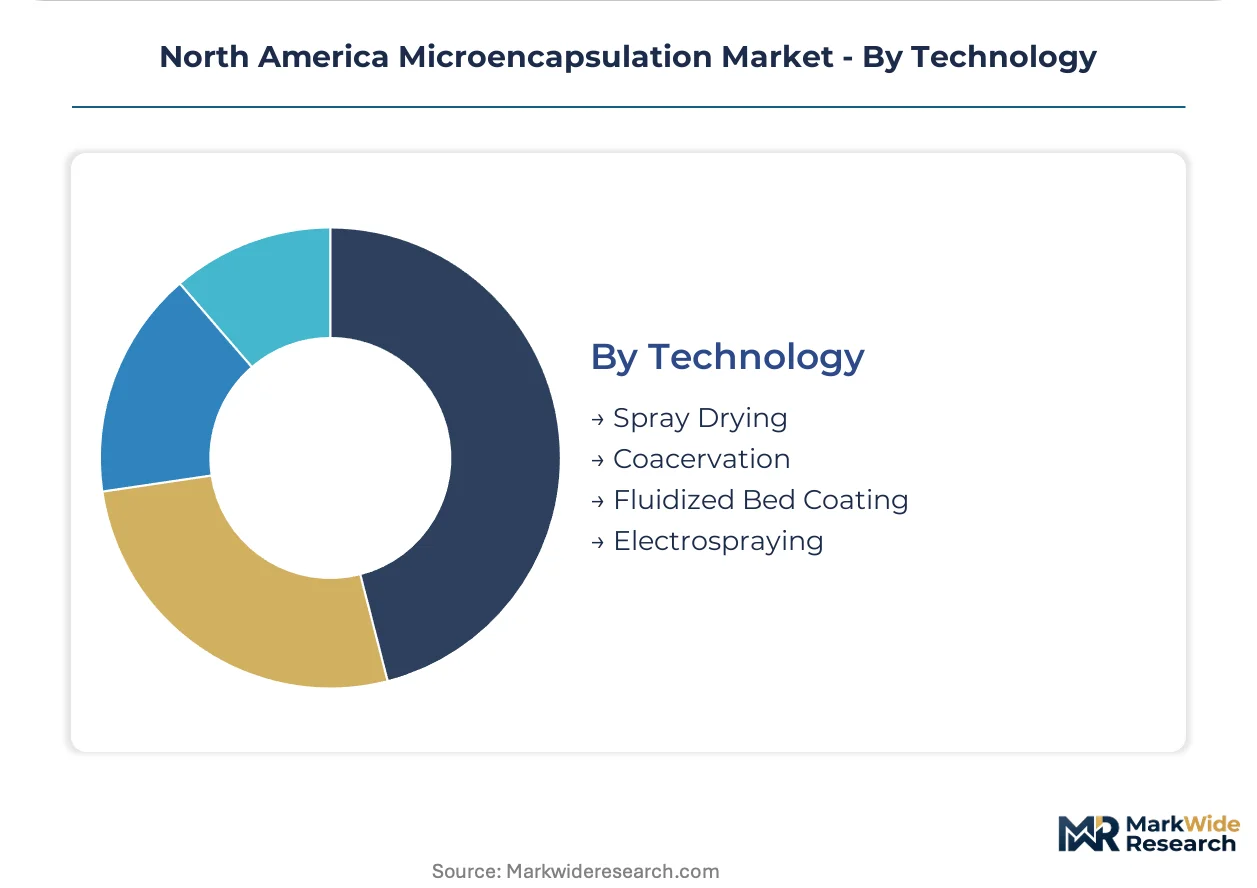
- Spray Drying:Atomization and rapid solvent evaporation deliver cost-efficient commercial-scale production for food and beverage flavor encapsulation. Midwest processors achieve superior unit economics versus coacervation alternatives at volume.
- Coacervation:Phase separation techniques enable complex multi-core architectures for sensitive pharmaceutical actives. Higher operational complexity limits adoption beyond specialty applications.
- Fluidized Bed Coating:Air suspension coating achieves uniform shell thickness for controlled-release pharmaceutical tablets. Equipment supply concentration among European OEMs constrains North American capacity expansion timelines.
- Electrospraying:Electrohydrodynamic spraying migrates from academic research into pilot production at California Central Valley agricultural stations. Sub-micron shell thickness control narrows performance gaps with synthetic polymer alternatives.
Spray Drying holds the dominant technology position, though Electrospraying is climbing the fastest on precision agriculture investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where FDA bioequivalence documentation commands premium toll manufacturing rates, while Mexican production corridors absorb cost-sensitive agricultural chemical volume under EPA-equivalent compliance frameworks.
United States
Pharmaceutical formulators in Massachusetts and North Carolina drive coating system procurement for controlled-release oncology therapeutics. FDA bioequivalence standards for complex generics compress supplier qualification timelines from 24 months to 14 months. California's Central Valley hosts Bayer Crop Science and Syngenta field stations piloting electrohydrodynamic spraying equipment for sub-micron agricultural shell thickness control.
Canada
Health Canada PMRA updated data requirements in 2023, mandating 12-month environmental fate leaching studies for encapsulated pesticide formulations. Toronto and Montreal contract manufacturers serve cross-border pharmaceutical sponsors seeking dual FDA-Health Canada registration pathways. Prairie province agricultural chemical distributors now stock matrix-encapsulated formulations to meet groundwater protection assessments.
Mexico
Nearshoring initiatives by US-based formulators create demand for localized encapsulation capacity serving NAFTA-integrated supply chains. Mexico's national pharmaceutical regulator imposes parallel stability testing requirements that shape product registration strategies for cross-border launches. Querétaro and Guanajuato manufacturing corridors attract toll manufacturers seeking proximity to Texas distribution hubs.
North America Microencapsulation Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying coating polymers and fluidized bed equipment. The North American microencapsulation market structures around three tiers: multinational chemical conglomerates with polymer science portfolios, mid-scale toll manufacturers with validated FDA platforms, and regional specialists in agricultural or nutritional matrices. Consolidation pressures intensify as procurement shifts toward fewer suppliers capable of bioequivalence documentation. Competitive moves concentrate on pre-validated platform licensing and captive raw material integration.
Within the multinational tier, BASF SE anchors supply relationships through its polymer science portfolio, while Evonik Industries AG occupies a position in specialty coating materials. Balchem Corporation exemplifies the mid-scale toll manufacturing archetype with documented nutritional encapsulation scale. These three entities represent the dominant competitive anchors across pharmaceutical, agricultural, and food-grade application vectors.
| Leading Market Players |
|---|
| BASF SE |
| Balchem Corporation |
| Encapsys LLC |
| AVEKA Group |
| Lycored |
| Capsulae |
| Ronald T. Dodge Company |
| Evonik Industries AG |
| Reed Pacific |
| Others |
Pricing and Supply Chain Analysis
Massachusetts contract manufacturing clusters concentrate pharmaceutical encapsulation capacity, and this geographic density grants toll manufacturers leverage over generic sponsors facing compressed FDA qualification timelines. California agricultural chemical processors absorb cost-sensitive volume under EPA-equivalent frameworks, creating divergent pricing power across application vectors.
Pricing Analysis
Customization-premium spreads separate configured-to-order coating platforms from standard matrix formulations. Contract manufacturers command project-based pricing for FDA bioequivalence documentation, while commodity spray-dried flavors transact on per-kilogram spot terms. Certification tier—specifically pre-validated platforms versus custom development—drives the widest price differentiation. Cost compression in standard agricultural matrices intensifies as Midwest processors achieve scale economies. Generic pharmaceutical sponsors exhibit lowest price sensitivity due to regulatory switching costs, while food processors demonstrate highest elasticity.
Supply Chain Analysis
Supplier-financing facilities from German and Swiss fluidized bed equipment OEMs extend payment terms to 18-24 months for North American toll manufacturers. Manufacturing capacity draws from the United States, Canada, and Mexico under NAFTA-integrated supply chains. Critical inputs encompass ethylene-vinyl acetate polymers, cellulose derivatives, and phospholipid shell materials. Single-source vulnerability concentrates in European coating equipment supply. Distribution runs through contract manufacturing organizations serving pharmaceutical sponsors and direct procurement by agricultural chemical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American microencapsulation sits in early-cycle expansion as responsive release mechanisms displace passive barrier architectures across pharmaceutical and agricultural applications.
For Market Incumbents: Insulate coating platform margins through captive polymer supply agreements with BASF SE and Evonik Industries, while accelerating FDA bioequivalence documentation to exploit compressed sponsor qualification timelines. Electrohydrodynamic spraying entrants from agricultural chemical majors threaten precision-coating differentiation. Backward integration into alginate and chitosan raw materials defends against California SB 54 sustainability mandates. For New Entrants and Emerging Players: Mexico pharmaceutical manufacturing corridors near Querétaro and Guanajuato represent the most penetrable entry point for toll encapsulation capacity serving nearshored US formulators. Nutraceutical gummy matrices for probiotic and omega-3 stabilization offer white-space expansion beyond tablet formats. Partner with pre-validated platform licensors rather than pursuing custom development timelines. For Investors and Strategic Acquirers: Long-term, this sits as a specialty toll manufacturing play because regulatory documentation moats compound with each FDA bioequivalence study completed. Acquisition targets should display validated coating platforms and documented sponsor track records. Watch electrohydrodynamic spraying adoption rates at California Central Valley field stations as inflection signal for precision agriculture displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Validated Platform Licensing | Compresses sponsor qualification timelines from 24 months to 14 months under FDA pressure. |
| Backward Integration into Biodegradable Polymers | Secures alginate and chitosan supply chains against California SB 54 compliance mandates. |
| Electrohydrodynamic Spraying Scale-Up | Bayer Crop Science and Syngenta field stations pilot sub-micron shell thickness control. |
| Mexico Manufacturing Corridor Expansion | Captures nearshored pharmaceutical volume under NAFTA-integrated supply chains. |
| Process Analytical Technology Deployment | Enables real-time release testing demanded by FDA for complex generic approvals. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical formulators, contract manufacturing executives, regulatory affairs specialists, and agricultural chemical R&D directors and refined through secondary validation. Sources encompassed FDA bioequivalence guidance documents, EPA pesticide formulation databases, Health Canada PMRA submissions, and SEC filings from listed chemical conglomerates. Bottom-up capacity assessments triangulated with top-down market sizing across technology and application segments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass coating system type, pharmaceutical versus agricultural end-use, shell material composition, and regional regulatory cluster. CAGRs derived from unit economics analysis at commercial scale and patent expiration timelines for controlled-release therapeutics. Inputs included fluidized bed equipment lead times, ethylene-vinyl acetate price volatility indices, and sponsor qualification pattern shifts.
Practitioners should monitor FDA complex generic approval queue lengths, EPA pesticide formulation rule amendments, and electrohydrodynamic spraying commercialization rates for early signals. Forecasts reflect assumptions on regulatory documentation burden stability and petrochemical feedstock price bands. Macroeconomic contraction, regulatory harmonization failure, or responsive release mechanism breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Firming Agents Market
Food Additives and Ingredients
Europe Feed Anti-Caking Agents Market
Food Additives and Ingredients
Europe Leavening Agents Market
Food Additives and Ingredients
Food Grade Release Agent Market
Food Additives and Ingredients
Gum Hydrocolloid Market
Food Additives and Ingredients
Food Humectants Market
Food Additives and Ingredients
Acidity Regulators Market
Food Additives and Ingredients
Italy Food Preservatives Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Coconut Fatty Acids Market
Food Additives and Ingredients
United States Feed Additives Market
Food Additives and Ingredients
Acrylamide Reduction Market
Food Additives and Ingredients
India Anti Caking Market
Food Additives and Ingredients
United Kingdom Food Emulsifier Market
Food Additives and Ingredients
Salatrim Market
Food Additives and Ingredients
North America Food Additives Market