
 India Food Color Industry Market | 2026-2036
India Food Color Industry Market Size, Share, and Industry Trends Forecast 2026-2036
India Food Color Industry Market Insights
Gujarat-based natural extract producers is realigning capacity toward carotenoid and anthocyanin concentrates. Ajanta Industries leverages backward integration into turmeric and paprika sourcing to secure raw material consistency. Kancor Ingredients Private Limited anchors its position through oleoresin-based color systems for beverage applications. Synthite competes on scale, operating one of India's largest spice extraction facilities near Kochi.
Food colors comprise dyes, pigments, and lakes that impart, preserve, or enhance visual appeal in edible products, with natural variants typically extracted at concentrations between 0.1% and 5.0% dry weight depending on source material and solvent system. These additives serve critical functions in product differentiation, quality perception masking, and shelf-life signaling across processed food value chains. Natural Colors now command premium positioning as FSSAI and export-oriented buyers enforce stricter clean-label protocols, while Synthetic Colors face margin compression from regulatory scrutiny despite maintaining volume leadership in mass-market confectionery. Lake Colors occupy a specialized niche in fat-based applications where dye bleeding would compromise product integrity, particularly within India's expanding chocolate and compound coating segment.
FSSAI's Food Safety and Standards (Food Products Standards and Food Additives) Regulations govern permissible color lists, maximum usage levels, and labeling requirements across domestic manufacturing. BIS certification for color additives and CDSCO oversight of pharmaceutical-grade excipients create layered compliance obligations for cross-sector suppliers. State food safety commissioners in Maharashtra, Gujarat, and Tamil Nadu conduct heightened enforcement against non-compliant synthetic dye use in traditional sweets. Stakeholders must monitor evolving FSSAI notification timelines for natural color approvals and align R&D pipelines accordingly.
Market Dynamics
FSSAI's tightened purity specifications for synthetic dyes are accelerating reformulation investments across Maharashtra and Gujarat, forcing packaged food manufacturers to expand synthetic-to-natural conversion lines.
Growth Catalysts
- FSSAI Regulatory Pressure:The regulator's tightened purity specifications for synthetic dyes are forcing manufacturers toward natural alternatives, creating immediate demand for carotenoid and anthocyanin concentrates.
- Processed Dairy Expansion:South India's dairy and confectionery corridor is driving volume demand for stable natural color systems in shelf-stable milk products and traditional sweets.
- Export-Oriented Clean-Label Mandates:European and North American buyer protocols are compelling Indian exporters to abandon synthetic dyes entirely, privileging suppliers with backward integration into turmeric and paprika sourcing.
Market Restraints
- Raw Material Volatility:Monsoon-dependent turmeric and paprika harvests in Andhra Pradesh and Karnataka create input cost instability for natural extract producers.
- Extraction Technology Bottlenecks:Solvent recovery rates below 85% in conventional oleoresin processing constrain yield economics for mid-scale operators.
- Lake Color Substitution Limits:Fat-based chocolate and compound coating applications lack viable natural alternatives to synthetic lakes, preserving regulatory exposure in this segment.
Strategic Opportunities
- Underpenetrated Northeast Corridor:Assam and West Bengal processed food sectors remain underserved by natural color technical support, creating first-mover positioning for application laboratories.
- Beverage Clarification Systems:Anthocyanin-based pH-stable colorants for acidic soft drinks represent white space as carbonated drink manufacturers face synthetic dye phase-out deadlines.
- PLI Scheme Alignment:The government's production-linked incentive scheme for food processing machinery indirectly subsidizes extraction equipment upgrades for natural color producers.
Industry Challenges
- Application Technologist Scarcity:Formulation chemists capable of stabilizing natural colors across varying pH and thermal processing conditions command premium salaries, constraining R&D expansion.
- Multi-Regulatory Certification Lag:FSSAI approval timelines for novel natural color sources run 18-24 months, misaligning with export customer product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Food Color Industry Market |
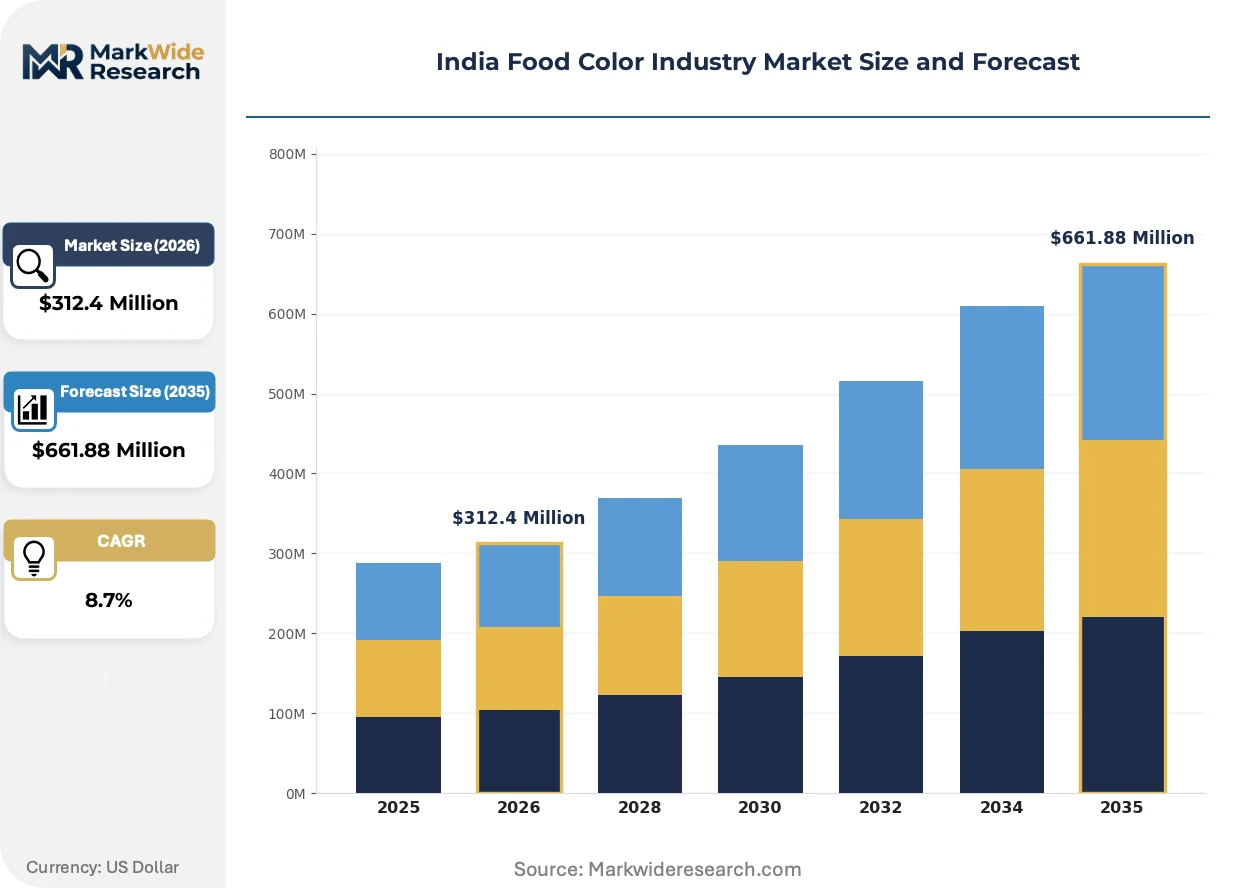
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colors, Synthetic Colors, Lake Colors, Caramel Colors End Use Industry: Food & Beverages, Pharmaceuticals, Cosmetics, Animal Feed Form: Liquid, Powder, Paste, Granule Application: Baking, Beverages, Confectionery, Dairy |
| Companies Covered | Ajanta Industries, Kancor Ingredients Private Limited, Synthite, Plant Lipids Private Limited, Sun Food Tech, Chr. Hansen Holding A/S, Döhler Group, BASF SE, Sensient Technologies Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Food Color Industry Market Trends and Innovations
Natural color extraction technologies are advancing rapidly as manufacturers seek to match synthetic dye performance characteristics without regulatory baggage.
Supercritical CO2 extraction is converging with microwave-assisted processing to reduce solvent residue and improve pigment yield from paprika and marigold feedstocks. Large beverage manufacturers in Maharashtra are piloting these hybrid systems to secure cleaner label claims. This convergence is compressing the cost gap between synthetic and natural color systems by 15-20% at commercial scale.
FSSAI's draft notification on expanded natural color approvals is forcing manufacturers to pre-position formulation alternatives before mandatory compliance deadlines. The regulator's accelerated review timeline for carotenoid-based additives is redirecting R&D budgets toward stability testing rather than novel molecule discovery. Confectionery exporters targeting Middle Eastern markets are most affected, as Gulf Cooperation Council standards increasingly reference FSSAI specifications.
Buyer concentration among organized retail private labels is consolidating procurement decisions toward fewer suppliers with full certificate-of-analysis documentation. Modern trade chains in Karnataka and Tamil Nadu now mandate batch-level heavy metal testing, displacing spot-check protocols. This behavioral shift most visibly pressures smaller natural color traders lacking in-house analytical capabilities.
India Food Color Industry Market Segmentation
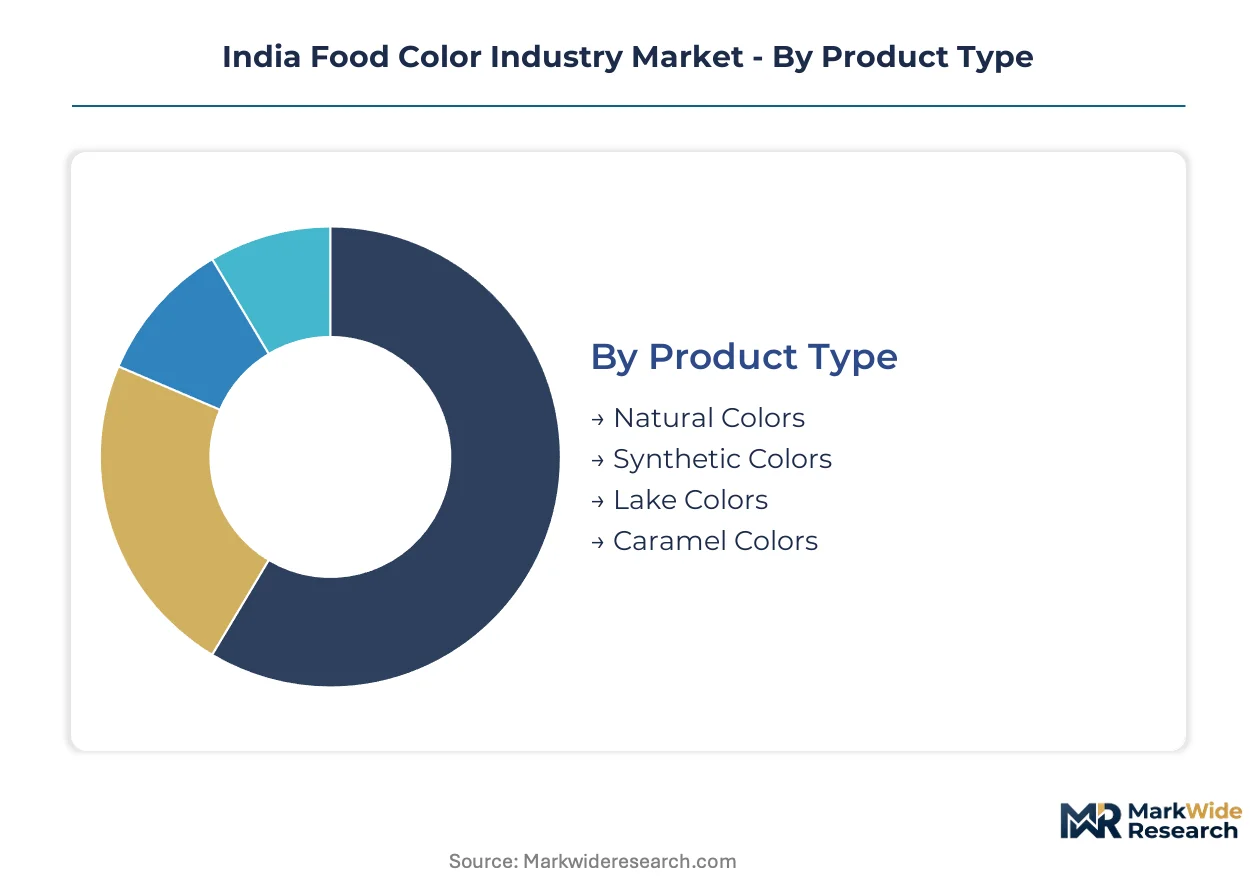
India's food color market fragments across product chemistry, end-use specifications, and physical form factors that dictate formulation compatibility. Each segmentation axis carries distinct margin profiles and regulatory exposure, with natural-synthetic positioning now the primary commercial fault line.
Product Type:
Supply concentration clusters around oleoresin extraction corridors in Kerala and Karnataka, where backward integration into turmeric and paprika farming secures input cost stability.
- Natural Colors:Carotenoid and anthocyanin concentrates extracted at 0.1% to 5.0% dry weight, with FSSAI's tightened purity specifications accelerating Maharashtra and Gujarat manufacturers toward synthetic-to-natural conversion lines. Demand concentrates in South India's processed dairy and confectionery corridor where clean-label protocols dominate procurement decisions.
- Synthetic Colors:Azo and triphenylmethane dyes maintaining volume leadership in mass-market confectionery despite margin compression from regulatory scrutiny. State food safety commissioners in Maharashtra, Gujarat, and Tamil Nadu conduct heightened enforcement against non-compliant use in traditional sweets.
- Lake Colors:Aluminum-barium complexes occupying specialized niche in fat-based chocolate and compound coating applications where dye bleeding would compromise product integrity.
- Caramel Colors:Heat-treated carbohydrate systems for beverage browning and baked goods coloration, with Class I plain caramel facing substitution pressure from natural alternatives.
Today's leader: Synthetic Colors. Tomorrow's challenger: Natural Colors.
End Use Industry:
Application maturity varies sharply, with food-grade specifications setting the baseline that pharmaceutical and cosmetic grades must exceed.
- Food & Beverages:Dominant consumption channel spanning carbonated drinks, shelf-stable dairy, and traditional sweets reformulation. CDSCO oversight of pharmaceutical-grade excipients creates layered compliance obligations for cross-sector suppliers targeting this segment.
- Pharmaceuticals:Tablet coating and syrup coloration requiring BIS certification and batch-level heavy metal documentation that displaces spot-check protocols among smaller traders.
- Cosmetics:Lipstick and skincare coloration facing EU REACH alignment pressure for export-oriented manufacturers.
- Animal Feed:Poultry and aquaculture pigment supplementation for flesh color enhancement, with carotenoid concentrates from marigold and paprika feedstock dominating.
Food & Beverages commands current volume. Pharmaceuticals offers steepest expansion trajectory on export certification premiums.
Form:
Physical state selection hinges on manufacturing equipment compatibility and dissolution kinetics in target matrices.
- Liquid:Preferred for beverage dosing and continuous processing lines, with pH-stable anthocyanin formulations gaining share in acidic soft drink applications.
- Powder:Dominant in baking and dry mix applications where moisture sensitivity constrains liquid alternatives, with spray-dried natural extracts commanding premium positioning.
- Paste:Concentrated intermediates for industrial compounders seeking precise viscosity control in chocolate and coating systems.
- Granule:Dust-free handling format for large-scale feed and dry blend manufacturers, with flowability specifications matching pneumatic conveying systems.
Powder retains manufacturing ubiquity. Liquid is climbing the fastest on beverage sector automation.
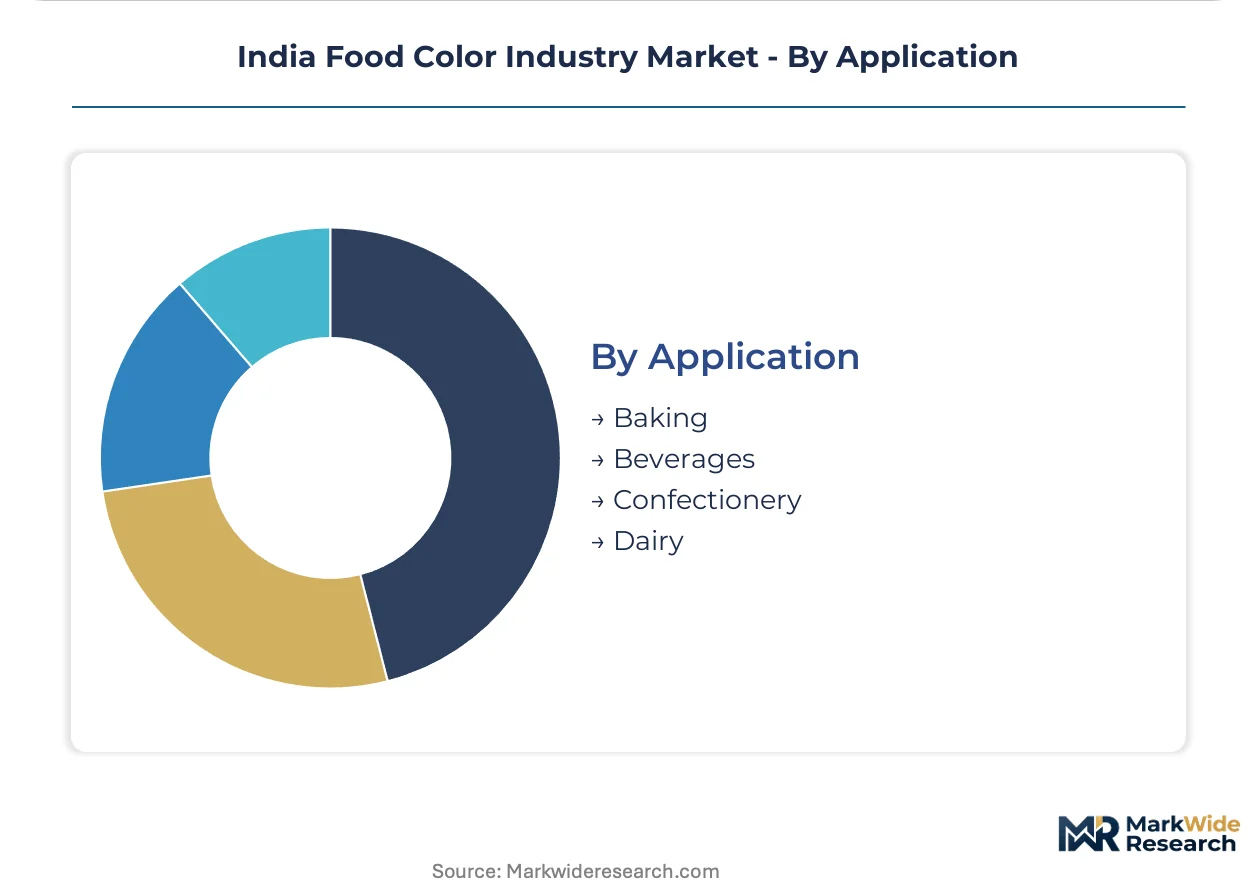
Application:
Thermal stability requirements and pH exposure create divergent technical barriers across processing environments.
- Baking:Heat-stable carotenoid and caramel systems for bread crust and cake coloration, with Maillard reaction masking driving consistent demand.
- Beverages:Anthocyanin-based pH-stable colorants represent white space as carbonated drink manufacturers face synthetic dye phase-out deadlines, with Maharashtra beverage manufacturers piloting supercritical CO2 extraction hybrids.
- Confectionery:Hard candy and panned products requiring thermal stability that natural alternatives struggle to match, preserving synthetic lake penetration in mass-market segments.
- Dairy:Shelf-stable milk products and flavored yogurts driving volume demand for stable natural color systems in South India's processing corridor.
Dairy anchors current natural color adoption. Beverages is gaining share fastest on clean-label deadline pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's synthetic-to-natural conversion lines outpace Gujarat's oleoresin capacity expansion, while South India's dairy corridor commands premium positioning for carotenoid concentrates.
Maharashtra
Packaged food manufacturers in Mumbai-Pune belt are expanding synthetic-to-natural conversion lines at the fastest clip nationally. FSSAI's tightened purity specifications for synthetic dyes are accelerating reformulation investments among confectionery exporters. The state's beverage manufacturers pilot supercritical CO2 extraction hybrids to secure cleaner label claims for carbonated drink applications.
Gujarat
Natural extract producers in Ahmedabad-Vadodara corridor are realigning capacity toward carotenoid and anthocyanin concentrates. BIS certification requirements for color additives create layered compliance obligations for cross-sector suppliers. Backward integration into turmeric and paprika sourcing secures raw material consistency for oleoresin-based color systems.
Karnataka
Modern trade chains in Bangalore mandate batch-level heavy metal testing, displacing spot-check protocols among smaller natural color traders. Monsoon-dependent turmeric harvests in Andhra Pradesh-Karnataka border regions create input cost instability. The state's spray-dried natural extracts command premium positioning in baking and dry mix applications.
Tamil Nadu
Shelf-stable milk products and flavored yogurts in Chennai-Coimbatore corridor drive volume demand for stable natural color systems. State food safety commissioners conduct heightened enforcement against non-compliant synthetic dye use in traditional sweets. The region's processed dairy and confectionery infrastructure anchors South India's clean-label procurement decisions.
Kerala
Synthite operates one of India's largest spice extraction facilities near Kochi, leveraging coastal logistics for export-oriented oleoresin shipments. Anthocyanin concentrates from local feedstocks serve pH-stable beverage applications. The state's extraction technology base supports hybrid microwave-assisted processing systems for improved pigment yield.
India Food Color Industry Market Competitive Landscape
Gujarat-based producers anchor the domestic natural extract tier; European specialists hold premium positioning through certificate-of-analysis documentation. The vendor base fragments across mid-scale oleoresin operators, multinational ingredient houses, and backward-integrated spice processors. Three archetypes dominate: captive agricultural sourcing models, application-technical service bundlers, and regulatory-compliance aggregators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as FSSAI approval timelines force pre-positioning investments.
Among domestic fabricators, Ajanta Industries exemplifies backward integration into turmeric and paprika sourcing to secure raw material consistency. Kancor Ingredients Private Limited occupies a position within the oleoresin-based color systems tier for beverage applications. Synthite anchors the scale-driven segment through extraction facility operations near Kochi. These three represent distinct strategic postures: agricultural supply control, application-specific formulation, and manufacturing scale.
| Leading Market Players |
|---|
| Ajanta Industries |
| Kancor Ingredients Private Limited |
| Synthite |
| Plant Lipids Private Limited |
| Sun Food Tech |
| Chr. Hansen Holding A/S |
| Döhler Group |
| BASF SE |
| Sensient Technologies Corp. |
| Others |
Pricing and Supply Chain Analysis
Turmeric spot price volatility in Andhra Pradesh and Karnataka propagates through extraction economics into three distinct procurement tiers for natural color concentrates. FSSAI-mandated purity upgrades compress margins for synthetic dye traders while rewarding oleoresin producers with backward-integrated farming contracts.
Pricing Analysis
Distributor margins of 12-18% separate bulk oleoresin converters from formulation-ready concentrate suppliers serving Maharashtra beverage manufacturers. Three-tier pricing structure across premium certified-natural, standard FSSAI-compliant, and economy synthetic grades reflects certification burden and heavy metal documentation depth. Cost compression in economy synthetic tiers is intensifying because state enforcement actions in Gujarat and Tamil Nadu accelerate reformulation demand. Organized retail private labels exhibit lowest price sensitivity due to clean-label mandates, while traditional sweet manufacturers in unorganized segments resist premium natural color conversion.
Supply Chain Analysis
Domestic-content mandates under the PLI scheme for food processing machinery are redirecting capital equipment procurement toward Indian fabrication, reducing import dependency for extraction infrastructure. Geographic supply concentration centers on Kerala for spice oleoresin, Gujarat for synthetic dye intermediates, and Karnataka for spray-dried natural extracts. Raw material dependencies rest on monsoon-sensitive turmeric rhizomes, paprika pods from contract farming clusters, and imported solvent carriers for conventional extraction. Single-source vulnerability pervades the Kochi-Ahmedabad logistics corridor where coastal oleoresin shipments face monsoon port congestion. Distribution runs through regional stock points serving Mumbai-Pune and Chennai-Coimbatore manufacturing belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in India's food color sector rests on extraction yield improvements and premium-tier certification premiums displacing commodity synthetic volumes.
For Market Incumbents: Extend application-technical service bundling into Assam and West Bengal's underserved processed food corridors before first-mover positioning solidifies. Anchor capacity expansion in Kerala and Karnataka near feedstock clusters to defend against raw material volatility. Deepen FSSAI pre-approval investments for novel carotenoid sources to outpace 18-24 month regulatory timelines. For New Entrants and Emerging Players: Enter via pH-stable anthocyanin formulations for Maharashtra's carbonated beverage synthetic phase-out deadlines, the most penetrable white space. Target spray-dried powder formats for Karnataka's modern trade chains mandating batch-level heavy metal documentation. Pursue toll-manufacturing partnerships with established oleoresin operators to bypass captive agricultural sourcing requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale natural extract producers possessing pilot-scale supercritical CO2 capability and pending FSSAI novel color approvals. Long-term viability favors acquisition targets with demonstrated stability testing infrastructure and export-oriented certificate-of-analysis documentation. Watch for FSSAI notification acceleration on expanded natural color approvals as the inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Turmeric and Paprika Sourcing | Ajanta Industries exemplifies captive supply securing raw material consistency against monsoon volatility. |
| Supercritical CO2 Extraction Scale-Up | Maharashtra beverage manufacturers pilot hybrid systems to compress natural-synthetic cost gaps. |
| Application Laboratory Expansion | Technical service bundlers target Assam and West Bengal's underpenetrated Northeast corridor. |
| FSSAI Pre-Approval R&D Positioning | Carotenoid stability testing investments outpace 18-24 month novel color regulatory timelines. |
| Export Certification Documentation | Batch-level heavy metal testing capabilities displace spot-check protocols among organized retail suppliers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with extraction plant managers, FSSAI regulatory affairs leads, procurement directors at Maharashtra confectionery exporters, and Kerala-based oleoresin technical directors with secondary validation. Trade data from CDSCO pharmaceutical-grade excipient filings, FSSAI notification registers, customs records for solvent and spice feedstock imports, and BIS certification databases anchored supply-side sizing. Bottom-up capacity utilization estimates triangulated against top-down end-use consumption models across dairy, beverage, and confectionery applications.
Historical reference periods spanning pre-regulatory tightening and post-FSSAI enforcement phases anchored the projection horizon's growth rate derivation. Segmentation modeling incorporated product chemistry tiers, physical form factors, thermal stability requirements, and pH exposure profiles alongside geographic production cluster dynamics. CAGRs emerged from iterative reconciliation of extraction capacity expansion schedules, reformulation investment pipelines, and export clean-label mandate adoption curves.
Inputs from FSSAI notification timelines and monsoon-adjusted agricultural yield data were available through the study window; gaps in real-time oleoresin spot pricing and confidential reformulation contract values introduce uncertainty bands around natural color penetration trajectories. Forecasts reflect documented assumptions on regulatory enforcement intensity and export buyer protocol alignment. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Beverage Stabilizer Market
Food Additives and Ingredients
Beverage Encapsulants Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Methyl Oleate Market
Food Additives and Ingredients
Global Food Anti Caking Agents Market
Food Additives and Ingredients
Emulsifiers Market
Food Additives and Ingredients
Calcium Butyrate Market
Food Additives and Ingredients
Pea Starch Concentrate Market
Food Additives and Ingredients
Asia-Pacific Food Enzymes Market
Food Additives and Ingredients
South America Food Acidulants Market
Food Additives and Ingredients
Filling Fat Market
Food Additives and Ingredients
Excipients Market
Food Additives and Ingredients
Potassium Polymetaphosphate Food Additives Market
Food Additives and Ingredients
Mexico Food Acidulants Market
Food Additives and Ingredients
Polyglycerol Esters of Fatty Acids Market
Food Additives and Ingredients
Spain Food Additives Market