
 Surgical Sphincteroplasty Market | 2026-2036
Surgical Sphincteroplasty Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Sphincteroplasty Market Intelligence
Modularization of surgical kits is decoupling instrument procurement from single-vendor contracts in sphincteroplasty. Medtronic leverages its broad endomechanical portfolio to sustain bundled service agreements across integrated delivery networks. Johnson & Johnson anchors its position through Ethicon suture and mesh lines that dominate open and laparoscopic repair workflows. B. Braun competes on specialized electrosurgical instruments tailored to pelvic floor access.
Surgical sphincteroplasty is a reconstructive procedure that repairs damaged anal sphincter muscle through direct apposition, overlapping repair, or augmentation with biologic or synthetic graft material, typically performed under regional or general anesthesia with operative times ranging from 60 to 180 minutes depending on complexity and concomitant repairs. The procedure restores fecal continence by re-establishing muscular ring integrity and improving resting and squeeze pressures measured via manometry. Robotic surgery within procedure type commands premium positioning as hospitals justify capital expenditure through broader pelvic floor service expansion, while endoscopic approaches gain traction for early-stage repairs in outpatient settings. Fecal incontinence as the leading indication captures the deepest reimbursement pools, though colorectal dysfunction segments are expanding fastest as awareness of integrated pelvic floor disorders grows among referring gastroenterologists.
The FDA regulates sphincteroplasty meshes as Class II medical devices requiring 510(k) premarket notification, with heightened scrutiny on synthetic materials following transvaginal mesh safety communications that have extended to anal indications. ISO 13485 quality management certification and CE marking under the EU Medical Device Regulation shape competitive access for European market entry, while Japan's PMDA oversees approval pathways for novel biologic grafts in Asia. Stakeholders must monitor how evolving evidence requirements for permanent implants reshape clinical trial investment and product lifecycle planning across jurisdictions.
Market Dynamics
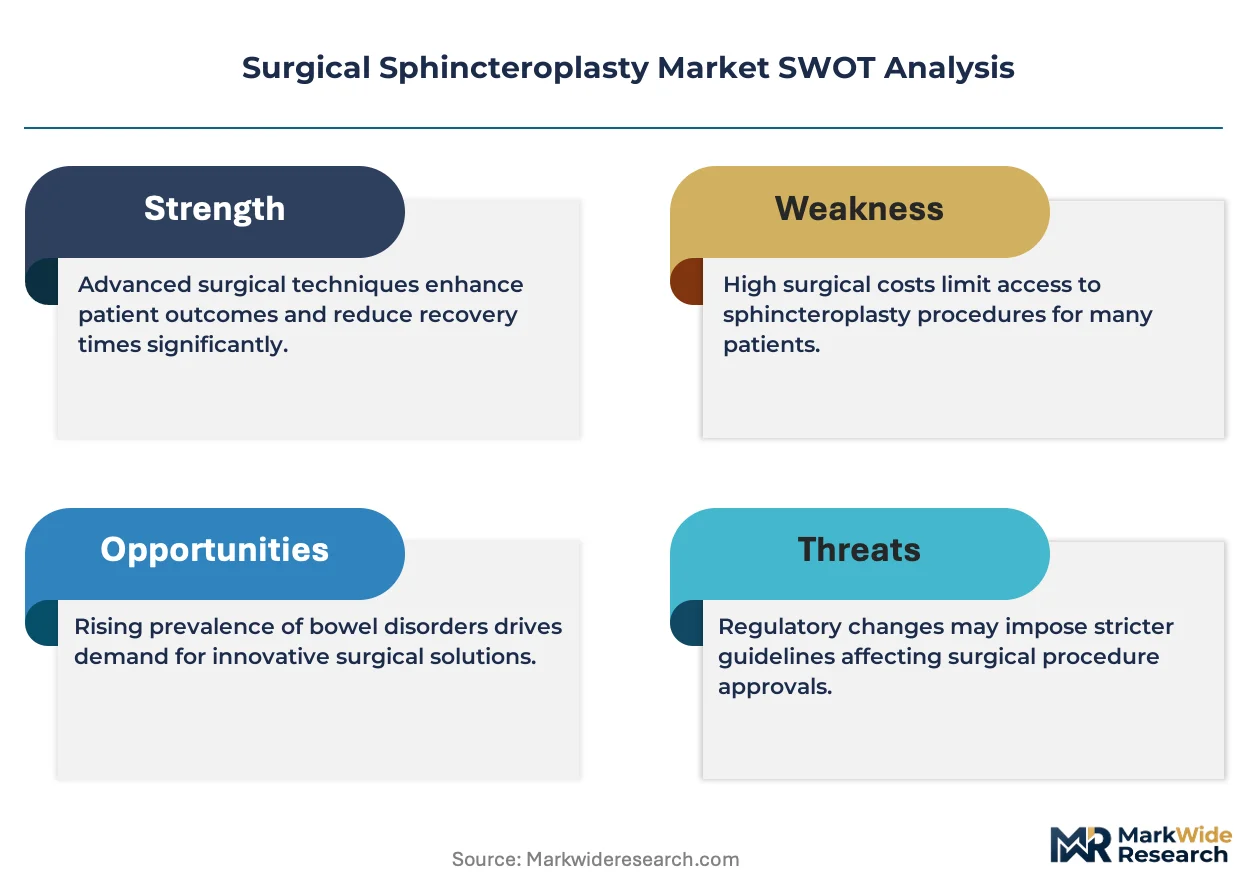
Robotic-assisted surgical platforms are compressing operative learning curves while FDA scrutiny of permanent mesh implants forces biologic graft validation investments, restructuring how manufacturers allocate R&D capital across open, laparoscopic, and endoscopic technique portfolios.
Growth Catalysts
- EU Medical Device Regulation:MDR's enhanced clinical evidence requirements for Class II implants are accelerating consolidation among CE-marked biologic graft suppliers with pre-existing PMCF data repositories.
- Academic medical centers:United States teaching hospitals are embedding sphincteroplasty within broader pelvic floor fellowship curricula, expanding the qualified surgeon pool for complex overlapping repairs.
- Specialized colorectal centers:Germany's dedicated pelvic floor surgery programs are generating referral networks that concentrate high-complexity cases and justify capital equipment amortization across robotic platforms.
Market Restraints
- Biologic graft supply concentration:Porcine and human allograft sourcing depends on a limited number of accredited tissue banks, creating batch-to-batch variability risks that complicate surgical planning.
- FDA 510(k) pathway friction:Synthetic mesh safety communications have extended premarket review timelines for novel anal indications, delaying product launches and elevating clinical trial costs.
- Sacral nerve modulation substitution:Medtronic's InterStim therapy captures moderate fecal incontinence cases that might otherwise progress to sphincteroplasty, capping addressable surgical volume.
Strategic Opportunities
- Outpatient ambulatory surgery centers:Endoscopic sphincteroplasty techniques enable same-day discharge protocols that align with United States CMS bundled payment expansion for lower-acuity pelvic floor procedures.
- Japan's PMDA novel biologic pathway:Accelerated approval frameworks for regenerative medical products create first-mover positioning for xenograft manufacturers with Japanese QMS certification.
- AI-assisted preoperative planning:Machine learning integration with 3D endoanal ultrasound is unifying anatomical mapping with predicted functional outcomes, enabling personalized repair technique selection.
Industry Challenges
- Pelvic floor surgeon training pipelines:Fellowship program slots in colorectal surgery remain constrained relative to retiring specialist cohorts, creating geographic access disparities for complex repairs.
- ISO 13485 certification timelines:European notified body backlogs extend quality management system audits to 12-18 months, delaying market entry for novel suture anchor designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Sphincteroplasty Market |
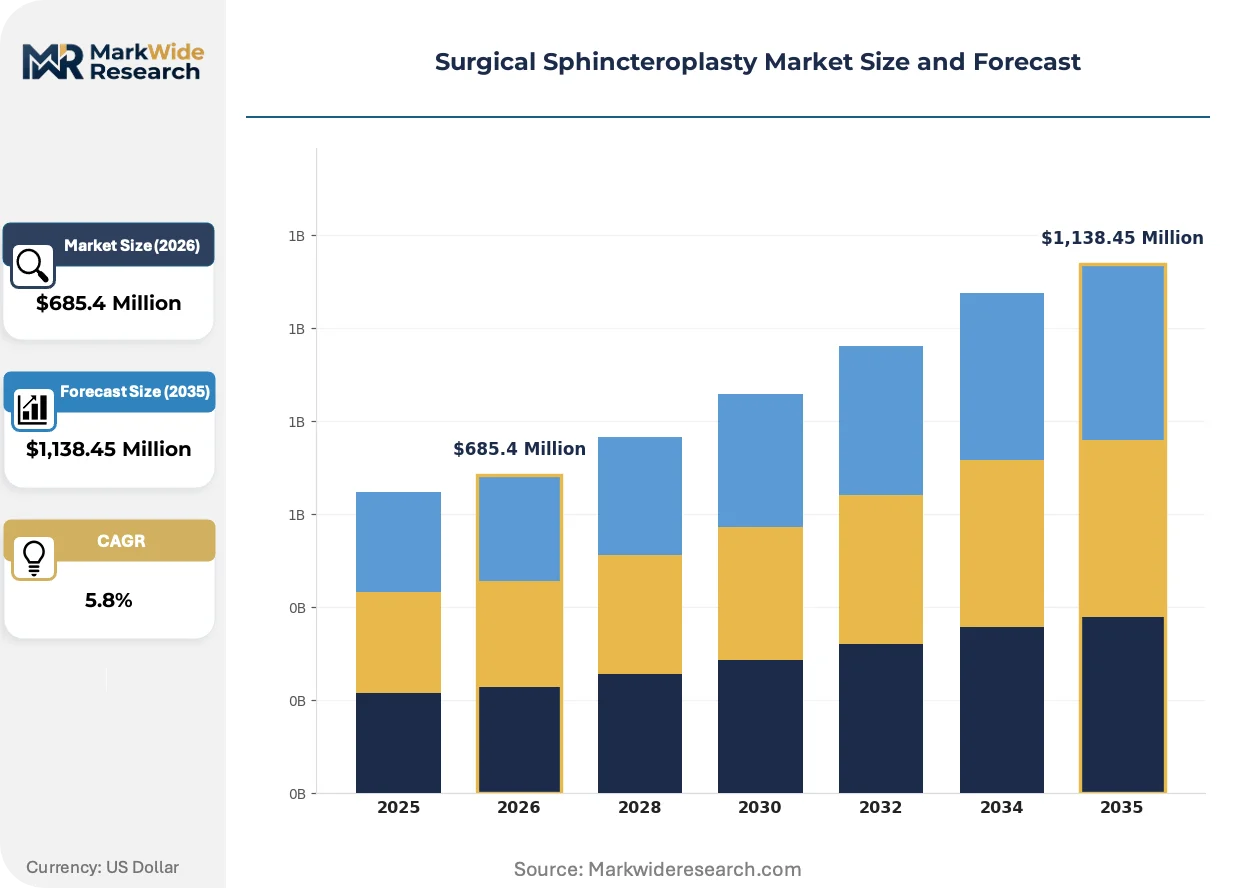
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Endoscopic, Open Surgery, Laparoscopic, Robotic Surgery Indication: Fecal Incontinence, Anal Fistula, Rectal Prolapse, Colorectal Dysfunction Patient Demographics: Adult Patients, Pediatric Patients, Elderly Patients, Gender-Specific Hospital Type: Private Hospitals, Public Hospitals, Specialty Clinics, Academic Medical Centers |
| Companies Covered | Medtronic, Johnson & Johnson, B. Braun, Becton, Dickinson and Company, Novo Surgical, Inc., Pelvalon, Hill-Rom Services, Inc., Boston Scientific Corporation, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Sphincteroplasty Market Strategic Shifts & Innovations
Convergence of robotic instrumentation with advanced imaging is compressing the technical gap between high-volume academic centers and community hospital settings, while regulatory fragmentation across jurisdictions forces parallel compliance architectures.
Robotic surgical platforms are unifying instrument control with haptic feedback and tremor filtration, enabling precise layered sphincter repair in confined pelvic spaces. Community hospitals in the United States are adopting these systems through shared-service arrangements with larger integrated delivery networks. This technology diffusion is unifying procedural outcomes across facility types while elevating capital intensity barriers for standalone surgical centers.
REACH chemical safety frameworks are extending scrutiny to processing agents used in biologic graft decellularization, compelling manufacturers to substitute legacy detergents with enzymatic protocols. European notified bodies now require residue testing documentation as part of technical file reviews. Xenograft suppliers with German manufacturing footprints are responding by vertically integrating tissue processing to control substance compliance.
Hospital purchasing committees are fragmenting bundled instrument contracts into modular component sourcing, decoupling suture and mesh procurement from capital equipment vendor lock-in. Academic medical centers in the United States lead this unbundling, negotiating separate agreements for robotic consumables, biologic grafts, and electrosurgical accessories. This pattern concentrates price transparency pressure on mid-tier suppliers without comprehensive portfolios.
Surgical Sphincteroplasty Market Segmentation
Surgical sphincteroplasty segmentation reflects divergent reimbursement pathways, capital intensity requirements, and patient risk stratification across procedural approaches. Each category isolates distinct purchasing decision-makers—from hospital value analysis committees to individual surgeon preference cards—shaping how manufacturers configure product portfolios and pricing architectures.
Procedure Type:
Technical sophistication and capital equipment requirements define competitive positioning across surgical approaches.
- Robotic Surgery:Da Vinci and comparable platforms enable tremor-filtered suturing in confined pelvic anatomy with 3D visualization. United States academic medical centers amortize capital costs across broader pelvic floor service lines, justifying premium consumable pricing through bundled episode economics.
- Laparoscopic:Conventional minimally invasive techniques leverage existing OR infrastructure without dedicated robotic capital expenditure. Community hospitals in Germany concentrate volume here, where specialized colorectal centers prioritize throughput over technology differentiation.
- Open Surgery:Direct sphincter access remains the fallback for complex revisions and concomitant perineal procedures. Surgeon training pipelines in India and Brazil emphasize open technique mastery before minimally invasive progression.
- Endoscopic:Transanal approaches enable same-day discharge protocols. United States ambulatory surgery centers are piloting these techniques for selected low-complexity repairs under CMS bundled payment frameworks.
Robotic surgery leads on scale through system placement expansion; endoscopic approaches lead on momentum through outpatient migration.
Indication:
Clinical endpoint severity and reimbursement coding density determine addressable patient populations.
- Fecal Incontinence:Primary indication capturing deepest CPT reimbursement pools in the United States, with established prior authorization pathways. Medicare coverage determinations for sacral nerve modulation create direct competitive substitution dynamics.
- Colorectal Dysfunction:Expanding fastest as integrated pelvic floor disorder awareness spreads among United States gastroenterology referral networks. Multidisciplinary clinics in the United Kingdom are building dedicated pathways for this segment.
- Anal Fistula:Sphincteroplasty serves as salvage therapy after failed primary fistulotomy or seton placement. Volume concentrates in tertiary centers with advanced imaging capabilities.
- Rectal Prolapse:Concomitant sphincter repair during abdominal rectopexy addresses occult incontinence. French colorectal societies have published specific technique modifications for this combined approach.
Fecal incontinence leads on scale through established reimbursement; colorectal dysfunction leads on momentum through diagnostic expansion.
Patient Demographics:
Age-related tissue quality and comorbidity burden influence graft selection and operative risk stratification.
- Elderly Patients:Fragile tissue architecture and polypharmacy complexity drive biologic graft preference over synthetic mesh in this cohort. Japan's aging demographic is expanding addressable volume fastest among OECD markets.
- Adult Patients:Prime surgical candidates with intact healing capacity and manageable comorbidity profiles. United States private payers favor this segment for bundled payment pilots.
- Gender-Specific:Obstetric sphincter injury repairs in postpartum women require distinct informed consent frameworks. United Kingdom NICE guidelines specifically address technique selection for this population.
- Pediatric Patients:Congenital anorectal malformation corrections demand specialized surgeon training. Volume concentrates in designated children's hospitals with dedicated pediatric colorectal programs.
Adult patients lead on scale through procedural volume; elderly patients lead on momentum through demographic transition.
Hospital Type:
Capital allocation authority and purchasing committee composition shape vendor access and contract structures.
- Academic Medical Centers:Fellowship training programs generate qualified surgeon pipelines while value analysis committees fragment bundled contracts into modular sourcing. Robotic platform adoption concentrates here in the United States.
- Public Hospitals:Budget-constrained procurement favors open and laparoscopic techniques over capital-intensive robotics. India's government hospital network represents significant volume through centralized tender processes.
- Private Hospitals:Competitive positioning through technology differentiation drives faster robotic adoption. Brazil's private hospital chains are investing in dedicated pelvic floor surgery units.
- Specialty Clinics:Focused colorectal and pelvic floor centers achieve economies through case concentration. Germany's specialized colorectal centers are building referral networks that justify dedicated robotic systems.
Academic medical centers lead on scale through training volume; specialty clinics lead on momentum through focused service line development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surgical sphincteroplasty techniques originated in European academic centers during the mid-20th century, with Germany and the United Kingdom pioneering overlapping sphincter repair methods that remain foundational to modern practice.
United States
Academic medical centers in Boston and the Research Triangle generate fellowship-trained colorectal surgeons who disseminate robotic-assisted techniques nationwide. FDA 510(k) premarket notification requirements for anal mesh implants extend review timelines and elevate clinical trial investment thresholds. Cleveland Clinic and Mayo Clinic anchor referral networks that concentrate complex revision cases.
Germany
Specialized colorectal centers in Hamburg and Berlin build dedicated pelvic floor surgery programs that justify capital equipment amortization across robotic platforms. EU Medical Device Regulation clinical evidence requirements for Class II implants accelerate consolidation among CE-marked biologic graft suppliers. The Ruhr region hosts vertically integrated tissue processing facilities responding to REACH chemical safety frameworks.
Japan
Aging demographics expand addressable surgical volume fastest among OECD markets, with Tokyo and Osaka metropolitan areas concentrating qualified surgeon pools. PMDA accelerated approval frameworks for regenerative medical products create first-mover positioning for xenograft manufacturers with Japanese QMS certification. Kansai region hospitals pilot AI-assisted preoperative planning integration.
United Kingdom
NICE guidelines specifically address technique selection for obstetric sphincter injury repairs in postpartum women, shaping informed consent frameworks. London teaching hospitals embed sphincteroplasty within broader pelvic floor fellowship curricula. Manchester and Birmingham multidisciplinary clinics build dedicated pathways for colorectal dysfunction segments.
India
Government hospital networks represent significant procedural volume through centralized tender processes favoring open and laparoscopic techniques. CDSCO oversight of imported biologic grafts creates regulatory friction for novel product launches. Maharashtra and Karnataka host private hospital chains investing in dedicated colorectal surgery units.
Surgical Sphincteroplasty Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology integration and regulatory certification dimensions. The vendor base stratifies into three tiers: diversified medtech conglomerates with broad endomechanical portfolios, specialized surgical instrument manufacturers with pelvic floor-specific catalogs, and regional suppliers competing on tender pricing. Consolidation pressures concentrate among mid-tier players lacking comprehensive portfolios or pre-existing PMCF data repositories. Dominant competitive moves include modular contract fragmentation by hospital purchasing committees and backward integration into tissue processing for biologic graft suppliers.
Among diversified medtech conglomerates, Medtronic and Johnson & Johnson occupy positions anchoring bundled service agreements across integrated delivery networks. Medtronic leverages its broad endomechanical portfolio to sustain hospital contracts, while Johnson & Johnson anchors positioning through Ethicon suture and mesh lines. B. Braun represents the specialized instrument manufacturer archetype, competing on electrosurgical tools tailored to pelvic floor access. These three exemplify distinct strategic postures: platform breadth, consumable dominance, and surgical specialization.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| B. Braun |
| Becton, Dickinson and Company |
| Novo Surgical, Inc. |
| Pelvalon |
| Hill-Rom Services, Inc. |
| Boston Scientific Corporation |
| Olympus Corporation |
| Others |
Cost & Logistics Intelligence
Fellowship-trained colorectal surgeons in the United States command compensation premiums that widen pricing spreads between academic medical centers and community hospitals, compressing margins for mid-tier instrument suppliers without robotic platform bundling leverage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates robotic consumable bundles from laparoscopic instrument kits from open surgery commodity sutures. Price differentiation rests on FDA 510(k) clearance tier and CE marking status under EU MDR. Pricing pressure stems from hospital purchasing committees fragmenting bundled contracts into modular component sourcing. Community hospitals in Germany exhibit highest price sensitivity; United States academic medical centers with capital amortization across service lines show lowest.
Supply Chain Analysis
Freight costs for temperature-controlled biologic graft shipments from German tissue processing facilities to Japan's Kansai region hospitals add meaningful landed cost premiums. Supply concentrates in the United States for robotic platforms, Germany for porcine-derived grafts, and India for stainless steel surgical instruments. Raw material dependencies include medical-grade silicone, decellularized extracellular matrix, and electrosurgical generator components. Single-source vulnerability pervades accredited tissue bank networks. Distribution runs through GPO contracts in the United States, direct hospital procurement in Germany, and centralized government tenders in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surgical sphincteroplasty functions as a late-cycle quality story where hospital purchasing committees now prioritize biologic graft traceability and PMCF data depth over per-unit cost, rewarding suppliers with pre-existing clinical evidence repositories.
For Market Incumbents: Acquire pre-existing PMCF data repositories to defend against EU MDR consolidation pressures. Backward integration into tissue processing insulates against REACH chemical safety framework disruption. Hospital value analysis committee unbundling threatens bundled service agreements; anchor positioning through suture line dominance retains surgeon preference card control. For New Entrants and Emerging Players: AI-assisted preoperative planning integration offers technology-first entry with lower regulatory capital requirements than robotic platforms. Japan's PMDA novel biologic pathway represents most penetrable geography for xenograft manufacturers with QMS certification. Partner with Kansai region hospitals piloting machine learning ultrasound mapping to establish clinical validation footholds. For Investors and Strategic Acquirers: Diversified medtech conglomerates are the most active acquirer in this space, seeking bolt-on biologic graft capabilities to fill portfolio gaps. Long-term viability favors suppliers with vertically integrated tissue processing and dual FDA-CE regulatory positioning. Watch sacral nerve modulation reimbursement expansion as volume-capture inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Investment | Pre-existing PMCF data repositories accelerate consolidation among CE-marked biologic graft suppliers. |
| Robotic Platform Shared-Service Arrangements | Community hospitals in the United States amortize capital costs through integrated delivery network partnerships. |
| Biologic Graft Backward Integration | German manufacturing footprints enable REACH chemical safety compliance through enzymatic decellularization substitution. |
| AI-Assisted Preoperative Planning Partnership | Kansai region hospitals unify 3D endoanal ultrasound with machine learning for personalized repair selection. |
| Ambulatory Surgery Center Technique Piloting | United States CMS bundled payment expansion enables same-day discharge protocols for endoscopic approaches. |
Research Approach
Direct dialogue with colorectal surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded qualitative insights. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates and top-down market sizing triangulated through cross-reference against capital equipment placement records and biologic graft shipment customs data.
Segment-level outputs across procedure type, indication, patient demographics, and hospital type informed analytical framework construction throughout the projection horizon. CAGRs derived from weighted average of historical capital expenditure trajectories, surgeon training pipeline expansion rates, and reimbursement pathway evolution. Forecast inputs incorporated robotic platform adoption curves in academic medical centers and EU MDR transition timelines for biologic graft suppliers.
The model holds under stable FDA 510(k) review timelines and REACH chemical safety enforcement continuity; deviation in synthetic mesh safety communication escalation or tissue bank accreditation disruptions would shift volume projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Hydrosurgery Systems Market
Surgical Instruments
Plastic Wound Retractor Market
Surgical Instruments
Tonsil and Adenoid Removal Products Market
Surgical Instruments
Saudi Arabia General Surgical Devices Market
Surgical Instruments
Cystoscopy Needles Market
Surgical Instruments
Surgical Sutures Market
Surgical Instruments
Lumpectomy Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Surgical Clips Market
Surgical Instruments
Surgical Visualization Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Argentina General Surgical Devices Market
Surgical Instruments
Absorbable PGA Surgical Sutures Market
Surgical Instruments
Special Purpose Needles Market
Surgical Instruments
Endoscopic Spinal Surgery Market
Surgical Instruments
Global Laparoscopic Instruments Market