
 Plastic Wound Retractor Market | 2026-2036
Plastic Wound Retractor Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Wound Retractor Market Analytics
Ambulatory surgical centers are reorganizing procurement patterns for plastic wound retractors as hospitals cede volume to outpatient settings. Applied Medical Resources leverages vertical integration in polymer sourcing to sustain cost advantages across its retractor portfolio. Medtronic anchors its position through R&D intensity in ergonomic handle designs that reduce surgeon fatigue. Ethicon differentiates via brand strength in sterile single-use configurations that dominate North American hospital purchasing.
Plastic wound retractors are ring-shaped devices manufactured from medical-grade polymers such as polypropylene or high-impact polystyrene that mechanically hold incisions open during surgical procedures, providing tissue protection and visual field access. Polypropylene-based variants lead unit shipments due to superior tensile strength and autoclave compatibility, while single-use configurations capture the fastest-growing demand segment as infection control protocols tighten. General surgery applications occupy the largest revenue pool, though cardiac surgery retractors command premium pricing through specialized sizing and reinforced structural geometries.
FDA 510(k) premarket notification requirements govern US market entry, while EU MDR technical documentation and ISO 13485 quality management standards shape global product compliance burdens. The EU AI Act and CSRD reporting obligations are beginning to influence supply chain transparency expectations for polymer sourcing in European markets. Stakeholders must monitor evolving sterilization validation requirements and polymer biocompatibility testing protocols as regulatory convergence between FDA and notified body expectations accelerates.
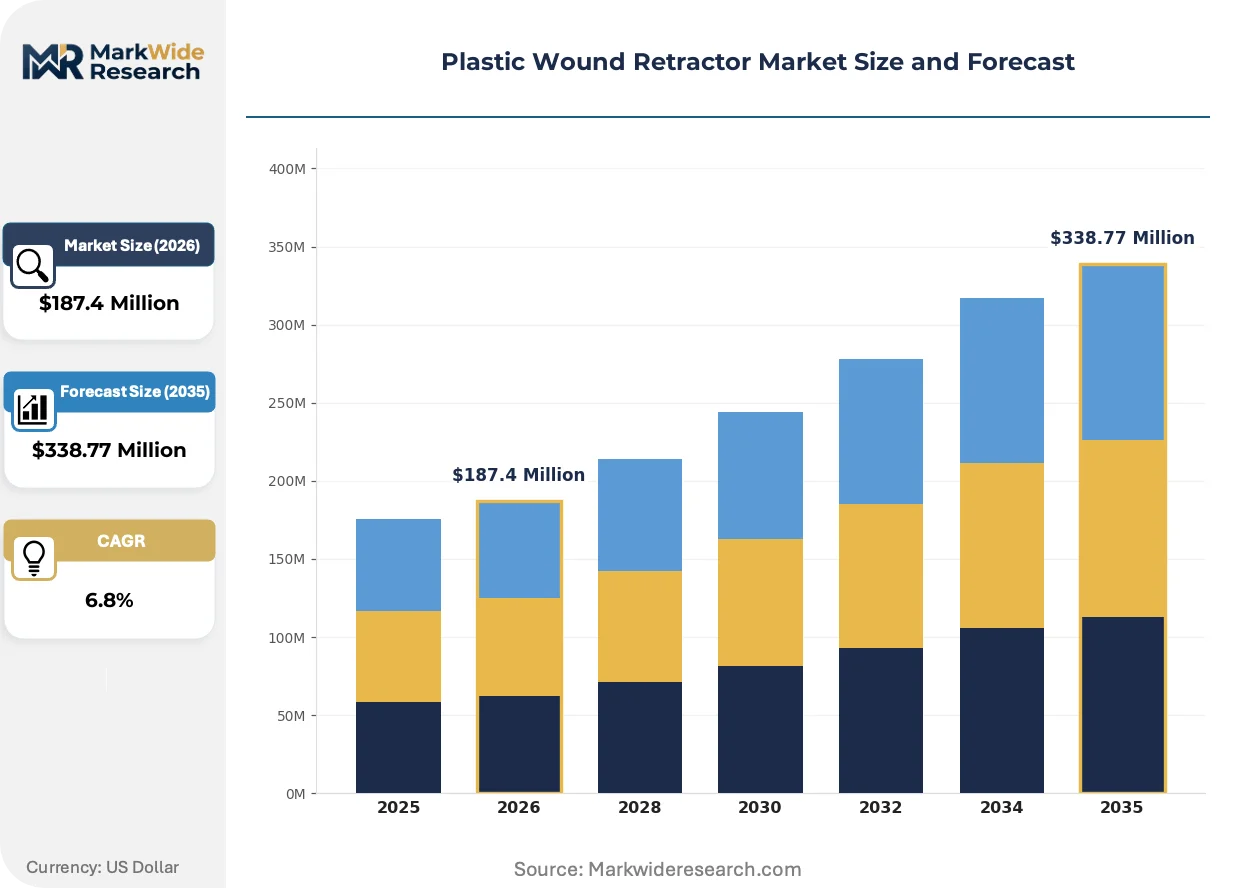
Market Dynamics
Ambulatory surgical centers are capturing volume from hospitals for outpatient procedures, forcing manufacturers to reconfigure distribution channels and packaging formats for smaller-quantity, higher-frequency orders.
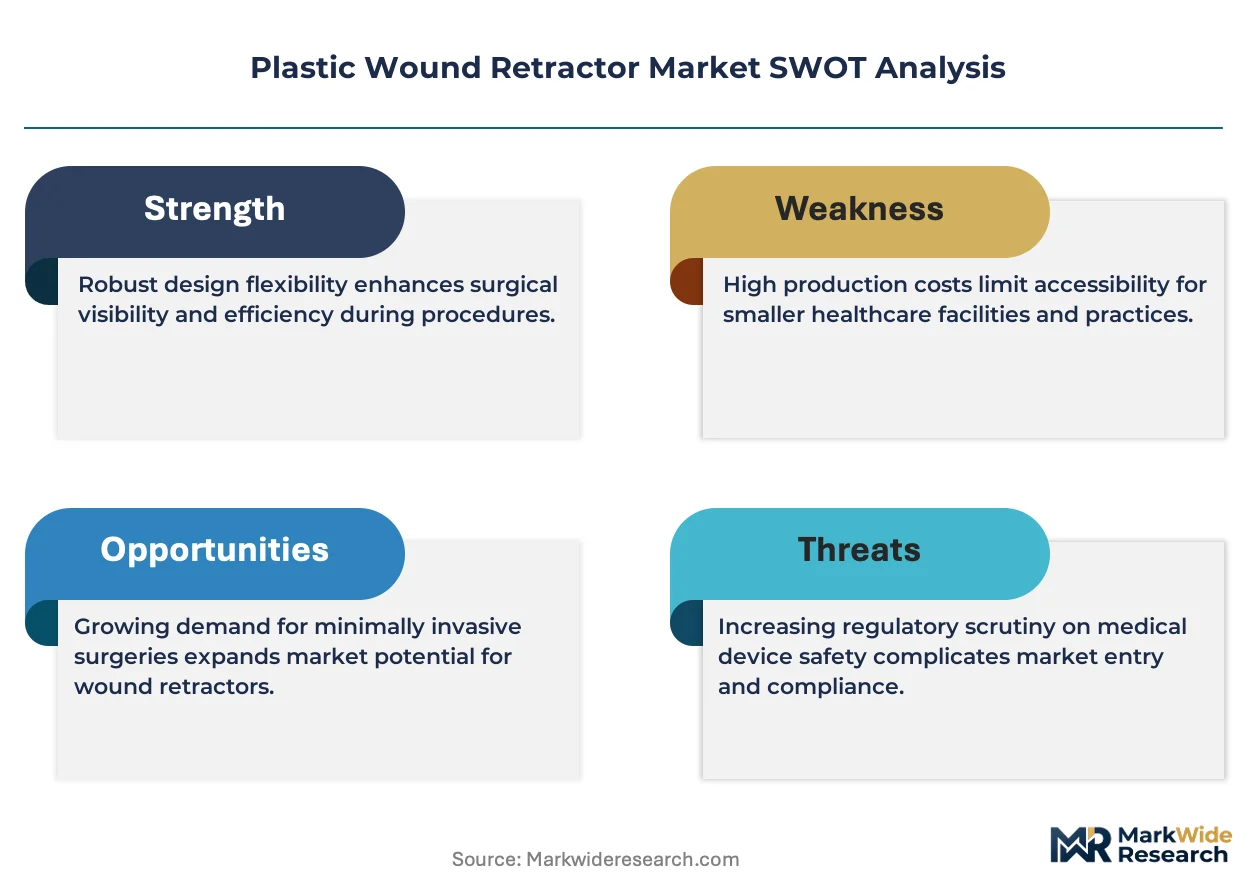
Growth Catalysts
- EU MDR compliance deadlines:Manufacturers accelerating sterile single-use production lines to meet notified body certification timelines ahead of enforcement windows.
- Polypropylene material properties:Superior tensile strength and autoclave compatibility drive preference over polystyrene in reusable surgical retractor segments.
- Japan's aging surgical population:Demographic pressure elevates procedure volumes requiring wound retraction in cardiac and orthopedic specialties.
Market Restraints
- Medical-grade polymer feedstock concentration:Polypropylene resin supply chains cluster around petrochemical hubs in Texas and Rotterdam, exposing manufacturers to input volatility.
- EU AI Act transparency mandates:Automated quality inspection systems face documentation burdens that extend validation cycles for polymer sourcing verification.
- Metal retractor substitution:Stainless steel alternatives persist in orthopedic trauma applications where structural rigidity demands exceed polymer capabilities.
Strategic Opportunities
- Germany's outpatient surgery expansion:Federal reimbursement reforms favor same-day procedures, creating demand for compact, procedure-specific retractor kits.
- Robotic-assisted surgery convergence:Integration with da Vinci and comparable platforms requires retractor geometries compatible with trocar positioning and instrument arm clearance.
- India's PLI scheme for medical devices:Domestic manufacturing incentives attract contract molding capacity for export-oriented single-use retractor production.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies face backlog at certified laboratories, delaying 510(k) submissions to FDA.
- ETO sterilization capacity constraints:Ethylene oxide facility closures in the United States force manufacturers to validate alternative terminal sterilization methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Wound Retractor Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Reusable, Customizable, Sterile Application: General Surgery, Orthopedic Surgery, Plastic Surgery, Cardiac Surgery End User: Hospitals, Specialty Clinics, Surgical Centers, Outpatient Facilities Material: High-Impact Polystyrene, Polypropylene, PVC, Copolymer |
| Companies Covered | Applied Medical Resources, Vaxcon Corporation, Betatech Medical, CooperSurgical, 3M, Medtronic, Ethicon, Hakko, Grena, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Wound Retractor Market Evolving Landscape
Product development cycles are compressing as sterile single-use configurations displace reusable alternatives, while regulatory documentation requirements expand for polymer traceability and sterilization validation.
Biodegradable polymer formulations are displacing conventional polypropylene in select wound retractor applications. European ambulatory surgical centers pilot these materials for low-risk procedures where mechanical demands permit reduced tensile strength. The shift is compressing residual waste liability for facilities facing CSRD reporting obligations on single-use medical device consumption.
EU MDR technical documentation requirements now mandate polymer sourcing disclosure through supply chain tiers. Manufacturers must map virgin resin origins and additive compositions for notified body review. Cardiac surgery retractor producers face the heaviest compliance burden due to extended implantation-adjacent use classifications.
Hospital purchasing cooperatives are consolidating procurement authority for plastic wound retractors into centralized supply agreements. Independent ambulatory surgical centers lose direct vendor relationships as group purchasing organizations aggregate volume and standardize SKU selection. The concentration is most pronounced in United States metropolitan markets where health system consolidation has accelerated.
Plastic Wound Retractor Market Segmentation
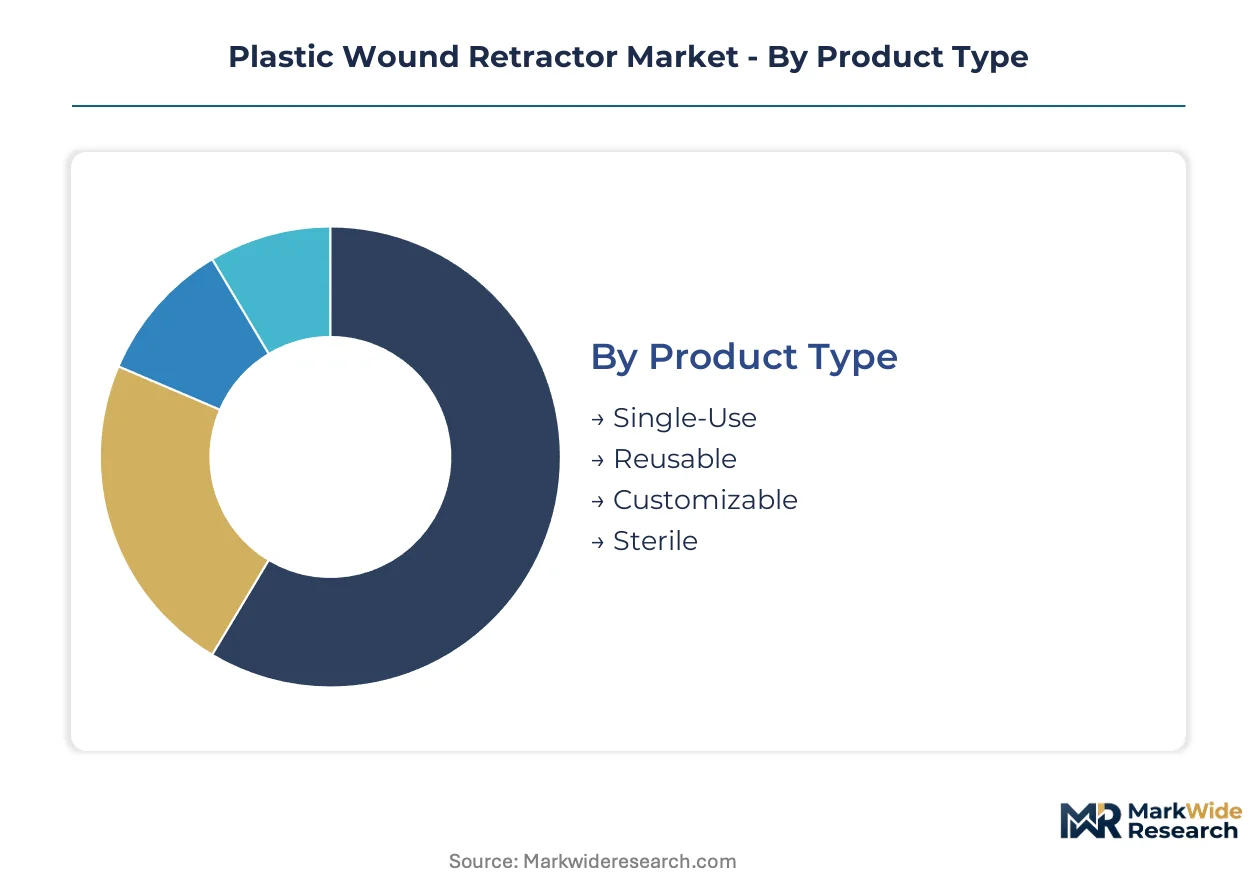
Segmentation in plastic wound retractors exposes divergent margin economics between infection-control premiums and material cost structures. Procurement patterns across ambulatory settings favor single-use configurations, while cardiac applications sustain pricing power through specialized geometries.
Product Type:
Margins concentrate in sterile single-use configurations where infection liability shifts to manufacturers and clinical workflows demand minimal processing.
- Single-Use:Polypropylene-based configurations dominate hospital purchasing through terminal sterilization and elimination of reprocessing labor. Ambulatory surgical centers in the United States drive volume acceleration as same-day procedure protocols expand.
- Reusable:Autoclave-compatible polypropylene variants retain footholds in cost-constrained health systems, though sterilization validation burdens erode operational savings. German outpatient facilities maintain limited procurement for high-volume, low-complexity interventions.
- Customizable:Modular ring diameters and blade configurations address patient-specific anatomical requirements in bariatric and pediatric cases.
- Sterile:Pre-packaged terminal-sterilized units command premium positioning through FDA 510(k) clearance and EU MDR technical documentation compliance.
The dominant share belongs to Single-Use, while Customizable is closing the gap fastest through procedure-specific kit configurations.
Application:
Revenue pools align with surgical complexity tiers, where cardiac and orthopedic specialties sustain equipment premiums through longer procedure durations.
- General Surgery:Cholecystectomy and appendectomy procedures generate the highest unit volumes through standardized ring sizes and minimal customization requirements. Japanese surgical centers drive consistent demand amid aging-related procedure expansion.
- Cardiac Surgery:Reinforced structural geometries and extended implantation-adjacent use classifications trigger EU MDR heightened scrutiny and documentation burdens. German cardiac centers sustain premium procurement for sternal retraction applications.
- Orthopedic Surgery:Trauma applications favor metal alternatives where polymer tensile strength proves insufficient for forceful tissue manipulation.
- Plastic Surgery:Aesthetic and reconstructive procedures demand smaller-diameter retractors with enhanced visual field clarity for delicate tissue handling.
General Surgery captures the volume base, yet Cardiac Surgery delivers the steepest margin expansion trajectory through specialized compliance requirements.
End User:
Procurement authority is consolidating toward centralized purchasing cooperatives that aggregate volume across formerly independent facilities.
- Hospitals:Integrated delivery networks in United States metropolitan markets standardize SKU selection through group purchasing organization contracts, compressing vendor margins.
- Surgical Centers:Ambulatory settings reorganize ordering patterns toward smaller-quantity, higher-frequency deliveries with compact packaging formats. Federal reimbursement reforms in Germany accelerate same-day procedure migration to these facilities.
- Specialty Clinics:Ophthalmic and dermatologic focused practices require miniature retractor configurations for confined anatomical sites.
- Outpatient Facilities:Standalone endoscopy and pain management centers drive demand for procedure-specific disposable kits.
Hospitals retain the installed base majority, though Surgical Centers are expanding most quickly through outpatient migration incentives.
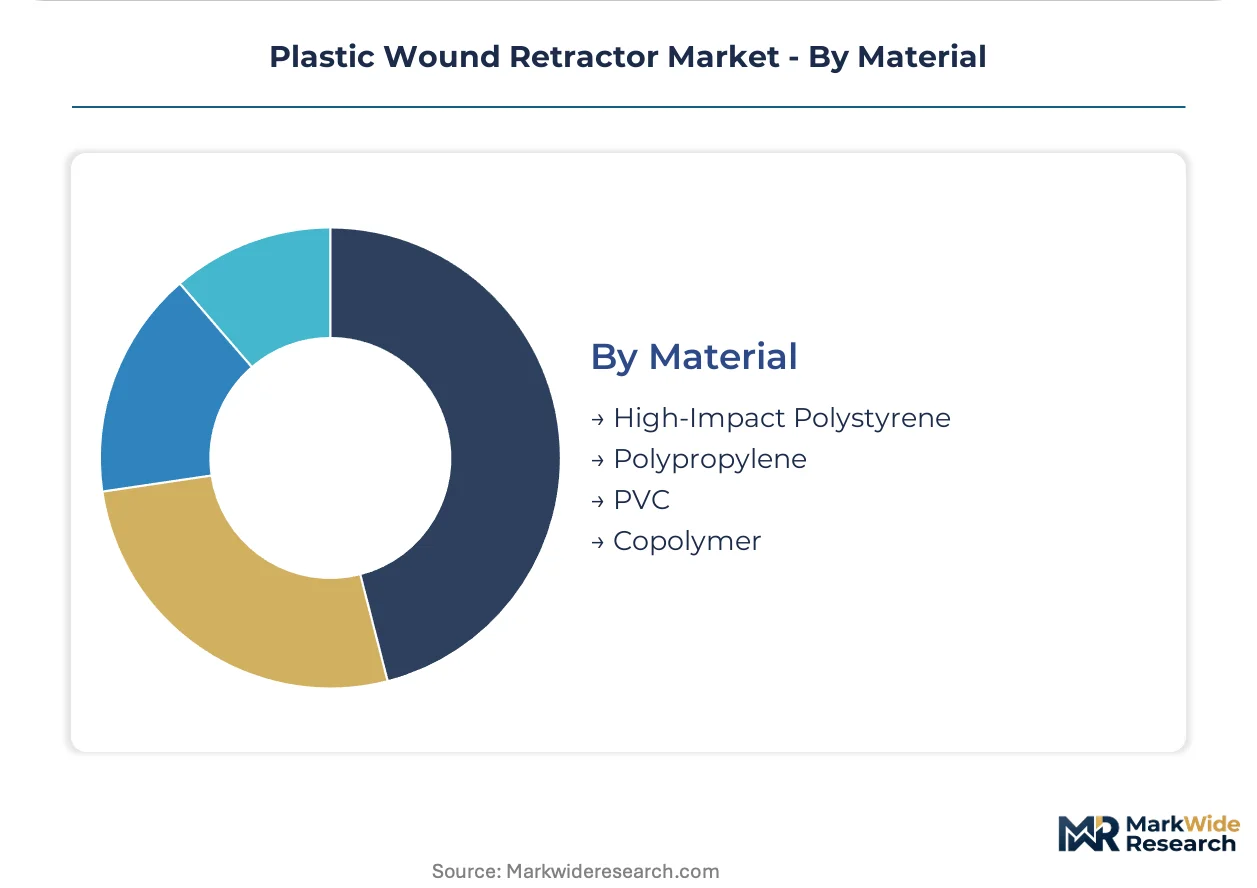
Material:
Supply concentration around petrochemical hubs in Texas and Rotterdam exposes manufacturers to feedstock volatility that propagates through pricing structures.
- Polypropylene:Superior tensile strength and repeated autoclave compatibility sustain preference in reusable segments. Virgin resin sourcing disclosure now mandatory under EU MDR technical documentation for notified body review.
- High-Impact Polystyrene:Lower material costs support single-use economics where mechanical demands permit reduced durability. Biodegradable formulation pilots in European ambulatory centers address CSRD reporting obligations on residual waste.
- PVC:Flexibility characteristics suit adjustable retractor mechanisms requiring repeated deformation cycles.
- Copolymer:Blended formulations balance stiffness and impact resistance for hybrid reusable-single-use product lines.
Polypropylene anchors the material mix, while High-Impact Polystyrene is gaining share fastest through cost-optimized single-use expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's petrochemical throughput anchors European polymer supply chains for medical-grade polypropylene, while Japan's Chubu Centrair International Airport facilitates just-in-time component deliveries to precision manufacturers in the Nagoya medical device cluster.
United States
Ambulatory surgical center expansion across Texas and Florida drives single-use retractor procurement acceleration. FDA 510(k) clearance pathways compress product development cycles for domestic manufacturers seeking rapid market entry. Houston's petrochemical corridor concentrates virgin polypropylene resin production, exposing device makers to feedstock price volatility.
Germany
Federal reimbursement reforms favor same-day procedures, elevating demand for compact retractor kits in Bavarian outpatient clinics. EU MDR technical documentation requirements now mandate polymer sourcing disclosure through supply chain tiers. The Baden-Württemberg medical technology corridor hosts specialized molding capacity for cardiac surgery retractors.
Japan
Aging demographics elevate cardiac and orthopedic procedure volumes requiring wound retraction in Kanto region hospitals. PMDA regulatory harmonization with FDA standards accelerates dual-market product registrations for domestic manufacturers. The Nagoya medical device cluster concentrates precision polymer processing for implantation-adjacent applications.
India
PLI scheme incentives attract contract molding capacity for export-oriented single-use retractor production in Gujarat and Maharashtra. CDSCO medical device regulations tighten quality management expectations for domestic market entry. The Pune-Ahmednagar industrial belt develops sterile packaging capabilities for terminal-sterilized configurations.
United Kingdom
NHS procurement consolidation drives standardized SKU selection across integrated care systems in England. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards for continued market access. The East Midlands medical technology cluster hosts sterilization validation services for polymer-based devices.
Plastic Wound Retractor Market Competitive Landscape
Concentration sits with diversified medtech conglomerates that leverage existing sterile manufacturing infrastructure and established hospital purchasing relationships. The vendor base spans three tiers: integrated multinationals with full surgical portfolios, mid-cap specialists focused on access devices, and regional contract manufacturers serving private-label demand. Strategic moves center on backward integration into polymer compounding and sterilization capacity expansion to secure supply chain control.
Among US-based diversified manufacturers, Applied Medical Resources, Medtronic, and Ethicon exemplify contrasting archetypes. Applied Medical Resources represents vertical integration specialists with captive polymer sourcing capabilities. Medtronic anchors the R&D-intensive tier with ergonomic design investments. Ethicon occupies the brand-differentiated position in sterile single-use configurations. CooperSurgical and 3M sit within the mid-cap specialist segment, while Vaxcon Corporation, Betatech Medical, Hakko, and Grena exemplify regional fabrication capabilities serving localized procurement patterns.
| Leading Market Players |
|---|
| Applied Medical Resources |
| Vaxcon Corporation |
| Betatech Medical |
| CooperSurgical |
| 3M |
| Medtronic |
| Ethicon |
| Hakko |
| Grena |
| Others |
Value Network & Pricing Analysis
Sixty-day inventory cycles for medical-grade polypropylene resin in Rotterdam and Houston directly translate to pricing volatility that manufacturers pass through to hospital purchasing committees. This lead-time exposure concentrates margin pressure on mid-tier suppliers lacking captive polymer sourcing or long-term offtake agreements with Texas petrochemical producers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared sterile configurations from EU MDR-certified variants and unbranded private-label alternatives. Price differentiation hinges on certification grade and volume scale, with ambulatory surgical centers extracting steepest discounts through group purchasing organization aggregation. Cost compression in the economy tier is intensifying because Indian contract manufacturers are scaling export-oriented molding capacity under PLI scheme incentives. Hospital systems exhibit lowest price sensitivity for cardiac surgery applications where liability exposure dominates procurement criteria.
Supply Chain Analysis
Texas and Rotterdam anchor virgin polypropylene resin production for medical-grade polymer feedstock. Supply draws from specialized petrochemical complexes in Houston and the Port of Rotterdam's chemical handling infrastructure, with compounding operations clustered in Germany's Baden-Württemberg corridor. Single-source vulnerability concentrates in ethylene oxide sterilization capacity following US facility closures. Distribution runs through health system group purchasing organizations that aggregate volume across formerly independent ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plastic wound retractor demand sits in early-cycle expansion as same-day procedure protocols penetrate cardiac and orthopedic specialties previously reserved for inpatient settings.
For Market Incumbents: Compound market position through backward integration into polymer compounding capacity in Texas or Rotterdam to neutralize feedstock volatility. Secure EU MDR technical documentation advantages ahead of notified body certification bottlenecks for cardiac surgery retractor classifications. Sterile single-use production line expansion addresses the substitution threat from biodegradable polymer pilots in European ambulatory centers. For New Entrants and Emerging Players: Anchor in India's PLI scheme subsidized manufacturing zones for export-oriented single-use retractor production targeting North American GPO contracts. Germany's outpatient surgery expansion offers the most penetrable geography, with compact procedure-specific kit configurations addressing federal reimbursement reform tailwinds. Direct-to-ambulatory-center distribution bypasses hospital purchasing cooperative consolidation. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medtech conglomerates seeking to divest non-core access device portfolios. Long-term viability frames around robotic-assisted surgery convergence requiring retractor geometries compatible with da Vinci platform trocar positioning. Watch FDA 510(k) submission backlogs at certified biocompatibility laboratories as the inflection signal for supply-constrained pricing power recovery.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified body certification timelines in Germany accelerate sterile single-use market access. |
| Backward Integration into Polymer Compounding | Captive resin sourcing in Houston neutralizes Texas petrochemical hub price volatility exposure. |
| Robotic-Assisted Surgery Platform Partnership | da Vinci-compatible retractor geometries unlock premium positioning in cardiac surgery segments. |
| Biodegradable Polymer Formulation Pilot | European ambulatory center CSRD compliance creates first-mover advantage in waste liability reduction. |
| Group Purchasing Organization Contract Consolidation | Hospital system volume aggregation in United States metropolitan markets compresses vendor margins. |
Research Methodology
The analysis maps single-use, reusable, and customizable retractor configurations, each validated through hospital purchasing committee interviews, GPO contracts managers, biomedical engineers, and sterile processing directors. Primary fieldwork combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and customs trade data. Bottom-up unit shipment modeling triangulated with top-down revenue estimates across polymer material tiers and surgical application segments.
Consistency checks validated volume and value outputs against external benchmarks including CMS procedure volume data, Japanese MHLW surgical statistics, and German federal reimbursement reform implementation timelines. The analytical framework segmented by product type, application specialty, end-user facility class, and material composition across the projection horizon. CAGRs derived from procedure volume elasticity models incorporating aging demographic coefficients and outpatient migration policy shifts.
Material uncertainties — regulatory harmonization delays, sterilization capacity disruptions, polymer feedstock price shocks — sit outside the modeled envelope. Forecasts reflect assumptions about EU MDR enforcement consistency and ambulatory surgical center reimbursement stability. Recalibration cycles align with material shifts in FDA 510(k) backlog resolution and notified body certification throughput.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
United Arab Emirates General Surgical Devices Market
Surgical Instruments
US Surgical Staplers Market
Surgical Instruments
Global Veterinary Surgical Instruments Market
Surgical Instruments
Global Surgical Instruments Market
Surgical Instruments
Middle East and Africa General Surgical Devices Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Global Arthroscopy Instruments Market
Surgical Instruments
Global Microsurgical Instruments Market
Surgical Instruments
High Flow Needle Sets Market
Surgical Instruments
Dissolvable Sutures Market
Surgical Instruments
Europe General Surgical Devices Market
Surgical Instruments
Homecare Surgical Drains Market
Surgical Instruments
Hydrosurgery Systems Market
Surgical Instruments
Surgical Lamps Market
Surgical Instruments
South Korea General Surgical Devices Market
Surgical Instruments
Global Gauze Swabs Market