
 Global Perineal Care Market | 2026-2036
Global Perineal Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Perineal Care Market Foresight
Buyer concentration across long-term care facilities is realigning procurement power toward larger regional operators with standardized hygiene protocols. Medline Industries leverages its direct distribution network to control supply relationships with multi-facility operators. Coloplast differentiates through hydrocolloid-based barrier formulations that target high-acuity incontinence segments. Essity Aktiebolag anchors European demand through its TENA institutional brand and captive manufacturing of superabsorbent cores.
Perineal care encompasses cleansers, barriers, and moisturizers formulated for skin integrity maintenance in the perineal region, typically incorporating pH-balanced surfactants, dimethicone barriers, and humectants such as glycerin or allantoin to prevent moisture-associated skin damage in immobilized or incontinent patients. Wipes dominate volume throughput in acute settings due to single-use convenience and cross-contamination protocols, while creams command premium positioning in surgical recovery and dermatology applications where epidermal barrier restoration drives reimbursement eligibility. Among end users, hospices and long-term care facilities represent the deepest margin pools given their recurring purchase structures and formulary lock-in dynamics, whereas home healthcare providers constitute the fastest-growing channel as post-discharge monitoring protocols expand.
The FDA regulates perineal wipes and barriers as Class I or II medical devices depending on antimicrobial claims, while the EU MDR requires notified body involvement for products with therapeutic indications, elevating documentation burdens for barrier creams marketed in Germany, France, and Italy. The EPA's emerging scrutiny of quaternary ammonium compounds in surface and skin disinfectants is pressuring reformulation toward benzalkonium chloride alternatives or preservative-free systems. Stakeholders must monitor evolving biocompatibility testing standards and reimbursement code consolidation across Medicare Advantage plans and national health services.
Market Dynamics
Buyer consolidation across long-term care chains is compressing supplier margins while elevating formulary control toward regional procurement directors who mandate standardized pH-balanced protocols across facility networks.
Growth Catalysts
- EU MDR clinical evidence mandates:Germany's notified bodies now require biocompatibility documentation for dimethicone barriers, accelerating institutional adoption of pre-validated product lines that reduce compliance risk for nursing home operators.
- Post-acute care infrastructure:Japan's Ministry of Health expansion of community-based integrated care systems is embedding perineal hygiene protocols into discharge planning, creating recurring demand from home healthcare agencies.
- Superabsorbent polymer advances:Captive manufacturing of odor-neutralizing cores is enabling thinner wipe constructions that reduce waste disposal costs for hospice operators managing high-frequency incontinence episodes.
Market Restraints
- Petrochemical feedstock volatility:Dimethicone and petroleum-derived surfactants face price instability tied to refinery output fluctuations, squeezing margin predictability for barrier cream manufacturers.
- Quaternary ammonium compound scrutiny:The EPA's emerging restrictions on benzalkonium chloride in skin-contact applications is forcing preservative system reformulations that extend R&D timelines by 12-18 months.
- Single-use wipe disposal regulations:France's AGEC law mandates extended producer responsibility for plastic-containing hygiene products, elevating compliance costs for wipes with synthetic fibers.
Strategic Opportunities
- India's geriatric care expansion:The country's National Programme for Health Care of the Elderly is funding district-level long-term care facilities where institutional perineal care protocols remain underdeveloped.
- Preservative-free formulation platforms:Steam-sterilized wipe systems using aseptic packaging are penetrating surgical recovery units where antimicrobial resistance concerns drive preference shifts.
- Remote patient monitoring integration:Smart incontinence detection systems paired with automated cleansing alerts are creating bundled service opportunities for home healthcare technology providers in Germany and the Netherlands.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies face backlog at accredited laboratories, delaying EU market entry for novel barrier formulations.
- Cross-functional talent scarcity:Formulation chemists with combined expertise in dermatological science and medical device regulatory pathways command premium compensation that mid-tier manufacturers struggle to match.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Perineal Care Market |
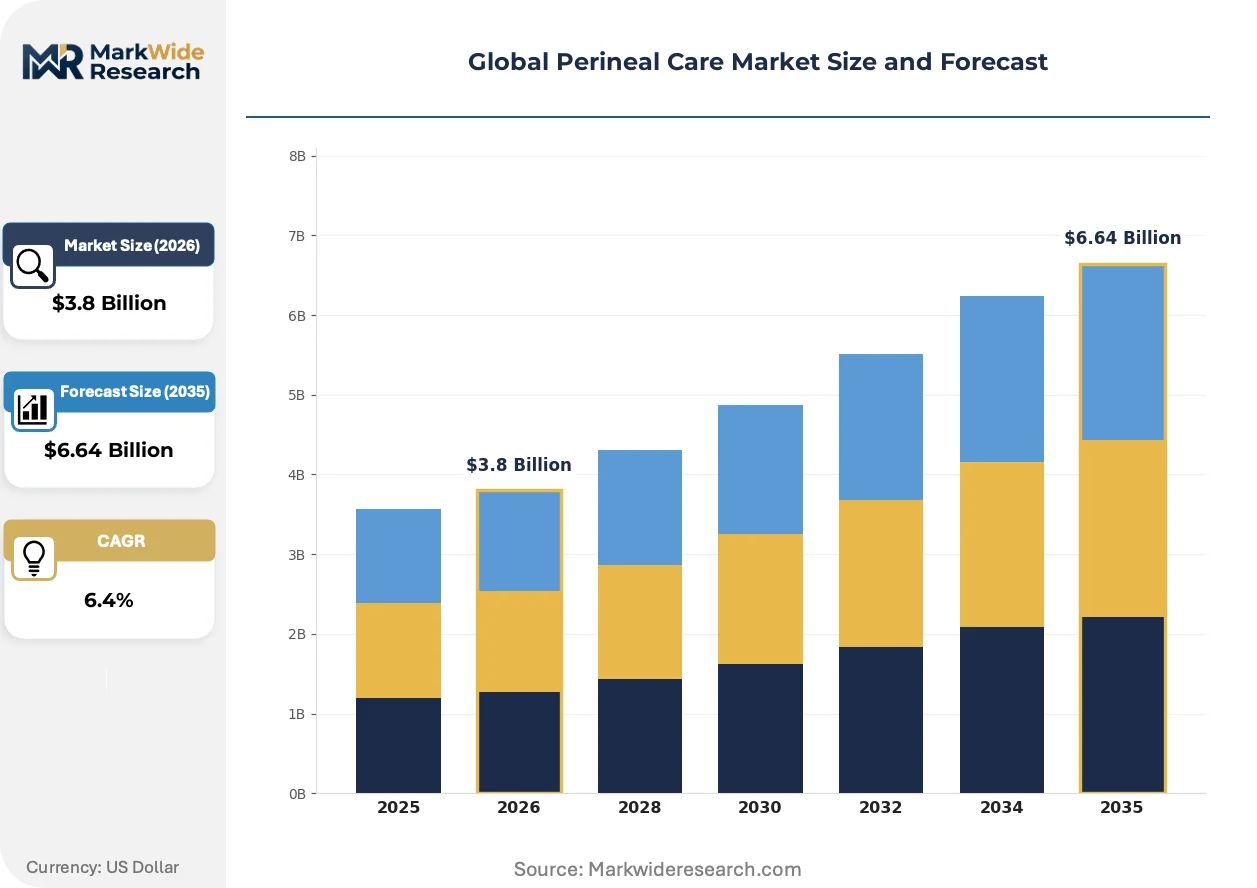
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wipes, Creams, Washes, Sprays, Ointments Application: Postpartum Care, Incontinence Management, Surgical Recovery, Elderly Care, Dermatology End User: Hospices, Home Healthcare Providers, Long-Term Care Facilities, Rehabilitation Centers, Maternity Clinics Channel: Hospital Pharmacies, Online Retailers, Medical Distributors, Specialized Stores, Direct Sales |
| Companies Covered | Medline Industries, 3M Company, Coloplast, ConvaTec Group, Cardinal Health, Smith & Nephew, GOJO Industries, Essity Aktiebolag, Sage Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Perineal Care Market Shifts & Advancements
Formulation science and regulatory compliance are converging to redefine product architectures, with pH optimization and biodegradability emerging as non-negotiable design parameters rather than premium differentiators.
Plant-derived surfactant systems derived from coconut glucosides and sugar-based cleansers are absorbing market share from petroleum-based alternatives as Germany's Blue Angel ecolabel and France's Ecolabel criteria tighten procurement specifications for public healthcare facilities. Long-term care operators in Scandinavia now specify renewable content thresholds in tender documents, compressing demand for conventional formulations that lack third-party sustainability certification.
The FDA's ongoing reclassification of antimicrobial wipes containing quaternary ammonium compounds is forcing manufacturers to submit 510(k) premarket notifications for products previously exempt as general wellness items. This regulatory friction is elevating documentation burdens for US market entrants while creating competitive shelter for established players with existing device clearances, particularly affecting barrier creams with therapeutic moisture-protection claims.
Consolidated procurement through regional healthcare purchasing cooperatives is displacing decentralized facility-level ordering across the United States, with Group Purchasing Organizations negotiating multi-year formulary lock-ins that privilege suppliers offering compliance training and inventory management systems. This behavioral shift is most visible in the Southwest and Midwest, where Catholic health systems and for-profit chains have centralized hygiene protocol standardization across 50-plus facility networks.
Global Perineal Care Market Segmentation
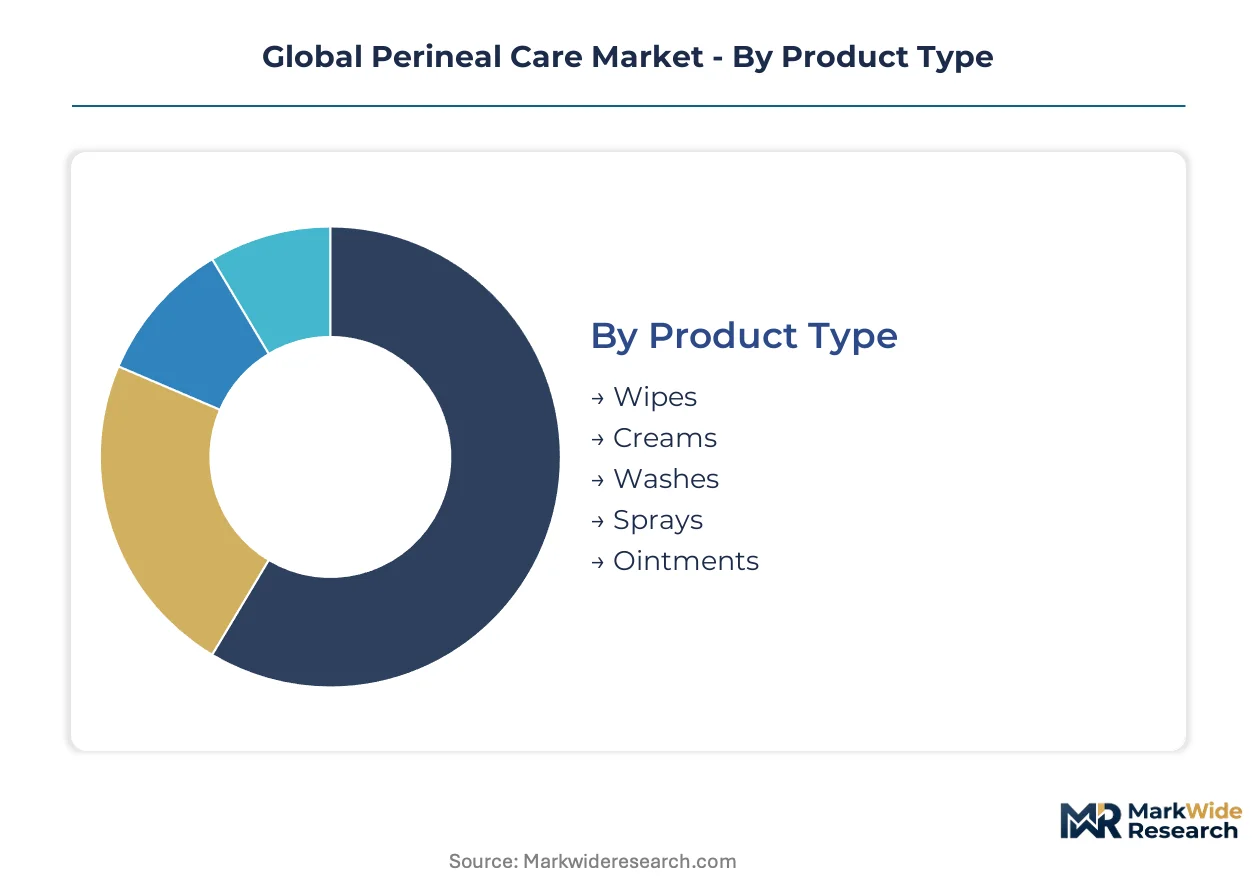
Perineal care segmentation reflects divergent clinical priorities across institutional and consumer channels. Product architectures vary sharply between high-volume disposable formats for acute settings and premium restorative formulations for surgical and dermatological applications.
Product Type:
The customization-standardization spectrum spans from commodity wipes with fixed pH specifications to bespoke barrier creams with patient-specific dimethicone concentrations.
- Wipes:Pre-moistened cellulose or synthetic fiber substrates impregnated with pH-balanced surfactant systems, typically incorporating glycerin humectants and benzalkonium chloride preservatives. Demand concentrates in German hospices and Japanese long-term care facilities where high-frequency incontinence episodes mandate single-use protocols and waste reduction imperatives drive thinner superabsorbent constructions.
- Creams:Semi-occlusive barrier formulations combining petrolatum or dimethicone with zinc oxide or allantoin for epidermal restoration. Surgical recovery units in the United States and dermatology clinics in France command premium positioning where Medicare Advantage and national health service reimbursement eligibility hinges on therapeutic moisture-protection claims.
- Washes:Rinse-free cleansing foams with coconut-derived glucoside surfactants for bed-bound patient hygiene.
- Sprays:Aerosol or pump-dispensed liquid barriers for difficult-to-reach perineal areas in bariatric care.
- Ointments:Petrolatum-based protective layers with higher occlusivity for severe moisture-associated skin damage.
Leading the category by volume: Wipes. Growing fastest: Creams.
Application:
Cost tier stratification separates reimbursable clinical indications from out-of-pocket wellness purchases.
- Incontinence Management:Protocol-driven skin integrity maintenance for urinary and fecal incontinence, incorporating barrier creams with documented moisture vapor transmission rates. Institutional procurement in the United States and Germany favors pre-validated product lines that satisfy FDA device classification and EU MDR biocompatibility documentation requirements.
- Surgical Recovery:Post-operative perineal hygiene following colorectal, urological, or gynecological procedures where epidermal barrier restoration accelerates discharge timelines. French and Italian reimbursement frameworks elevate formulary control toward hydrocolloid-based systems with notified body certification.
- Postpartum Care:Perineal cleansing and soothing protocols for maternal recovery, typically midwife-directed in European maternity systems.
- Elderly Care:General skin integrity maintenance in geriatric populations with reduced mobility and compromised epidermal resilience.
- Dermatology:Specialist-prescribed interventions for inflammatory or infectious perineal conditions requiring compounding pharmacy involvement.
Deepest margin pools: Surgical Recovery. Steepest expansion trajectory: Incontinence Management.
End User:
Customer type determines purchasing frequency, formulary lock-in duration, and compliance training requirements.
- Long-Term Care Facilities:Multi-bed institutions with standardized hygiene protocols across regional operator networks, typically negotiating multi-year formulary lock-ins through Group Purchasing Organizations. Catholic health systems and for-profit chains in the United States Southwest and Midwest centralize procurement across 50-plus facility networks.
- Home Healthcare Providers:Post-discharge monitoring agencies embedding perineal hygiene into community-based integrated care systems. Japan's Ministry of Health expansion of these systems creates recurring demand from agencies managing aging-in-place populations.
- Hospices:End-of-life care facilities with high-frequency incontinence episodes and waste disposal cost sensitivities.
- Rehabilitation Centers:Post-acute facilities with transitional care protocols bridging hospital and home settings.
- Maternity Clinics:Midwife-led or obstetrician-directed perinatal care with protocol variation across national health systems.
Most concentrated procurement power: Long-Term Care Facilities. Gaining share fastest: Home Healthcare Providers.
Channel:
Supply concentration in medical distribution contrasts with emerging direct-to-institution models.
- Medical Distributors:Regional and national wholesalers controlling inventory management and compliance training for multi-facility operators. Medline Industries leverages direct distribution networks to anchor supply relationships with standardized protocol mandates.
- Hospital Pharmacies:Captive dispensing within acute care institutions with formulary committees privileging pre-cleared device classifications.
- Online Retailers:E-commerce platforms penetrating home healthcare and postpartum segments where patient-directed purchasing bypasses institutional procurement.
- Specialized Stores:Medical supply retailers serving outpatient dermatology and surgical recovery patients with prescription-linked transactions.
- Direct Sales:Manufacturer-to-institution contracts for large regional operators with customized logistics and training bundles.
Dominant throughput: Medical Distributors. Expanding most quickly: Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, Japan, and the United States, where aging demographics and post-acute care infrastructure investments are accelerating institutional adoption of advanced perineal care systems.
United States
Long-term care chains in the Southwest and Midwest are consolidating procurement across 50-plus facility networks through Group Purchasing Organizations. The FDA's medical device classification updates for antimicrobial wipes are elevating documentation burdens for new market entrants. Catholic health systems in these regions mandate standardized pH-balanced protocols across their networks.
Germany
Notified bodies under the EU MDR now require biocompatibility documentation for dimethicone barriers, accelerating institutional adoption of pre-validated product lines. The country's Blue Angel ecolabel criteria tighten procurement specifications for public healthcare facilities. Manufacturing clusters in North Rhine-Westphalia supply superabsorbent cores to continental European markets.
Japan
The Ministry of Health's expansion of community-based integrated care systems embeds perineal hygiene protocols into discharge planning. METI guidelines on medical device quality management shape formulation standards for skin-contact products. Home healthcare agencies in the Kanto region manage recurring demand from aging-in-place populations.
France
The AGEC law mandates extended producer responsibility for plastic-containing hygiene products, elevating compliance costs for wipes with synthetic fibers. ANSM oversight of therapeutic barrier claims drives notified body involvement for premium creams. Procurement in the Île-de-France region privileges hydrocolloid-based systems with documented clinical evidence.
India
The National Programme for Health Care of the Elderly funds district-level long-term care facilities where institutional perineal care protocols remain underdeveloped. CDSCO medical device rules are gradually aligning with international standards for skin-contact products. State-level health missions in Maharashtra and Karnataka pilot standardized hygiene protocols in geriatric wards.
Global Perineal Care Market Competitive Landscape
United States producers anchor one tier; European specialists hold formulation differentiation through notified body certifications. The vendor base spans diversified medical supply conglomerates, dedicated wound care companies, and hygiene-focused consumer health groups. Three archetypes dominate: direct-distribution medical suppliers, hydrocolloid barrier specialists, and captive superabsorbent manufacturers. Consolidation through Group Purchasing Organization formulary lock-ins and backward integration into polymer supply are the primary competitive vectors.
Within the direct-distribution tier, Medline Industries exemplifies supply relationship control with multi-facility operators. Coloplast occupies a position among barrier formulation specialists, while Essity Aktiebolag anchors European demand through institutional brand presence and in-house superabsorbent production. These three represent distinct strategic postures: logistics-dominated, clinically differentiated, and vertically integrated.
| Leading Market Players |
|---|
| Medline Industries |
| 3M Company |
| Coloplast |
| ConvaTec Group |
| Cardinal Health |
| Smith & Nephew |
| GOJO Industries |
| Essity Aktiebolag |
| Sage Products |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap manufacturers in North Rhine-Westphalia and the American Midwest anchor supply discipline through conservative leverage policies that buffer raw material volatility while preserving pricing power against private-equity-rolled competitors chasing volume share.
Pricing Analysis
Wipes command thin margins at high throughput while creams capture premium spreads in reimbursable clinical segments. Three-tier pricing structure across premium, standard, and economy levels separates hydrocolloid-based barrier systems with notified body certification from commodity petrolatum formulations and private-label alternatives. Cost compression in the wipes tier intensifies because Group Purchasing Organizations negotiate multi-year formulary lock-ins that privilege suppliers with captive manufacturing. Hospices and long-term care chains exhibit the sharpest price sensitivity, whereas surgical recovery units and dermatology clinics prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Reverse-logistics flows for synthetic-fiber wipe returns face mounting friction under France's AGEC extended producer responsibility mandates, elevating compliance costs for distributors managing multi-national facility networks. Manufacturing concentrates in Germany, the United States, and Japan, with superabsorbent polymer production anchored in North Rhine-Westphalia and captive dimethicone synthesis in Texas and Louisiana. Feedstock dependencies rest on petroleum-derived surfactants, cellulose pulp, and medical-grade silicones. Single-source vulnerability in benzalkonium chloride supply chains intensifies as EPA scrutiny forces preservative system reformulations. Distribution runs through regional medical wholesalers with direct-to-institution contracts displacing decentralized facility ordering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The perineal care sector sits in a formulation-transition phase, with plant-derived surfactant systems and preservative-free platforms displacing legacy petroleum-based and quaternary ammonium compound chemistries.
For Market Incumbents: Deepen backward integration into superabsorbent polymer supply to defend margin position against feedstock volatility and secure formulary lock-ins with Group Purchasing Organizations. Invest in ISO 10993 biocompatibility documentation ahead of EU MDR enforcement waves to create compliance moats that delay challenger entry.
For New Entrants and Emerging Players: The mid-tier price gap between Coloplast's hydrocolloid premiums and economy private-label wipes offers white-space positioning for coconut glucoside-based alternatives with Blue Angel certification. Target India's district-level long-term care facilities under the National Programme for Health Care of the Elderly, where institutional protocols remain underdeveloped and first-mover training relationships cement recurring demand.
For Investors and Strategic Acquirers: Distressed-cycle entries favor European notified-body-certified formulators with existing dimethicone barrier clearances as regulatory documentation backlogs lengthen. Long-term viability hinges on five-to-ten year windows for preservative-free platform adoption. Monitor EPA benzalkonium chloride restriction timelines as the critical inflection signal for reformulation capex cycles and competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Preservative-Free Platform Development | Steam-sterilized aseptic packaging addresses antimicrobial resistance concerns in surgical recovery units. |
| Notified Body Certification Investment | EU MDR biocompatibility documentation creates competitive shelter in German and French institutional procurement. |
| Superabsorbent Polymer Backward Integration | Captive core manufacturing reduces waste disposal costs for hospice operators managing high-frequency episodes. |
| India Distribution Partnership | District-level facility relationships under the National Programme for Health Care of the Elderly secure first-mover positioning. |
| Smart Incontinence System Integration | Automated cleansing alerts bundled with remote monitoring penetrate German and Dutch home healthcare channels. |
Research Methodology
Multi-period observation of formulation patent filings, notified body certification timelines, and Group Purchasing Organization contract awards anchored the trend analysis, supplemented by interviews with regulatory affairs directors at barrier cream manufacturers, procurement managers at multi-facility long-term care operators, biomedical engineers specializing in skin-contact devices, and distribution executives at regional medical wholesalers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR notified body guidance documents, EPA chemical substance restrictions, and hospital procurement contract disclosures. Bottom-up volume estimates triangulated against top-down expenditure flows from national health service reimbursement frameworks.
Input-output matrix modeling connected raw material cost indices for dimethicone and cellulose pulp to finished product pricing tiers across wipes, creams, and wash formats. Segmentation dimensions spanned product architecture, clinical application, end-user facility type, and distribution channel structure. CAGRs were derived from logistic adoption curves fitted to institutional procurement cycle data and demographic projections for aging populations. Forecast inputs incorporated EU MDR implementation pace and EPA quaternary ammonium compound regulatory trajectory.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time Group Purchasing Organization contract pricing introduce uncertainty bands around volume share estimates. Forecasts reflect documented assumptions regarding reimbursement code consolidation and biocompatibility testing laboratory capacity expansion. Practitioners should monitor EPA benzalkonium chloride restriction announcements and EU MDR notified body backlog reports for early signals of competitive repositioning timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
Shoe Cover Market
Patient Care Supplies
GCC Adult Diaper Market
Patient Care Supplies
Asia-Pacific Hospital Supplies Market
Patient Care Supplies
External Urine Management Products Market
Patient Care Supplies
Reusable Nursing Pads Market
Patient Care Supplies
Hip Shield Market
Patient Care Supplies
Patient Identification Wristbands Market
Patient Care Supplies
Therapy Pillow Market
Patient Care Supplies
Global Stoma Care/Ostomy Care and Accessories Market
Patient Care Supplies
Global Incontinence and Ostomy Care Product Market
Patient Care Supplies
Stoma Care Market
Patient Care Supplies
Ice Packs for Pain Market
Patient Care Supplies
Global Patient Lateral Transfer Market
Patient Care Supplies
Stretcher Accessories Market
Patient Care Supplies
Disposable Incontinence Products (Dips) Market
Patient Care Supplies
Self Inflating Bag Market