
 Surgical Sutures Market | 2026-2036
Surgical Sutures Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Sutures Market Intelligence
Asset-light leasing models for surgical kitting services is rewriting competitive entry barriers for mid-tier manufacturers. Johnson & Johnson Services, Inc. [Ethicon] leverages its captive polymer supply chain to sustain margin control across absorbable product lines. Medtronic anchors North American hospital contracts through integrated wound-closure bundles. B. Braun SE differentiates its European positioning with proprietary needle alloy formulations that reduce tissue drag.
Surgical sutures are sterile, thread-like medical devices manufactured from natural or synthetic polymers such as polyglycolic acid or polypropylene, designed to approximate wound edges and maintain tensile strength through defined absorption or permanent retention periods. Their primary commercial purpose is to enable reliable tissue closure across operative procedures while minimizing infection risk and scar formation. Absorbable sutures lead product type revenue due to their elimination of follow-up removal visits, though antibacterial sutures represent the fastest-growing category as infection-control protocols tighten. Polyglycolic acid dominates material demand for its predictable hydrolytic degradation profile, while silk retains niche use in cardiovascular and ophthalmic specialties where handling supersedes absorption needs.
FDA 510(k) clearance pathways and EU MDR Class IIa certification requirements shape product development timelines and clinical evidence burdens for manufacturers seeking market access. ISO 10993 biocompatibility testing and USP tensile-strength standards further constrain material substitutions and supplier qualification processes. Stakeholders must monitor how FDA's evolving sterilization validation guidance and EMA's renewed focus on particulate contamination limits will reshape manufacturing compliance investments and outsourcing decisions.
Market Dynamics
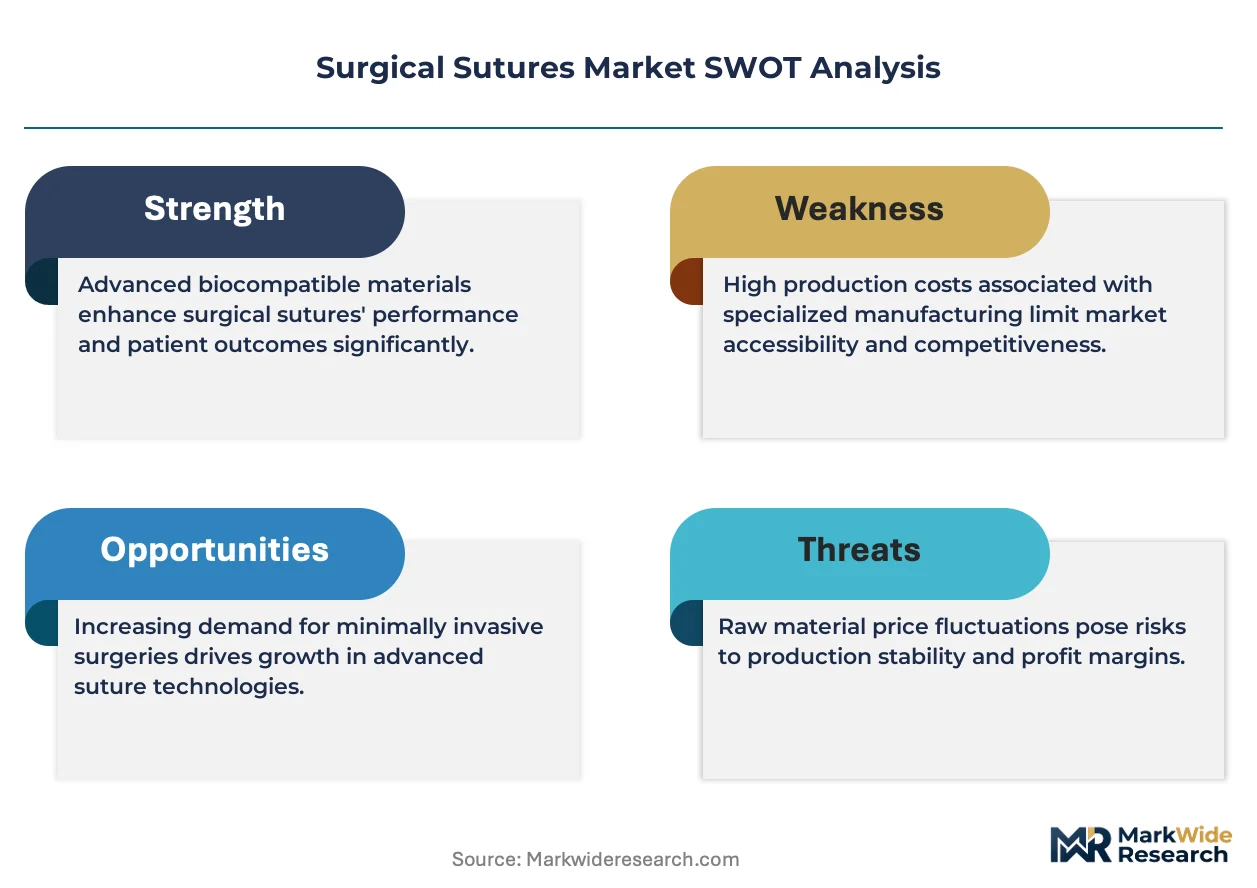
Polymer supply concentration and sterilization validation complexity are compressing margin structures for mid-tier manufacturers while rewarding integrated producers with captive raw material streams.
Growth Catalysts
- India PLI Scheme for Medical Devices:Domestic manufacturing incentives are accelerating local suture production capacity in Asia-Pacific surgical hubs, reducing import dependency for government hospital networks.
- Antibacterial suture protocols:Infection-control mandates in tertiary care centers are driving substitution toward triclosan-coated and polyhexamethylene biguanide-impregnated product lines.
- Cardiovascular procedure volumes:Rising coronary artery bypass grafting and valve replacement caseloads in China's tier-1 cities is expanding demand for silk and polyester non-absorbable specialty sutures.
Market Restraints
- Polyglycolic acid monomer supply:Three Asian petrochemical conglomerates control upstream glycolide feedstock, creating price volatility exposure for non-integrated suture manufacturers.
- EU MDR Class IIa clinical evidence burdens:Extended conformity assessment timelines and notified body capacity constraints are delaying product launches across European markets by 18-24 months.
- Surgical stapler substitution:Powered endoscopic stapling systems are capturing incision closure share in laparoscopic cholecystectomy and bariatric procedures, particularly in North American ambulatory surgery centers.
Strategic Opportunities
- Vietnam and Indonesia hospital buildouts:Government infrastructure programs in Southeast Asia are creating first-mover advantages for suture kitting service providers establishing regional distribution hubs.
- Bioresorbable polymer-electronics convergence:Integration of conductive polymer sutures with real-time wound monitoring sensors opens post-operative care revenue streams in reconstructive surgery segments.
- Asset-light leasing models:Subscription-based surgical kitting services reduce capital barriers for mid-tier manufacturers seeking hospital contract access without sterile packaging facility investments.
Industry Challenges
- Needle alloy metallurgy expertise:Scarce specialized engineers capable of optimizing 300-series stainless and proprietary ternary alloy formulations for reduced tissue drag limit product differentiation velocity.
- ISO 10993 biocompatibility testing bottlenecks:Contract laboratory capacity constraints and extended cytotoxicity study durations are compressing product development cycle predictability.
- Sterilization validation protocol transitions:FDA's evolving guidance on ethylene oxide residual limits and alternative sterilization modalities requires manufacturing line requalification investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Sutures Market |
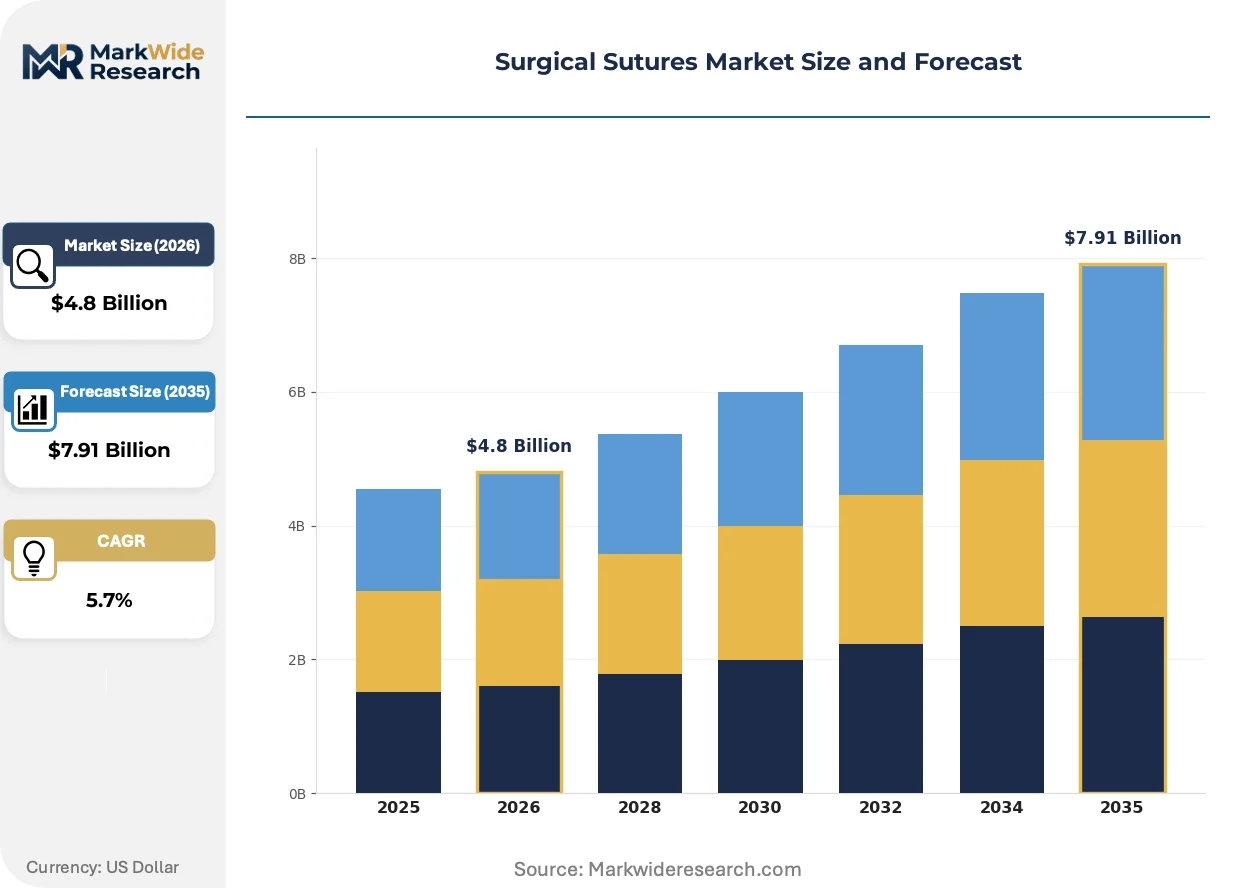
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable Sutures, Non-Absorbable Sutures, Combination Sutures, Antibacterial Sutures Material: Silk, Nylon, Polypropylene, Polyglycolic Acid End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Distribution Channel: Direct Sales, Online Sales, Medical Distributors, Retail Pharmacies |
| Companies Covered | Smith & Nephew, Boston Scientific Corporation, Johnson & Johnson Services, Inc. [Ethicon], Healthium MedTech, CONMED Corporation, Medtronic, Advanced Medical Solutions Group Plc, DemeTECH Corporation, B. Braun SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Sutures Market Strategic Shifts & Innovations
Active polymer science advances and regulatory sterilization mandates are redefining product performance benchmarks while procurement centralization is restructuring channel economics for wound closure devices.
Barbed knotless suture technology eliminates the need for traditional knot-tying during laparoscopic closure, accelerating operative efficiency in minimally invasive procedures. Academic medical centers in Germany and South Korea are adopting these systems at the fastest clip for myomectomy and sleeve gastrectomy applications. Conventional interrupted suturing technique is rendering obsolete in these high-volume surgical environments where operative time directly correlates with throughput economics.
EMA's renewed particulate contamination limits for Class IIa medical devices are forcing manufacturers to implement sub-10 micron filtration systems and enhanced cleanroom protocols across European production facilities. The industrial consequence is a bifurcation between integrated producers with capital reserves for compliance upgrades and contract manufacturers facing facility obsolescence. Absorbable synthetic suture lines with complex braided architectures are most affected, as fiber fraying and surface particulate generation pose elevated detection risks.
Hospital procurement consortiums are consolidating suture purchasing into integrated wound-closure bundles that span sutures, staplers, and topical skin adhesives under single-source contracts. Distributor margins are compressing as these buying collectives disintermediate traditional medical-surgical supply intermediaries. This pattern is most visible in United States health system alliances and National Health Service England procurement frameworks, where standardization incentives override brand loyalty in vendor selection criteria.
Surgical Sutures Market Segmentation
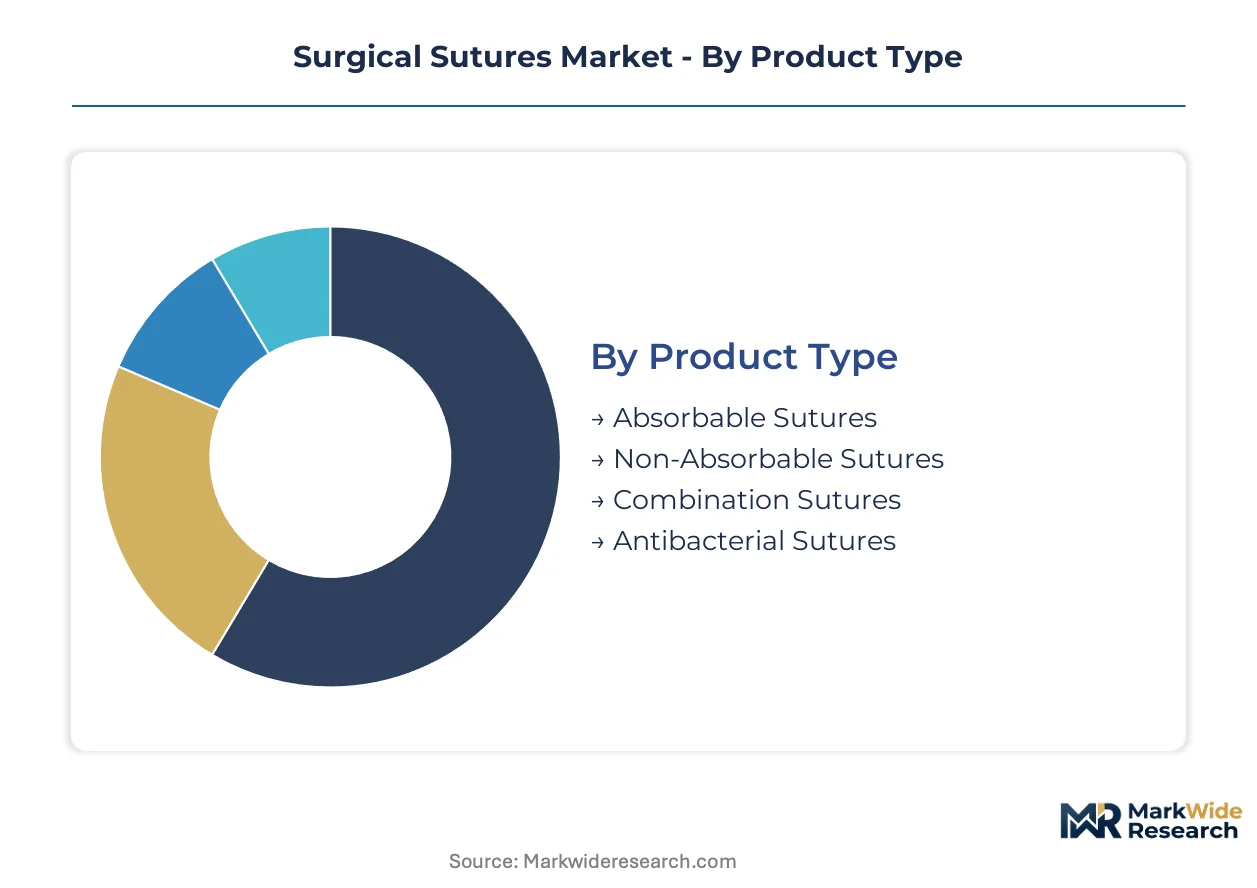
Surgical suture segmentation reveals how polymer chemistry, procedural setting, and procurement channel intersect to determine margin structures. Manufacturers configure product portfolios across these dimensions to match reimbursement environments and sterilization requirements in target markets.
Product Type:
Mature absorbable formats dominate hospital formulary placement while emerging antibacterial coatings command premium positioning in infection-control protocols.
- Absorbable Sutures:Polyglycolic acid and polylactic acid copolymers hydrolyze predictably within 60-90 days, eliminating removal visits. General surgery departments in Indian government hospitals specify these for hernia repair and appendectomy closure where follow-up access is limited.
- Antibacterial Sutures:Triclosan-impregnated or polyhexamethylene biguanide-coated filaments suppress Staphylococcus aureus colonization at the wound interface. Tertiary care centers in China's tier-1 cities are mandating these for orthopedic and cardiovascular procedures under revised nosocomial infection protocols.
- Non-Absorbable Sutures:Permanent tensile retention suits cardiovascular anastomosis and ophthalmic microsurgery where long-term structural support outweighs absorption benefits.
- Combination Sutures:Hybrid constructions pair absorbable cores with non-absorbable sheaths for staged tensile strength degradation in complex wound closure.
Absorbable Sutures handles the majority of throughput; Antibacterial Sutures is the fastest mover on share.
Material:
Cost tier stratification separates commodity polymer feedstocks from specialty alloys and natural fibers with handling-dependent premiums.
- Polyglycolic Acid:Synthetic aliphatic polyester with predictable bulk erosion kinetics and minimal tissue reaction. Korean and Chinese manufacturers have scaled glycolide polymerization capacity under domestic medical device incentives, compressing regional price benchmarks.
- Silk:Natural fibroin protein with superior knot security and minimal memory, prized in cardiovascular and ophthalmic microsurgery where instrument handling precision is paramount.
- Polypropylene:Isotactic crystalline polymer providing permanent tensile strength with minimal inflammatory response, standard for hernia mesh fixation and vascular anastomosis.
- Nylon:Polyamide filament with high elasticity and low tissue drag, retained for skin closure and plastic surgery applications where cosmetic outcome is prioritized.
Polyglycolic Acid commands the highest volume throughput; silk maintains the steepest premium tier.
End User:
Customer type determines packaging configuration, sterilization validation burden, and contract pricing structures across institutional procurement channels.
- Hospitals:Integrated health systems negotiate multi-year wound-closure bundles spanning sutures, staplers, and topical adhesives. India's government hospital expansion under the PLI scheme for medical devices is concentrating demand in public sector tertiary facilities.
- Ambulatory Surgical Centers:Procedure-specific kitting and just-in-time inventory requirements favor distributors with regional logistics infrastructure. German and South Korean day-surgery networks are adopting barbed knotless systems for efficiency gains in high-volume laparoscopic procedures.
- Specialty Clinics:Dermatology and ophthalmology practices prioritize handling characteristics and cosmetic outcomes over unit cost.
- Research Institutions:Preclinical and biomechanical studies drive demand for experimental polymer formulations and custom needle geometries.
Hospitals absorb the dominant procurement volume; Ambulatory Surgical Centers are expanding most quickly as procedure migration accelerates.
Distribution Channel:
Supply concentration varies from direct manufacturer relationships to fragmented retail pharmacy networks with working capital constraints.
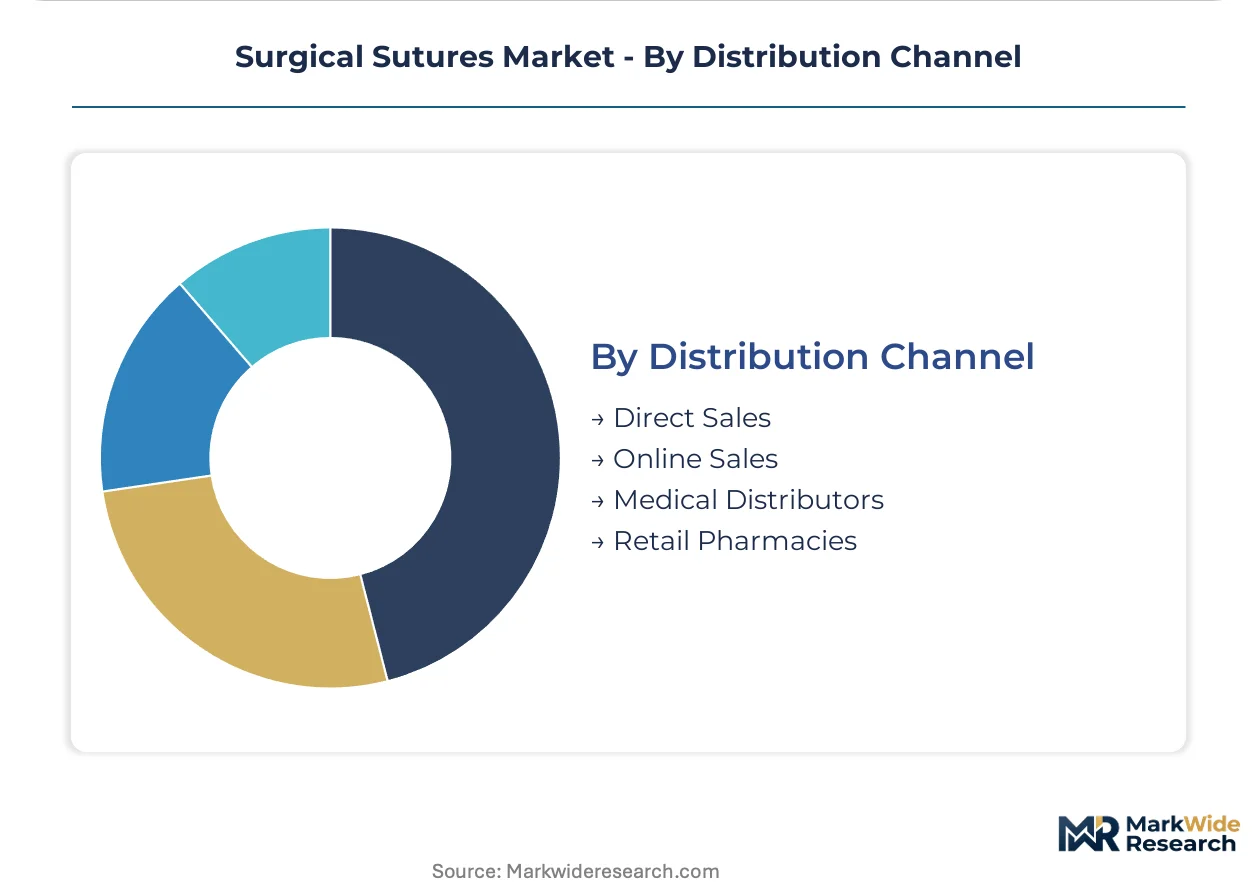
- Direct Sales:Manufacturer field forces manage formulary placement and consignment inventory at major health system accounts. National Health Service England procurement frameworks favor direct contracting for standardization.
- Medical Distributors:Regional intermediaries provide sterile storage, kitting services, and emergency stock rotation for mid-tier hospitals. Vietnamese and Indonesian hospital buildouts are attracting distributor hub investments.
- Online Sales:E-procurement platforms serve small clinics and rural facilities with limited supplier access, though cold-chain and sterility assurance limits category penetration.
- Retail Pharmacies:Consumer-facing outlets handle minor wound closure products and emergency suture removal kits, negligible in institutional volume.
Direct Sales captures the largest contract value; Medical Distributors are gaining share fastest in emerging market infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss manufacturing clusters where alloy metallurgy expertise commands double-digit premiums over Asian commodity producers. Indian government procurement frameworks under the PLI scheme compress margins for imported sutures while accelerating domestic capacity buildouts. Brazilian hospital networks face currency-driven cost pressures that favor regional distributors over direct manufacturer relationships.
United States
Ambulatory surgery centers in Texas and Florida drive demand for barbed knotless systems that reduce operative time in high-volume laparoscopic procedures. FDA 510(k) clearance pathways shape product development timelines for manufacturers seeking market access. The Minneapolis-St. Paul corridor anchors North American distribution infrastructure for wound-closure bundle contracts.
Germany
Tertiary care centers in Bavaria and Baden-Württemberg mandate antibacterial sutures under revised nosocomial infection protocols. EMA's renewed particulate contamination limits for Class IIa devices force sub-10 micron filtration investments across European production facilities. The Stuttgart industrial cluster concentrates specialty needle alloy formulation expertise that reduces tissue drag in cardiovascular applications.
China
Coronary artery bypass grafting caseloads in Beijing and Shanghai expand demand for silk and polyester non-absorbable specialty sutures. NMPA registration requirements and GB standards compliance shape local manufacturing investments. The Yangtze River Delta hosts scaled glycolide polymerization capacity under domestic medical device incentive programs.
India
Government hospital expansion programs under the PLI scheme for medical devices concentrate demand in public sector tertiary facilities in Maharashtra and Karnataka. CDSCO regulatory frameworks align with ISO 10993 biocompatibility testing protocols for market authorization. The Chennai surgical hub attracts regional distribution investments from kitting service providers.
Brazil
Private hospital networks in São Paulo and Rio de Janeiro prioritize cost-optimized absorbable sutures for general surgery departments. ANVISA registration requirements govern import authorization timelines for multinational manufacturers. The São Paulo state industrial corridor hosts contract sterilization facilities serving South American distribution networks.
Surgical Sutures Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in polymer feedstock and needle metallurgy. The vendor base stratifies across three tiers: multinational health conglomerates with captive supply chains, mid-tier regional manufacturers with government contract access, and specialized alloy formulators serving premium cardiovascular segments. Two strategic archetypes dominate competitive positioning: integrated producers leveraging backward control over glycolide monomer supply, and asset-light kitting service providers leasing sterile packaging capacity. Capacity expansion in Vietnamese and Indonesian distribution hubs and technology licensing for bioresorbable polymer-electronics convergence represent the dominant competitive moves.
Among diversified health conglomerates, Johnson & Johnson Services, Inc. [Ethicon] and Medtronic occupy positions that exemplify integrated platform control over wound-closure bundle contracts. B. Braun SE anchors the European specialist tier through proprietary manufacturing expertise. These three entities represent distinct competitive archetypes: captive polymer supply chain integration, North American hospital contract anchoring, and specialty alloy formulation differentiation.
| Leading Market Players |
|---|
| Smith & Nephew |
| Boston Scientific Corporation |
| Johnson & Johnson Services, Inc. [Ethicon] |
| Healthium MedTech |
| CONMED Corporation |
| Medtronic |
| Advanced Medical Solutions Group Plc |
| DemeTECH Corporation |
| B. Braun SE |
| Others |
Cost & Logistics Intelligence
Polyglycolic acid monomer supply concentration among three Asian petrochemical conglomerates determines both pricing tier spreads and supply chain shape across the surgical sutures market. This single-source dependency for glycolide feedstock creates volatility exposure that compresses margins for non-integrated manufacturers while rewarding producers with captive polymer streams.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across hospital procurement consortiums. Pricing stratifies across premium, standard, and economy tiers driven by certification level—FDA 510(k) versus EU MDR Class IIa pathways—and volume scale under integrated wound-closure bundles. Cost compression in mid-tier absorbable sutures is intensifying because Korean and Chinese manufacturers have scaled domestic glycolide polymerization capacity. Ambulatory surgical centers exhibit highest price sensitivity due to procedure-specific kitting requirements, while cardiovascular specialty clinics retain lowest sensitivity given handling-dependent premiums for silk and proprietary needle alloys.
Supply Chain Analysis
Contract sterilization capacity concentrates in Germany, Switzerland, and the São Paulo state industrial corridor serving South American distribution networks. Raw material dependencies rest on glycolide monomer from Asian petrochemical feedstock, 300-series stainless and proprietary ternary alloys for needle metallurgy, and triclosan or polyhexamethylene biguanide antimicrobial agents. Single-source vulnerability for glycolide polymerization creates price volatility exposure for non-integrated suture manufacturers. Distribution runs through direct manufacturer field forces at major health system accounts, with regional intermediaries providing sterile storage and kitting services for mid-tier hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical sutures market is experiencing high-growth disruption as antibacterial suture protocols and bioresorbable polymer-electronics convergence redefine product performance benchmarks and post-operative care revenue streams.
For Market Incumbents: Harden formulary placement through backward integration into glycolide monomer supply and sterile packaging capacity investments. Defensive consolidation requires securing notified body relationships to navigate EU MDR Class IIa clinical evidence burdens, while expanding barbed knotless suture portfolios counters powered endoscopic stapler substitution in laparoscopic procedures.
For New Entrants and Emerging Players: Establish a beachhead in Vietnamese and Indonesian hospital buildouts where government infrastructure programs create first-mover advantages for kitting service providers. Asset-light leasing models for sterile packaging capacity reduce capital barriers for mid-tier manufacturers seeking contract access without facility investments, while antibacterial suture lines offer premium positioning under tightening infection-control mandates.
For Investors and Strategic Acquirers: EU MDR Class IIa certification timelines reshapes the acquisition landscape toward targets with notified body relationships and sub-10 micron filtration compliance already achieved. Long-term viability centers on platform integrators with backward polymer control and regional distribution hubs in Southeast Asia. Watch sterilization validation protocol transitions at FDA as the inflection indicator for manufacturing line requalification investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Antibacterial Coating Development | Triclosan and PHMB-impregnated filaments address tightening nosocomial infection protocols in tertiary care centers. |
| Barbed Knotless System Launch | German and South Korean academic medical centers accelerate operative efficiency in myomectomy and sleeve gastrectomy applications. |
| Southeast Asia Distribution Hub | Vietnamese and Indonesian hospital buildouts create regional logistics infrastructure for kitting service providers. |
| Bioresorbable Polymer-Electronics Convergence | Conductive polymer sutures with real-time wound monitoring sensors open reconstructive surgery revenue streams. |
| EU MDR Class IIa Compliance Investment | Sub-10 micron filtration systems and enhanced cleanroom protocols address EMA particulate contamination limits. |
Research Approach
Operator-level perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and sterilization validation specialists anchored the qualitative base for this study. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EMA MDR submissions, hospital procurement databases, and GPO contract repositories. Bottom-up procedure volume modeling and top-down polymer feedstock demand analysis provided triangulation across the analysis window.
Scenario-bracketing framed volume and value outputs across product type, material chemistry, end-user facility tier, and regional regulatory cluster dimensions. CAGRs were derived from procedure migration patterns, domestic manufacturing incentive uptake, and substitution dynamics between sutures and powered stapling systems. Forecast inputs incorporated India PLI scheme capacity buildouts, EU notified body capacity constraints, and FDA sterilization guidance evolution.
Macroeconomic conditions sit as an overlay; deviation in currency volatility for Brazilian hospital networks or Asian petrochemical feedstock pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline normalization and infection-control protocol adoption curves. Quarterly review of notified body capacity indicators, glycolide monomer spot pricing, and hospital procurement consortium consolidation patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Global Bone Wax Market
Surgical Instruments
Electrosurgery Market
Surgical Instruments
Laparoscopic Needle Holder Robotic Devices Market
Surgical Instruments
Global Myomectomy Market
Surgical Instruments
Ischemic Stroke Surgery Market
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Equine Surgical Equipment Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Ultrasonic Tissue Ablation System Market
Surgical Instruments
Surgical Clips Market
Surgical Instruments
Surgical Sphincteroplasty Market
Surgical Instruments
Operating Room Smoke Aspirators Market
Surgical Instruments
Suture Needles Market
Surgical Instruments
Disposable Ophthalmic Surgical Products Market
Surgical Instruments
Absorbable Sutures Market