
 US Colorectal Cancer Screening Market | 2026-2036
US Colorectal Cancer Screening Market Size, Share, and Industry Trends Forecast 2026-2036
US Colorectal Cancer Screening Market Insights
The US colorectal cancer screening landscape is consolidating around a sharp split between premium molecular diagnostics and commodity fecal immunochemical testing. Exact Sciences Corporation leverages its integrated lab services model to sustain premium positioning in stool DNA screening. Laboratory Corporation of America Holdings anchors high-throughput processing capacity across its national network. FUJIFILM Holdings Corporation competes on endoscopic imaging systems that dominate hospital-based colonoscopy workflows.
Colorectal cancer screening encompasses diagnostic protocols and technologies designed to detect malignancies or precancerous lesions in the colon and rectum, primarily through endoscopic visualization, imaging-based structural examination, or biomarker analysis of stool and blood samples with sensitivity thresholds varying by modality. Its primary commercial purpose is enabling early-stage intervention that reduces mortality and treatment costs within US healthcare systems. Stool DNA testing captures expanding margin pools as laboratories build automated processing infrastructure. Colonoscopy retains structural dominance in hospital and ambulatory surgical center settings due to therapeutic capability. Fecal immunochemical testing occupies high-volume, low-margin positioning in physician office and laboratory channels.
FDA premarket approval pathways and CMS national coverage determinations shape product commercialization timelines and reimbursement access for novel screening modalities. The Affordable Care Act's preventive services mandates and USPSTF grade A recommendations enforce zero-cost sharing for qualifying tests, directly expanding eligible patient populations. State Medicaid program variations and Veterans Health Administration procurement protocols create additional access layers. Stakeholders must monitor evolving FDA guidance on blood-based multi-cancer early detection assays and corresponding CMS parallel review processes that could restructure competitive dynamics.
Market Dynamics
The US colorectal cancer screening market is restructuring around CMS reimbursement shifts that favor non-invasive modalities, compressing traditional colonoscopy volumes while expanding laboratory-based testing infrastructure across integrated health networks.
Growth Catalysts
- USPSTF Grade A Recommendations:The task force's preventive services mandates enforce zero-cost sharing for qualifying tests, directly expanding eligible patient populations into commercial and Medicare Advantage plans.
- FDA Premarket Approval Expansion:Blood-based multi-cancer early detection assays are advancing through parallel review pathways, accelerating novel modality commercialization timelines.
- Integrated Laboratory Networks:Large diagnostic platforms in Texas, California, and Florida are consolidating stool DNA processing capacity, capturing economies of scale in high-throughput automation.
Market Restraints
- Colonoscopy Infrastructure Concentration:Therapeutic-capable endoscopy suites cluster in metropolitan hospital systems, limiting rural access and creating geographic screening deserts.
- State Medicaid Variation:Inconsistent coverage determinations across state programs fragment patient access to non-invasive alternatives, particularly in non-expansion states.
- Pathologist Workforce Constraints:Specialized gastrointestinal pathology expertise concentrates in academic medical centers, creating diagnostic bottlenecks for emerging biomarker platforms.
Strategic Opportunities
- Veterans Health Administration Procurement:Centralized federal purchasing protocols for screening assays create volume consolidation opportunities for qualified laboratory vendors.
- Direct-to-Consumer Channel Development:Employer wellness programs and retail health clinics are emerging as alternative access points for fecal immunochemical testing distribution.
- Artificial Intelligence-Enhanced Endoscopy:Computer-aided polyp detection systems are converging with standard colonoscopy workflows, creating premium positioning for imaging-integrated screening protocols.
Industry Challenges
- Laboratory Information System Integration:Legacy electronic health record architectures in community hospitals require costly middleware development to support multi-biomarker result reporting.
- Quality Assurance Standardization:Pre-analytical specimen handling protocols vary across stool DNA collection kit manufacturers, complicating inter-laboratory proficiency testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Colorectal Cancer Screening Market |
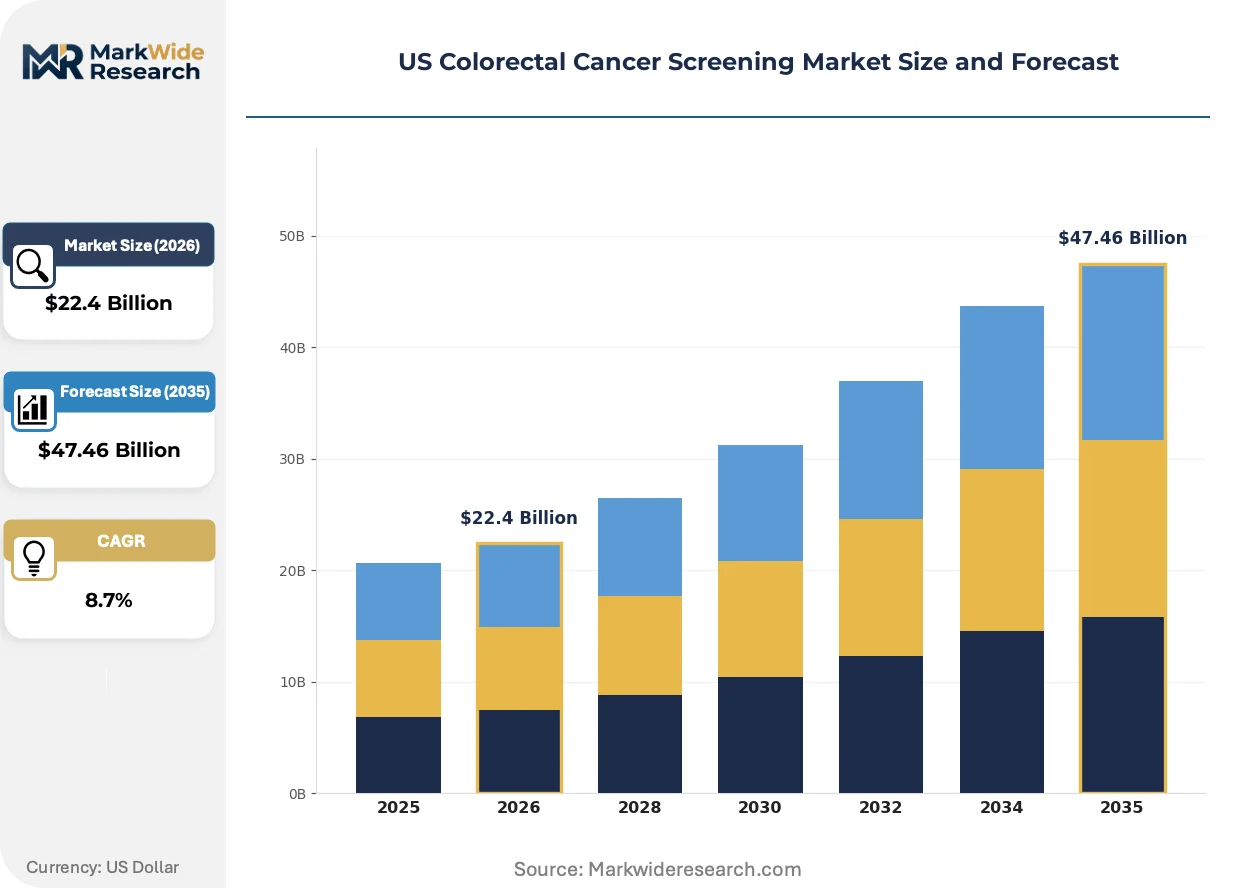
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $47.46 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Screening Method: Colonoscopy, Fecal Immunochemical Test, CT Colonography, Flexible Sigmoidoscopy, Stool DNA Test Screening Frequency: Annual, Biennial, Triennial, Every Five Years, Every Ten Years End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Physician Offices Insurance Coverage Type: Private Insurance, Medicare, Medicaid, Uninsured, Veterans Health Administration |
| Companies Covered | Exact Sciences Corporation, Olympus Corporation, Laboratory Corporation of America Holdings, FUJIFILM Holdings Corporation, Guardant Health, Abbott Laboratories, Quest Diagnostics, Medtronic, Hoya Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Colorectal Cancer Screening Market Trends and Innovations
Automation and algorithmic analysis are displacing manual review processes across screening modalities, while regulatory parallel review mechanisms compress commercialization timelines for blood-based assays.
Next-generation sequencing platforms are automating stool DNA extraction and mutation detection workflows. Regional reference laboratories in Florida and Texas are deploying these systems at scale, reducing per-sample processing costs and enabling same-day result turnaround for positive screens requiring colonoscopy referral.
FDA's breakthrough device designation pathway and CMS parallel review programs are synchronizing coverage and coding determinations for novel screening technologies. Blood-based multi-cancer detection assays are navigating this framework, with commercial laboratories accelerating clinical evidence generation to support national coverage determination submissions.
Self-collection models are displacing clinic-based specimen acquisition for fecal testing. Large integrated delivery networks in California are deploying home-based screening programs through patient portals, with automated result delivery and care navigation for positive findings replacing traditional physician office workflows.
US Colorectal Cancer Screening Market Segmentation
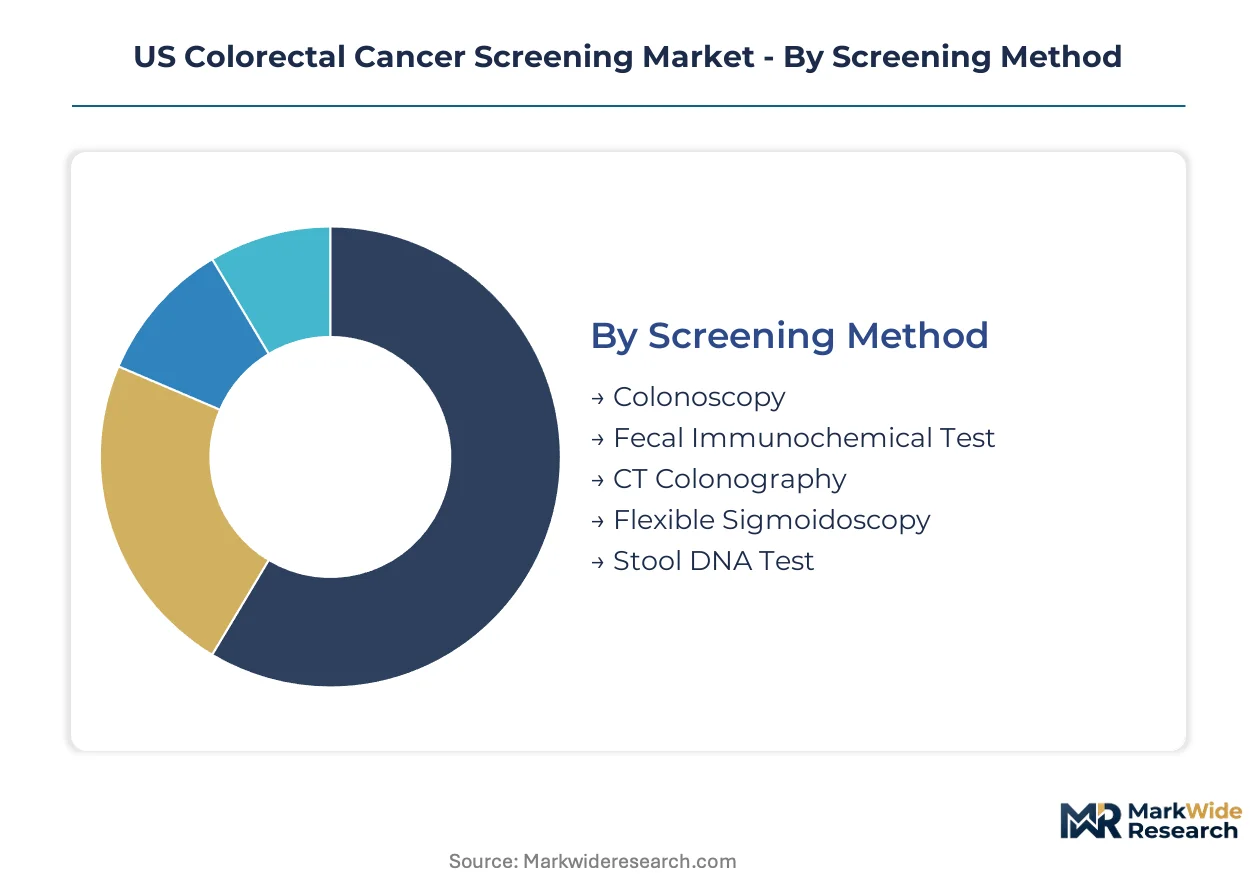
Screening modality selection in the US colorectal cancer market follows reimbursement logic and clinical workflow constraints rather than pure clinical preference. Each segment category maps to distinct supply chain configurations and margin structures.
Screening Method:
Supply concentration in high-throughput laboratory infrastructure favors non-invasive modalities with automated processing capabilities.
- Colonoscopy:Endoscopic visualization with therapeutic polypectomy capability remains the diagnostic gold standard. Hospital systems in Texas and California maintain the densest concentration of endoscopy suites. CMS reimbursement rates and facility fees sustain premium economics despite capital intensity.
- Fecal Immunochemical Test:Single-marker stool hemoglobin detection enables high-volume, low-cost population screening. Diagnostic laboratories in Florida deploy automated analyzers processing thousands of samples daily. USPSTF Grade A recommendation enforces zero-cost sharing in commercial plans.
- CT Colonography:Computed tomographic imaging with 3D reconstruction requires radiologist interpretation and follow-up protocols for extracolonic findings.
- Flexible Sigmoidoscopy:Limited distal colon examination with lower sedation requirements occupies a narrowing clinical niche.
- Stool DNA Test:Multi-target mutation and methylation analysis integrates with laboratory information systems for automated result reporting.
Colonoscopy absorbs the bulk of installed capacity; stool DNA testing is expanding most quickly.
Screening Frequency:
Cost tier stratification separates high-frequency low-unit-cost modalities from premium episodic screening.
- Annual:Fecal immunochemical testing protocols align with employer wellness program calendars and health plan quality metrics. Large integrated delivery networks in California automate annual outreach through patient portals.
- Biennial:Stool DNA testing intervals balance sensitivity gains against per-test reimbursement thresholds. Laboratory Corporation of America and Exact Sciences optimize kit distribution for 24-month rescreening cycles.
- Triennial:Intermediate intervals accommodate mixed-modality screening pathways with colonoscopy backup for positive screens.
- Every Five Years:CT colonography and flexible sigmoidoscopy schedules reflect radiology capacity constraints and procedural risk profiles.
- Every Ten Years:Colonoscopy intervals for average-risk populations maximize cost-effectiveness in CMS actuarial models.
Annual screening captures the highest test volumes; biennial intervals are climbing the fastest as stool DNA adoption accelerates.
End User:
Customer type determines specimen handling protocols and result delivery mechanisms across the care continuum.
- Hospitals:Integrated health systems combine screening colonoscopy with therapeutic services in ambulatory surgery departments. Academic medical centers concentrate gastrointestinal pathology expertise for complex cases.
- Ambulatory Surgical Centers:Freestanding endoscopy facilities compete on throughput and scheduling convenience for commercially insured populations.
- Diagnostic Laboratories:National reference networks process stool-based assays with automated extraction and next-generation sequencing workflows. Regional hubs in Texas and Florida achieve economies of scale in kit distribution.
- Physician Offices:Primary care clinics function as collection points for fecal testing with point-of-care result interpretation.
Diagnostic laboratories absorb the bulk of non-invasive test volume; ambulatory surgical centers are gaining share fastest through site-of-service pricing differentials.
Insurance Coverage Type:
Procurement patterns vary sharply across payer categories with distinct prior authorization requirements and fee schedules.
- Private Insurance:Commercial plans implement USPSTF-mandated zero-cost sharing for qualifying tests. Large employers in California and Texas negotiate direct contracts with laboratory networks for preferred pricing.
- Medicare:CMS national coverage determinations and preventive services mandates define reimbursement for beneficiaries over 50. Annual wellness visits trigger automated screening orders in Medicare Advantage plans.
- Medicaid:State program variations create coverage fragmentation, with non-expansion states limiting access to non-invasive alternatives.
- Uninsured:Safety-net hospital systems and community health centers provide colonoscopy access through charity care pools and sliding-scale programs.
- Veterans Health Administration:Centralized federal procurement protocols create volume consolidation opportunities for qualified laboratory vendors serving VA medical centers.
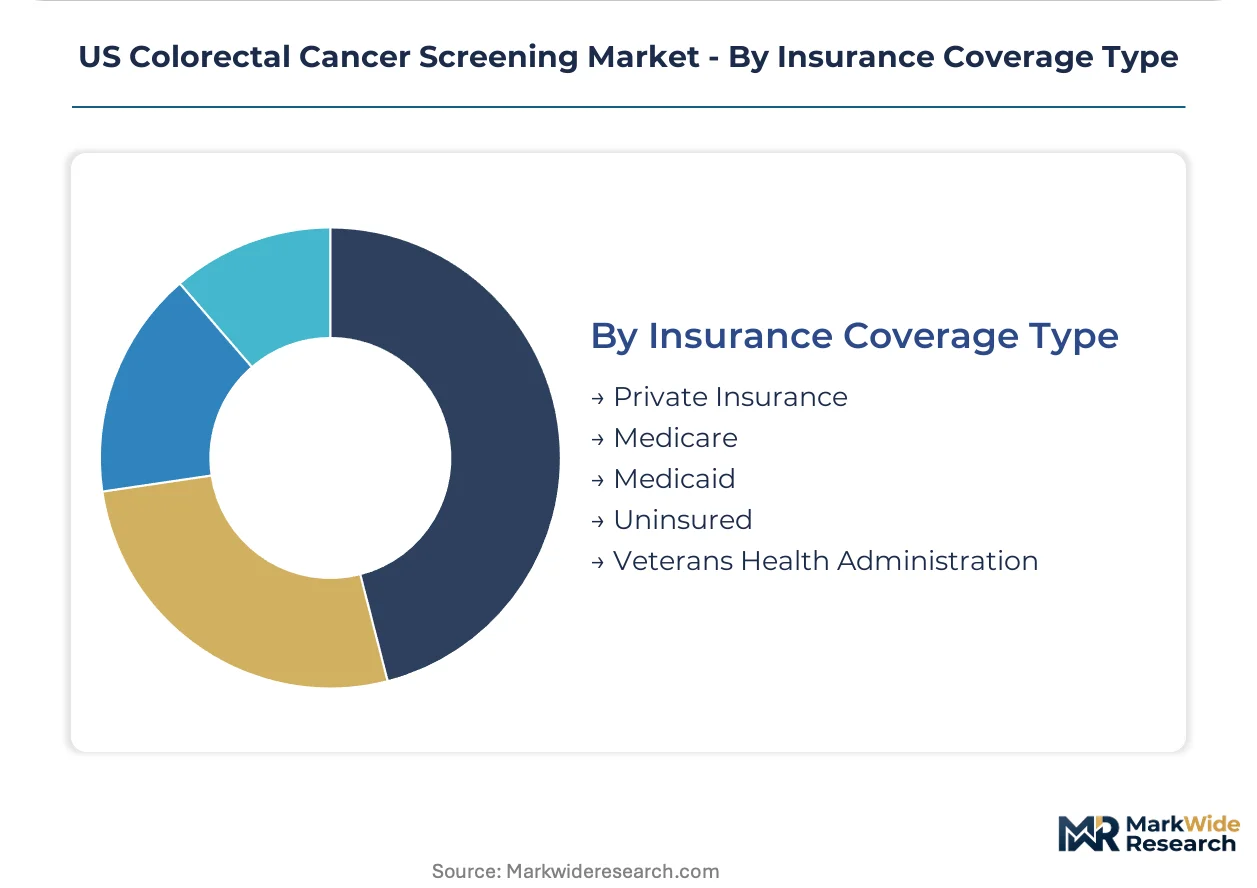
Private insurance and Medicare absorb the bulk of revenue; Veterans Health Administration procurement is expanding most quickly through centralized assay standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors the densest concentration of commercial laboratory processing capacity for stool DNA testing in the United States.
Texas
Integrated diagnostic networks in Houston and Dallas process high volumes of fecal immunochemical tests through automated analyzers. State Medicaid expansion under the Affordable Care Act extended coverage to non-invasive screening alternatives. San Antonio's Veterans Health Administration medical center serves as a federal procurement hub for standardized assay distribution across the Southwest.
California
Large integrated delivery networks in Los Angeles and the Bay Area deploy home-based screening programs through patient portals with automated care navigation. CMS national coverage determinations for stool DNA testing accelerated laboratory infrastructure investment in San Diego. Sacramento's health plan administrators negotiate direct contracts with reference laboratories for preferred pricing in commercial markets.
Florida
Regional reference laboratories in Miami and Tampa achieve economies of scale in kit distribution for biennial rescreening cycles. State demographic aging patterns concentrate Medicare Advantage enrollment in screening-eligible populations. Orlando's ambulatory surgical center networks compete on throughput pricing for commercially insured colonoscopy volumes.
Illinois
Academic medical centers in Chicago concentrate gastrointestinal pathology expertise for complex biomarker platform interpretation. Private insurance mandates under USPSTF guidelines enforce zero-cost sharing for qualifying tests across Cook County. Rockford's diagnostic laboratory networks process specimens from rural catchment areas lacking endoscopy suite access.
New York
Metropolitan hospital systems in Manhattan and Long Island maintain therapeutic-capable endoscopy suites with premium facility fee structures. State Medicaid program variations create coverage fragmentation for non-invasive alternatives in upstate regions. Buffalo's safety-net hospital systems provide colonoscopy access through charity care pools for uninsured populations.
US Colorectal Cancer Screening Market Competitive Landscape
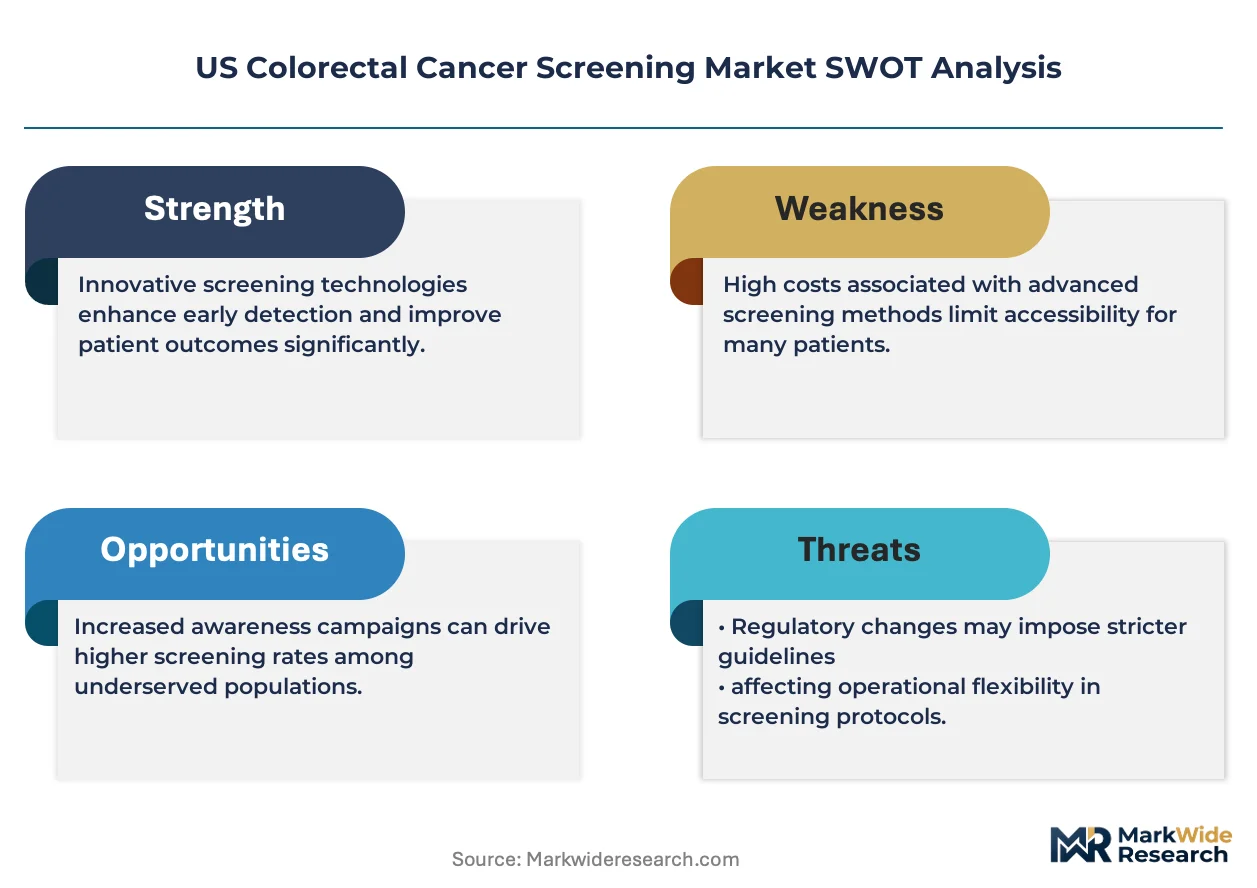
Premium-margin players sit above commodity-margin players across reimbursement tier and processing automation levels. The US colorectal cancer screening market structures around three distinct competitive tiers: molecular diagnostic specialists commanding premium pricing for multi-biomarker assays, high-throughput reference laboratories capturing scale economies in fecal testing, and endoscopic imaging manufacturers dominating hospital-based procedural workflows. Consolidation pressures favor integrated laboratory networks with automated extraction capabilities. Competitive moves center on strategic partnerships with integrated delivery networks and capacity expansion in high-volume processing hubs.
Within the molecular diagnostic tier, Exact Sciences Corporation and Guardant Health exemplify premium-positioned players navigating FDA premarket approval pathways for novel screening modalities. Laboratory Corporation of America Holdings anchors the high-throughput reference laboratory segment with national specimen processing infrastructure. FUJIFILM Holdings Corporation occupies a position within the endoscopic imaging manufacturer archetype, competing on visualization systems that integrate with hospital-based colonoscopy workflows.
| Leading Market Players |
|---|
| Exact Sciences Corporation |
| Olympus Corporation |
| Laboratory Corporation of America Holdings |
| FUJIFILM Holdings Corporation |
| Guardant Health |
| Abbott Laboratories |
| Quest Diagnostics |
| Medtronic |
| Hoya Corporation |
| Others |
Pricing and Supply Chain Analysis
Backward integration into automated stool DNA processing anchors Exact Sciences Corporation's supply position and defends premium pricing against high-throughput reference laboratories. This captive production model concentrates margin capture in Texas and California processing hubs while insulating against third-party kit cost volatility.
Pricing Analysis
Outcome-linked reimbursement anchors stool DNA testing at premium tiers above commodity fecal immunochemical testing. Three-tier pricing structure across molecular diagnostic, high-throughput laboratory, and endoscopic imaging levels separates Exact Sciences from Laboratory Corporation of America and FUJIFILM Holdings. Price differentiation rests on USPSTF Grade A qualification and FDA premarket approval tier. Cost compression in fecal immunochemical testing intensifies as automated analyzers displace manual review. Employer wellness programs demonstrate highest price sensitivity; Medicare Advantage plans show lowest sensitivity due to preventive services mandates.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Los Angeles orchestrate hub-and-spoke kit fulfillment for stool DNA collection. Geographic supply concentration clusters in the United States for endoscopic equipment, China for electronic imaging components, and Germany for precision optical systems. Raw material dependencies include specialized polymers for collection vessels, next-generation sequencing reagents, and high-resolution sensor arrays. Single-source vulnerability concentrates in semiconductor-dependent imaging processors. Distribution runs through integrated delivery network procurement portals and national reference laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US colorectal cancer screening market sits in a technology-transition phase as blood-based multi-cancer early detection assays displace stool-based protocols. FDA breakthrough device designations and CMS parallel review mechanisms accelerate this substitution timeline.
For Market Incumbents: Anticipate reimbursement compression in fecal immunochemical testing as blood-based assays secure USPSTF Grade A recommendations. Defend position by deepening automated processing capacity in Texas and California hubs. Prioritize FDA premarket approval investment for next-generation biomarker panels before competitor blood tests achieve national coverage determination. For New Entrants and Emerging Players: Begin with Veterans Health Administration procurement channels where centralized federal purchasing creates volume consolidation opportunities. Rural screening deserts in non-expansion Medicaid states offer the most penetrable geography. Pursue direct-to-consumer distribution through employer wellness programs bypassing traditional physician office gatekeepers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated laboratory networks seeking automated extraction capabilities. Long-term viability favors molecular diagnostic specialists with FDA-approved platforms over commodity testing processors. Watch CMS parallel review decisions for blood-based multi-cancer detection assays as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Blood-based assay developers navigate breakthrough device designation to synchronize coverage with CMS national coverage determinations. |
| Integrated Laboratory Network Partnership | Exact Sciences leverages hospital system alliances in Texas and California to secure preferred provider status for stool DNA processing. |
| Automated Processing Scale-Up | Laboratory Corporation of America deploys next-generation sequencing infrastructure to reduce per-sample costs below competitor thresholds. |
| Direct-to-Consumer Channel Development | Retail health clinics and employer wellness programs bypass traditional physician office workflows for fecal immunochemical testing distribution. |
| Reimbursement Strategy | Stakeholders align clinical evidence generation with USPSTF review cycles to secure zero-cost sharing mandates in commercial plans. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with laboratory operations directors, hospital procurement managers, GPO contracts specialists, and CMS policy analysts combined with FDA 510(k) submission databases, CMS national coverage determination records, and hospital procurement databases. Bottom-up test volume modeling and top-down reimbursement flow analysis provided triangulation across data streams.
Data-stream reconciliation across screening modality volumes, reimbursement rate schedules, and laboratory capacity utilization shaped the analytical framework. Segmentation dimensions included screening method, testing frequency, end-user facility type, and insurance coverage category across the projection horizon. CAGRs derived from fitted adoption curves for novel biomarker platforms and colonoscopy volume displacement scenarios. Clinical evidence publication timelines and USPSTF review cycle schedules served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; stool DNA testing and colonoscopy volumes carry tighter precision than emerging blood-based assay projections. Forecasts reflect documented assumptions regarding FDA approval timelines and CMS coverage determinations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Glioma Diagnosis and Treatment Market
Oncology Diagnostics
Oncology Imaging Software Market
Oncology Diagnostics
Ovarian Cancer Diagnostics Market
Oncology Diagnostics
US Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Cancer Biopsy Market
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia-Pacific Liver Cancer Diagnostics Market
Oncology Diagnostics
Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Europe Non-Small Cell Lung Cancer Diagnostics Market
Oncology Diagnostics
Multi Cancer Early Detection Market
Oncology Diagnostics
Bladder Cancer Diagnostics Market
Oncology Diagnostics
Non-Hodgkin Lymphoma Diagnostics Market
Oncology Diagnostics
US Cancer Biopsy Market
Oncology Diagnostics
Europe Kidney Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Brain Tumor Diagnostics Market