
 Global Fecal Occult Blood Tests Market | 2026-2036
Global Fecal Occult Blood Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fecal Occult Blood Tests Market Foresight
The gap between hospital-based testing and home care users is collapsing as decentralized screening gains reimbursement traction. Abbott Laboratories leverages its point-of-care diagnostics infrastructure to capture ambulatory volume, while Exact Sciences Corporation anchors its position through DNA-based test integration with established lab networks. Siemens Healthcare GmbH competes on automated analyzer throughput, sustaining installed-base loyalty across European diagnostic laboratories.
Fecal occult blood tests detect hemoglobin or its derivatives in stool samples through immunochemical, guaiac-based, enzymatic, or DNA-based methodologies, with detection thresholds typically ranging from 50 to 100 nanograms of hemoglobin per milliliter of buffer. These tests serve as non-invasive frontline tools for colorectal cancer screening and gastrointestinal bleeding assessment in both clinical and home settings. Immunochemical formats now lead test type segmentation due to superior specificity and no dietary restrictions, while DNA-based applications command premium positioning despite higher per-test costs. Home care users represent the fastest-growing end user channel as direct-to-consumer distribution and self-collection protocols expand, though diagnostic laboratories retain the deepest margin pools through high-volume contract structures.
FDA clearance pathways and EMA in vitro diagnostic regulations shape product standards, with both agencies tightening analytical performance benchmarks for immunochemical sensitivity. WHO screening guidelines and national reimbursement frameworks in Japan, Germany, and the United States directly determine accessible patient volumes and test frequency protocols. Stakeholders must monitor evolving colorectal screening age thresholds and decentralized testing reimbursement decisions across multiple health systems.
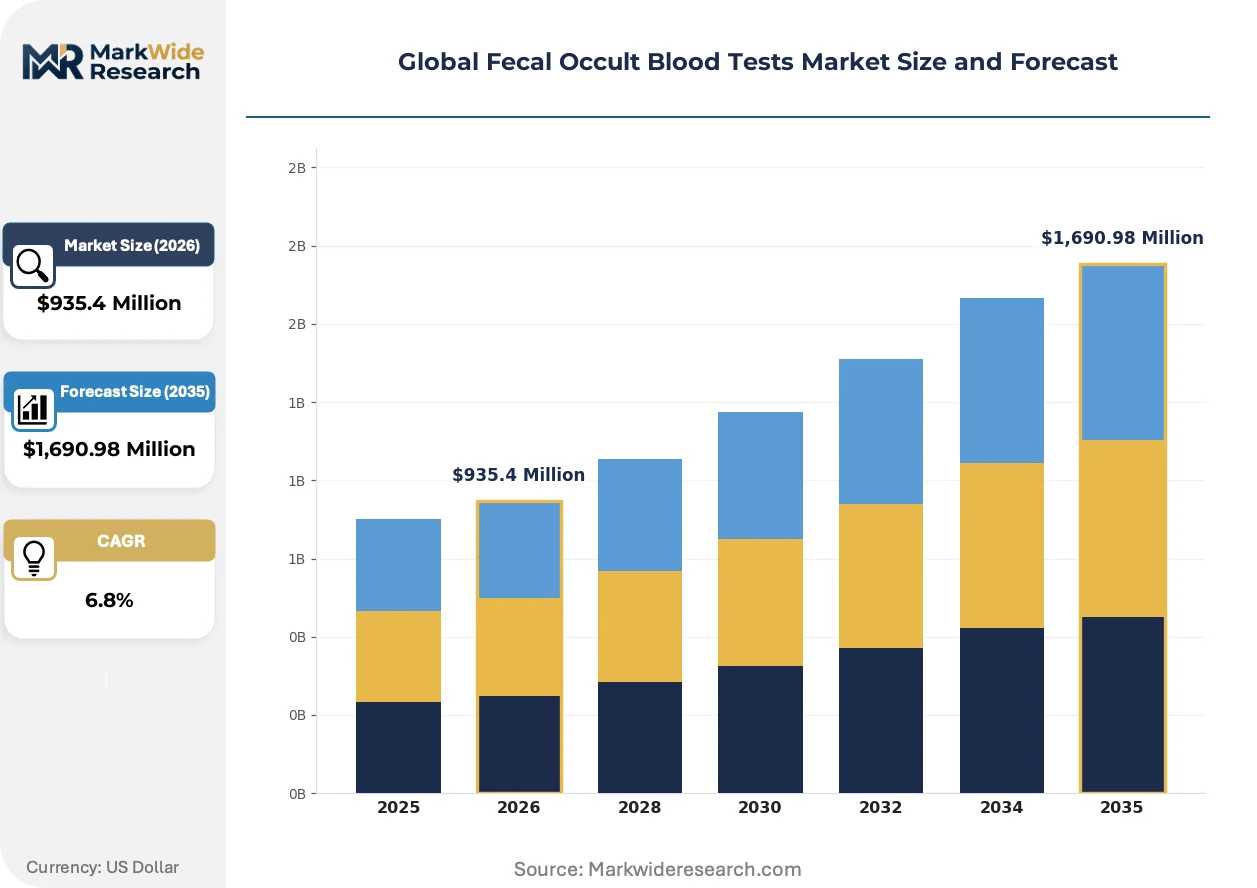
Market Dynamics
Decentralized screening protocols are collapsing the historical divide between hospital laboratories and home-based collection, forcing manufacturers to reconfigure distribution infrastructure and reimbursement documentation simultaneously.
Growth Catalysts
- FDA Quality Benchmarks:Tightened analytical performance standards for immunochemical sensitivity are accelerating replacement cycles in US diagnostic networks.
- Japan's National Screening Program:Government-mandated colorectal protocols for citizens over 50 sustain institutional volume commitments.
- Immunochemical Formats:Superior specificity and elimination of dietary restrictions are pulling test selection away from guaiac-based alternatives.
Market Restraints
- DNA-Based Cost Premium:Per-test pricing multiples above immunochemical formats limit access in price-sensitive reimbursement environments.
- European Supply Concentration:Automated analyzer manufacturing clusters in Germany create vulnerability to single-source component delays.
- Guaiac Dietary Protocols:Patient non-compliance with pre-test restrictions degrades effective sensitivity in legacy screening programs.
Strategic Opportunities
- Direct-to-Consumer Channels:Self-collection protocols and telehealth integration open patient acquisition outside traditional lab networks.
- EMA In Vitro Diagnostic Regulation:Harmonized performance documentation requirements reduce multi-market registration friction for compliant manufacturers.
- Multi-Cancer Early Detection:Blood-based liquid biopsy convergence with stool DNA screening creates bundled preventive care propositions.
Industry Challenges
- Reimbursement Documentation Burden:Divergent prior authorization requirements across US state Medicaid programs consume administrative bandwidth.
- Laboratory Information System Integration:Home care result portals require API development against legacy hospital EMR architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fecal Occult Blood Tests Market |
| Market Size in 2026 | $935.4 Million |
| Market Size in 2035 | $1,690.98 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Guaiac-based, Immunochemical, DNA-based, Combination, Enzymatic End User: Diagnostic Laboratories, Research Institutes, Ambulatory Care Centers, Home Care Users Application: Colorectal Cancer Screening, Gastrointestinal Disorder Detection, Clinical Trials, Preventive Healthcare Form: Liquid, Test Strips, Cassette, Automated Analyzers |
| Companies Covered | Abbott Laboratories, Quidel Corporation, Siemens Healthcare GmbH, Exact Sciences Corporation, Roche Diagnostics, Quest Diagnostics Incorporated, HUMASIS.COM, CTK Biotech, Inc., Wondfo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fecal Occult Blood Tests Market Shifts & Advancements
Digital pathology integration and artificial intelligence-assisted result interpretation are redefining workflow economics across screening networks, compressing turnaround times while elevating analytical throughput requirements.
Quantitative immunochemical analyzers is displacing qualitative lateral flow devices in high-volume diagnostic laboratories. European hospital networks are consolidating procurement around automated platforms capable of processing 200-plus samples hourly. This displacement is compressing margins for manufacturers lacking installed-base service infrastructure.
EMA's In Vitro Diagnostic Regulation (IVDR) reclassification of fecal hemoglobin devices under Class C risk categories imposes clinical evidence requirements previously reserved for companion diagnostics. Manufacturers with legacy CE-IVD certificates face renewal timelines demanding prospective performance studies. German and French notified bodies are prioritizing IVDR technical documentation reviews, creating regulatory queue advantages for early filers.
Patients are bypassing physician referral channels through employer-sponsored wellness programs and pharmacy retail clinics. United States health systems are responding with white-label home collection partnerships that preserve laboratory revenue share. This channel migration is most visible in metropolitan markets with dense specialist networks and high commercial insurance penetration.
Global Fecal Occult Blood Tests Market Segmentation
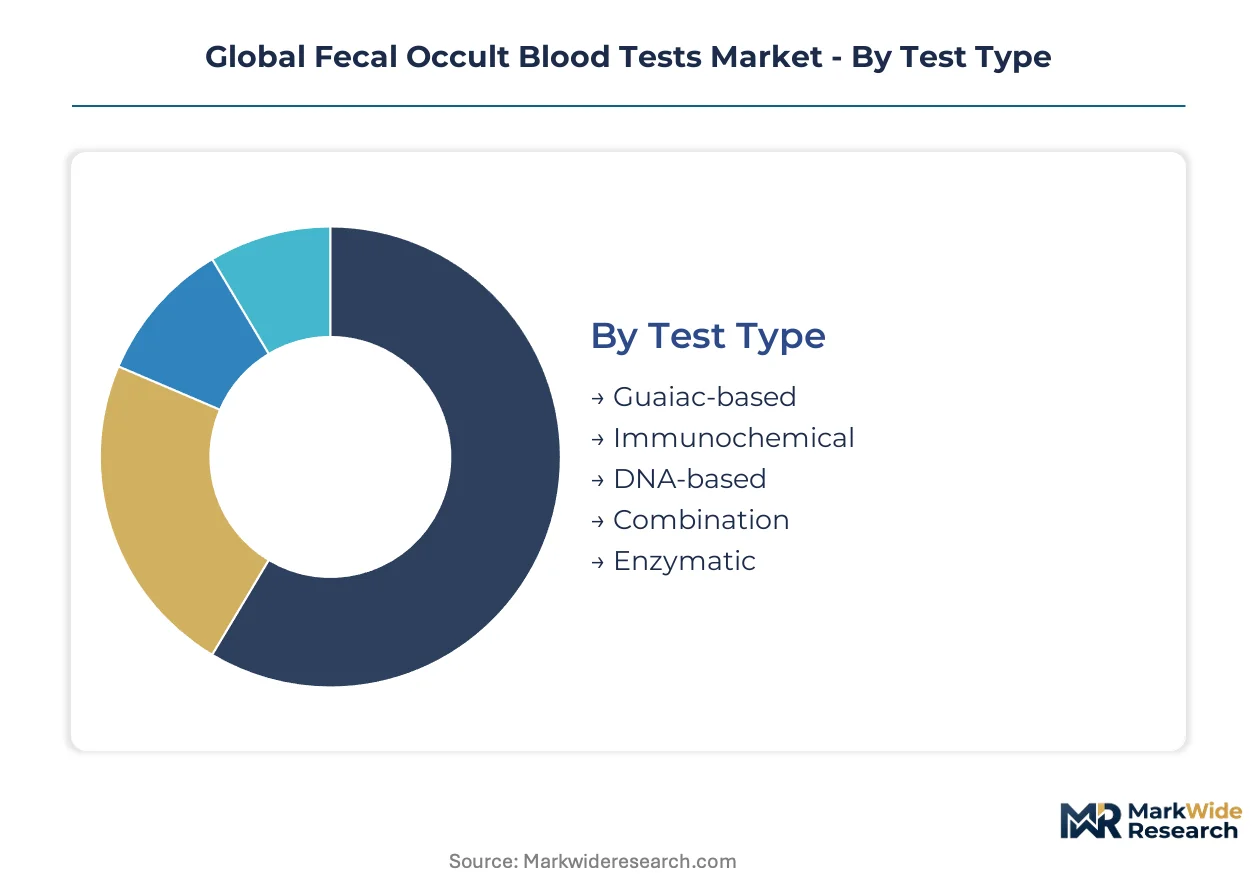
Test format selection directly determines reimbursement eligibility and patient compliance rates across screening programs. Manufacturers must align product portfolios with specific regulatory pathways and end-user workflow requirements to capture volume in this fragmented diagnostic landscape.
Test Type:
FDA and EMA performance benchmarks create divergent commercial trajectories across methodological platforms, with sensitivity thresholds and clinical evidence requirements shaping manufacturer investment priorities.
- Immunochemical:These assays detect human hemoglobin through antibody-antigen binding with detection thresholds of 50-100 nanograms per milliliter, eliminating dietary restriction protocols that plague legacy alternatives. Demand concentrates in United States diagnostic laboratories where Medicare reimbursement favors quantitative formats with documented analytical precision.
- DNA-based:Multi-target stool DNA assays combine hemoglobin detection with KRAS mutations and aberrant methylation markers, commanding premium positioning through superior sensitivity for advanced adenomas. Japan's national screening program and US commercial payers sustain volume despite per-test cost multiples above immunochemical alternatives.
- Guaiac-based:Peroxidase-catalyzed color change detection remains entrenched in resource-limited settings with established procurement contracts.
- Combination:Integrated immunochemical-DNA panels target high-risk patient stratification in tertiary care networks.
- Enzymatic:Catalytic hemoglobin degradation assays serve niche applications in veterinary and research settings.
Established volume favors immunochemical formats; emerging adoption favors DNA-based platforms.
End User:
Channel economics diverge sharply between centralized laboratory networks and decentralized collection models, with margin structures and patient acquisition costs driving manufacturer resource allocation.
- Home Care Users:Self-collection protocols with mail-back logistics and telehealth result delivery are climbing the fastest as direct-to-consumer distribution bypasses traditional referral channels. United States metropolitan markets with dense specialist networks and high commercial insurance penetration show concentrated uptake.
- Diagnostic Laboratories:High-throughput automated platforms processing 200-plus samples hourly sustain the deepest margin pools through long-term service contracts and installed-base loyalty.
- Ambulatory Care Centers:Point-of-care immunochemical devices serve urgent care and retail clinic workflows with rapid turnaround requirements.
- Research Institutes:Specialized assays for biomarker validation studies and clinical trial endpoints occupy a narrow procurement niche.
Laboratory consolidation strengthens established channels; direct-to-consumer expansion opens patient acquisition outside traditional networks.
Application:
Screening indication breadth determines addressable patient populations and reimbursement code availability across health systems.
- Colorectal Cancer Screening:Population-scale preventive protocols for asymptomatic adults over 50 anchor institutional procurement volumes in Germany, Japan, and the United States.
- Gastrointestinal Disorder Detection:Occult bleeding assessment for inflammatory bowel disease and peptic ulcer evaluation drives hospital-based testing demand.
- Clinical Trials:Standardized fecal hemoglobin monitoring supports gastrointestinal safety endpoints in pharmaceutical development programs.
- Preventive Healthcare:Employer-sponsored wellness initiatives and pharmacy retail screening expand asymptomatic testing beyond traditional medical channels.
Oncology screening dominates volume; preventive healthcare applications show steepest expansion trajectory.
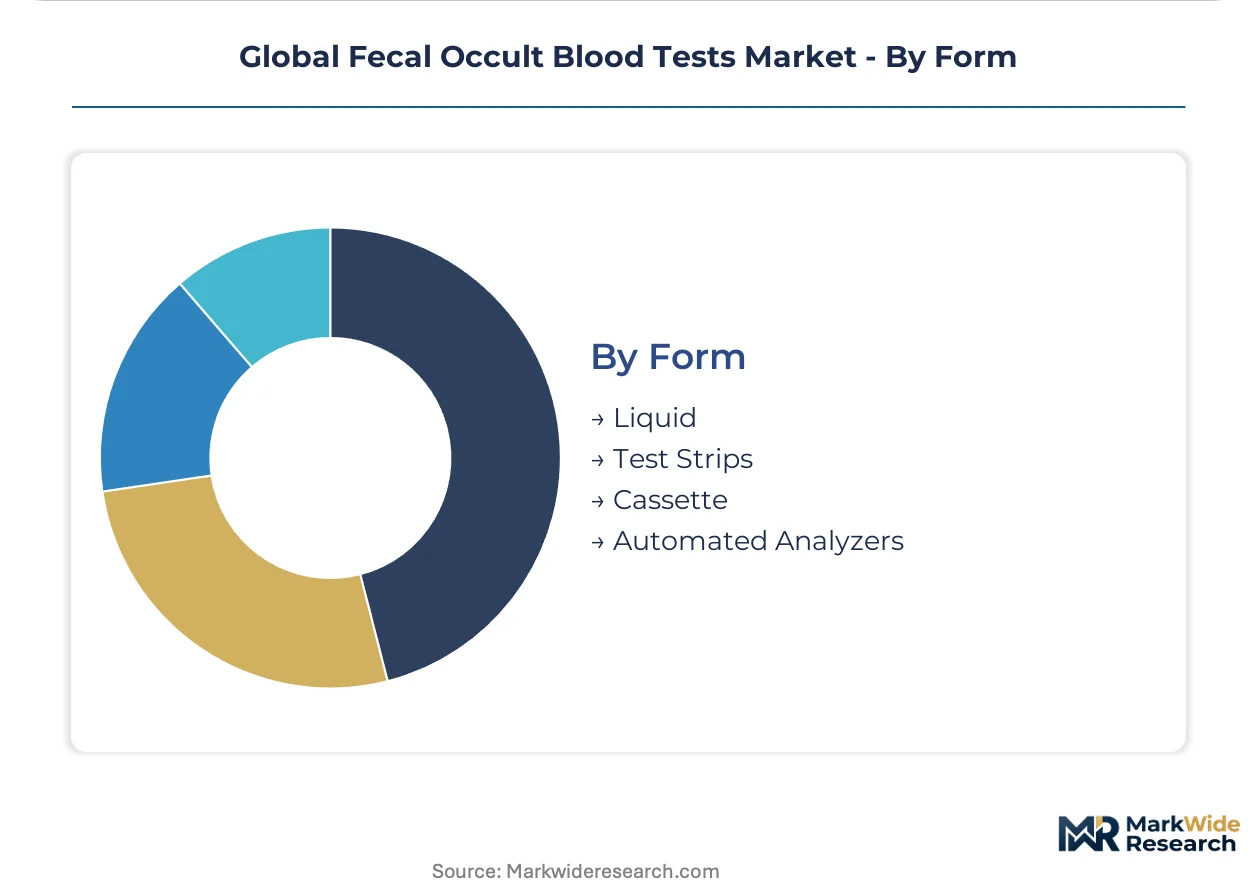
Form:
Physical test configuration dictates workflow integration requirements and capital equipment dependencies across end-user settings.
- Automated Analyzers:Quantitative immunochemical platforms with barcode tracking and LIS integration command European hospital network procurement consolidation.
- Cassette:Self-contained lateral flow devices with built-in controls serve decentralized collection and resource-limited settings.
- Test Strips:Dipstick formats for manual visual interpretation retain cost-sensitive market positions.
- Liquid:Reagent solutions for open-system analyzer compatibility support laboratory flexibility and multi-analyte workflow consolidation.
Capital-intensive automation dominates high-volume settings; cassette simplicity enables decentralized expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic analyzer manufacturing clusters in Germany and automated platform development in Japan concentrate supply-side capabilities. United States demand pulls volume through Medicare reimbursement expansion. Chinese manufacturers compete on cassette cost structures for decentralized collection.
United States
Medicare coverage for quantitative immunochemical formats and employer-sponsored wellness programs drive institutional and direct-to-consumer volume. FDA tightened analytical sensitivity benchmarks under 21 CFR Part 866, accelerating replacement cycles in diagnostic networks. Boston and San Diego anchor DNA-based test development clusters with multi-cancer early detection convergence.
Germany
EMA IVDR Class C reclassification and statutory health insurance reimbursement for population screening sustain high-throughput analyzer demand. German notified bodies prioritize IVDR technical documentation reviews, creating regulatory queue advantages for early filers. Mannheim and Erlangen host automated platform manufacturing and service infrastructure serving European hospital networks.
Japan
Government-mandated colorectal screening for citizens over 50 and PMDA quality benchmarks institutionalize test frequency protocols. METI coordinates national cancer control strategy with prefectural health authorities. Tokyo and Osaka metropolitan markets show concentrated uptake of self-collection protocols through pharmacy retail partnerships.
China
NMPA in vitro diagnostic registration reforms and expanding tier-hospital screening programs create volume opportunities. National Health Commission colorectal cancer prevention guidelines drive provincial procurement consolidation. Guangzhou and Hangzhou manufacturing clusters supply cassette formats for resource-limited settings across Southeast Asia.
Global Fecal Occult Blood Tests Market Competitive Landscape
Concentration sits with diversified diagnostics conglomerates and specialized oncology testing platforms. Three archetypes define competitive positioning: multinational conglomerates with installed-base service infrastructure, molecular diagnostics specialists with DNA-based test portfolios, and point-of-care device manufacturers with decentralized distribution capabilities. M&A activity targets complementary assay technologies while strategic partnerships secure laboratory network access.
Among US-based diversified diagnostics groups, Abbott Laboratories and Quest Diagnostics Incorporated exemplify scale-driven archetypes with point-of-care and laboratory network positioning. Exact Sciences Corporation represents the molecular diagnostics specialist tier. Siemens Healthcare GmbH anchors European automated analyzer supply. Roche Diagnostics occupies premium-tier positioning across immunochemical and molecular platforms.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Quidel Corporation |
| Siemens Healthcare GmbH |
| Exact Sciences Corporation |
| Roche Diagnostics |
| Quest Diagnostics Incorporated |
| HUMASIS.COM |
| CTK Biotech, Inc. |
| Wondfo |
| Others |
Supply & Pricing Matrix
High-throughput analyzer capacity utilization above 85% in German manufacturing clusters creates asymmetric pricing power for immunochemical platform suppliers, compressing margin floors for cassette-format competitors while elevating service-contract premiums across European diagnostic networks.
Pricing Analysis
Volume-discount tiering structures stratify across institutional procurement scale, with diagnostic laboratories commanding 40-60% unit cost reductions against ambulatory care minimums. Price differentiation hinges on FDA clearance tier and automated LIS integration capability, with quantitative analyzer placements least sensitive to cost pressure. Pricing softness reflects Chinese cassette manufacturers penetrating Southeast Asian resource-limited contracts. Home care direct-to-consumer channels show highest price elasticity, driving subscription bundling experiments.
Supply Chain Analysis
Germany and Japan anchor automated analyzer production and monoclonal antibody reagent supply, while China dominates lateral flow cassette manufacturing for decentralized collection. Supply chains draw from specialized plastic molding, nitrocellulose membrane, and recombinant antibody inputs. Single-source vulnerability concentrates in German precision optics for quantitative detection modules. Distribution runs through diagnostic laboratory GPO contracts in the United States and statutory health insurance tenders in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home care channel penetration remains below 15% of addressable screening populations, creating expansion headroom as telehealth reimbursement protocols mature across United States and Japanese metropolitan markets.
For Market Incumbents: Secure installed-base loyalty through API-native LIS integration and predictive service contracts that preempt Chinese cassette competitors. DNA-based test portfolios require defensive patent thickets against multi-cancer early detection convergence. Vertical integration into recombinant antibody production insulates margin compression from reagent supply volatility.
For New Entrants and Emerging Players: Differentiate on employer-sponsored wellness program channels where procurement decentralization bypasses established laboratory GPO lock-in. White-label partnerships with United States health systems offer fastest penetration path. Target pharmacy retail clinic networks in Japan's prefectural health authority structures for volume scale.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors molecular diagnostics specialists with FDA-cleared DNA platforms over point-of-device manufacturers facing analyzer commoditization. Five-to-ten year viability hinges on multi-cancer assay menu expansion. Watch EMA IVDR Class C technical documentation approval velocity as regulatory capacity constraint signal.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | IVDR Class C clinical evidence requirements demand prospective performance studies for German notified body priority review. |
| Hospital System Partnership | White-label home collection agreements preserve laboratory revenue share against direct-to-consumer disintermediation. |
| Software Companion Development | AI-assisted result interpretation elevates throughput economics for high-volume European diagnostic networks. |
| Reimbursement Strategy | Medicare quantitative format coverage and state Medicaid prior authorization harmonization unlock United States volume. |
| Reagent Supply Agreement | Captive monoclonal antibody production secures margin insulation against biologics input cost volatility. |
Research Methodology
Operator-level perspectives from diagnostic laboratory directors, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineers anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) filings, EMA IVDR technical documentation registers, CMS Medicare reimbursement databases, and Japanese MHLW screening program statistics. Bottom-up test volume modeling and top-down healthcare expenditure triangulation cross-verified market sizing.
Sensitivity analysis tested immunochemical versus DNA-based format adoption curves across varying reimbursement scenarios throughout the forecast period. Segmentation dimensions spanned test methodology, end-user channel configuration, application indication, and physical form factor. CAGRs derived from logistic diffusion modeling of screening program penetration rates and analyzer installed-base replacement cycles. Japanese national program volume commitments and United States commercial payer coverage expansion served as key demand inputs.
Material uncertainties — regulatory reclassification timelines, decentralized testing reimbursement reversals, and multi-cancer liquid biopsy substitution — sit outside the modeled envelope. Forecasts reflect documented assumptions concerning screening age threshold stability and IVDR notified body capacity constraints. Recalibration cycles align with material shifts in national cancer control strategy and point-of-care regulatory guidance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
In Vitro Diagnostic Substrate Market
Diagnostics
Mycology Immunoassays Testing Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Global Predictive Genetic Testing and Consumer/Wellness Genomics Market
Diagnostics
Brazil in Vitro Diagnostics Market
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market
Diagnostics
HIV Diagnostics Market
Diagnostics
Mycoplasma Diagnostics Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
Asia-Pacific Antinuclear Antibody Test Market
Diagnostics
Hepatitis B Diagnostic Tests Market
Diagnostics
BNP and NT-Probnp Market
Diagnostics
Global Respiratory Diagnostics Market
Diagnostics
Global Saliva Collection and Diagnosis Market
Diagnostics
South Africa in-Vitro Diagnostics Market