
 Surgical Planning Software Market | 2026-2036
Surgical Planning Software Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Planning Software Market Intelligence
Modular bundling of 3D visualization with preoperative simulation is expanding buyer choice in surgical planning software procurement. Medtronic leverages its implant portfolio to anchor integrated planning-to-execution workflows. Materialise specializes in patient-specific anatomical modeling that competes on precision with generic templating tools. Brainlab controls the neurosurgery segment through dedicated navigation-planning suites that dominate European hospital tenders.
Surgical planning software comprises digital platforms that reconstruct patient anatomy from DICOM imaging data, enabling preoperative measurement, implant selection, and procedural simulation with sub-millimeter accuracy. These systems serve orthopedic, neurosurgical, and cardiac teams by reducing operative time and implant mismatch rates. Cloud-based solutions represent the fastest-expanding technology segment as hospital IT departments prioritize interoperability and remote access. Orthopedic surgery occupies the largest application share due to high procedural volume and implant templating complexity. Workflow management tools capture concentrated margin pools where vendors bundle scheduling, inventory linkage, and outcomes tracking.
FDA 510(k) clearance requirements govern software-as-medical-device classifications in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for planning algorithms in Europe. Japan's PMDA evaluates AI-assisted planning modules under accelerated review pathways that shape vendor submission strategies. Stakeholders must monitor evolving regulatory divergence between jurisdictions to align product roadmaps with market access timelines.
Market Dynamics
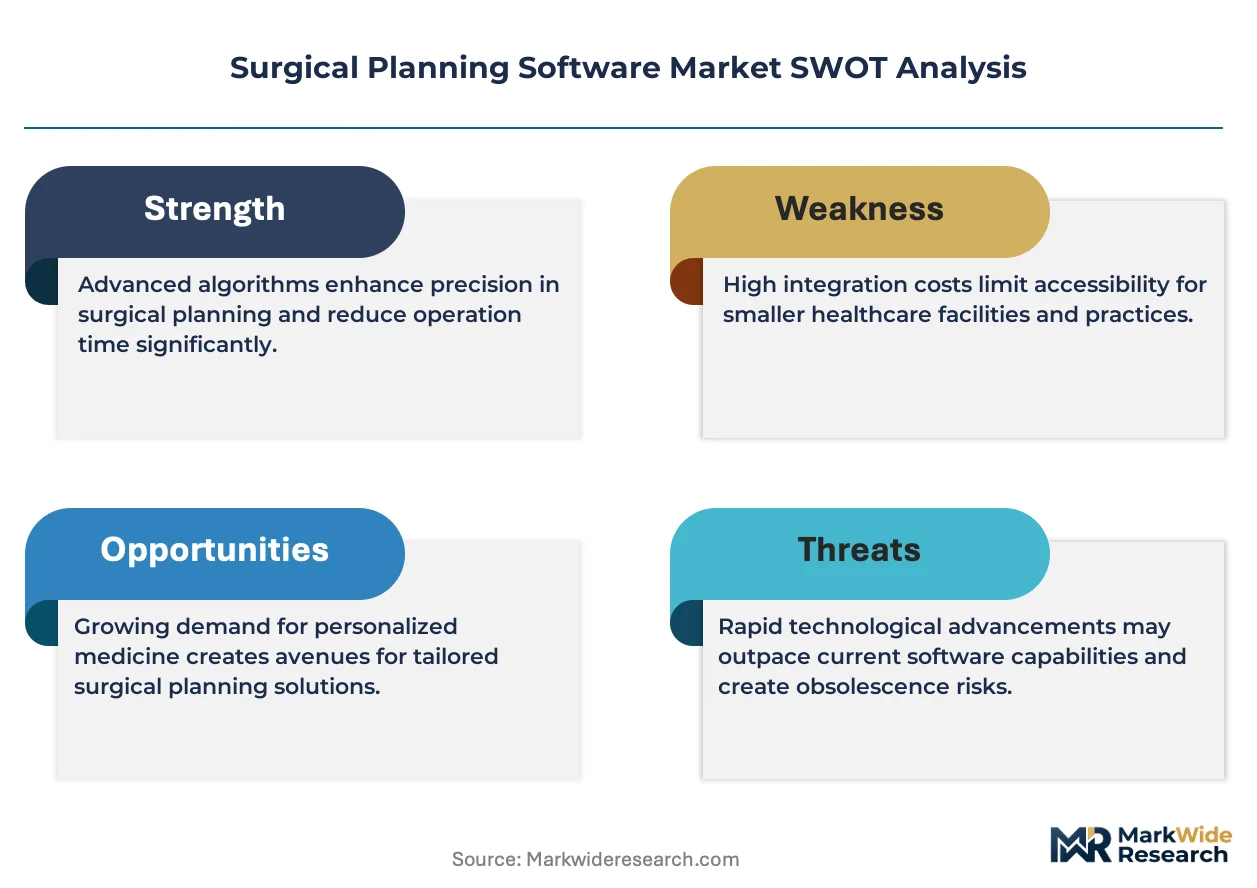
Cloud migration is compressing deployment cycles for surgical planning platforms while FDA 510(k) clearance requirements lengthen product validation timelines. This tension between IT modernization urgency and regulatory rigor defines vendor investment priorities.
Growth Catalysts
- Reimbursement frameworks:Germany's Diagnosis-Related Group system rewards hospitals for documented surgical efficiency gains from digital planning workflows. Orthopedic centers accelerate procurement to capture these incentives.
- Interoperability mandates:The United States ONC 21st Century Cures Act requires EHR connectivity for certified health IT. Surgical planning vendors integrate HL7 FHIR standards to maintain hospital eligibility.
- Implant complexity:Patient-specific instrumentation for revision arthroplasty demands sub-millimeter preoperative measurement. 3D visualization tools address templating precision that generic imaging cannot achieve.
Market Restraints
- IT infrastructure heterogeneity:Legacy PACS architectures in mid-sized United States hospitals resist cloud-native integration. Vendors maintain costly on-premise variants.
- Clinical validation burden:EU Medical Device Regulation demands prospective clinical data for AI-assisted planning algorithms. Smaller developers lack trial funding.
- Specialized talent scarcity:Biomedical engineers with dual expertise in DICOM standards and surgical anatomy command premium compensation. Recruitment bottlenecks delay product releases.
Strategic Opportunities
- Ambulatory surgical centers:United States outpatient joint replacement volume expands as CMS removes procedure codes from inpatient-only lists. Lightweight cloud planning tools suit limited IT staff.
- Cardiac electrophysiology:Structural heart procedures require complex anatomical mapping. Planning software vendors extend orthopedic platforms into electrophysiology suites.
- Japan PMDA Sakigake pathway:Accelerated review for breakthrough medical devices compresses time-to-market for AI planning modules. First-movers secure tender advantages at university hospitals.
Industry Challenges
- Cybersecurity certification:IEC 62304 medical device software lifecycle processes require documented threat modeling. Development teams restructure quality management systems.
- Legacy system integration:PACS from GE Healthcare, Philips, and Siemens operate proprietary DICOM implementations. Planning platforms require custom connectors per installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Planning Software Market |
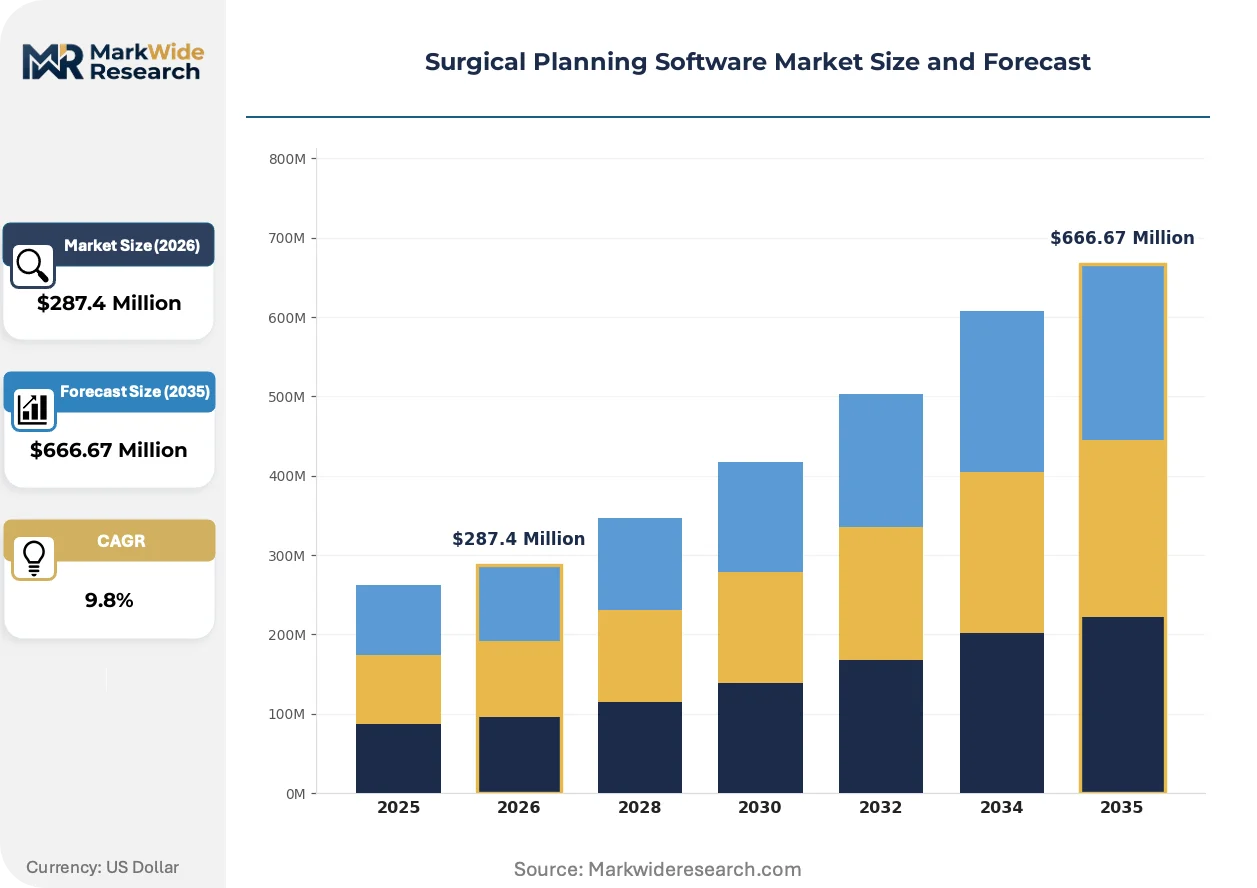
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $666.67 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Visualization, Simulation Tools, Workflow Management, Integration Software End User: Surgical Centers, Hospitals, Specialty Clinics, Research Institutions Technology: Cloud-based Solutions, On-premise Solutions, Mobile Applications, Hybrid Systems Application: Orthopedic Surgery, Neurosurgery, Cardiac Surgery, General Surgery |
| Companies Covered | Medtronic, 3D Systems, Brainlab, Smiths Group, Johnson & Johnson, Stryker, Materialise, Renishaw, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Planning Software Market Strategic Shifts & Innovations
Real-time computational rendering is collapsing the gap between preoperative simulation and intraoperative navigation. Vendors race to unify planning and execution environments.
GPU-accelerated volumetric reconstruction is consolidating previously separate segmentation and visualization pipelines. Academic medical centers in the United States deploy these unified workstations for craniomaxillofacial cases. The compression of discrete software modules into single-platform licensing is consolidating vendor margins and reducing hospital procurement complexity.
EU Medical Device Regulation Article 10 clinical evaluation requirements now extend to software-only products. Planning algorithm developers must submit equivalence arguments or original clinical data. European orthopedic vendors delay launches to compile MDR technical documentation, ceding temporary share to established competitors with legacy device portfolios.
Hospital value analysis committees now mandate outcomes tracking as a contract condition. United States health systems bundle planning software with implant procurement, requiring vendors to demonstrate case-time reduction. This purchasing consolidation favors suppliers with integrated implant-planning portfolios over standalone software vendors.
Surgical Planning Software Market Segmentation
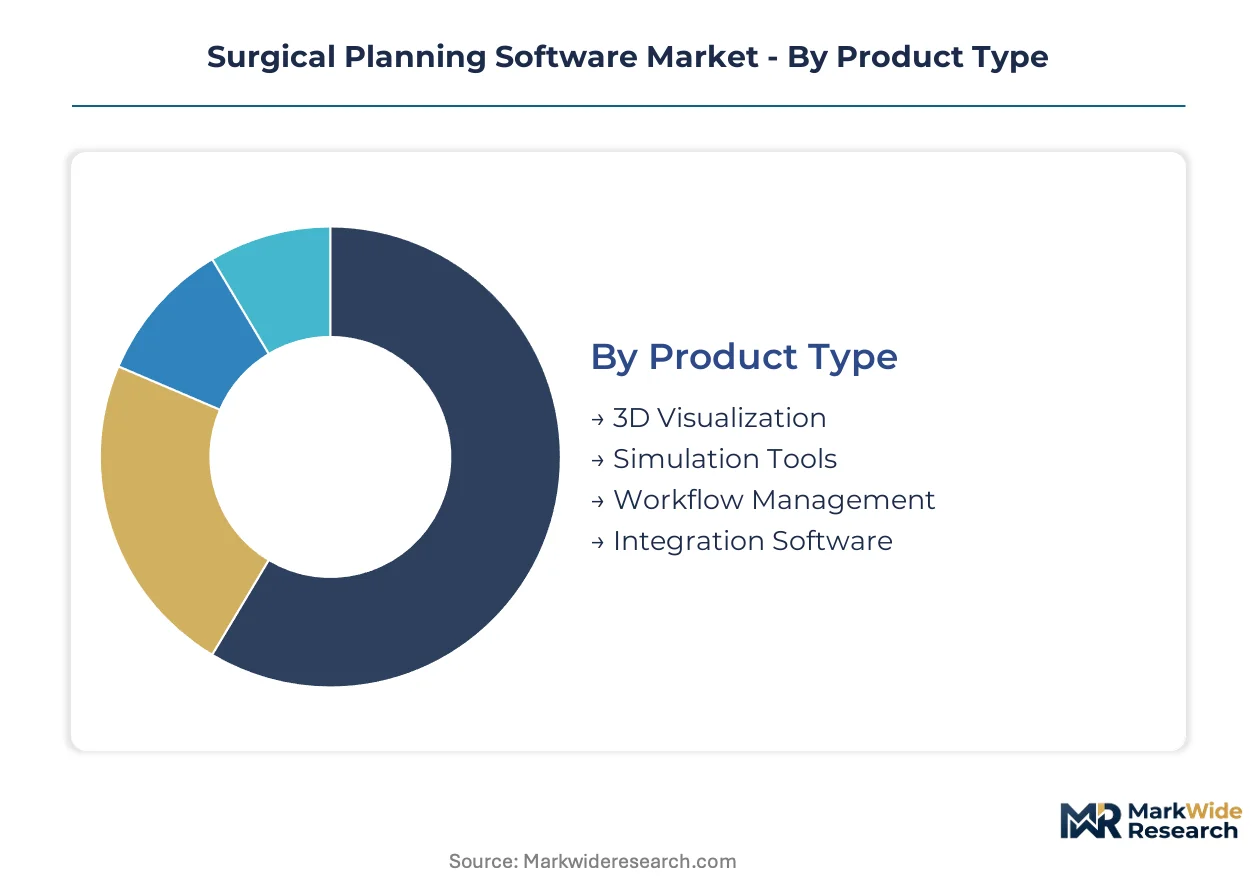
Surgical planning software procurement hinges on interoperability requirements and procedural specialization. Buyers prioritize platforms that compress preoperative workflows while satisfying institutional IT governance. Segmentation reveals where vendors concentrate R&D investment versus where margin compression threatens standalone software providers.
Product Type:
Hospital procurement committees weigh standalone capabilities against bundled platform economics when evaluating software categories.
- 3D Visualization:GPU-accelerated volumetric reconstruction engines process DICOM datasets into manipulable anatomical models. United States academic medical centers deploy these workstations for craniomaxillofacial reconstruction cases where sub-millimeter precision determines implant fit.
- Simulation Tools:Physics-based procedural rehearsal modules enable virtual implant placement and trajectory planning. German orthopedic centers leverage these tools to document surgical efficiency gains for Diagnosis-Related Group reimbursement capture.
- Workflow Management:Scheduling, inventory linkage, and outcomes tracking modules command premium pricing through operational efficiency claims.
- Integration Software:HL7 FHIR-compliant middleware bridges planning platforms with EHR and PACS architectures.
Volume sits with 3D Visualization; growth tilts toward Workflow Management.
End User:
Capital availability and IT staff depth determine purchasing patterns across facility types.
- Hospitals:Enterprise-scale deployments with dedicated biomedical engineering teams favor comprehensive platform licensing. North American health systems bundle planning software with implant procurement contracts, demanding documented case-time reduction.
- Surgical Centers:Lightweight cloud-native solutions suit limited technical staff at United States ambulatory joint replacement facilities.
- Specialty Clinics:Focused orthopedic and neurosurgical practices prioritize procedure-specific modules over full-stack platforms.
- Research Institutions:Academic medical centers in Japan and Germany drive adoption of experimental AI-assisted planning algorithms.
Revenue concentrates in Hospitals; expansion accelerates fastest at Surgical Centers.
Technology:
IT modernization urgency collides with cybersecurity certification requirements across deployment architectures.
- Cloud-based Solutions:Browser-accessible platforms with centralized GPU rendering eliminate on-premise hardware dependencies. United States hospital IT departments prioritize these for remote surgeon access and automatic software updates.
- On-premise Solutions:Air-gapped installations satisfy data sovereignty requirements at European institutions navigating GDPR medical data processing constraints.
- Mobile Applications:Tablet-optimized viewers enable intraoperative reference access.
- Hybrid Systems:Split architectures process sensitive imaging locally while pushing anonymized analytics to cloud infrastructure.
Deployment share favors Cloud-based Solutions; Hybrid Systems gain traction where regulatory fragmentation persists.
Application:
Procedural complexity and implant templating requirements shape segment economics.
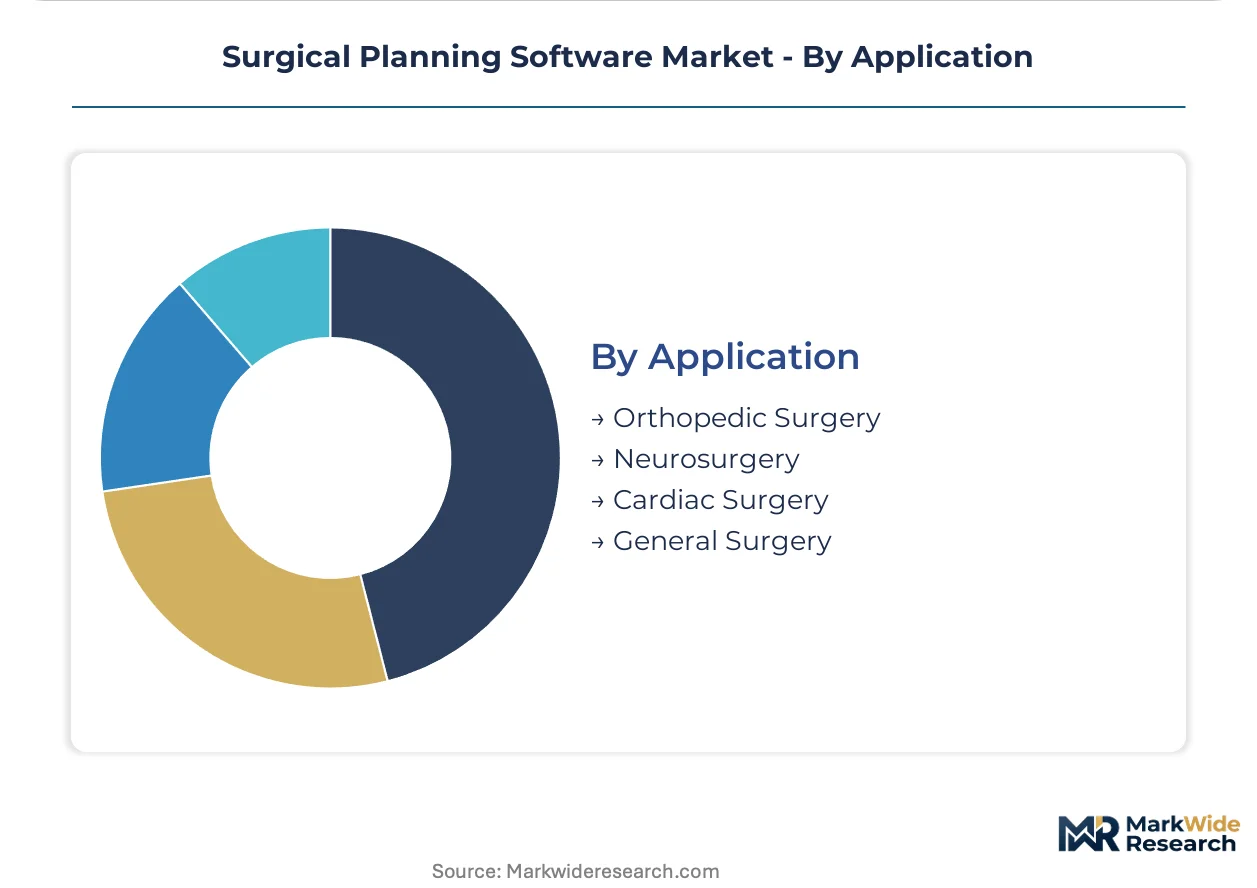
- Orthopedic Surgery:Joint replacement and trauma cases generate the highest planning software utilization due to implant sizing precision demands. Revision arthroplasty patient-specific instrumentation drives sub-millimeter measurement requirements.
- Neurosurgery:Navigation-planning suites dominate European hospital tenders through Brainlab's established European market position.
- Cardiac Surgery:Structural heart procedures require complex anatomical mapping that extends orthopedic platform capabilities.
- General Surgery:Hepatobiliary and oncologic resection planning represents an emerging adoption frontier.
Procedure volume anchors Orthopedic Surgery; Neurosurgery commands the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Development concentrates in jurisdictions with established reimbursement pathways for digital surgical workflows. Consumption patterns diverge between health systems that bundle planning software with implant procurement and those maintaining standalone procurement.
United States
Hospital value analysis committees mandate outcomes tracking as a contract condition. FDA 510(k) clearance governs software-as-medical-device classifications. Academic medical centers in Boston and the Research Triangle deploy GPU-accelerated volumetric reconstruction for craniomaxillofacial cases.
Germany
The Diagnosis-Related Group system rewards documented surgical efficiency gains from digital planning workflows. EU Medical Device Regulation imposes stricter clinical evidence standards for planning algorithms. Orthopedic centers in Bavaria and North Rhine-Westphalia accelerate procurement to capture reimbursement incentives.
Japan
University hospitals drive adoption of experimental AI-assisted planning algorithms. PMDA evaluates AI-assisted planning modules under accelerated review pathways. Medical device clusters in Kanto and Kansai regions secure tender advantages through early regulatory engagement.
United Kingdom
NHS procurement frameworks favor platforms demonstrating HL7 FHIR interoperability. The national regulator aligns software classification with EU MDR transitional provisions. London and Greater Manchester health systems consolidate vendor selection through integrated care board tenders.
Switzerland
Swissmedic maintains streamlined review pathways for planning software with predicate device histories. Cantonal hospital procurement favors modular licensing over comprehensive platform commitments. Basel and Zurich university hospitals anchor adoption of patient-specific instrumentation planning tools.
Surgical Planning Software Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across procurement segments. The market structure consolidates around implant manufacturers bundling planning software with hardware portfolios. Three archetypes dominate: diversified medical device conglomerates with integrated implant-planning portfolios; pure-play software vendors specializing in anatomical modeling precision; and navigation-system specialists controlling procedure-specific segments. Competitive moves center on M&A to acquire 3D visualization capabilities and strategic partnerships with academic medical centers for clinical validation.
Within the diversified conglomerate tier, Medtronic and Stryker represent the implant-anchored planning workflow archetype. Brainlab occupies a distinct position among navigation-system specialists with concentrated presence in neurosurgery tenders. Materialise exemplifies the pure-play anatomical modeling specialist competing on sub-millimeter precision against generic templating alternatives.
| Leading Market Players |
|---|
| Medtronic |
| 3D Systems |
| Brainlab |
| Smiths Group |
| Johnson & Johnson |
| Stryker |
| Materialise |
| Renishaw |
| Zimmer Biomet |
| Others |
Cost & Logistics Intelligence
Backward integration into GPU rendering infrastructure anchors both supply security and pricing power for surgical planning software vendors. Cloud-native platforms draw from captive data center investments in the United States and Germany, while on-premise variants rest on third-party hardware procurement that exposes margins to semiconductor cost cycles.
Pricing Analysis
Cost-down pressure on mid-tier SaaS subscriptions accelerates because United States health systems consolidate vendor selection through bundled implant-procurement contracts. Three-tier pricing structure across premium, standard, and economy levels separates enterprise platform licensing from modular departmental tools and lightweight cloud viewers. Price differentiation hinges on FDA 510(k) clearance tier and after-sales clinical support depth. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with dedicated biomedical engineering teams demonstrate lowest.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan anchor hub-and-spoke delivery of DICOM processing hardware and GPU compute infrastructure. Component sourcing draws from Taiwan for semiconductor fabrication, South Korea for memory modules, and the Netherlands for photonics equipment. Single-source vulnerability concentrates in specialized DICOM parser libraries maintained by European academic consortia. Distribution runs through direct enterprise sales teams for hospital systems and value-added resellers for mid-sized orthopedic clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surgical planning software represents a consolidation play where EU Medical Device Regulation compliance costs force sub-scale developers toward acquisition or exit. Regulatory divergence between FDA 510(k) and MDR clinical evidence requirements accelerates this filtering mechanism.
For Market Incumbents: Anticipate margin compression from cloud-native entrants by deepening captive control over implant-planning workflow integration. Acquire 3D visualization specialists to defend against modular bundling threats. Prioritize MDR technical documentation investment to maintain European hospital tender eligibility while smaller competitors delay launches.
For New Entrants and Emerging Players: AI-assisted planning algorithms for cardiac electrophysiology offer the most penetrable white-space target, as established vendors remain anchored in orthopedic and neurosurgical segments. Japan's PMDA Sakigake accelerated review pathway provides regulatory fast-track differentiation. Pursue university hospital pilot partnerships to generate clinical validation data for subsequent commercial scaling.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical device conglomerates seeking planning-to-execution workflow integration. Long-term viability favors pure-play anatomical modeling specialists with established FDA predicates and recurring SaaS revenue bases. Monitor FDA 510(k) clearance backlogs as inflection indicator for vendor time-to-market competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Software-as-medical-device classification governs United States market access timelines and competitive positioning. |
| CE Marking Pathway | EU MDR Article 10 clinical evaluation requirements extend to planning algorithms, reshaping European vendor economics. |
| Hospital System Partnership | Integrated care board tenders in Germany and NHS frameworks in the United Kingdom consolidate procurement decisions. |
| Software Companion Development | HL7 FHIR-compliant middleware bridges planning platforms with EHR architectures mandated by ONC interoperability rules. |
| Reimbursement Strategy | Germany's Diagnosis-Related Group efficiency incentives and United States CMS outpatient procedure code expansions drive adoption. |
Research Approach
Document review covered FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contracts, complemented by interviews with surgical planning software product managers, hospital biomedical engineers, orthopedic surgeons, and health system IT procurement officers. Secondary validation drew from CMS reimbursement data, PMDA review pathway disclosures, and academic medical center pilot study publications. Bottom-up vendor revenue estimates triangulated against top-down health system IT spending allocations.
Market size and growth trajectories across the analysis window reflect procedure volume modeling by surgical specialty, cloud adoption curve assumptions, and regulatory clearance pipeline velocity. Segmentation dimensions included deployment architecture, application area, end-user facility type, and regional reimbursement framework. CAGRs were derived from fitted adoption curves benchmarked against analogous healthcare IT categories. Forecast inputs incorporated hospital capital expenditure cycles and implant manufacturer bundling contract trends.
Several conditions sit outside the modeled scope, including cybersecurity incident impacts on cloud adoption willingness, sudden regulatory reclassification of AI-assisted algorithms, and macroeconomic disruptions to hospital capital budgets. Forecasts reflect documented assumptions regarding clearance timeline continuity and reimbursement stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Global Plastic Surgery Software Market
Digital Health Solutions
VR in Healthcare Market
Digital Health Solutions
Mhealth Market
Digital Health Solutions
Amblyopia Treatment Softwares Market
Digital Health Solutions
Mixed Reality in Healthcare Market
Digital Health Solutions
Global Microservices in Healthcare Market
Digital Health Solutions
Patient Case Management Software Market
Digital Health Solutions
AI-Powered Clinical Decision Support Market
Digital Health Solutions
Global Clinical Decision Support System Market
Digital Health Solutions
North America Mobile Health (Mhealth) Market
Digital Health Solutions
US Advance Care Planning Solutions Market
Digital Health Solutions
Global Patient Centric Healthcare App Market
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
Prescribed Health Apps Market
Digital Health Solutions
Healthcare Mobile Application Market
Digital Health Solutions
Digital Health Tracking Apps Market