
 Asia-Pacific Ostomy Care and Accessories Market | 2026-2036
Asia-Pacific Ostomy Care and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ostomy Care and Accessories Market Analytics
Trained stoma therapy nursing capacity is bifurcating the Asia-Pacific Ostomy Care and Accessories Market into markets with adequate clinical support and those where patient self-management dominates. Coloplast Group leverages its dedicated stoma care nurse training programs to sustain premium positioning across Japan and South Korea. Hollister Incorporated anchors its regional footprint through localized manufacturing and direct hospital contracting in Australia and India.
Asia-Pacific ostomy care and accessories encompass pouching systems, skin barriers, and adjunct products designed for fecal or urinary diversion following colorectal, urological, or gastrointestinal surgery, typically constructed from odor-resistant films with hypoallergenic adhesives to maintain peristomal skin integrity and contain effluent. These products serve post-operative recovery, chronic condition management, and patient quality-of-life maintenance across acute and community settings. Colostomy and ileostomy bags occupy the dominant revenue share due to higher procedure volumes and repeat purchase frequency, while accessories generate expanding margin pools as patient education improves adherence to complementary skin care and deodorizing protocols. Home care end users represent the fastest-growing consumption channel as discharge protocols shorten hospital stays and family caregivers assume routine pouching responsibilities.
Japan's PMDA and Australia's TGA enforce stringent biocompatibility and adhesive safety standards that elevate compliance costs for new market entrants across the Asia-Pacific Ostomy Care and Accessories Market. India's CDSCO medical device rules and China's NMPA registration requirements further fragment approval timelines, favoring incumbents with established regulatory dossiers and local quality infrastructure. Stakeholders must monitor how reimbursement harmonization between national health insurance schemes and private payers reshapes patient access economics and brand switching behavior.
Market Dynamics
Home care nursing capacity gaps across Southeast Asia are forcing manufacturers to redesign product portfolios for unassisted patient self-management, compressing training-dependent premium offerings while expanding simplified one-piece systems.
Growth Catalysts
- CDSCO Quality Norms:India's tightened medical device quality standards for imported ostomy products are accelerating domestic manufacturing investments and local supply chain development.
- Tier-One Hospital Procurement:China's centralized hospital network procurement channels concentrate demand volumes, enabling scale economies for compliant suppliers.
- Hydrocolloid Adhesive Advances:Next-generation skin barrier materials with extended wear times reduce peristomal complications and drive repeat purchase loyalty.
Market Restraints
- Medical-Grade Silicone Volatility:Input cost fluctuations for hypoallergenic adhesive films compress margin stability for pouching system manufacturers.
- Regulatory Fragmentation:Divergent PMDA, TGA, NMPA, and CDSCO approval timelines extend product launch cycles and duplicate compliance expenditures.
- Reimbursement Heterogeneity:Inconsistent national health insurance coverage across Australia, Japan, South Korea, and India creates patient access disparities.
Strategic Opportunities
- Vietnam and Indonesia Home Care:Underpenetrated Southeast Asian markets with expanding private insurance coverage present first-mover positioning for simplified product lines.
- Digital Stoma Care Platforms:Telehealth integration with remote peristomal skin monitoring creates subscription-based service revenue adjacent to hardware sales.
- Biodegradable Barrier Films:Converging sustainability mandates and patient environmental preferences open differentiation through compostable pouch materials.
Industry Challenges
- Stoma Therapy Nurse Scarcity:Limited specialized nursing capacity across India's secondary cities forces manufacturers to absorb patient education costs directly.
- Legacy Hospital Contract Lock-In:Incumbent suppliers with multi-year procurement agreements in Japan and Australia create switching friction for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ostomy Care and Accessories Market |
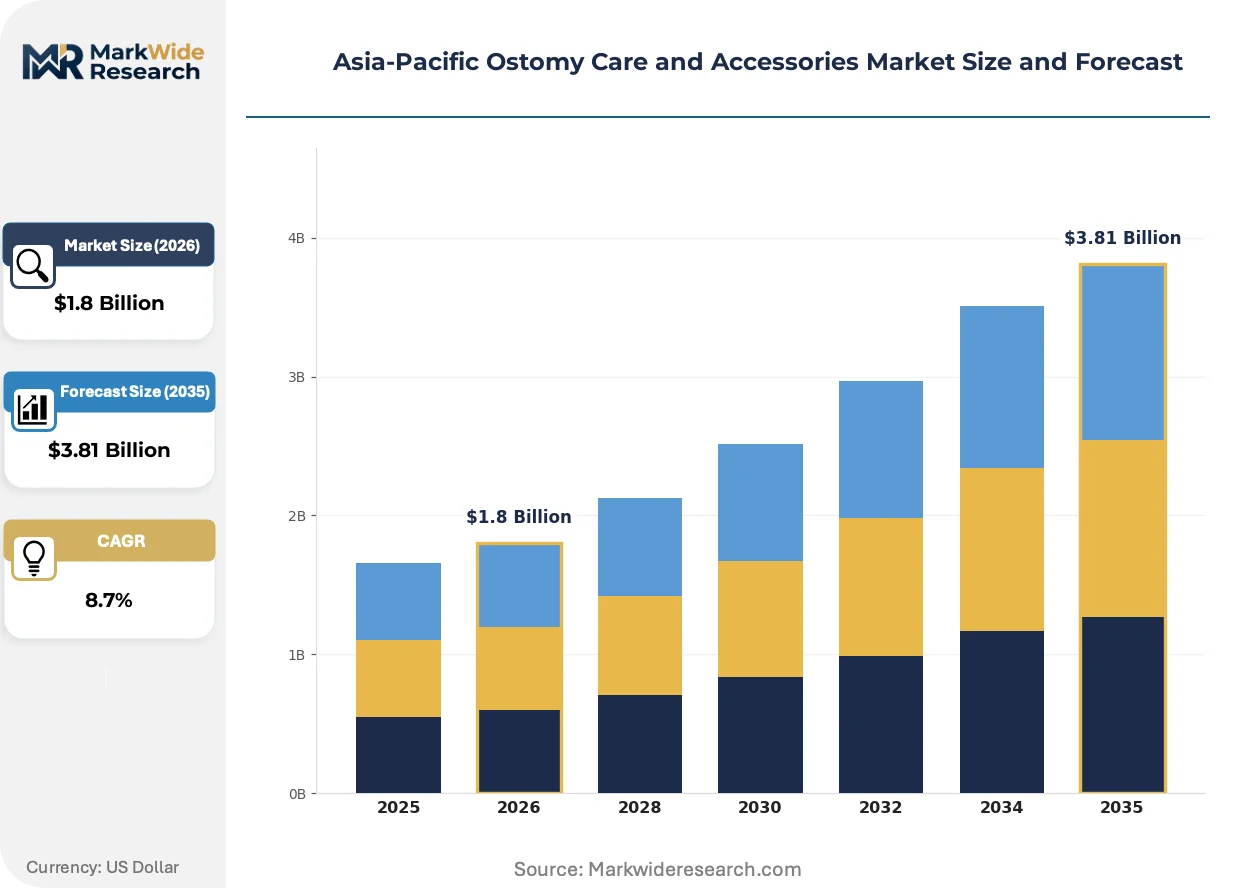
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colostomy Bags, Ileostomy Bags, Urostomy Bags, Accessories End User: Hospitals, Home Care, Specialty Clinics, Long-term Care Facilities Distribution Channel: Pharmacies, E-commerce, Retail Stores, Direct Sales Application: Post-surgery Care, Daily Management, Lifestyle Adaptation, Emergency Care |
| Companies Covered | Coloplast Group, ConvaTec Inc., Hollister Incorporated, ALCARE Co., Ltd., B. Braun Melsungen, Smith & Nephew, 3M Company, Salts Healthcare Ltd., Cymed Ostomy Co., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ostomy Care and Accessories Market Evolving Landscape
Product simplification and digital connectivity are converging to reduce clinical dependency while capturing patient adherence data. Manufacturers now compete on unassisted usability metrics rather than clinical support depth alone.
Closed-end pouch systems with integrated charcoal filters are supplanting traditional two-piece designs in Japan's home care segment. Elderly ostomates managing colostomies without nursing assistance favor these all-in-one units for odor containment and disposal convenience. The shift is compressing demand for separate skin barrier accessories and reducing manufacturer revenue per patient.
Australia's TGA biocompatibility standards are tightening adhesive safety testing protocols for extended-wear skin barriers. Manufacturers must submit expanded cytotoxicity and sensitization data, extending registration timelines by four to six months. Premium suppliers with established TGA dossiers are absorbing smaller competitors unable to fund parallel regulatory pathways.
Family caregivers in China's tier-two cities are assuming routine pouching responsibilities as hospital discharge protocols shorten. E-commerce platforms and hospital-affiliated pharmacies are displacing traditional medical supply distributors for initial product sourcing. This channel rotation concentrates purchasing power with platforms capable of same-day delivery and subscription replenishment services.
Asia-Pacific Ostomy Care and Accessories Market Segmentation
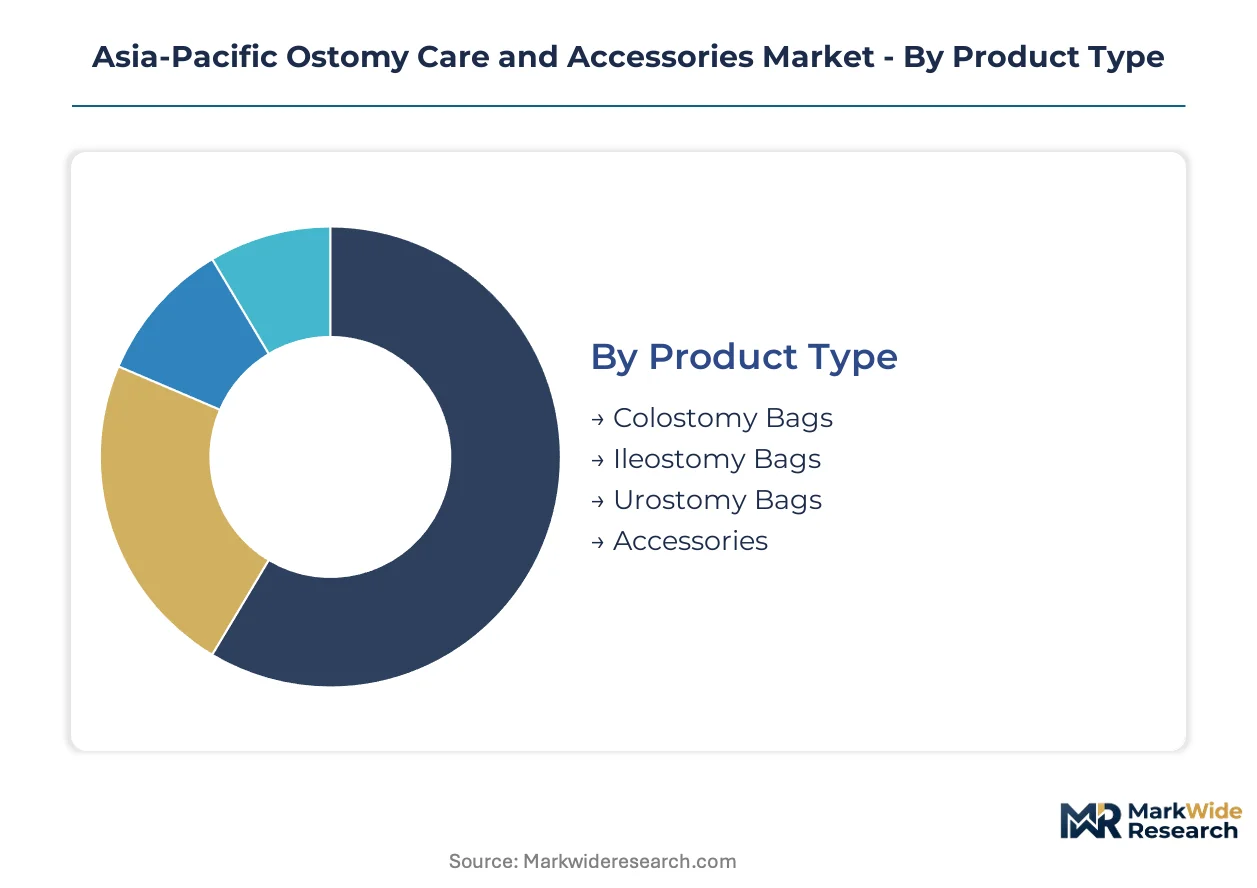
Product differentiation across the Asia-Pacific Ostomy Care and Accessories Market determines reimbursement eligibility and patient self-management feasibility. Segment boundaries shift as hydrocolloid adhesive technologies mature and home care nursing capacity expands unevenly across the region.
Product Type:
Closed-end pouch systems with integrated filters are displacing traditional two-piece designs in Japan's elderly self-care segment, intensifying substitution pressure on separate skin barrier accessories.
- Colostomy Bags:One-piece and two-piece pouching systems constructed from odor-resistant films with hypoallergenic adhesives. Demand concentrates in China's tier-one hospital procurement networks where centralized purchasing favors scale-compliant manufacturers.
- Ileostomy Bags:Higher-output drainage systems with enhanced adhesive security for liquid effluent management. Australia's TGA biocompatibility standards are elevating compliance costs for extended-wear variants, favoring incumbents with established dossiers.
- Urostomy Bags:Urinary diversion pouches with anti-reflux valves and tap drainage systems.
- Accessories:Skin barriers, deodorizing filters, adhesive removers, and belt systems.
Colostomy bags anchor the volume base while accessories gain share at the steepest rate as patient education improves adherence to complementary skin care protocols.
End User:
Cost tier stratification separates premium clinical-supported segments from economy self-management channels across Southeast Asia's fragmented reimbursement landscape.
- Hospitals:Acute care settings performing initial stoma formation surgeries and post-operative training. China's discharge protocol compression is shortening average length of stay and accelerating patient transition to community settings.
- Home Care:Family-managed pouching routines with remote nursing support. India's CDSCO quality norms for imported products are redirecting demand toward domestic manufacturing as patients assume routine care responsibilities.
- Specialty Clinics:Dedicated stoma therapy centers in Japan and South Korea with trained nursing capacity.
- Long-term Care Facilities:Institutional settings managing elderly ostomates with limited mobility.
Hospitals dominate current procurement volumes while home care expands most quickly as nursing capacity gaps force product redesign for unassisted use.
Distribution Channel:
Geographic concentration of purchasing power is shifting from traditional medical supply distributors toward platform-controlled replenishment services in China's urban corridors.
- Pharmacies:Hospital-affiliated and community retail channels with prescription-linked dispensing. Australia's long-term contract structures with incumbent suppliers create switching friction for new market entrants.
- E-commerce:Platform-based sourcing with subscription replenishment and same-day delivery capabilities. Family caregivers in China's tier-two cities are displacing traditional distributors for initial product procurement.
- Retail Stores:Limited specialty medical supply outlets with trained staff.
- Direct Sales:Manufacturer-to-institution contracting for high-volume hospital networks.
Direct sales capture the largest contract values while e-commerce climbs the fastest as channel rotation concentrates purchasing power with logistics-integrated platforms.
Application:
Customer maturity divergence separates established daily management routines from acute intervention requirements, with technology investment prioritizing adherence monitoring over emergency functionality.
- Post-surgery Care:Initial stoma formation recovery with intensive nursing support and product trial periods. Japan's PMDA stringent biocompatibility standards elevate entry barriers for new adhesive formulations during this critical adaptation phase.
- Daily Management:Routine pouching cycles with emphasis on wear time extension and skin integrity preservation. South Korea's expanding private insurance coverage is improving patient access to premium extended-wear systems.
- Lifestyle Adaptation:Travel, exercise, and social participation accessories.
- Emergency Care:Backup supplies and complication response products.
Daily management commands the recurring revenue base while post-surgery care shows the steepest expansion trajectory as procedure volumes rise across India's secondary cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PMDA biocompatibility standards and NMPA registration requirements anchor procurement dynamics across the region's dominant geographies. National health insurance schemes and private payer structures create divergent access economics that reshape brand loyalty and switching behavior.
China
Tier-one hospital networks concentrate pouching system demand through centralized procurement channels that favor scale-compliant manufacturers. NMPA registration timelines for extended-wear skin barriers extend product launch cycles, elevating compliance costs for new adhesive formulations. Yangtze River Delta medical device clusters around Shanghai absorb domestic manufacturing investments as discharge protocols shorten hospital stays.
Japan
Elderly ostomates managing colostomies without nursing assistance drive closed-end pouch adoption with integrated charcoal filters for odor containment. PMDA stringent biocompatibility and adhesive safety standards compress demand for separate skin barrier accessories. Kanto region stoma therapy centers maintain trained nursing capacity that sustains premium positioning for clinically supported product tiers.
India
Secondary cities force manufacturers to absorb direct patient education costs as specialized stoma therapy nurse scarcity limits clinical support infrastructure. CDSCO tightened quality norms for imported ostomy products accelerate domestic manufacturing investments and local supply chain development. Maharashtra and Gujarat medical device corridors capture redirected demand toward domestically produced simplified one-piece systems.
Australia
Long-term contract structures with incumbent suppliers create switching friction for new market entrants across hospital and pharmacy channels. TGA biocompatibility standards tighten adhesive safety testing protocols, extending registration timelines by four to six months. Victoria and New South Wales home care segments expand fastest as family caregivers assume routine pouching responsibilities with remote nursing support.
South Korea
Expanding private insurance coverage improves patient access to premium extended-wear systems with hydrocolloid adhesive advances. MFDS medical device regulations align with international standards while maintaining distinct documentation requirements. Seoul Capital Area specialty clinics concentrate trained stoma care nursing capacity that differentiates clinically supported segments from self-management channels.
Asia-Pacific Ostomy Care and Accessories Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific Ostomy Care and Accessories Market. The vendor base concentrates around established incumbents with regulatory dossiers and local quality infrastructure, while mid-tier challengers compete on simplified product lines for unassisted patient self-management. Two strategic archetypes dominate: premium suppliers with dedicated stoma care nurse training programs, and scale-driven manufacturers with localized production and direct hospital contracting. Competitive moves center on geographic expansion through regulatory dossier accumulation and portfolio diversification into digital stoma care platforms.
Within the premium clinical-support tier, Coloplast Group and Hollister Incorporated exemplify divergent regional anchoring strategies. Coloplast represents the nursing-capacity-dependent archetype with dedicated training programs sustaining premium positioning across Japan and South Korea. Hollister occupies the localized-manufacturing position through direct hospital contracting in Australia and India. Among diversified medical technology conglomerates, B. Braun Melsungen and Smith & Nephew sit within broader wound care and surgical portfolios where ostomy products represent adjacent category extensions rather than core strategic focus.
| Leading Market Players |
|---|
| Coloplast Group |
| ConvaTec Inc. |
| Hollister Incorporated |
| ALCARE Co., Ltd. |
| B. Braun Melsungen |
| Smith & Nephew |
| 3M Company |
| Salts Healthcare Ltd. |
| Cymed Ostomy Co. |
| Others |
Value Network & Pricing Analysis
Centralized procurement volumes across China's tier-one hospital networks generate scale economies that compress unit economics for compliant manufacturers while elevating price floors for new adhesive formulations seeking NMPA registration. Tier-one hospital buyers leverage consolidated demand to extract volume discounts from scale-compliant suppliers, while smaller secondary-city institutions face higher per-unit costs due to fragmented purchasing and logistics overhead.
Pricing Analysis
Japan commands premium positioning at 40-60% above India's domestic-manufactured equivalent, reflecting PMDA biocompatibility compliance costs and trained nursing support bundling. Three-tier pricing structure across premium extended-wear systems, standard two-piece designs, and economy one-piece alternatives separates clinically supported segments from self-management channels. Cost compression in China's economy tier intensifies as domestic manufacturers absorb CDSCO quality compliance investments. Home care family caregivers in Southeast Asia exhibit highest price sensitivity, while Japan's elderly ostomates with private insurance coverage show lowest elasticity.
Supply Chain Analysis
Strategic stockpiling of medical-grade silicone and hydrocolloid adhesive resins dominates inventory strategy as manufacturers buffer against raw material volatility and extended regulatory approval timelines. Manufacturing concentrates in China, Japan, and India, with Yangtze River Delta clusters serving domestic hospital procurement and Maharashtra corridors absorbing redirected demand from tightened import quality norms. Supply chains rest on hypoallergenic adhesive films, odor-resistant polymer films, and charcoal filter components. Single-source vulnerability runs through specialized medical-grade silicone suppliers concentrated in East Asian chemical corridors. Distribution runs through hospital-affiliated pharmacy platforms in China, direct manufacturer contracting in Australia, and traditional medical supply distributors in India's secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Ostomy Care and Accessories Market sits in early-stage cyclical recovery as procedure volumes rebound from pandemic-deferred colorectal surgeries and home care nursing capacity expansion accelerates product redesign cycles.
For Market Incumbents: Consolidate regulatory dossier advantages by accelerating NMPA and CDSCO parallel submissions before tightened biocompatibility standards elevate compliance barriers for challengers. Deepen backward integration into hydrocolloid adhesive production to buffer margin pressure from medical-grade silicone volatility. Lock in multi-year direct hospital contracts across Australia's concentrated procurement structures to preempt switching opportunities for emerging domestic manufacturers.
For New Entrants and Emerging Players: Lead with simplified one-piece pouch systems designed for unassisted patient self-management in Vietnam and Indonesia's underpenetrated home care segments. Target family caregivers in China's tier-two cities through e-commerce platform partnerships with same-day delivery capabilities. Pursue white-label manufacturing arrangements with established domestic producers to bypass CDSCO import quality barriers while building brand recognition.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with captive adhesive production and established regulatory dossiers across PMDA, TGA, and NMPA jurisdictions. Long-term viability hinges on digital stoma care platform adjacencies that capture recurring subscription revenue beyond hardware sales. Acquisition target archetype: mid-scale domestic manufacturers in India and China with CDSCO/NMPA approvals and underutilized capacity. Watch for inflection when telehealth reimbursement codes for remote peristomal monitoring achieve parity with in-person nursing consultations.
| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO/NMPA Parallel Registration | Accelerated approval timelines capture market access before quality norm tightening elevates barriers. |
| Domestic Manufacturing Investment | Localized production in Maharashtra and Gujarat corridors redirects demand from import-dependent channels. |
| Digital Stoma Care Platform Development | Telehealth integration with remote skin monitoring creates subscription revenue adjacent to hardware sales. |
| Simplified One-Piece System Launch | Unassisted usability design captures Southeast Asian home care expansion where nursing capacity gaps persist. |
| Biodegradable Barrier Film R&D | Compostable pouch materials align with Japan's sustainability mandates and patient environmental preferences. |
Research Methodology
The analysis maps colostomy bags, ileostomy bags, urostomy systems, and accessories segments, each validated through stoma therapy nurses, hospital procurement managers, biomedical engineers, and GPO contracts specialists. Primary interviews with manufacturers, distributors, and clinical end-users combined with secondary validation against NMPA registration databases, CDSCO medical device rules, hospital procurement records, and PMDA approval filings. Bottom-up demand modeling across patient population incidence and top-down supply-side capacity assessment provided triangulation consistency.
External benchmark validation against regional medical device trade data and reimbursement scheme disclosures ensured output consistency across the projection horizon. Segmentation dimensions modeled include product type, end-user setting, distribution channel, and application phase, with hydrocolloid adhesive technology maturity as an industry-specific demand driver. CAGRs derived from procedure volume trajectories, discharge protocol compression rates, and home care nursing capacity expansion curves.
Underlying assumptions cover stable regulatory approval timelines, silicone price volatility within historical bands, and reimbursement harmonization progress, with deviation risk concentrated in sudden CDSCO quality norm enforcement acceleration or NMPA biocompatibility standard elevation. Revision becomes warranted when telehealth reimbursement parity thresholds cross or centralized procurement concentration in China's tier-one networks shifts toward platform-based aggregation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Anterior Cervical Plating Market
Medical Devices
Digital Respiratory Devices Market
Medical Devices
Germany Contraceptive Devices Market
Medical Devices
Non-Invasive Glucose Monitoring Devices Market
Medical Devices
Smart Vision Aids Market
Medical Devices
Heart Defect Closure Devices Market
Medical Devices
Smart Pills Technology Market
Medical Devices
Inhaled Corticosteroid Device Market
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
Heel Pressure Injury Relieving Devices Market
Medical Devices
Wearable Artificial Kidney Market
Medical Devices
Additional Defibrillator Accessories (AED) Market
Medical Devices
Elbow Fixation Systems Market
Medical Devices
Microcurrent Facial Market
Medical Devices
Colon Hydrotherapy Units Market
Medical Devices
Surgical AR Systems Market