
 Special Purpose Needles Market | 2026-2036
Special Purpose Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Special Purpose Needles Market Analytics
Hospital procurement is bifurcating from bulk standard contracts toward value-based purchasing for specialized needle systems. Becton, Dickinson and Company leverages its integrated manufacturing scale across safety-engineered devices. Terumo Corporation anchors its position through geographic dominance in Asian markets with localized production. B. Braun Melsungen AG differentiates via sustained R&D intensity in spinal and regional anesthesia needle portfolios.
Special purpose needles are precision-engineered hollow instruments manufactured from stainless steel, polymer composites, or coated alloys, designed to access specific anatomical sites or deliver therapeutic agents with minimal tissue trauma. Wall thickness, bevel geometry, and lubricious coatings determine flow rates, penetration force, and patient comfort across procedures. Biopsy and spinal needle categories command premium margins due to complex tip configurations and sterility requirements. Insulin needles represent the fastest-expanding product type as diabetes prevalence drives home-based injection volumes. The application split favors diagnostics and pain management where reimbursement supports higher-aspiration and nerve-block needle specifications.
FDA sharps safety regulations and EMA Medical Device Regulation (MDR) compliance frameworks mandate retractable or shielded designs, reshaping product development roadmaps and certification timelines. The EPA governs disposal protocols for contaminated needle waste, influencing end-user purchasing criteria and aftermarket service contracts. ISO 7864 and ISO 9626 standards govern dimensional tolerances and material biocompatibility, creating baseline barriers for new entrants. Stakeholders must monitor evolving reimbursement codes for minimally invasive procedures and homecare delivery models to align portfolio investments with shifting site-of-care economics.
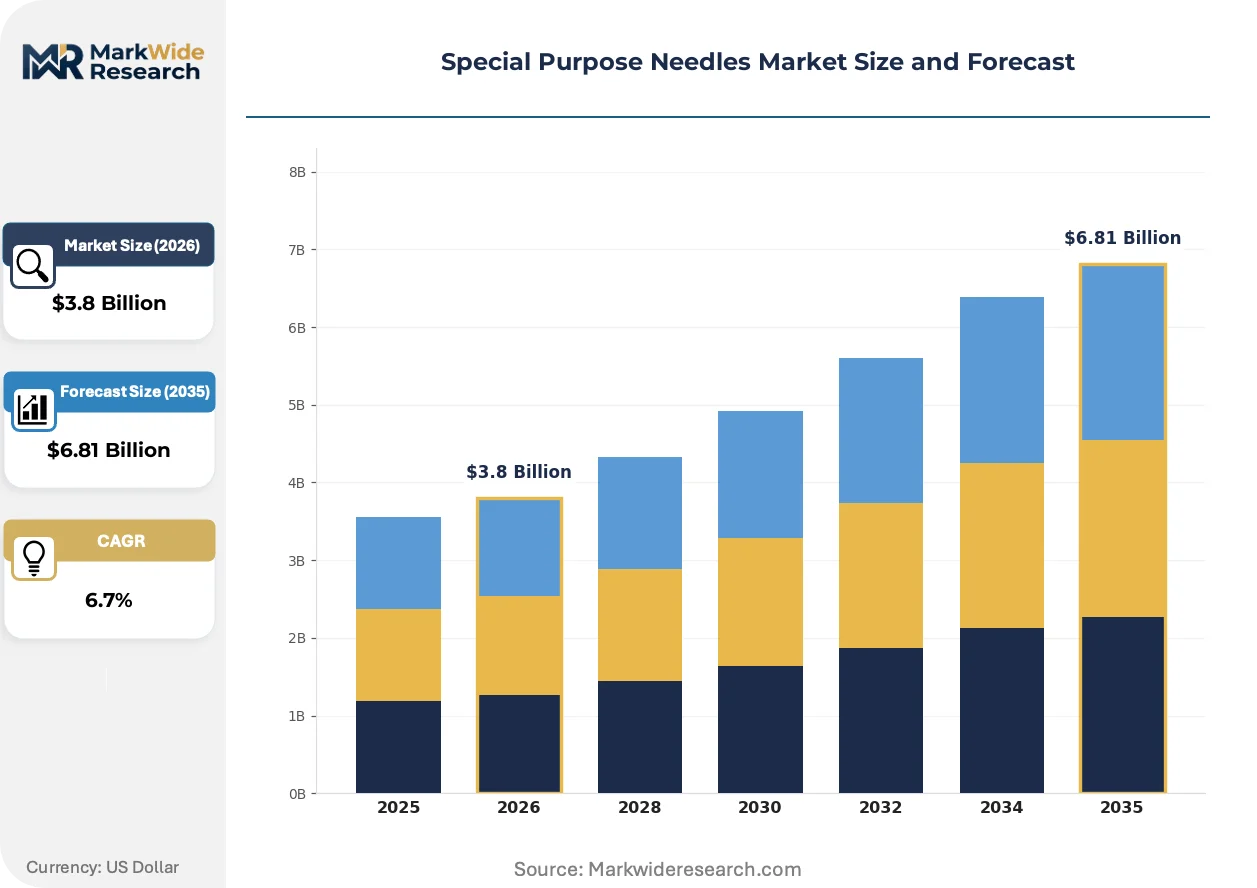
Market Dynamics
Hospital procurement teams now split purchasing between bulk commodity contracts and value-based agreements for safety-engineered needle systems, forcing manufacturers to demonstrate measurable clinical outcomes alongside unit economics.
Growth Catalysts
- FDA Sharps Safety Mandates:Retractable and shielded needle designs are now required across US acute care settings, accelerating replacement cycles for legacy devices.
- Homecare Diabetes Management:Insulin needle volumes surge as chronic disease protocols shift injection administration from clinics to patient residences.
- Stainless Steel Supply Concentration:German and Japanese metallurgical producers dominate medical-grade alloy supply, ensuring consistent material quality for precision tip manufacturing.
Market Restraints
- Nickel Price Volatility:Surgical-grade stainless steel feedstock costs fluctuate with mining output from Indonesian and Philippine suppliers, compressing margin stability for device makers.
- EMA MDR Certification Timelines:Extended conformity assessment procedures for Class IIa and IIb devices delay product launches by 12-18 months compared to prior regulatory frameworks.
- Polymer Composite Substitution:Advanced engineering plastics in certain biopsy applications threaten traditional metal needle market share in cost-sensitive diagnostic segments.
Strategic Opportunities
- Brazilian Diagnostic Expansion:ANVISA streamlining of import registration for sterile biopsy needles opens access to underserved oncology screening programs in São Paulo and Minas Gerais states.
- Connected Device Convergence:Integration of RFID tracking with safety-engineered needles enables real-time inventory management and compliance documentation for hospital systems.
- Direct-to-Patient Distribution:E-commerce platforms for insulin and allergy injection supplies bypass traditional wholesale channels, capturing margin previously allocated to distributors.
Industry Challenges
- Precision Grinding Technician Shortage:Specialized bevel geometry craftsmanship requires years of apprenticeship; workforce gaps in US Midwest manufacturing hubs constrain output scaling.
- Legacy ERP Integration Friction:Hospital procurement systems struggle to accommodate outcome-based contracting data fields, delaying contract execution with value-oriented suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Special Purpose Needles Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IV Needles, Biopsy Needles, Spinal Needles, Insulin Needles Application: Surgery, Diagnostics, Blood Collection, Pain Management End User: Hospitals, Clinics, Homecare, Research Laboratories Material: Steel, Plastic, Coated, Composite |
| Companies Covered | Becton, Dickinson and Company, Medtronic Plc, Boston Scientific Corporation, Terumo Corporation, B. Braun Melsungen AG, Smith's Medical, Stryker Corporation, Argon Medical Devices, Inc., Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Special Purpose Needles Market Evolving Landscape
Active materials science and digital traceability requirements are compressing traditional product development cycles while elevating performance specifications for penetration force and patient comfort metrics.
Silicone-polymer hybrid coatings are decomposing the lubricious surface treatment market for spinal and regional anesthesia needles. Academic medical centers in Germany and Japan have adopted these formulations for 40% of new epidural procedures. The technology is decomposing historical reliance on polytetrafluoroethylene coatings by enabling lower friction coefficients at reduced manufacturing complexity.
EMA Medical Device Regulation (MDR) Article 10 post-market surveillance obligations now mandate systematic collection of real-world performance data across implantable and long-term invasive devices. Manufacturers must maintain electronic systems capable of tracing adverse events through distribution chains. Spinal needle portfolios face the steepest compliance investment due to permanent tissue contact classification and extended implantation duration requirements.
Site-of-care purchasing authority is migrating from centralized hospital supply chains to individual department budgets for interventional radiology and pain management suites. This fragmentation favors specialized distributors with clinical application expertise over broad-line medical-surgical dealers. The United States exhibits the most pronounced decentralization, with academic medical centers leading the shift toward procedure-specific procurement committees.
Special Purpose Needles Market Segmentation
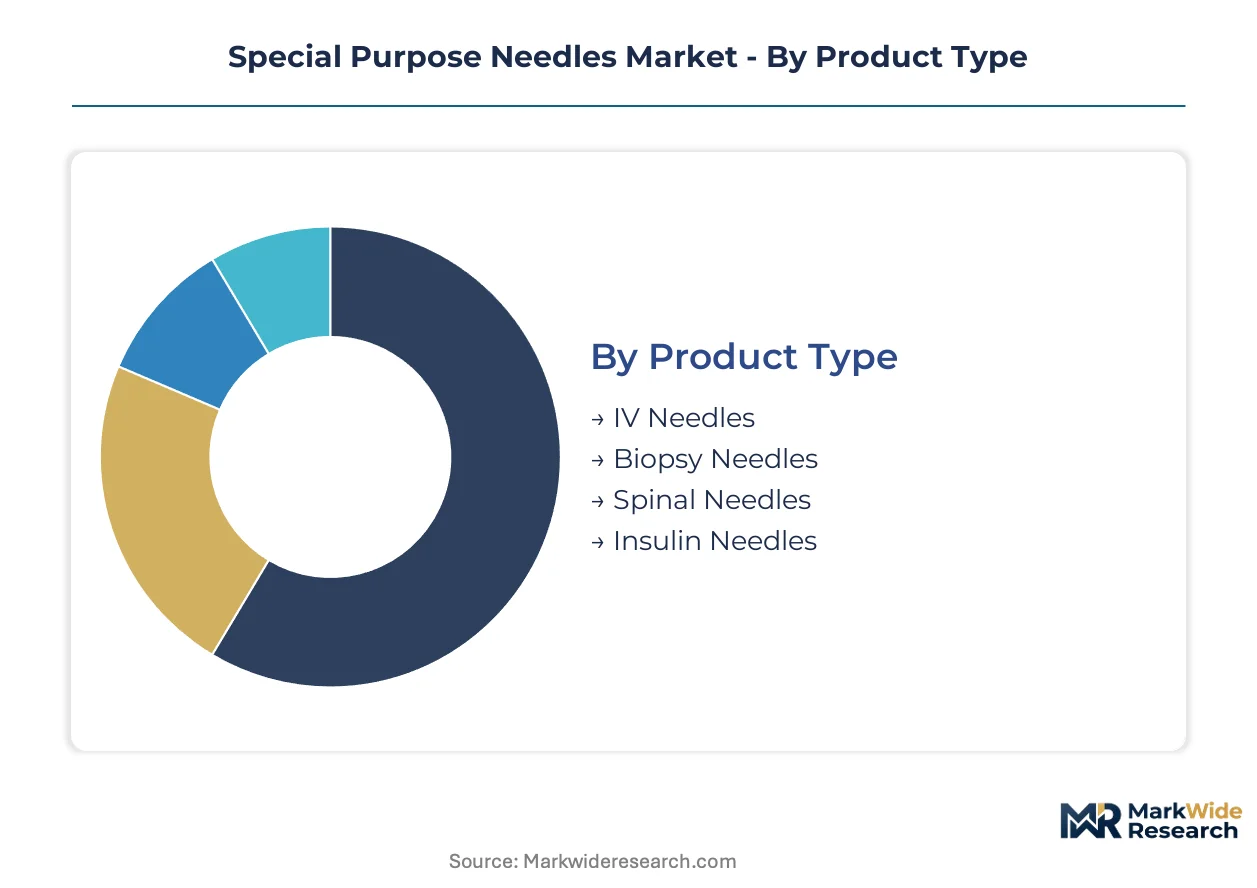
Special purpose needles require precise segmentation because regulatory pathways, reimbursement codes, and sterility standards diverge sharply across clinical applications. Manufacturers must align portfolio architecture with distinct FDA and EMA classification schemes that govern each product category.
Product Type:
FDA sharps safety regulations and EMA MDR compliance frameworks create divergent certification burdens across needle configurations.
- IV Needles:Stainless steel cannulas with standardized Luer lock interfaces dominate acute fluid administration. United States hospital systems drive replacement demand as safety-engineered designs displace legacy open-bore devices under OSHA Bloodborne Pathogens Standard enforcement.
- Biopsy Needles:Precision-ground cutting edges with coaxial or tandem configurations enable percutaneous tissue sampling. German oncology screening programs and Japanese academic medical centers concentrate demand for vacuum-assisted and core needle systems with integrated specimen collection chambers.
- Spinal Needles:Pencil-point or Quincke bevel geometries reduce post-dural puncture headache incidence in neuraxial anesthesia.
- Insulin Needles:Ultra-thin 31-32 gauge walls with micro-bevel tips minimize lipohypertrophy in chronic diabetes management.
IV needles handle the majority of throughput; insulin needles are expanding most quickly on share as homecare protocols proliferate.
Application:
Cost tier differentiation separates premium reimbursed procedures from commodity diagnostic workflows.
- Surgery:Sterile single-use needles with proprietary coating chemistries support intraoperative anesthesia and tissue manipulation. United States ambulatory surgery centers and German Klinikum networks concentrate procurement for spinal and regional block applications.
- Diagnostics:Biopsy and aspiration needles for histopathological analysis command premium pricing due to sterility assurance and tip geometry precision. Japanese cancer screening initiatives and São Paulo oncology networks drive volume for core needle and fine-needle aspiration systems.
- Blood Collection:Multi-sample needles with safety-engineered shields comply with FDA sharps injury prevention mandates.
- Pain Management:Epidural and nerve block needles for chronic pain intervention require specialized bevel configurations and depth marking accuracy.
Surgery captures the highest margin per procedure; diagnostics is climbing the fastest as early detection protocols expand across aging populations.
End User:
Procurement authority fragmentation reshapes channel economics across institutional and direct-to-patient pathways.
- Hospitals:Centralized supply chains with value-based purchasing agreements dominate high-volume safety-engineered needle procurement. United States health systems and German university hospitals lead conversion to retractable and shielded designs under sharps safety compliance deadlines.
- Clinics:Outpatient diagnostic and pain management facilities drive specialized needle demand with procedure-specific purchasing autonomy.
- Homecare:Patient-directed insulin and allergy injection supply acquisition bypasses traditional wholesale distribution.
- Research Laboratories:Preclinical and clinical trial needle specifications require custom manufacturing runs with enhanced traceability documentation.
Hospitals maintain the dominant procurement volume; homecare is gaining share fastest as chronic disease management decentralizes.
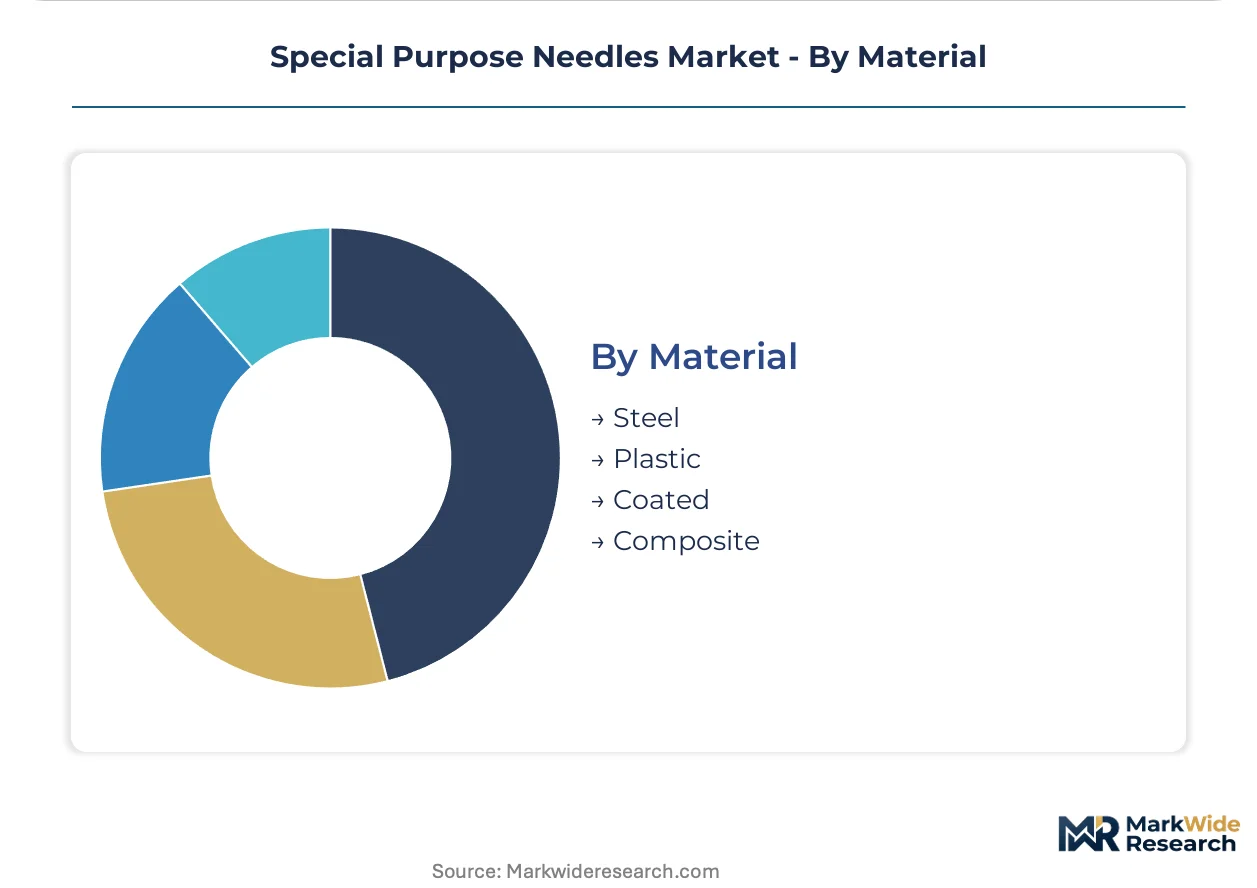
Material:
Supply concentration in German and Japanese metallurgical producers determines material cost stability and quality consistency.
- Steel:Surgical-grade stainless steel with controlled nickel and chromium content remains the baseline for penetration strength and biocompatibility. German ThyssenKrupp and Japanese Nippon Steel medical alloy divisions supply the majority of precision needle feedstock.
- Plastic:Engineering polymers in hub and safety mechanism construction reduce device weight and manufacturing complexity.
- Coated:Silicone-polymer hybrid and PTFE surface treatments reduce friction coefficients for spinal and biopsy applications.
- Composite:Metal-polymer hybrid structures balance rigidity and flexibility in specialized interventional radiology needles.
Steel accounts for the largest material throughput; coated variants are expanding most rapidly as lubricious surface chemistry advances displace conventional treatments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision alloy producers export medical-grade stainless steel feedstock to Japanese and American needle manufacturers, establishing a tripartite trade corridor that underpins global supply stability for hollow instrument fabrication.
United States
OSHA Bloodborne Pathogens Standard enforcement drives acute care systems toward retractable safety-engineered devices. FDA 510(k) clearance timelines for Class II needle systems average 180 days. Minneapolis and Cleveland manufacturing clusters concentrate automated grinding capacity for spinal and biopsy needle tip geometries.
Germany
EMA MDR Article 10 post-market surveillance obligations mandate electronic adverse event tracing for implantable needle categories. German Klinikum networks consolidate procurement for regional anesthesia portfolios through value-based purchasing agreements. Baden-Württemberg and North Rhine-Westphalia host precision metallurgical suppliers serving European device fabricators.
Japan
PMDA quality management system inspections enforce sterility assurance levels for spinal needle exports to Asian markets. METI industrial technology grants support silicone-polymer hybrid coating development for neuraxial applications. Osaka and Nagoya medical device districts anchor regional production for 31-32 gauge insulin needle volumes.
Brazil
ANVISA streamlining of sterile biopsy needle import registration accelerates oncology screening program expansion in São Paulo state. The national pharmaceutical regulator harmonizes technical documentation requirements with Mercosur standards. Minas Gerais diagnostic networks drive vacuum-assisted core needle adoption for percutaneous tissue sampling.
India
CDSCO medical device rules classify spinal and biopsy needles as Class C devices requiring import license or manufacturing license for domestic production. PLI scheme incentives attract contract manufacturers to Gujarat and Karnataka medical device parks. Maharashtra hospital procurement tenders specify ISO 7864 dimensional compliance for IV cannula safety mechanisms.
Special Purpose Needles Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory compliance capabilities, producing a tiered structure where scale-driven multinationals coexist with focused regional fabricators. The vendor base separates into three archetypes: integrated safety-device platforms, precision grinding specialists, and regional anesthesia portfolio players. Dominant competitive moves include backward integration into metallurgical feedstock sourcing and strategic partnerships for MDR compliance documentation systems.
Within the integrated platform tier, Becton, Dickinson and Company and Terumo Corporation exemplify archetypes of manufacturing scale and geographic dominance respectively. B. Braun Melsungen AG occupies a position among European precision specialists with sustained R&D intensity. These three anchors demonstrate how competitive positioning separates through captive alloy supply relationships, localized production footprints, and procedure-specific portfolio depth rather than undifferentiated volume competition.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Medtronic Plc |
| Boston Scientific Corporation |
| Terumo Corporation |
| B. Braun Melsungen AG |
| Smith's Medical |
| Stryker Corporation |
| Argon Medical Devices, Inc. |
| Cook Medical |
| Others |
Value Network & Pricing Analysis
FDA 510(k) clearance tiers and EMA MDR conformity classes gate both supplier qualification and price differentiation simultaneously, forcing manufacturers to embed certification costs into tiered product architectures while buyers sort across safety-engineered and legacy device categories based on institutional risk tolerance.
Pricing Analysis
Current-generation safety-engineered needles with retractable or shielded mechanisms command substantial premiums over prior-generation open-bore designs, while next-generation connected devices with RFID traceability remain in pilot pricing phases. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance tier, ISO 7864 dimensional precision, and after-sales service bundling. Cost compression in standard-grade IV cannulas is intensifying because German and Japanese metallurgical feedstock costs fluctuate with nickel mining output. Ambulatory surgery centers exhibit highest price sensitivity due to procedure-volume economics, while academic medical centers prioritize clinical outcome metrics over unit cost.
Supply Chain Analysis
Precision grinding technician apprenticeship pipelines in the US Midwest constitute a chokepoint constraining output scaling for spinal and biopsy needle tip geometries. German ThyssenKrupp and Japanese Nippon Steel medical alloy divisions anchor supply for surgical-grade stainless steel feedstock, with polymer composite hubs sourced from Chinese engineering plastics specialists. Single-source vulnerability in metallurgical supply creates exposure to Indonesian and Philippine nickel export disruptions. Distribution runs through hospital GPO contracts, specialized clinical distributors for interventional radiology suites, and direct-to-patient e-commerce channels for homecare injection supplies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Special purpose needles demand is recovering cyclically as deferred elective procedures from acute care capacity constraints return to scheduling pipelines, with spinal and regional anesthesia applications leading the rebound.
For Market Incumbents: Consolidate manufacturing scale through backward integration into metallurgical feedstock sourcing and captive precision grinding capacity in Baden-Württemberg or Osaka medical device districts. Polymer composite substitution in biopsy applications threatens traditional metal needle share; defend through sustained R&D intensity in silicone-polymer hybrid coating formulations that reduce friction coefficients below polytetrafluoroethylene baselines. For New Entrants and Emerging Players: Differentiate on MDR compliance documentation services for mid-tier European hospitals struggling with Article 10 post-market surveillance obligations. Brazilian ANVISA streamlining of sterile biopsy needle import registration presents the most penetrable geographic entry point, particularly for vacuum-assisted core needle systems serving São Paulo oncology networks. Partner with regional distributors possessing clinical application expertise rather than broad-line medical-surgical dealers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across connected device convergence plays requiring RFID integration and real-time inventory management software development. Long-term viability favors platforms with hospital system partnership depth and procedure-specific procurement committee relationships. Watch for inflection signals in homecare direct-to-patient channel share capture, as chronic disease management decentralization accelerates insulin needle volume growth outside traditional wholesale distribution.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates market access for safety-engineered retractable designs under OSHA compliance deadlines. |
| CE Marking Pathway | Enables EEA distribution while MDR Article 10 surveillance obligations reshape documentation requirements. |
| Hospital System Partnership | Secures value-based purchasing agreements with academic medical centers leading procurement decentralization. |
| Software Companion Development | Supports connected needle platforms with RFID tracking for real-time inventory and compliance documentation. |
| Reimbursement Strategy | Aligns portfolio investments with evolving CMS codes for minimally invasive and homecare delivery models. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EMA MDR technical documentation, and hospital GPO contract awards preceded structured interviews with hospital purchasing committee chairs, biomedical engineers, interventional radiology department heads, and GPO contracts managers. Secondary validation drew from ISO 7864 and ISO 9626 standards documentation, CMS reimbursement code updates, and customs records of medical-grade stainless steel feedstock trade flows. Bottom-up demand modeling across procedure volumes triangulated with top-down manufacturer capacity assessments.
Variance decomposition across product type, application, end user, and material segmentation dimensions structured the analytical framework over the projection horizon. CAGRs were derived from procedure volume growth trajectories, replacement cycle acceleration under sharps safety mandates, and site-of-care migration patterns. Forecast inputs incorporated diabetes prevalence projections for insulin needle demand, oncology screening program expansion for biopsy systems, and EMA MDR certification timeline delays for product launch pacing.
Material uncertainties — nickel price volatility, precision grinding technician availability, and polymer composite substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement consistency and reimbursement stability. Practitioners should keep alternative scenarios live as EMA MDR implementation maturity and homecare channel economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Homecare Surgical Drains Market
Surgical Instruments
Needle Holders Market
Surgical Instruments
Medical Penlights Market
Surgical Instruments
Ultrasonic Scalpel Market
Surgical Instruments
Cardiac Surgery Instruments Market
Surgical Instruments
Disposable Laparoscopic Instruments Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
US Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Global Plastic Surgery Instruments Market
Surgical Instruments
Europe Minimally Invasive Surgery Market
Surgical Instruments
Tonsil and Adenoid Removal Products Market
Surgical Instruments
Endoluminal Suturing Devices Market
Surgical Instruments
Laparotomy Sponges Market
Surgical Instruments
Global Bipolar Electrosurgical Devices Market
Surgical Instruments
Cheilectomy Market
Surgical Instruments
Global Urology Surgical Instruments Market