
 Italy General Surgical Devices Market | 2026-2036
Italy General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Italy General Surgical Devices Market Foresight
Polymer composites are displacing stainless steel in retractor and forceps handles, broadening design flexibility while reducing sterilization-cycle fatigue. Medtronic PLC leverages its Galway manufacturing network to supply Italian distributors with electrosurgical generators. Stryker Corporation anchors its southern European position through specialized sales teams covering Rome and Naples territories. Smith & Nephew plc differentiates via advanced wound closure portfolios tailored to Italian public procurement frameworks.
General surgical devices encompass manually operated and powered instruments designed for tissue manipulation, dissection, cauterization, and wound closure in operative settings, typically manufactured from medical-grade stainless steel, titanium, or polymer composites with tolerances reaching 0.01 millimeters for microsurgical applications. Electrosurgical devices and laparoscopic devices command expanding share as Italian hospitals prioritize minimally invasive procedure volumes and reduced length-of-stay metrics. Sutures maintain stable revenue contribution through recurring consumption patterns in public hospital networks, while surgical instruments face margin compression from parallel import channels.
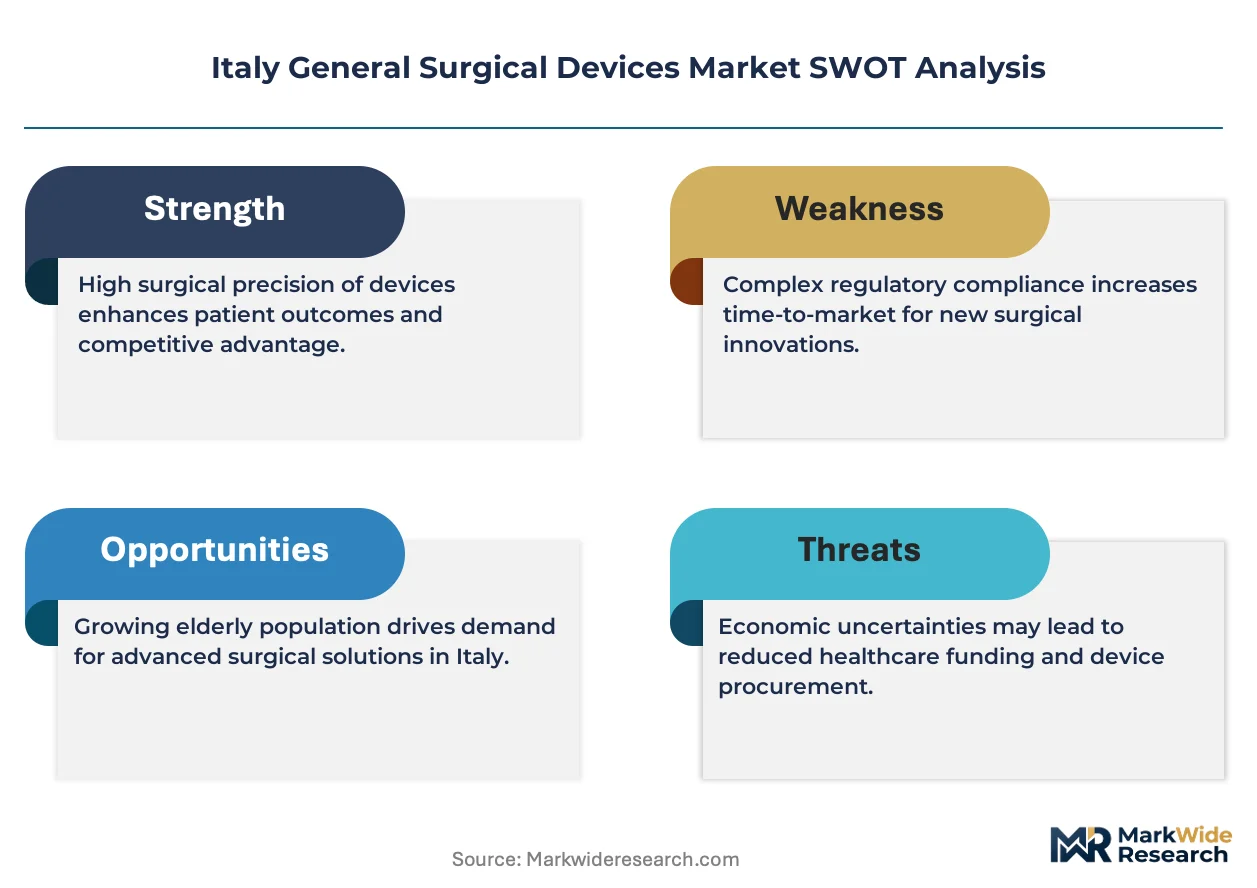
Italy's medical device sector operates under EU MDR enforcement through notified bodies accredited by the Ministry of Health, with additional scrutiny from AIFA on devices incorporating drug-device combinations. The EU AI Act introduces classification requirements for surgical robotics incorporating machine-learning guidance systems, affecting technology roadmaps for vendors deploying robotic surgery platforms. Stakeholders must monitor notified body capacity constraints and regional health authority tender calendars to secure placement in Lombardy and Veneto procurement cycles.
Market Dynamics
Italy's general surgical devices sector is experiencing structural pressure from EU MDR compliance timelines, which are compressing notified body capacity and forcing manufacturers to accelerate technical documentation updates ahead of certificate expiration dates.
Growth Catalysts
- Ambulatory surgical center expansion:Day-surgery facilities across Lombardy and Veneto are scaling disposable instrument procurement to align with regional efficiency targets for same-day discharge protocols.
- EU MDR alignment:The Ministry of Health's updated vigilance requirements are accelerating quality system investments among domestic distributors seeking notified body certification renewal.
- Polymer composite adoption:Handle components in retractors and forceps are transitioning from stainless steel to medical-grade polymers, reducing sterilization-cycle fatigue and enabling ergonomic customization.
Market Restraints
- Notified body capacity constraints:Limited accredited bodies under EU MDR are extending certification timelines for Class IIa and IIb devices, delaying market entry for updated product lines.
- Parallel import channels:Gray-market instrument flows from Eastern European distributors are compressing margins on standardized surgical tools in public hospital networks.
- Titanium raw material volatility:Price fluctuations in aerospace-grade titanium feedstock are pressuring cost structures for microsurgical instrument manufacturers serving Milan's premium hospital segment.
Strategic Opportunities
- EU AI Act compliance services:Surgical robotics vendors can capture value by bundling machine-learning classification documentation with platform sales to hospitals navigating the new regulatory framework.
- Southern Italy penetration:Underdeveloped procurement infrastructure in Calabria and Sicily creates white space for specialized sales coverage and distributor partnerships.
- Wound closure innovation:Advanced suture portfolios tailored to AIFA reimbursement codes offer differentiation in public tender processes across the national health service.
Industry Challenges
- Biocompatibility testing bottlenecks:Extended turnaround times at polymer testing laboratories are delaying product validation cycles for composite-handle instruments.
- Legacy electrosurgical integration:New generator platforms face compatibility friction with installed base accessories in Rome and Naples hospital systems, complicating upgrade pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy General Surgical Devices Market |
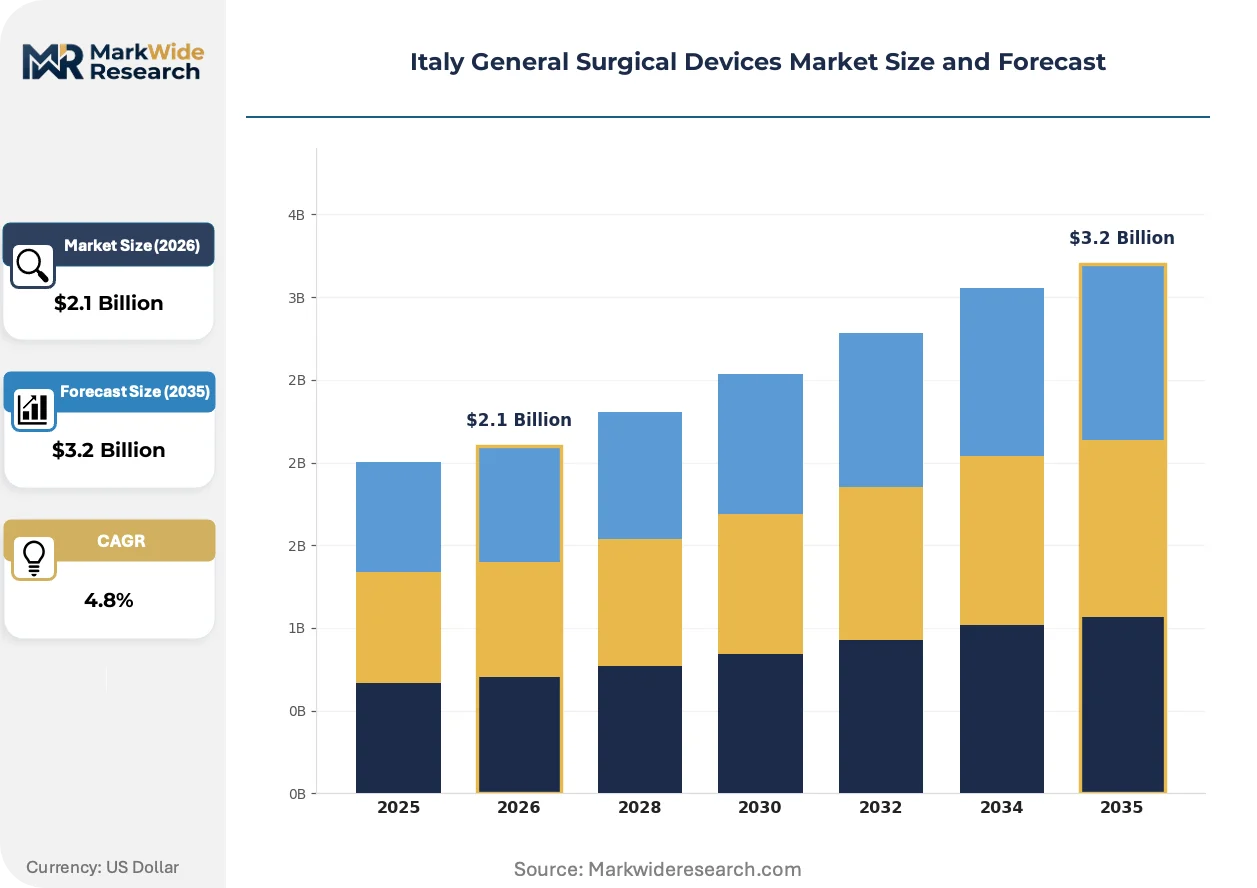
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Sutures, Electrosurgical Devices, Laparoscopic Devices End User: Hospitals, Clinics, Ambulatory Surgical Centers, Specialty Clinics Technology: Minimally Invasive, Robotic Surgery, Traditional Surgical Techniques, Laser Surgery Application: General Surgery, Cardiovascular Surgery, Orthopedic Surgery, Neurological Surgery |
| Companies Covered | Medtronic PLC, GE Healthcare, Abbott Laboratories, Siemens AG, Olympus Corporation, Stryker Corporation, Smith & Nephew plc, Zimmer Biomet, Koninklijke Philips NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy General Surgical Devices Market Shifts & Advancements
Electrosurgical and laparoscopic platforms are reshaping procedural economics in Italian hospitals, with device selection increasingly tied to length-of-stay reduction targets and same-day surgery expansion mandates from regional health authorities.
Radiofrequency-based vessel sealing is consolidating position in open and laparoscopic procedures across Lombardy's hospital network. General surgery departments at Milan's Policlinico and Humanitas facilities are adopting these platforms for colorectal and gynecologic interventions. The technology is consolidating market share previously held by mechanical clip appliers and suture ligation, compressing supplier rosters to vendors with integrated generator-instrument ecosystems.
EU MDR Article 117 implementation is tightening scrutiny of drug-device combinations involving antibiotic-coated sutures and hemostatic agents. AIFA now requires additional clinical evidence submissions for products crossing the medical device-pharmaceutical boundary. Wound closure manufacturers are responding by segregating regulatory pathways and establishing dedicated MDR compliance teams to manage notified body interactions.
Regional tender aggregation is consolidating purchasing authority across Lombardy and Veneto health authorities, shifting negotiation leverage toward volume-scale suppliers. Multi-hospital consortia in Brescia and Verona are unbundling service contracts from device procurement, forcing vendors to price instruments and maintenance separately. This pattern is most visible in electrosurgical platform acquisitions, where five-year total cost of ownership models are displacing upfront capital purchase structures.
Italy General Surgical Devices Market Segmentation
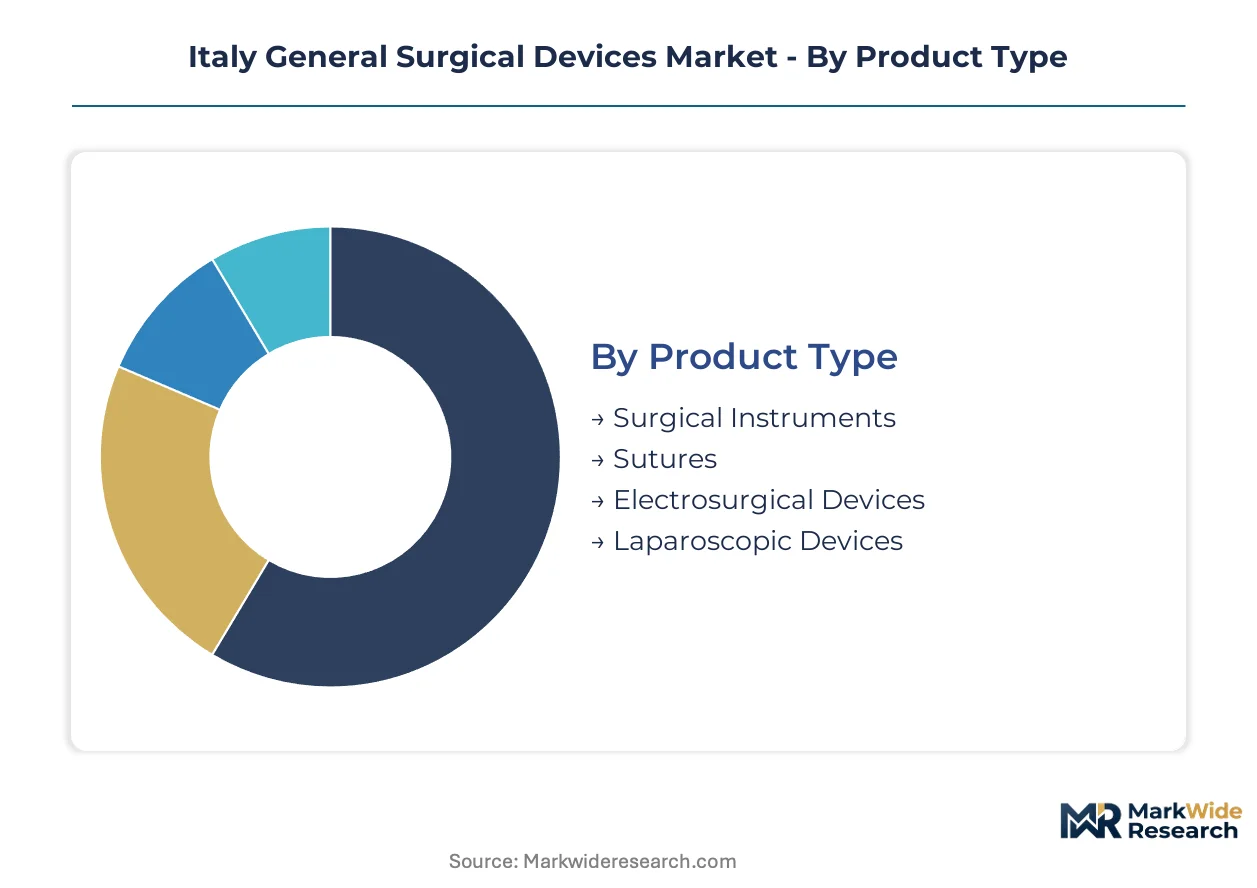
Device classification in Italy's surgical market dictates procurement pathways, reimbursement eligibility, and regulatory scrutiny intensity. Segment boundaries increasingly blur as electrosurgical and laparoscopic platforms converge under minimally invasive protocols, forcing vendors to map capabilities across multiple taxonomies simultaneously.
Product Type:
Capital intensity varies sharply across product categories, with electrosurgical generators and laparoscopic towers requiring substantial upfront investment while consumables operate on recurring replenishment models.
- Surgical Instruments:Manually operated tools manufactured from medical-grade stainless steel, titanium, or polymer composites with tolerances reaching 0.01 millimeters for microsurgical applications. Milan's Policlinico and Humanitas networks drive premium-grade forceps and retractor procurement, though parallel import channels from Eastern European distributors compress margins on standardized catalog items.
- Electrosurgical Devices:Radiofrequency-based generators and active electrode systems for tissue cutting and coagulation. Lombardy hospital consortia in Brescia and Verona are unbundling service contracts from device procurement, forcing vendors to price platforms and maintenance separately under five-year total cost of ownership models.
- Sutures:Absorbable and non-absorbable wound closure materials with recurring consumption patterns in public hospital networks. AIFA reimbursement codes govern pricing tiers for antibiotic-coated variants crossing the drug-device boundary under EU MDR Article 117.
- Laparoscopic Devices:Trocars, insufflators, and articulated instruments for minimally invasive access. Day-surgery facilities across Veneto are scaling disposable instrument kit procurement to align with same-day discharge efficiency targets.
Electrosurgical devices absorb the bulk of installed capacity; laparoscopic devices are expanding most quickly as regional health authorities mandate length-of-stay reductions.
End User:
Procurement authority concentrates differently across customer types, with multi-hospital consortia wielding volume leverage while ambulatory centers prioritize disposable workflows over capital equipment.
- Hospitals:Acute-care institutions with centralized purchasing through regional health authority tender calendars. Rome and Naples hospital systems present compatibility friction for new electrosurgical generator platforms against installed base accessories.
- Ambulatory Surgical Centers:Day-surgery facilities scaling disposable instrument procurement. Lombardy and Veneto regional efficiency targets for same-day discharge protocols are accelerating kit-based purchasing models.
- Clinics:Smaller-volume settings with limited sterilization infrastructure. Polymer composite handle instruments reduce cycle fatigue constraints in these environments.
- Specialty Clinics:Focused providers in ophthalmology, dermatology, and dental surgery with specialized instrument requirements. Southern Italy's underdeveloped procurement infrastructure in Calabria and Sicily creates white space for distributor partnerships.
Hospitals dominate current revenue contribution; ambulatory surgical centers are climbing the fastest as regional authorities shift procedures to lower-cost settings.
Technology:
Regulatory burden escalates with system complexity, from straightforward mechanical instruments to AI-enabled robotic platforms facing EU AI Act classification requirements.
- Minimally Invasive:Laparoscopic and endoscopic techniques reducing tissue trauma and recovery time. Italian hospitals prioritize these procedure volumes under length-of-stay reduction mandates from regional health authorities.
- Robotic Surgery:Machine-learning guidance systems requiring notified body scrutiny under EU AI Act implementation. Vendors must bundle classification documentation with platform sales to hospitals navigating the new framework.
- Traditional Surgical Techniques:Open procedures with conventional manual instruments. Stable demand persists for emergency and trauma applications where rapid access supersedes minimally invasive constraints.
- Laser Surgery:Photonic tissue ablation and cutting systems with specialized applications in ophthalmology and dermatology. Limited penetration in general surgery due to capital cost and training requirements.
Traditional techniques retain the largest installed base; robotic surgery is gaining share fastest as EU MDR alignment accelerates quality system investments among domestic distributors.
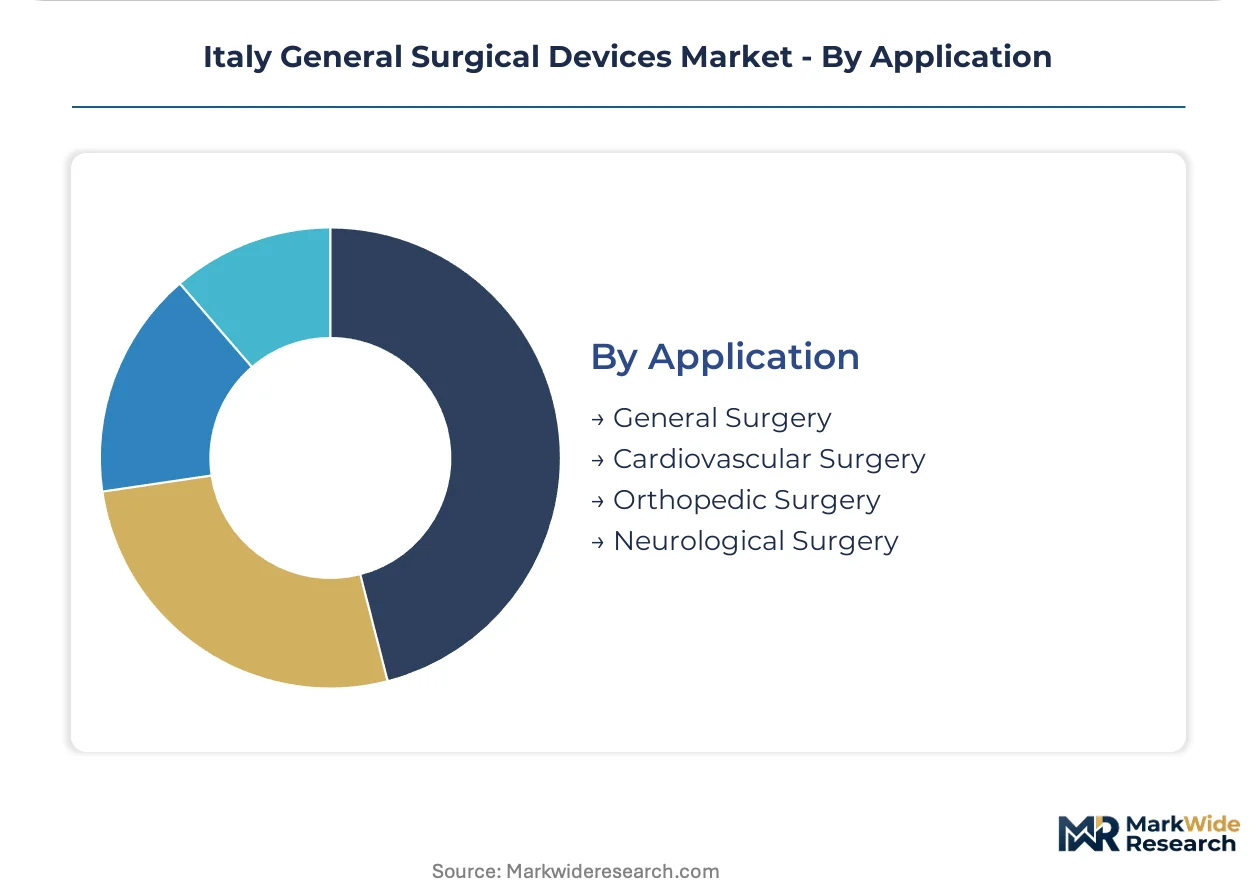
Application:
Procedure volume and reimbursement rates diverge across surgical specialties, with cardiovascular and orthopedic interventions commanding premium device specifications.
- General Surgery:Abdominal, gastrointestinal, and soft tissue procedures representing the core volume base. Colorectal interventions at Milan facilities are consolidating around radiofrequency vessel sealing platforms.
- Orthopedic Surgery:Bone and joint procedures with specialized instrument sets and power tools. Titanium raw material volatility in aerospace-grade feedstock pressures cost structures for microsurgical instrument manufacturers.
- Cardiovascular Surgery:Cardiac and vascular interventions with highest precision requirements. EU MDR biocompatibility testing bottlenecks at polymer laboratories delay validation cycles for composite-handle instruments.
- Neurological Surgery:Cranial and spinal procedures with microsurgical tolerance demands. Limited addressable volume concentrates in Milan's premium hospital segment.
General surgery absorbs the bulk of procedure volume; orthopedic surgery is expanding most quickly as Italy's aging population drives joint replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian demand concentrates in Lombardy's hospital network, where Milan's premium facilities drive electrosurgical adoption. Regional health authorities in Veneto and Lazio shape procurement through consolidated tender calendars. Southern Italy presents underdeveloped infrastructure with white-space potential for specialized distribution.
Lombardy
Milan's Policlinico and Humanitas networks anchor premium-grade forceps and retractor procurement. The region operates under EU MDR alignment through Ministry of Health-accredited notified bodies. Brescia and Verona hospital consortia are unbundling service contracts from device procurement, forcing five-year total cost of ownership pricing models.
Veneto
Day-surgery facilities across the region scale disposable instrument kit procurement to meet same-day discharge efficiency targets. Regional health authority tender calendars govern multi-hospital purchasing authority. Verona's procurement consortia are separating maintenance contracts from capital equipment acquisitions.
Lazio
Rome's hospital systems present compatibility friction for new electrosurgical generator platforms against installed base accessories. The Ministry of Health's updated vigilance requirements accelerate quality system investments among domestic distributors. Central Italy procurement infrastructure concentrates purchasing decisions through regional health authority frameworks.
Campania
Naples territories anchor Stryker Corporation's specialized sales coverage for southern European positioning. Underdeveloped procurement infrastructure creates distributor partnership opportunities. Regional efficiency targets lag northern counterparts, extending traditional surgical technique dominance.
Sicily
Calabria and Sicily's procurement gaps create white space for specialized sales coverage expansion. Limited sterilization infrastructure elevates demand for polymer composite handle instruments reducing cycle fatigue. Southern regional health authorities are consolidating tender processes to match northern efficiency mandates.
Italy General Surgical Devices Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors navigate EU MDR compliance timelines and notified body capacity constraints. The vendor base organizes around three tiers: multinational platform suppliers with integrated generator-instrument ecosystems, mid-scale specialists in wound closure and polymer composites, and regional distributors managing parallel import channels. Competitive positioning hinges on bundling machine-learning classification documentation with platform sales, securing placement in Lombardy and Veneto procurement cycles, and penetrating underdeveloped southern territories through distributor partnerships.
Among Ireland-anchored multinationals, Medtronic PLC leverages Galway manufacturing networks to supply Italian distributors with electrosurgical generators. Stryker Corporation occupies a position covering Rome and Naples territories through specialized sales teams. Smith & Nephew plc exemplifies the wound closure differentiation archetype, tailoring advanced portfolios to Italian public procurement frameworks and AIFA reimbursement codes. These three represent distinct competitive vectors: manufacturing scale, geographic coverage depth, and regulatory-tailored portfolio design.
| Leading Market Players |
|---|
| Medtronic PLC |
| GE Healthcare |
| Abbott Laboratories |
| Siemens AG |
| Olympus Corporation |
| Stryker Corporation |
| Smith & Nephew plc |
| Zimmer Biomet |
| Koninklijke Philips NV |
| Others |
Supply & Pricing Matrix
Regional health authority consortia in Lombardy and Veneto concentrate procurement leverage, forcing vendors toward five-year total cost of ownership models that unbundle capital equipment from service contracts. This buyer concentration compresses upfront pricing on electrosurgical generators while elevating recurring revenue streams through maintenance and disposable instrument kits.
Pricing Analysis
Volume-driven consumables generate thinner margins than capital-intensive electrosurgical platforms, though the latter face elongating sales cycles due to EU MDR certification requirements. Pricing stratifies across premium, standard, and economy tiers based on notified body certification tier and sterilization-cycle durability ratings. Cost compression in standardized surgical instruments runs through parallel import channels from Eastern European distributors. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement rates, while Milan's premium hospital networks prioritize performance specifications over unit economics.
Supply Chain Analysis
Freight cost volatility from Ireland and Germany shapes landed cost structures for electrosurgical generators and polymer composite feedstocks. Manufacturing concentrates in Ireland, Germany, and Switzerland for high-precision instruments, with sterilization consumables sourcing from Italy's domestic polymer processors. Supply chain risk centers on single-source vulnerability for aerospace-grade titanium microsurgical components. Distribution runs through specialized medical device distributors holding Ministry of Health import licenses, with regional health authority tender calendars governing hospital system access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance timelines function as a cost-of-compliance moat, with notified body capacity constraints extending certification timelines and elevating quality system investments that disadvantage undercapitalized competitors.
For Market Incumbents: Extend service contract bundling to capture recurring revenue streams as regional consortia unbundle procurement, while accelerating polymer composite handle validation to outpace biocompatibility testing bottlenecks. Defensive positioning requires deepening backward integration into polymer feedstock supply to offset raw material volatility and parallel import pressure on standardized instruments. For New Entrants and Emerging Players: Specialized distributors in Calabria and Sicily represent the most penetrable channel infrastructure, given underdeveloped procurement systems and limited sterilization capacity elevating demand for disposable workflows. A go-to-market angle anchored in polymer composite instruments reduces cycle fatigue constraints for clinics lacking central sterilization departments. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale wound closure specialists with established AIFA reimbursement code alignment in southern Italian territories. Long-term viability hinges on EU AI Act classification capabilities for surgical robotics platforms. The signal to watch is notified body accreditation expansion announcements from Ministry of Health authorities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation investments secure certificate renewal ahead of expiration deadlines. |
| Hospital System Partnership | Five-year total cost of ownership contracts with Lombardy consortia lock out parallel import competitors. |
| Software Companion Development | Machine-learning classification documentation bundles address EU AI Act compliance for robotic platforms. |
| Reimbursement Strategy | AIFA code alignment for antibiotic-coated sutures differentiates wound closure portfolios in public tenders. |
| Geographic Expansion | Distributor partnerships in Sicily and Calabria capture white-space demand from consolidating regional health authorities. |
Research Methodology
Document review covered EU MDR implementation guidance from notified bodies, AIFA reimbursement code databases, and regional health authority tender calendars, complemented by interviews with hospital procurement committee members, biomedical engineers, GPO contracts managers, and specialized medical device distributors. Secondary validation drew from Ministry of Health vigilance reports, customs import records, and polymer testing laboratory turnaround disclosures. Bottom-up instrument shipment estimates and top-down healthcare expenditure allocations were triangulated to produce segment-level outputs.
Model outputs span product type, end user, technology, and application dimensions across the projection horizon. CAGRs were derived from procedure volume trajectories, reimbursement rate assumptions, and EU MDR compliance cost pass-through estimates. Industry-specific inputs included regional health authority same-day discharge efficiency targets and polymer composite adoption curves in sterilization-cycle-sensitive settings.
Caveats apply where notified body capacity constraints, titanium feedstock price volatility, or parallel import channel expansion could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Medical Penlights Market
Surgical Instruments
US Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
Lumpectomy Market
Surgical Instruments
Colorectal Procedure Market
Surgical Instruments
Surgical Stapling Devices Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Electrosurgery Market
Surgical Instruments
Dental Surgical Microscopes Market
Surgical Instruments
Global Surgical Scissors Market
Surgical Instruments
Adult Cardiovascular Surgical Instruments Package Market
Surgical Instruments
Global Dental Surgical Instruments Market
Surgical Instruments
Cryosurgery Market
Surgical Instruments
Global Surgical Instruments Market
Surgical Instruments
Absorbable PGA Surgical Sutures Market
Surgical Instruments
Surgical Clips Market