
 Absorbable PGA Surgical Sutures Market | 2026-2036
Absorbable PGA Surgical Sutures Market Size, Share, and Industry Trends Forecast 2026-2036
Absorbable PGA Surgical Sutures Market Insights
Maintenance and recalibration service contracts for suturing platforms is repositioning vendor relationships from transactional supply to multi-year partnerships. Johnson & Johnson (Ethicon) leverages its vertically integrated polymer supply chain to control raw material quality for PGA filament production. Medtronic anchors its position through deep hospital GPO relationships and dedicated surgical training infrastructure. B. Braun Melsungen AG differentiates via European manufacturing scale and REACH-compliant coating chemistry.
Absorbable PGA surgical sutures consist of braided or monofilament polyglycolic acid filaments, typically sized USP 5-0 to 2-0, designed for tensile strength retention over 14-21 days followed by hydrolytic absorption within 60-90 days. These devices primarily serve wound closure applications where elimination of foreign body removal reduces operative burden and infection risk. Multifilament braids occupy the largest volume share due to superior knot security and handling properties in general surgery. Barbed configurations represent the fastest-expanding product category as knotless designs accelerate laparoscopic closure times and reduce operative technical demand. Coated variants command premium positioning where silicone or polymer coatings minimize tissue drag in cardiovascular and orthopedic procedures.
FDA 510(k) premarket notification and EU MDR Class IIa certification requirements govern sterility assurance, biocompatibility testing per ISO 10993, and clinical performance documentation for PGA suture market access. The EPA regulates glycolide monomer waste streams from polymerization facilities, while ISO 13485 quality management standards shape manufacturing audit protocols across supplier bases. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA guidance on absorbable polymer degradation profile standardization as these frameworks will determine competitive qualification timelines and capital deployment priorities.
Market Dynamics
Barbed knotless suture configurations are compressing operative time metrics in laparoscopic procedures, forcing manufacturers to reallocate R&D budgets toward specialized geometries while maintaining core braided filament portfolios for open surgery.
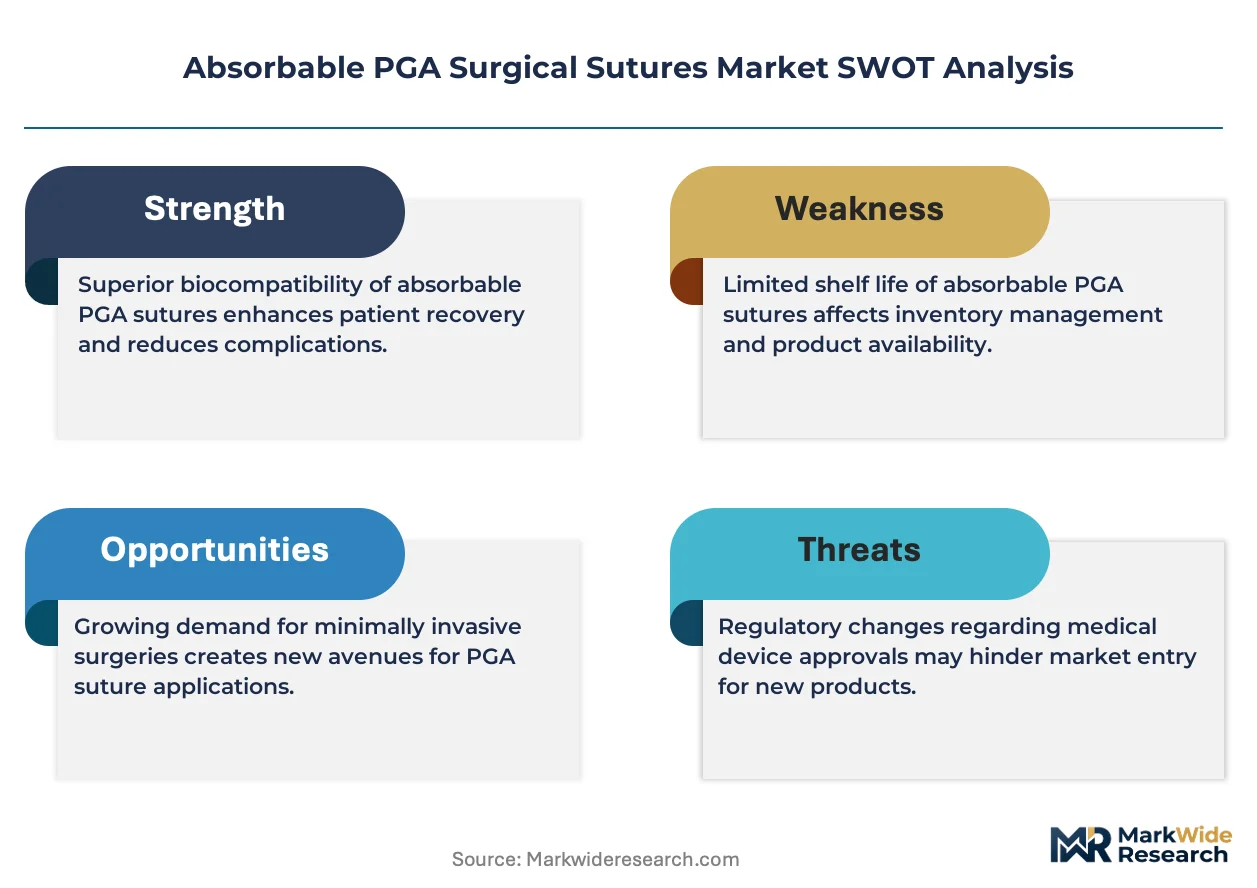
Growth Catalysts
- EU MDR Class IIa certification pathways:Harmonized sterility benchmarks across member states reduce redundant testing burdens for manufacturers with established notified body relationships.
- Ambulatory surgical center volume expansion:Same-day discharge protocols in the United States drive demand for absorbable closure devices that eliminate follow-up removal visits.
- Polymer coating chemistry advances:Silicone and copolymer surface treatments reduce tissue drag coefficients in cardiovascular applications where precision handling commands premium positioning.
Market Restraints
- Glycolide monomer input cost volatility:Petroleum-derived feedstock exposure creates margin pressure during energy price spikes, particularly for non-integrated manufacturers.
- Notified body capacity constraints in Europe:EU MDR transition backlogs extend certification timelines for novel suture designs, delaying market entry.
- Synthetic absorbable polymer substitution:Polylactic acid and polydioxanone alternatives compete for wound closure applications with comparable absorption profiles.
Strategic Opportunities
- Japanese orthopedic procedure expansion:Aging demographics and joint replacement volume growth create unmet demand for coated PGA variants in tendon and ligament repair.
- REACH-compliant coating chemistry:European environmental mandates favor manufacturers with solvent-free polymer deposition processes.
- Remote surgical training platforms:Virtual reality suturing simulation expands addressable markets for device vendors with educational infrastructure investments.
Industry Challenges
- ISO 10993 biocompatibility testing timelines:Extended cytotoxicity and sensitization study durations compress product launch windows against competitive filings.
- Legacy ERP integration with track-and-trace systems:UDI compliance requirements force mid-tier manufacturers into capital-intensive software migrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absorbable PGA Surgical Sutures Market |
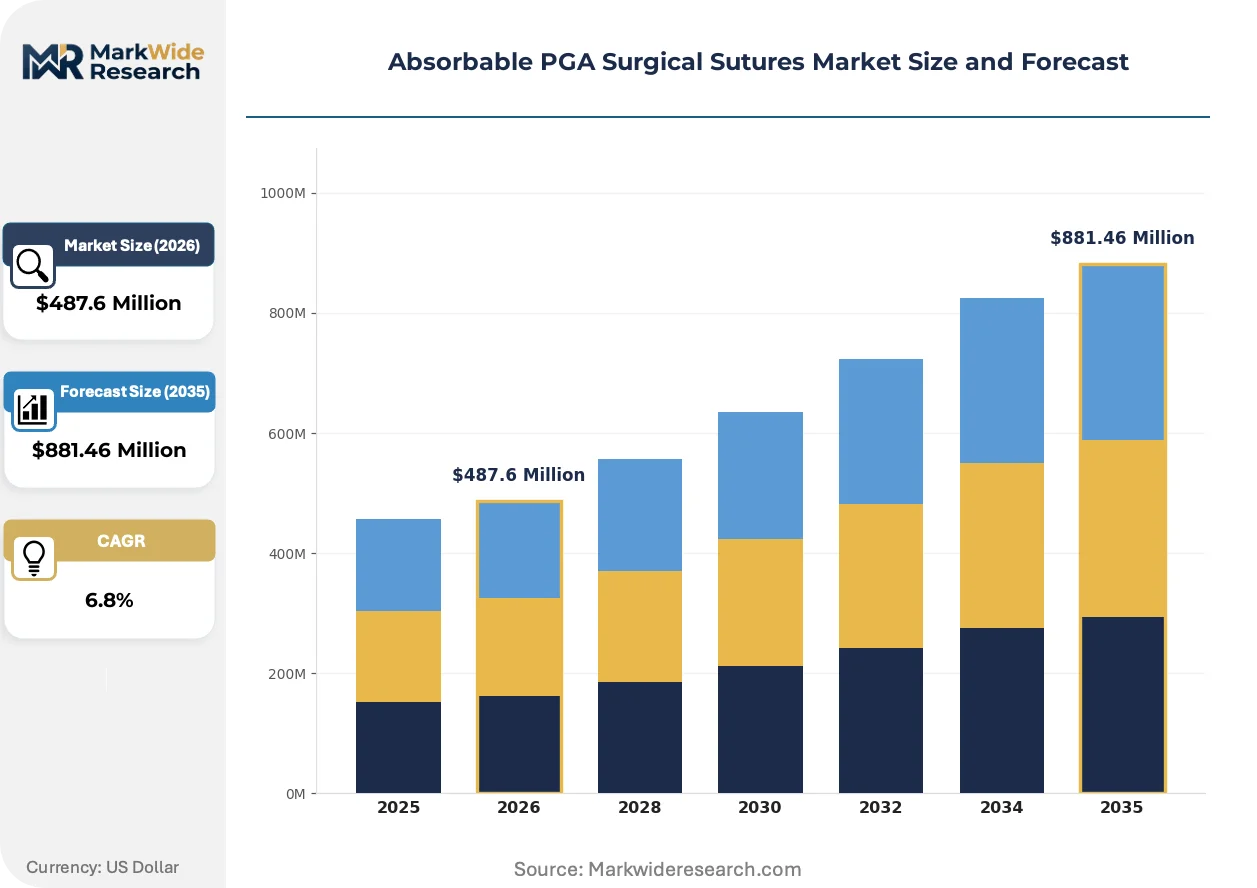
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monofilament, Multifilament, Barbed, Coated, Uncoated Application: General Surgery, Orthopedic Surgery, Cardiovascular Procedures, Gynecological Surgery, Urological Procedures End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialty Care Centers, Research Institutes Packaging Type: Sterile Blister Packs, Vials, Pouches, Tubes, Peelable Foil Packs |
| Companies Covered | Johnson & Johnson (Ethicon), Medtronic, B. Braun Melsungen AG, Smith+Nephew, Boston Scientific, DemeTECH Corporation, Teleflex, Advanced Medical Solutions Group, Healthium MedTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absorbable PGA Surgical Sutures Market Trends and Innovations
Manufacturing automation and polymer science advances are compressing cost structures while regulatory harmonization efforts reshape qualification requirements. Three forces dominate current strategic planning.
Barbed monofilament configurations are consolidating market share in minimally invasive closure applications. Laparoscopic surgical suites in German university hospitals have standardized knotless designs for port-site closure, reducing operative technical demand. This geometry is consolidating procurement specifications across GPO contract renewals.
EU MDR notified body capacity shortages are extending certification timelines for absorbable polymer devices. Manufacturers now front-load clinical performance documentation to preempt technical file queries. German and French regulatory consultants report 40% longer review cycles compared to prior Medical Device Directive frameworks.
Hospital supply chain directors are unbundling maintenance contracts from device procurement. Multi-year service agreements for suturing platform calibration now route through separate capital expenditure channels. This bifurcation is most visible in United States integrated delivery networks consolidating vendor relationships.
Absorbable PGA Surgical Sutures Market Segmentation
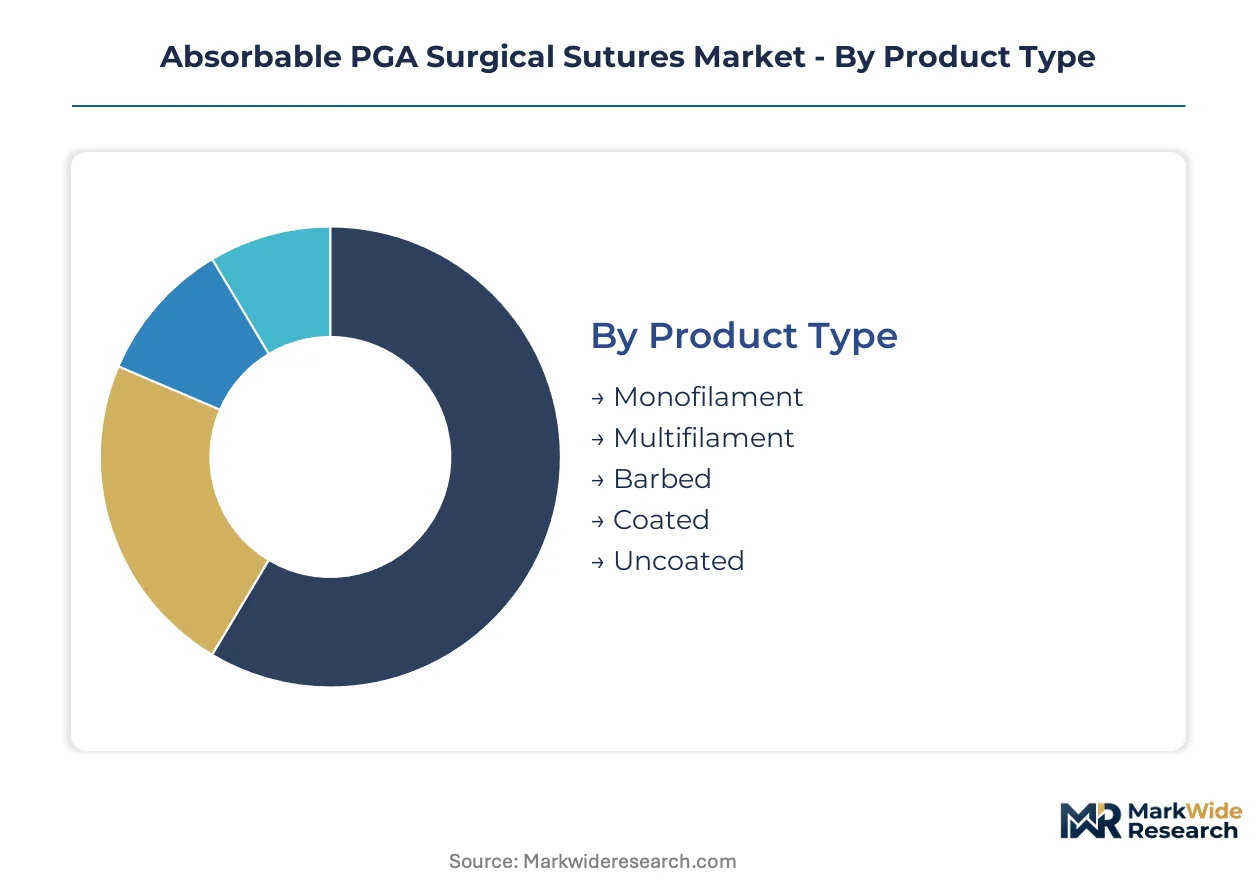
Segmentation in absorbable PGA surgical sutures reveals how regulatory pathways, procedural settings, and packaging standards fragment procurement specifications. Manufacturers must align filament configurations with specific clinical workflows and sterility assurance levels to secure contract placement across diverse healthcare delivery environments.
Product Type:
FDA 510(k) clearance and EU MDR Class IIa certification requirements vary sharply across filament architectures, with barbed and coated variants demanding extended biocompatibility documentation compared to conventional braids.
- Multifilament:Braided polyglycolic acid filaments deliver superior knot security and handling characteristics for open surgical procedures. General surgery departments in German university hospitals specify these configurations for abdominal wall closure where tensile strength retention over 14-21 days matches healing timelines.
- Barbed:Knotless monofilament designs with unidirectional or bidirectional barbs eliminate the need for traditional knot-tying. Laparoscopic surgical suites in the United States have standardized these for port-site closure, compressing operative time metrics and reducing technical demand on surgical residents.
- Monofilament:Single-strand PGA construction offers reduced tissue drag and lower infection risk profile compared to braided alternatives.
- Coated:Silicone or copolymer surface treatments minimize tissue friction in cardiovascular applications where precision handling commands premium positioning.
- Uncoated:Base filament configurations serve cost-sensitive procurement channels and research applications where coating chemistry adds unnecessary expense.
Multifilament sits at the top of the volume ranking, with Barbed climbing the fastest.
Application:
Procedure-specific reimbursement codes and surgical volume trajectories determine which application segments absorb R&D investment and sales force deployment.
- General Surgery:Abdominal, thoracic, and soft tissue closure procedures consume the largest filament volumes. Hospital procurement committees in Japan prioritize absorbable sutures for cholecystectomy and appendectomy cases where same-day discharge protocols eliminate follow-up removal visits.
- Orthopedic Surgery:Tendon and ligament repair applications demand coated variants with extended strength retention. Aging demographics in Germany and the United States sustain joint replacement volume growth that translates into unmet demand for specialized PGA configurations.
- Cardiovascular Procedures:Vascular anastomosis and sternal closure require precision-handling sutures with minimal tissue drag.
- Gynecological Surgery:Hysterectomy and pelvic floor repair procedures utilize mid-range filament sizes with standardized absorption profiles.
- Urological Procedures:Nephrectomy and prostatectomy closure applications favor rapid-absorption variants to minimize foreign body exposure.
General Surgery commands the largest revenue pool, while Orthopedic Surgery shows the steepest expansion trajectory.
End User:
Capital expenditure cycles and vendor consolidation strategies differ markedly across institutional settings, reshaping contract negotiation leverage.
- Hospitals:Integrated delivery networks in the United States dominate procurement volume through multi-year GPO agreements. These institutions bundle suture procurement with maintenance contracts for suturing platform calibration, routing spend through separate capital channels.
- Ambulatory Surgical Centers:Same-day discharge protocols drive demand for absorbable closure devices that eliminate return visits for suture removal. United States ASC volume expansion concentrates procurement in high-turnover, cost-optimized SKUs.
- Clinics:Office-based minor procedures utilize smaller filament sizes with simplified packaging configurations.
- Specialty Care Centers:Cardiovascular and orthopedic focused facilities command premium-coated variants through direct manufacturer relationships.
- Research Institutes:Preclinical and clinical trial applications generate demand for uncoated and experimental filament configurations.
Hospitals anchor procurement volume, with Ambulatory Surgical Centers gaining share fastest.
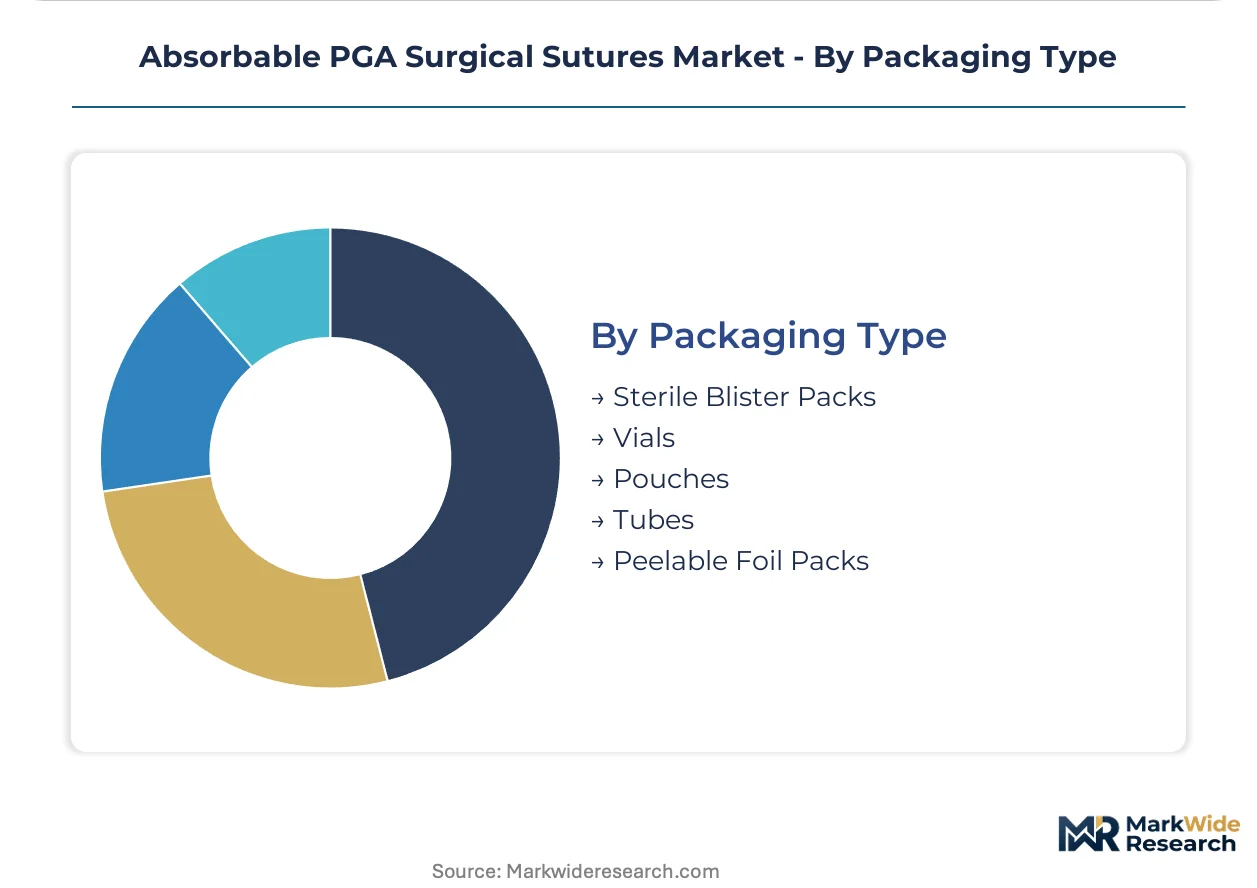
Packaging Type:
Sterility assurance levels and supply chain handling requirements segment packaging specifications across institutional tiers.
- Sterile Blister Packs:Rigid thermoformed trays with Tyvek lidding dominate hospital and ASC procurement. These configurations withstand gamma irradiation sterilization and provide visible damage indication that satisfies Joint Commission audit protocols in United States facilities.
- Peelable Foil Packs:Aluminum-laminated pouches with controlled peel force suit high-volume surgical suites where rapid opening reduces operative setup time. German university hospitals specify these for emergency surgery stockpiles.
- Vials:Glass or polymer containers with septum closures serve liquid-coated or antibiotic-impregnated suture variants.
- Pouches:Flexible polymer bags accommodate bulk filament storage in central supply departments.
- Tubes:Cylindrical containers protect monofilament and barbed configurations from compression damage during transport.
Sterile Blister Packs lead procurement specifications, with Peelable Foil Packs expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan demonstrate contrasting procurement intensities for absorbable PGA surgical sutures, with German university hospitals driving premium-coated filament adoption while Japanese orthopedic centers prioritize rapid-absorption variants for aging patient populations.
United States
Ambulatory surgical center volume expansion and same-day discharge protocols sustain procurement of knotless barbed configurations. FDA 510(k) premarket notification requirements govern sterility assurance and biocompatibility documentation for market access. Integrated delivery networks in Texas and Florida bundle suture procurement with maintenance contracts for suturing platform calibration.
Germany
EU MDR Class IIa certification pathways and REACH-compliant coating chemistry mandates shape manufacturer qualification. German university hospitals in Bavaria and North Rhine-Westphalia specify multifilament braids for abdominal wall closure where tensile strength retention matches healing timelines.
Japan
Aging demographics and joint replacement volume growth create unmet demand for coated PGA variants in tendon and ligament repair. PMDA regulatory frameworks govern absorbable polymer degradation profile standardization. Tokyo and Osaka metropolitan clusters concentrate orthopedic procedure expansion and specialized suture procurement.
United Kingdom
NHS procurement frameworks and cost-optimization protocols drive demand for high-turnover, standardized SKUs in general surgery applications. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR sterility benchmarks. London and Southeast England hospital networks anchor filament volume consumption.
India
Domestic manufacturing scale-up under CDSCO regulatory oversight expands access to cost-optimized uncoated configurations. Maharashtra and Gujarat industrial corridors host contract sterilization facilities serving regional distribution networks. Government hospital procurement committees prioritize absorbable closure devices for rural surgical outreach programs.
Absorbable PGA Surgical Sutures Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated polymer producers commanding premium positioning in coated variants while regional fabricators compete on cost-optimized uncoated volumes. Market structure consolidates around three strategic archetypes: multinational medtech conglomerates with dedicated surgical divisions, mid-tier European manufacturers with REACH-compliant chemistry capabilities, and emerging Asian producers leveraging domestic sterilization infrastructure. Dominant competitive moves include backward integration into glycolide monomer production and multi-year service agreements for suturing platform maintenance.
Among multinational conglomerates, Johnson & Johnson (Ethicon) and Medtronic exemplify the integrated archetype, with Ethicon representing captive polymer supply chain control and Medtronic anchoring hospital GPO relationship depth. B. Braun Melsungen AG occupies a position within the European manufacturing tier, exemplifying REACH-compliant coating chemistry specialization.
| Leading Market Players |
|---|
| Johnson & Johnson (Ethicon) |
| Medtronic |
| B. Braun Melsungen AG |
| Smith+Nephew |
| Boston Scientific |
| DemeTECH Corporation |
| Teleflex |
| Advanced Medical Solutions Group |
| Healthium MedTech |
| Others |
Pricing and Supply Chain Analysis
Polymer chemist concentrations in Bavaria and North Rhine-Westphalia anchor European filament production, with labor-cost differentials between German technical specialists and Asian manufacturing technicians driving spreads between REACH-compliant premium tiers and cost-optimized economy configurations.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for uncoated multifilament braids, compressing margins for non-integrated Western manufacturers. Three-tier pricing structure across premium, standard, and economy levels segments by coating chemistry complexity and notified body certification depth. Pricing pressure stems from glycolide monomer feedstock volatility linked to petroleum derivative markets. Ambulatory surgical centers exhibit highest price sensitivity due to same-day discharge protocol economics, while cardiovascular specialty centers accept premium positioning for precision-handling coated variants.
Supply Chain Analysis
India's phased domestic-content mandates under CDSCO oversight are reshaping sourcing patterns for sterilization and final packaging operations. Raw material concentration centers on China and Germany for glycolide monomer, with the United States and Japan contributing specialized coating chemistry inputs. Single-source vulnerability runs through petroleum-derived feedstock exposure for non-integrated producers. Distribution runs through hospital GPO contracts in North America, direct manufacturer relationships with German university hospital networks, and government procurement channels for Indian public health programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The absorbable PGA surgical sutures market reads as a late-cycle quality story, with procurement committees prioritizing biocompatibility documentation depth and coating performance specifications over unit cost minimization.
For Market Incumbents: To counter barbed knotless configuration commoditization from Asian contract manufacturers, deepen backward integration into glycolide monomer production and lock multi-year service agreements for suturing platform calibration into separate capital expenditure channels. Prioritize REACH-compliant coating chemistry investments to defend European university hospital specifications.
For New Entrants and Emerging Players: Launch via ASC-focused distribution partnerships targeting same-day discharge protocol adoption in United States metropolitan clusters. White-space concentration sits in Japanese orthopedic tendon repair applications and Indian rural surgical outreach programs. Lead with rapid-absorption uncoated variants to bypass coating chemistry regulatory complexity.
For Investors and Strategic Acquirers: Mid-tier European manufacturers with established notified body relationships and solvent-free polymer deposition capabilities are the most active acquirer targets in this space. Five-to-ten year viability hinges on MDR certification timeline compression and coating chemistry IP portfolios. Signal to monitor: notified body capacity expansion announcements from German and French regulatory consultants.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Pathway | Notified body relationships compress technical file review cycles for novel filament geometries. |
| Backward Integration into Glycolide Monomer | Captive feedstock supply insulates margin structures from petroleum derivative volatility. |
| Hospital System Partnership | GPO contract anchoring secures multi-year volume commitments across integrated delivery networks. |
| Software Companion Development | Virtual reality suturing simulation platforms expand addressable markets through educational infrastructure. |
| Reimbursement Strategy | Procedure-specific coding alignment accelerates adoption in ambulatory surgical center settings. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polymer chemists, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists with secondary validation against FDA 510(k) filings, EU MDR technical file databases, hospital procurement records, and glycolide monomer trade flow data. Bottom-up filament volume modeling and top-down healthcare expenditure triangulation anchored market sizing.
Historical absorption rates and surgical volume trajectories across the analysis window established baseline parameters for projection modeling. Segmentation dimensions included filament architecture, coating chemistry tier, application specialty, end-user institutional type, and regional regulatory cluster. CAGRs derived from procedure volume elasticity and pricing trajectory synthesis, with Japanese orthopedic expansion and ASC same-day discharge protocol adoption as primary demand-side inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under notified body capacity constraints and glycolide monomer supply disruptions. Projections reflect documented assumptions regarding MDR transition timelines and coating chemistry regulatory evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Medical Penlights Market
Surgical Instruments
Electrosurgery Market
Surgical Instruments
Cleft Lip and Palate Repair Surgical Instrument Package Market
Surgical Instruments
Ultrasonic Tissue Ablation System Market
Surgical Instruments
Europe Biosurgery Market
Surgical Instruments
Cheilectomy Market
Surgical Instruments
Surgical Hand-Access Port Market
Surgical Instruments
Knotless Tissue Control Devices Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Corneal Transplantation Surgical Instrument Package Market
Surgical Instruments
Global Surgical Case Carts Market
Surgical Instruments
Global Microsurgical Instruments Market
Surgical Instruments
Global Microsurgery Market
Surgical Instruments
Germany General Surgical Devices Market
Surgical Instruments
Absorbable Sutures Market