
 Suprapubic Catheters Market | 2026-2036
Suprapubic Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Suprapubic Catheters Market Intelligence
ISO 13485 certification is rotating as the primary gating mechanism for market access, filtering out contract manufacturers lacking documented quality management systems. Becton, Dickinson and Company leverages its sterile packaging infrastructure to sustain hospital contracts across North America. Cook Medical anchors its position through specialized silicone catheter portfolios for long-term indwelling use. Teleflex Incorporated competes on ultrasound-guided insertion kits that reduce percutaneous complication rates.
A suprapubic catheter is a hollow, flexible tube inserted through the abdominal wall into the bladder to enable chronic or temporary urinary drainage, typically manufactured from medical-grade silicone, latex, or polyurethane with French sizes ranging from 14Fr to 24Fr and balloon capacities of 5–30 mL for secure retention. Silicone catheters dominate the product landscape due to biocompatibility and extended dwell times up to twelve weeks, while hydrogel-coated variants command premium positioning through reduced encrustation and tissue adhesion. Home healthcare represents the fastest-expanding end-user channel as reimbursement frameworks shift toward outpatient management, whereas hospitals retain the deepest margin pools through bundled procedural pricing.
The FDA enforces Class II device controls under 21 CFR 876.5130, mandating biocompatibility testing and sterilization validation for all commercially distributed suprapubic catheters, while the EU Medical Device Regulation requires notified body conformity assessment and unique device identification for market placement in Europe. These frameworks elevate compliance costs for smaller manufacturers but simultaneously protect incumbent suppliers with established regulatory infrastructure. Stakeholders must monitor evolving reimbursement thresholds for home-based catheter replacement cycles and the pace of ultrasound-guided insertion training adoption across ambulatory surgical networks.
Market Dynamics
The migration of catheter care from acute settings to home environments is restructuring procurement patterns, with reimbursement codes now favoring extended-dwell silicone devices over standard latex alternatives in outpatient bundles.
Growth Catalysts
- Home Healthcare Expansion:Medicare reimbursement shifts in the United States now cover biweekly catheter exchanges for neurogenic bladder patients, expanding the addressable patient pool beyond hospital discharge.
- MDR Compliance Infrastructure:The EU Medical Device Regulation's unique device identification mandate is accelerating replacement cycles as providers stock ISO 13485-certified inventory to avoid supply interruptions.
- Ultrasound-Guided Insertion:Percutaneous access kits with integrated sonography are reducing complication rates in ambulatory surgical centers, broadening the prescriber base beyond urology specialists.
Market Restraints
- Medical-Grade Silicone Supply Concentration:Specialty elastomer production clusters in Germany and Japan, exposing catheter manufacturers to input cost volatility when pharmaceutical-grade silicone feedstocks tighten.
- FDA 510(k) Pathway Friction:Substantial equivalence demonstrations for coated catheter variants now require extended biocompatibility dossiers, lengthening time-to-market for iterative product improvements.
- Intermittent Catheter Substitution:Single-use hydrophilic intermittent systems are capturing select neurogenic bladder cases where patient dexterity permits self-catheterization without abdominal wall penetration.
Strategic Opportunities
- Underpenetrated Rural Networks:Home health agencies in the United States Mountain West and Great Plains regions lack consistent access to specialty urology distributors, creating whitespace for direct-to-provider logistics models.
- Telehealth-Integrated Monitoring:Catheter systems with embedded flow sensors and cloud-connected drainage bags are converging with remote patient monitoring platforms to reduce emergency department visits for occlusion events.
- IRA Supply Chain Reshoring Incentives:Domestic production tax credits under the Inflation Reduction Act are offsetting capital equipment costs for sterile packaging lines serving Veterans Affairs hospital networks.
Industry Challenges
- Interventional Radiology Skill Gaps:Percutaneous suprapubic placement training programs remain concentrated at academic medical centers, limiting procedure availability in community hospital settings where general surgeons lack fluoroscopic guidance experience.
- ISO 13485 Certification Timelines:Notified body backlogs in Europe and capacity constraints at US-registrar affiliates are stretching quality management system audits to fourteen-month cycles for contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Suprapubic Catheters Market |
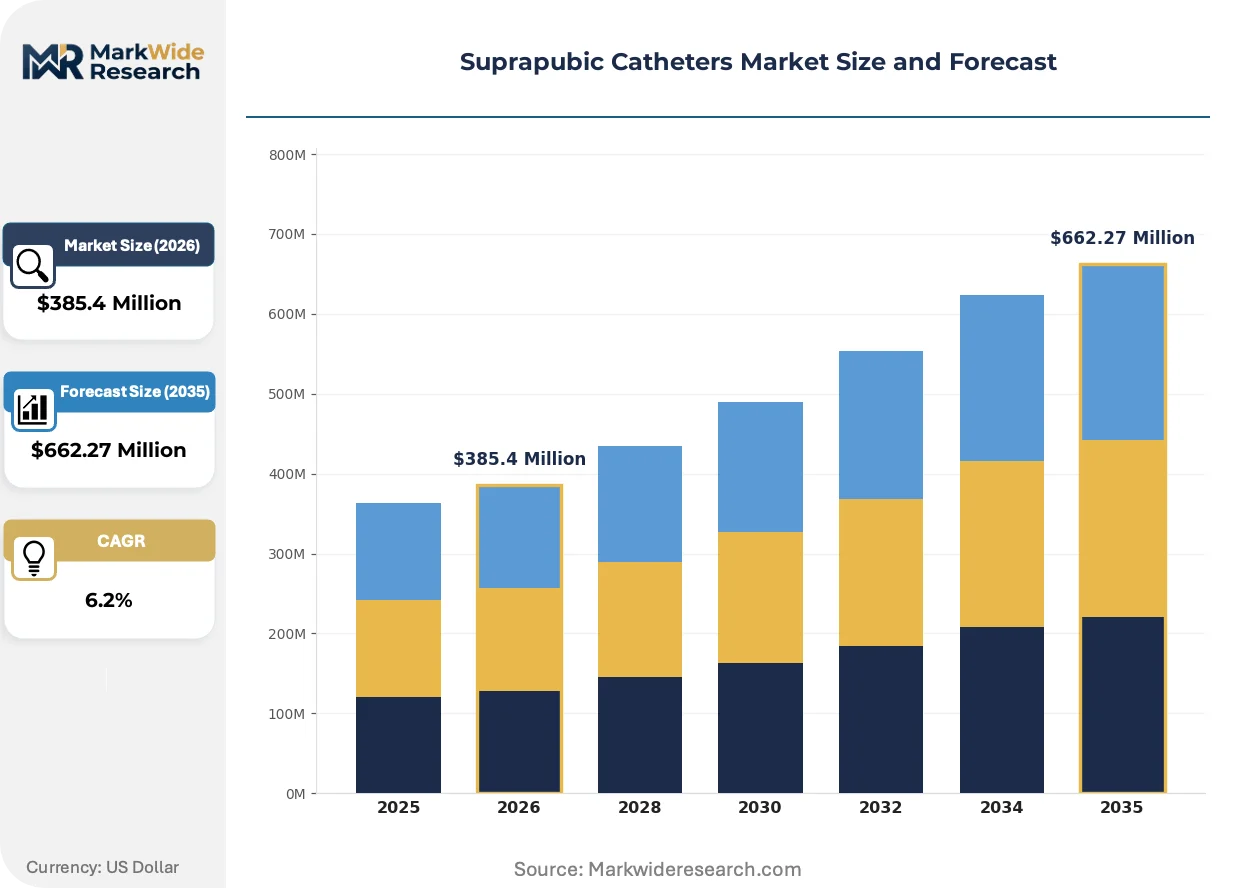
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Catheters, Latex Catheters, Polyurethane Catheters, Hydrogel-Coated Catheters Application: Urinary Retention, Postoperative Care, Chronic Urinary Incontinence, Neurogenic Bladder End User: Hospitals, Ambulatory Surgical Centers, Long-Term Care Facilities, Home Healthcare Insertion Technique: Percutaneous, Open Surgical, Ultrasound-Guided, Fluoroscopic-Guided |
| Companies Covered | B. Braun Melsungen AG, Becton, Dickinson and Company, Cook Medical, Teleflex Incorporated, Amecath, Fortune Medical Instrument Corp., Degania Silicone Ltd, Urovision GmbH, UroMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Suprapubic Catheters Market Strategic Shifts & Innovations
Material science advances and regulatory digitization are compressing product lifecycles while expanding the clinical settings where suprapubic catheterization is technically feasible and economically justified.
Silicone-hydrogel composite catheters with silver-ion elution surfaces are displacing standard silicone devices in long-term indwelling applications. Academic medical centers in the United States and university hospitals in Germany are adopting these anti-encrustation variants at accelerating pace for spinal cord injury cohorts. The technology is displacing quarterly exchange protocols with six-month dwell schedules, compressing recurring revenue per patient while reducing complication-related hospitalization costs.
The EU Medical Device Regulation's EUDAMED database mandate is forcing manufacturers to restructure post-market surveillance systems. Economic operators must now submit serious incident reports within ten days to notified bodies, elevating compliance staffing requirements. Small-to-mid catheter producers without captive regulatory affairs departments are outsourcing vigilance functions to specialized consultancies in Ireland and Switzerland.
Patients and caregivers are demanding closed-system drainage bags with tamper-evident valves and discrete carrying options, shifting preference away from standard bedside collectors. Home medical equipment suppliers in the United States are bundling these premium accessories with catheter replacement kits to capture higher-margin recurring revenue. The behavioral shift is most visible in Medicare Advantage plan populations where supplemental benefits cover durable medical equipment upgrades.
Suprapubic Catheters Market Segmentation
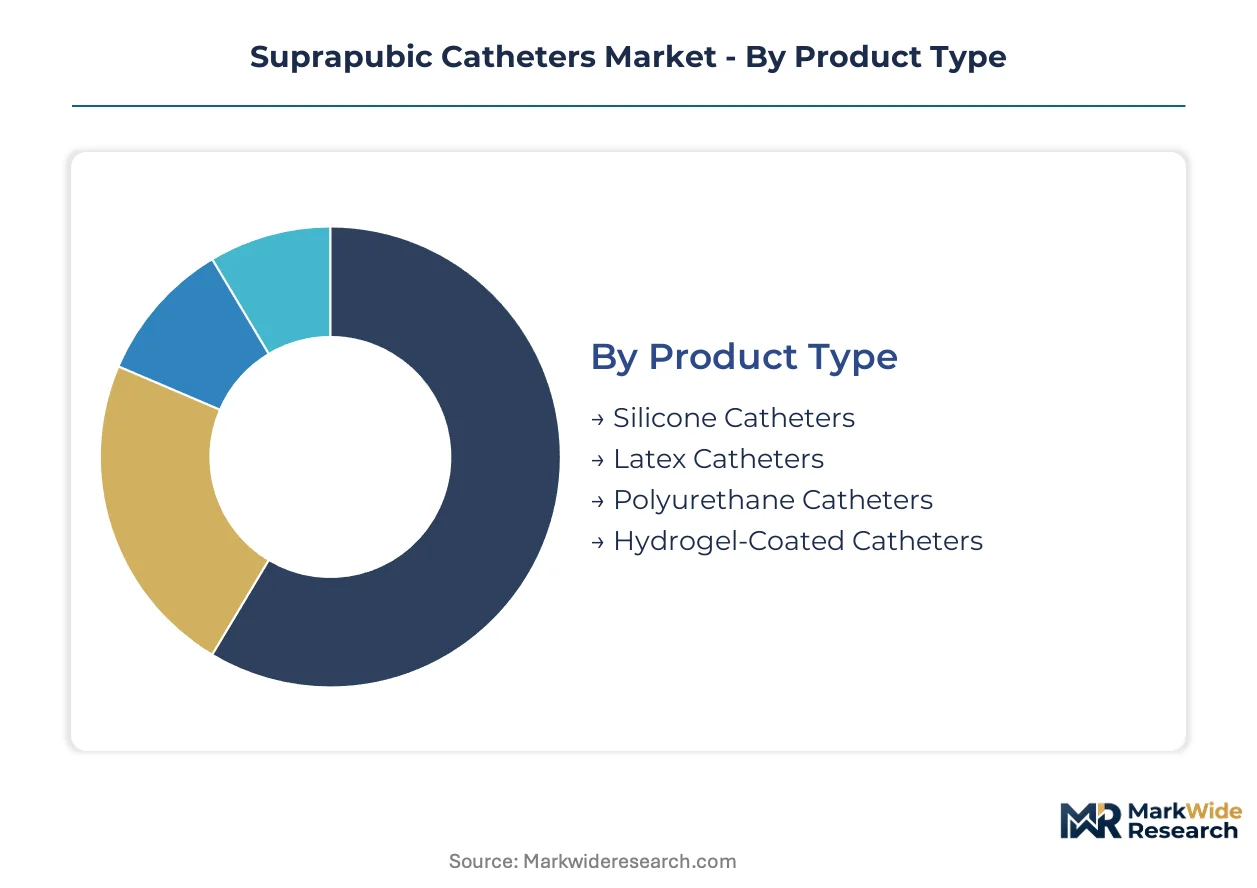
Suprapubic catheter procurement patterns diverge sharply across material grades, clinical settings, and insertion protocols. Reimbursement codes and infection risk profiles reshape which segments capture volume versus margin.
Product Type:
Latex catheters face intensifying substitution pressure from silicone and hydrogel variants as allergy documentation requirements expand across US hospital systems.
- Silicone Catheters:Medical-grade silicone construction permits twelve-week indwelling intervals with reduced tissue irritation. Medicare Advantage plans in Florida and Arizona prioritize these for spinal cord injury patients requiring long-term drainage.
- Hydrogel-Coated Catheters:Polyvinylpyrrolidone surface layers minimize protein adhesion and encrustation formation. German university hospitals specify these for six-month exchange protocols in neurogenic bladder management.
- Latex Catheters:Natural rubber elastomer with lower unit costs but documented Type I hypersensitivity risks. Retains procurement share in price-sensitive Indian public hospital tenders.
- Polyurethane Catheters:Thermoplastic construction offers thinner walls at equivalent French sizes. Deployed in Japanese acute care settings where catheter diameter minimization reduces insertion trauma.
Silicone catheters retain volume leadership; hydrogel-coated variants hold the steepest expansion curve.
Application:
Cost tier stratification separates emergency procedural use from scheduled chronic management.
- Neurogenic Bladder:Long-term indwelling requirement drives premium material selection and closed-system drainage accessories. Home healthcare agencies in Texas and California scale catheter kit deliveries for spinal cord injury cohorts.
- Postoperative Care:Temporary drainage following pelvic or urologic surgery demands rapid-insertion kits with secure retention balloons. Ambulatory surgical centers in Illinois prioritize ultrasound-guided placement to reduce return visits.
- Urinary Retention:Acute obstruction management favors standard silicone devices with shorter dwell protocols. Emergency departments in New York state stock 14Fr and 16Fr sizes for immediate decompression.
- Chronic Urinary Incontinence:Alternative to transurethral catheterization in elderly patients with urethral stricture. Long-term care facilities in Pennsylvania specify smaller balloon capacities to minimize bladder mucosa trauma.
Postoperative care generates the highest procedure throughput; neurogenic bladder applications command the longest revenue per patient.
End User:
Volume concentration tilts toward settings with bundled reimbursement and procedural infrastructure.
- Hospitals:Academic medical centers in Massachusetts and North Carolina anchor catheter placement training programs. Retain deepest margin pools through bundled procedural pricing inclusive of imaging guidance.
- Home Healthcare:Medicare reimbursement shifts enable biweekly catheter exchanges outside institutional settings. Agencies in the US Mountain West lack consistent specialty distributor access.
- Ambulatory Surgical Centers:Same-day discharge protocols favor percutaneous insertion with minimal sedation. Ohio and Michigan facilities invest in portable ultrasound units for point-of-care placement.
- Long-Term Care Facilities:Staff turnover challenges sustain demand for pre-connected closed drainage systems. Virginia nursing homes specify tamper-evident valve designs to reduce unauthorized disconnection.
Hospitals retain procedural volume leadership; home healthcare agencies are expanding most quickly as reimbursement migrates outpatient.
Insertion Technique:
Skill scarcity and equipment requirements fragment adoption across provider types.
- Ultrasound-Guided:Real-time sonographic visualization reduces bowel perforation risk in percutaneous access. Teleflex Incorporated kits dominate ambulatory surgical center procurement in Georgia and Washington.
- Percutaneous:Trocar-based blind insertion remains standard in resource-constrained settings. Community hospitals in Indiana rely on this technique where interventional radiology coverage is limited.
- Fluoroscopic-Guided:Radiographic confirmation ensures correct suprapubic positioning in complex anatomy. Academic medical centers in Maryland and Minnesota reserve this for revision procedures.
- Open Surgical:Direct cystotomy under general anesthesia for failed percutaneous attempts. Retained for pediatric and morbidly obese patient cohorts in tertiary referral centers.
Percutaneous technique retains volume leadership; ultrasound-guided placement holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement expansions for home-based catheter exchanges are restructuring procurement geography across mature healthcare systems. The FDA's updated sterile device guidelines and the EU MDR's unique device identification mandate are elevating compliance costs unevenly across manufacturing bases.
United States
Neurogenic bladder prevalence among spinal cord injury patients and aging demographics sustain clinical volume in Florida and Arizona Medicare Advantage networks. The FDA enforces Class II device controls under 21 CFR 876.5130 with extended biocompatibility dossier requirements for coated variants. Home health agencies in the Mountain West and Great Plains regions lack consistent specialty distributor access, creating whitespace for direct-to-provider logistics models.
Germany
University hospitals specify hydrogel-coated catheters for six-month exchange protocols in neurogenic bladder management, driving premium material adoption. The EU Medical Device Regulation requires notified body conformity assessment and EUDAMED database registration for market placement. Specialty elastomer production clusters in industrial regions expose catheter manufacturers to input cost volatility when pharmaceutical-grade silicone feedstocks tighten.
Japan
Acute care settings deploy polyurethane catheters where diameter minimization reduces insertion trauma, particularly in elderly patient cohorts. METI oversees medical device quality standards alignment with international harmonization frameworks. Tokyo and Osaka metropolitan medical centers anchor catheter placement training programs with fluoroscopic guidance infrastructure for complex revision procedures.
United Kingdom
Long-term care facilities specify smaller balloon capacities to minimize bladder mucosa trauma among elderly patients with urethral stricture. The Medicines and Healthcare products Regulatory Agency implements post-Brexit device registration pathways parallel to EU MDR structures. London and Southeast England academic medical centers concentrate interventional radiology skill development for percutaneous placement.
India
Price-sensitive public hospital tenders retain procurement share for latex catheters despite allergy documentation expansion in private systems. CDSCO regulates medical device imports and domestic manufacturing under phased notification schemes. Maharashtra and Gujarat industrial corridors host contract manufacturers seeking ISO 13485 certification to access export markets.
Suprapubic Catheters Market Key Industry Players
Listed leaders compete with private specialists across regulatory infrastructure and sterile packaging capabilities. The supplier base stratifies into tiered quality certifications, with ISO 13485 compliance rotating as the primary gating mechanism for market access. Three archetypes dominate: diversified medical device conglomerates with hospital contract depth, silicone specialty manufacturers with materials science integration, and regional distributors with home healthcare logistics networks. Competitive moves center on M&A for regulatory dossier accumulation and capacity expansion for domestic sterile packaging lines.
Within the diversified conglomerate tier, Becton, Dickinson and Company and B. Braun Melsungen AG exemplify scale-driven positioning through established hospital contract infrastructure across North America and Europe. Cook Medical and Teleflex Incorporated occupy specialist positions, with the former representing silicone catheter portfolio depth and the latter anchoring ultrasound-guided insertion kit development. Among regional fabricators, Degania Silicone Ltd and Urovision GmbH sit within materials-focused archetypes, while Amecath and Fortune Medical Instrument Corp. exemplify emerging market access strategies.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Becton, Dickinson and Company |
| Cook Medical |
| Teleflex Incorporated |
| Amecath |
| Fortune Medical Instrument Corp. |
| Degania Silicone Ltd |
| Urovision GmbH |
| UroMed |
| Others |
Cost & Logistics Intelligence
ISO 13485 certification gates both supplier qualification and price differentiation in suprapubic catheter procurement, with notified body audits stretching to fourteen-month cycles and premium-grade silicone devices commanding sustained margin separation from uncertified alternatives.
Pricing Analysis
Certification level creates the primary spread across suprapubic catheter tiers. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 13485 compliance, hydrogel coating presence, and sterile packaging infrastructure. Cost compression in standard silicone tiers is intensifying because Indian contract manufacturers are scaling uncertified production for domestic tenders. Price-sensitive public hospital systems in emerging markets exhibit highest elasticity, while Medicare Advantage networks in Florida and Arizona show lowest sensitivity for long-term indwelling applications.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for German and Japanese pharmaceutical-grade silicone feedstocks. Specialty elastomer production clusters in Germany, Japan, and select Indian industrial corridors anchor global catheter manufacturing. Raw material dependencies rest on medical-grade silicone polymers, silver-ion antimicrobial additives, and hydrogel coating precursors. Single-source vulnerability concentrates in German specialty chemical suppliers for pharmaceutical-grade silicone. Distribution runs through hospital GPO contracts in North America, specialty urology distributors in Europe, and direct-to-provider logistics in underserved US rural networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Suprapubic catheter incumbents face sustained substitution pressure from single-use hydrophilic intermittent systems in dexterous neurogenic bladder patients, requiring defensive positioning around long-term indwelling superiority.
For Market Incumbents: Shield core hospital contracts through captive sterile packaging infrastructure and FDA 510(k) pathway expertise. Deepen backward integration into medical-grade silicone compounding to offset German and Japanese feedstock volatility. Accelerate ultrasound-guided insertion kit training partnerships with ambulatory surgical centers to preempt percutaneous technique commoditization.
For New Entrants and Emerging Players: Differentiate on telehealth-integrated catheter systems with embedded flow sensors and cloud-connected drainage monitoring. Target home healthcare agencies in the US Mountain West and Great Plains regions lacking consistent specialty distributor access. Pursue direct-to-provider logistics models bypassing incumbent distributor relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed silicone specialty manufacturers seeking regulatory dossier expansion for EU MDR compliance. Long-term viability hinges on reimbursement durability for home-based catheter exchanges and ultrasound-guided placement training adoption curves. Watch Medicare Advantage plan supplemental benefit expansions for durable medical equipment upgrades as inflection signal.
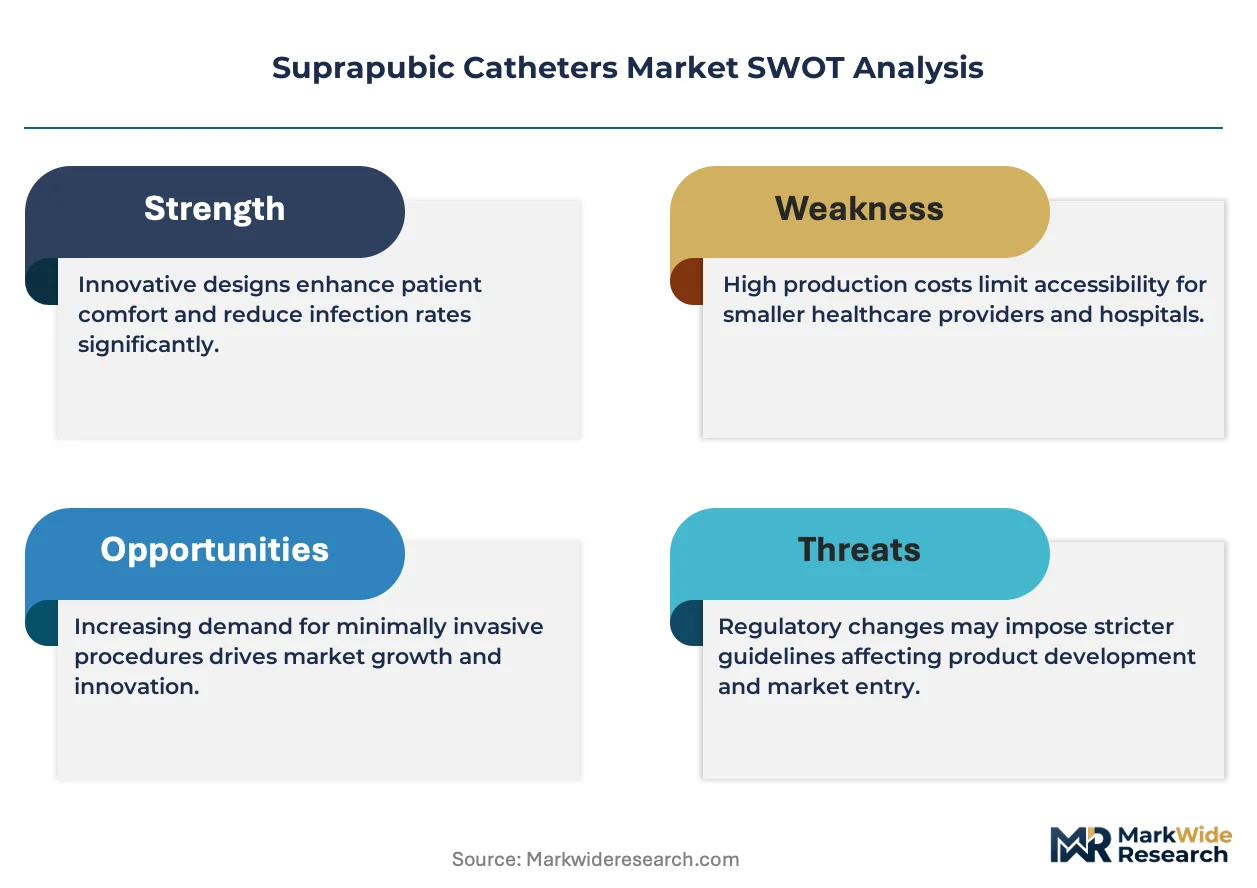
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Notified body conformity assessment unlocks EU MDR market placement and hospital GPO contract eligibility. |
| Ultrasound-Guided Insertion Kit Development | Teleflex Incorporated's ambulatory surgical center penetration demonstrates procedure democratization beyond urology specialists. |
| Telehealth-Integrated Monitoring Platform | Embedded flow sensors converging with remote patient monitoring reduce emergency department visits for occlusion events. |
| Domestic Sterile Packaging Line Expansion | IRA production tax credits offset capital equipment costs for Veterans Affairs hospital network supply contracts. |
| Hydrogel-Coated Catheter Portfolio Extension | German university hospital six-month exchange protocols validate premium positioning through anti-encrustation performance. |
Research Approach
A standing panel of urology department heads, hospital purchasing committee chairs, biomedical engineers, and home healthcare procurement managers provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, EU EUDAMED incident reports, and GPO contract disclosure records. Bottom-up catheter unit demand modeling triangulated against top-down procedure volume estimates from academic medical centers and ambulatory surgical networks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include material grade tier, insertion technique protocol, end-user setting, and regional reimbursement framework. CAGRs derived from weighted average of historical procedure growth, demographic elasticity coefficients, and technology substitution rates. Industry-specific inputs incorporated ultrasound-guided placement training adoption curves and Medicare Advantage supplemental benefit expansion trajectories.
Material uncertainties — regulatory timeline delays for ISO 13485 audits, pharmaceutical-grade silicone feedstock disruptions, and intermittent catheter substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about reimbursement stability and training infrastructure buildout. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
North America Transrectal Ultrasound Market
Urology
Urinary Retention Therapeutics Market
Urology
Ureteral Obstruction Market
Urology
Genitourinary Cancers Treatment Market
Urology
Global Lithotripsy Market
Urology
Cystoscope Market
Urology
Complicated Urinary Tract Infections Treatment Market
Urology
India Urology Market
Urology
Prostate Cancer Treatment Market
Urology
Global Bladder Cancer Market
Urology
Global Bladder Cancer Therapeutics Market
Urology
Urethral Stricture Market
Urology
Uncomplicated Urinary Tract Infection Treatment Market
Urology
Hematuria Treatment Market
Urology
Uropathy Treatment Market
Urology
Ureter Cancer Treatment Market