
 Uncomplicated Urinary Tract Infection Treatment Market | 2026-2036
Uncomplicated Urinary Tract Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Uncomplicated Urinary Tract Infection Treatment Market Analytics
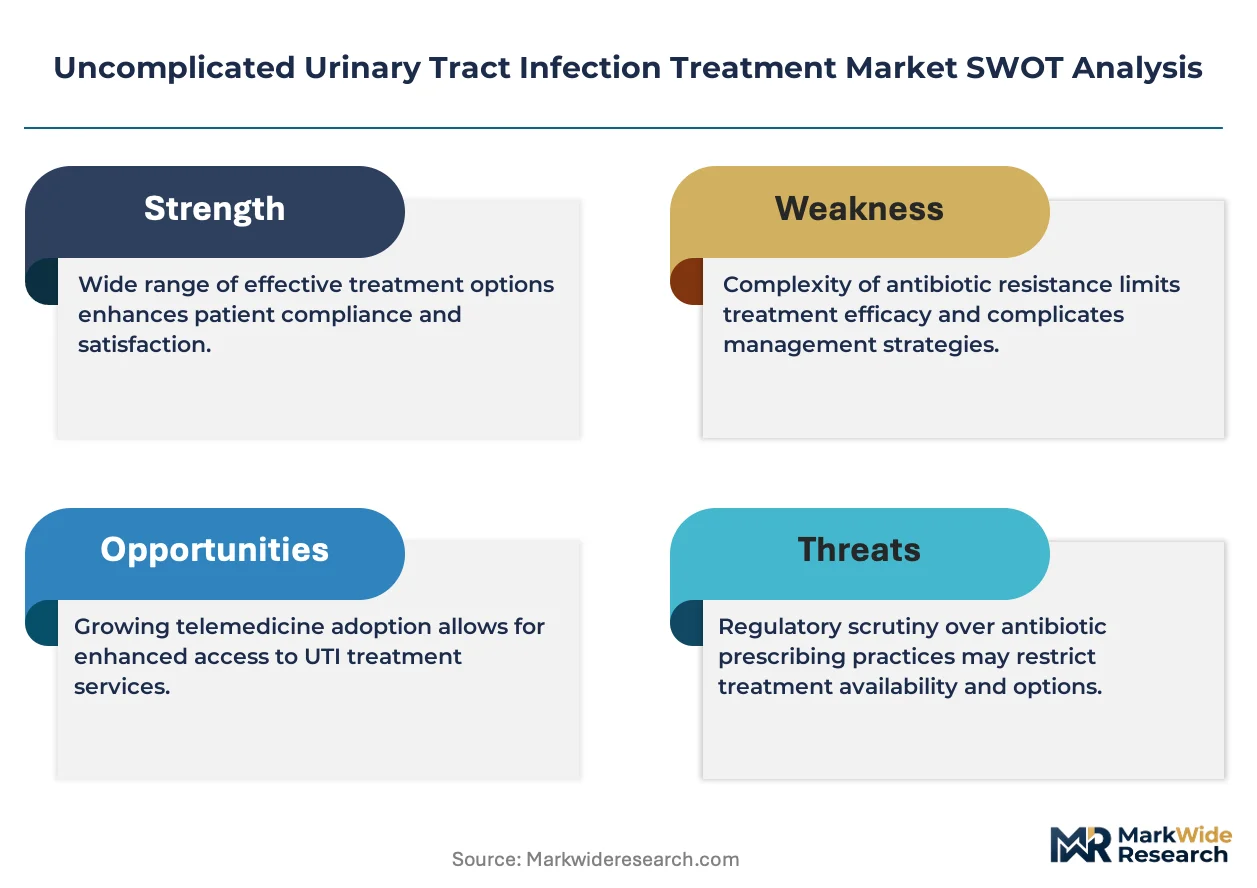
India is narrowing the cost gap in active pharmaceutical ingredient production for generic antibiotics. GlaxoSmithKline leverages its established manufacturing footprint in emerging markets to sustain supply chain reliability for first-line therapies. Pfizer competes through vertical control over fermentation-based bulk drug production, while Bayer AG anchors its position in nitrofurantoin supply through backward integration into key intermediates.
Uncomplicated urinary tract infection treatment encompasses antimicrobial therapies targeting cystitis in structurally and neurologically normal urinary tracts, with first-line agents typically requiring susceptibility against Escherichia coli in concentrations achievable at standard oral dosing. These therapies function to eradicate infection while minimizing resistance selection and preserving renal function. The oral delivery mode dominates volume due to patient convenience and cost efficiency, though intravenous formulations retain margin concentration in hospital settings. Adult women represent the largest patient type segment given anatomical predisposition, while fosfomycin is gaining traction as a single-dose alternative where resistance patterns complicate standard therapy selection.
The FDA governs antibiotic approval pathways and post-market surveillance through its Center for Drug Evaluation and Research, while the EMA's Committee for Medicinal Products for Human Use coordinates centralized assessments across European member states. Both frameworks increasingly tie market access to antimicrobial stewardship commitments and resistance monitoring protocols. Stakeholders must weigh the pace of generic entry against evolving susceptibility breakpoints when allocating R&D and manufacturing investments.
Market Dynamics
Retail pharmacy chains in the United States are consolidating formulary control over acute infection therapies, redirecting prescribing authority away from hospital systems and toward outpatient channels. This shift compresses margin structures for manufacturers while elevating the importance of direct distribution relationships.
Growth Catalysts
- FDA Streamlined Generic Pathways:Accelerated abbreviated new drug application reviews for first-line antibiotics reduce time-to-market for follow-on entrants, expanding therapeutic options.
- Outpatient Clinic Expansion:Primary care networks are capturing uncomplicated UTI volume previously routed to emergency departments, creating concentrated demand nodes for oral formulations.
- Single-Dose Fosfomycin Adoption:Resistance-pattern complications in standard therapy selection are driving prescriber acceptance of alternative antimicrobial agents with simplified dosing.
Market Restraints
- Fermentation Input Volatility:Bulk antibiotic production depends on agricultural commodity feedstocks whose price swings transmit directly to manufacturing economics.
- Indian API Concentration:Active pharmaceutical ingredient sourcing clusters in specific subcontinent manufacturing zones, exposing supply continuity to localized disruption risks.
- Antimicrobial Stewardship Mandates:EMA and FDA resistance-monitoring protocols impose post-market surveillance burdens that extend compliance costs across product lifecycles.
Strategic Opportunities
- Underpenetrated Telehealth Channels:Virtual care platforms in the United States are opening direct-to-patient prescription pathways that bypass traditional clinic infrastructure.
- Point-of-Care Diagnostics Convergence:Rapid susceptibility testing integration with prescribing workflows enables targeted therapy selection at the site of diagnosis.
- Antibiotic Resistance Insurance Models:Novel reimbursement frameworks in European markets reward manufacturers for resistance-sparing product characteristics.
Industry Challenges
- Microbiology Talent Scarcity:Specialized expertise in susceptibility breakpoint determination and resistance surveillance functions commands premium compensation in competitive labor markets.
- Legacy System Integration:Electronic health record interoperability gaps between retail pharmacies and hospital networks complicate prescription tracking and stewardship compliance.
- Regulatory Timeline Compression:Simultaneous FDA and EMA filing requirements demand parallel development tracks that strain regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uncomplicated Urinary Tract Infection Treatment Market |
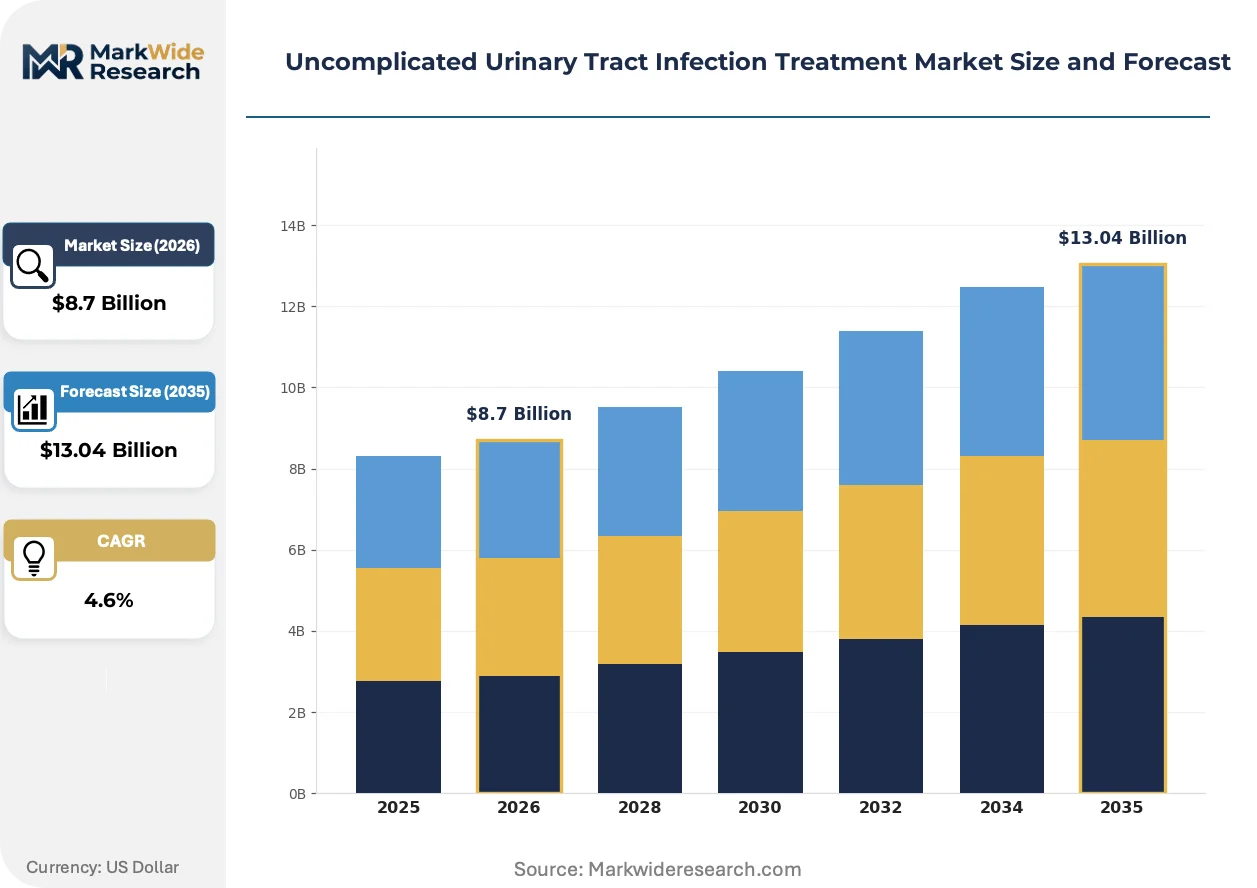
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ampicillin, Nitrofurantoin, Trimethoprim, Fosfomycin Delivery Mode: Oral, Injectable, Topical, Intravenous Patient Type: Adult Women, Adult Men, Pediatric Patients, Pregnant Women Treatment Setting: Hospital, Urgent Care, Primary Care, Outpatient Clinic |
| Companies Covered | GlaxoSmithKline, Bayer AG, Pfizer, Novartis AG, AstraZeneca, Merck & Co., F. Hoffmann-La Roche, Bristol-Myers Squibb, AbbVie, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uncomplicated Urinary Tract Infection Treatment Market Evolving Landscape
Antimicrobial stewardship technology is digitizing prescribing decision support, compressing the gap between diagnostic data and therapeutic selection. Three developments are restructuring how uncomplicated UTIs are managed across care settings.
Artificial intelligence-enabled susceptibility prediction algorithms analyze regional resistance patterns to recommend first-line agents before culture results return. Large health systems in the United States are deploying these tools across integrated delivery networks. This capability is digitizing the traditional empiric prescribing workflow, reducing inappropriate broad-spectrum exposure.
EMA's revised clinical trial guidance for uncomplicated infections now permits non-inferiority designs with symptomatic cure endpoints rather than microbiological eradication. This regulatory shift accelerates development timelines for novel agents while maintaining patient-relevant outcome standards. European sponsors are restructuring Phase III programs to align with these streamlined evidentiary requirements.
Direct-to-consumer pharmacy platforms are unbundling the traditional prescriber-pharmacist-patient relationship, enabling asynchronous consultation and same-day delivery of acute therapies. Young adult women in urban United States markets are adopting these channels at rates exceeding other demographic segments. This behavioral shift concentrates volume with vertically integrated retail operators possessing captive logistics infrastructure.
Uncomplicated Urinary Tract Infection Treatment Market Segmentation
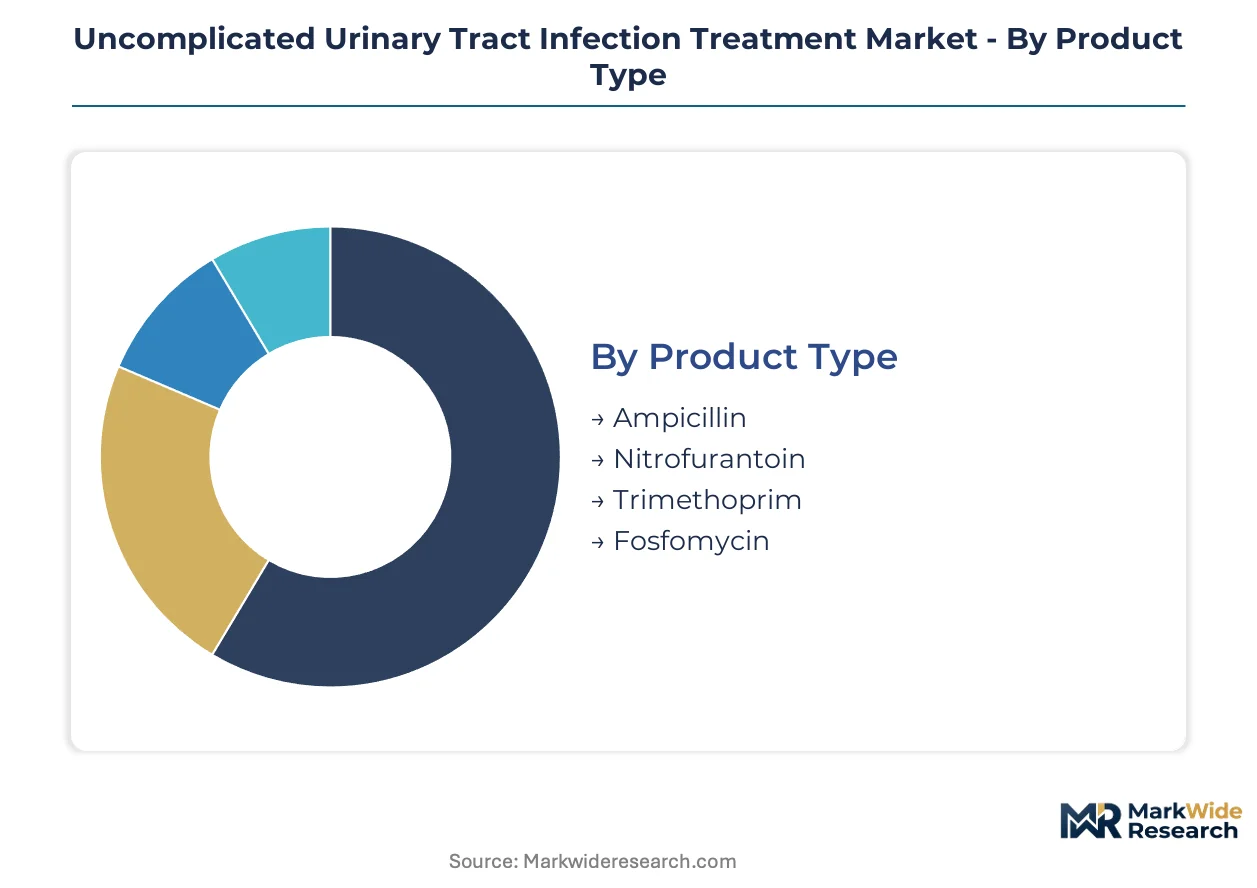
Antibiotic selection for uncomplicated UTIs fragments across molecular classes with distinct resistance profiles and dosing conveniences. Delivery mode and patient demographics further stratify prescribing patterns, while treatment setting determines reimbursement pathways and formulary access.
Product Type:
Cost tier separates first-line generics from resistance-pattern alternatives with premium positioning.
- Nitrofurantoin:A nitrofuran antibiotic achieving high urinary concentrations with minimal systemic absorption. Demand concentrates in United States outpatient clinics where FDA susceptibility breakpoints support empiric prescribing against susceptible Escherichia coli.
- Fosfomycin:A phosphonic acid antibiotic delivered as single-dose oral granules with distinct resistance mechanism. United States retail pharmacy chains are capturing volume as resistance complications displace standard fluoroquinolone selection.
- Ampicillin:A beta-lactam aminopenicillin with established generic manufacturing infrastructure.
- Trimethoprim:A dihydrofolate reductase inhibitor often co-formulated with sulfamethoxazole.
Nitrofurantoin commands the established base. The steepest expansion runs through Fosfomycin.
Delivery Mode:
Application context determines whether therapy reaches ambulatory or acute care channels.
- Oral:Tablet, capsule, and granule formulations enabling self-administered completion outside clinical facilities. Primary care networks in the United States are routing uncomplicated cystitis volume away from emergency departments toward retail pharmacy fulfillment.
- Intravenous:Parenteral formulations reserved for pyelonephritis progression or oral intolerance. Hospital formularies retain margin concentration where admission criteria trigger reimbursement at administered rates.
- Injectable:Intramuscular depot preparations for compliance-constrained patients.
- Topical:Limited formulations for periurethral application in specific clinical scenarios.
Oral administration commands the established base. The steepest expansion runs through Intravenous.
Patient Type:
Customer type dictates anatomical risk factors and pregnancy safety considerations that constrain therapeutic selection.
- Adult Women:Patients aged 18-65 with anatomical urethral proximity predisposing to ascending infection. United States urgent care chains are deploying rapid diagnostic protocols to capture this volume through same-day prescription workflows.
- Pregnant Women:Patients requiring Category B safety profiles with teratogenic avoidance mandates. EMA pharmacovigilance requirements impose extended follow-up obligations for sponsors targeting this indication.
- Adult Men:Patients with structural or functional urinary tract abnormalities requiring exclusion from "uncomplicated" classification.
- Pediatric Patients:Age-weighted dosing populations with limited oral suspension availability for specific agents.
Adult Women commands the established base. The steepest expansion runs through Pregnant Women.
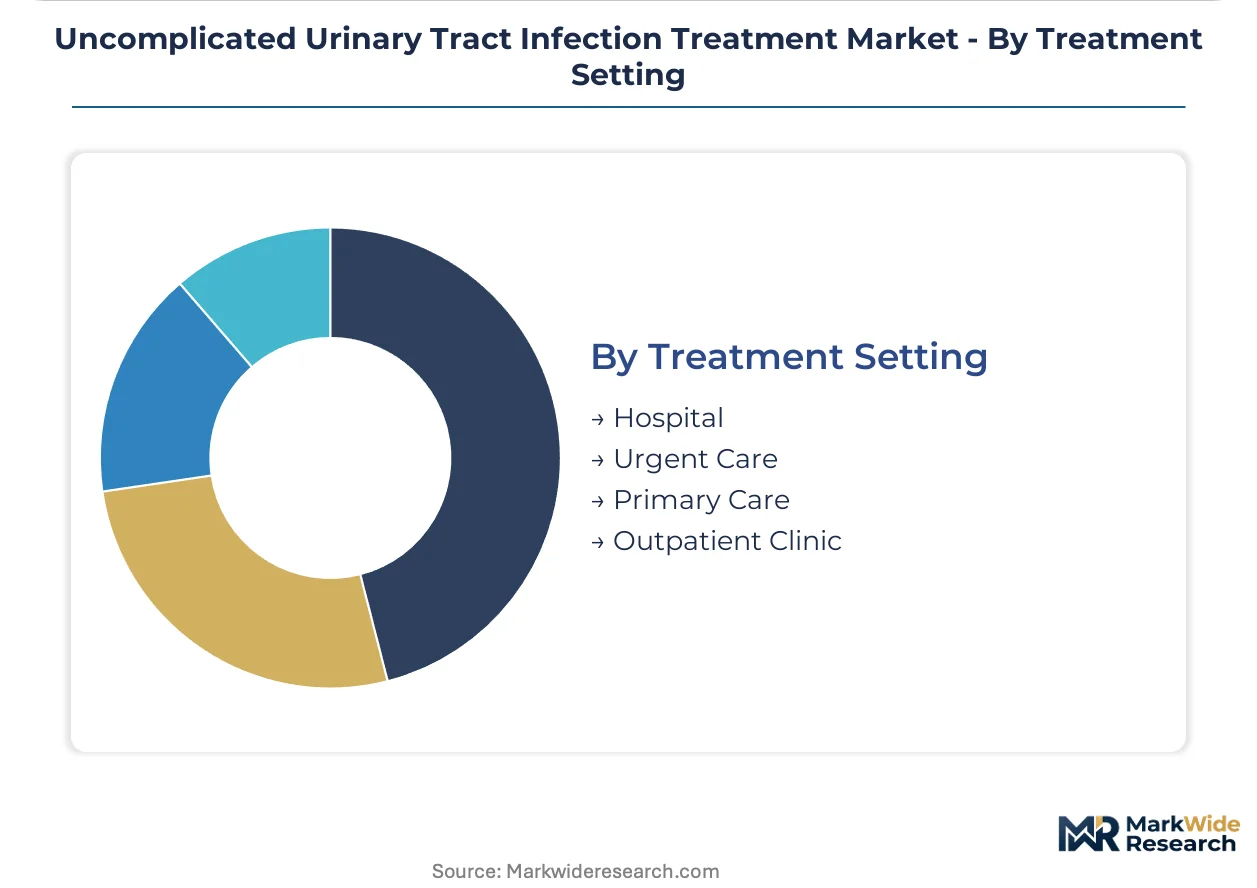
Treatment Setting:
Geography of care delivery determines whether prescribing authority rests with hospital systems or retail-integrated networks.
- Outpatient Clinic:Primary care and community health centers capturing uncomplicated UTI volume through scheduled or walk-in access. United States retail pharmacy chains are consolidating formulary control through direct distribution contracts that compress manufacturer margins.
- Urgent Care:Freestanding emergency alternatives with on-site dispensing capabilities. Urban United States markets are seeing telehealth-urgent care convergence through asynchronous consultation platforms.
- Primary Care:Longitudinal physician relationships with established susceptibility pattern familiarity.
- Hospital:Inpatient admission settings triggered by complicated infection criteria or comorbidity burden.
Outpatient Clinic commands the established base. The steepest expansion runs through Urgent Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing clusters in India and China concentrate generic antibiotic supply, while United States demand for outpatient UTI therapies reshapes distribution economics. Formulary control by retail pharmacy chains in North America redirects prescribing authority toward ambulatory channels. European antimicrobial stewardship mandates impose parallel compliance frameworks that differentiate market access requirements.
United States
Retail pharmacy chains consolidate formulary control over acute infection therapies, compressing manufacturer margins while elevating direct distribution relationships. FDA streamlined generic pathways accelerate abbreviated new drug application reviews for first-line antibiotics. Urgent care networks in urban markets deploy rapid diagnostic protocols to capture uncomplicated cystitis volume through same-day prescription workflows.
Germany
EMA centralized assessments coordinate market access across European member states with increasing ties to antimicrobial stewardship commitments. EMA revised clinical trial guidance permits non-inferiority designs with symptomatic cure endpoints for uncomplicated infections. Pharmaceutical manufacturing clusters in Baden-Württemberg sustain fermentation-based bulk drug production infrastructure.
India
API production cost advantages narrow the competitive gap for generic antibiotic manufacturing against Western suppliers. CDSCO regulatory frameworks govern domestic pharmaceutical quality standards while export-oriented facilities target FDA and EMA inspections. Manufacturing zones in Maharashtra and Gujarat concentrate fermentation feedstock processing and intermediate synthesis capabilities.
China
NMPA oversight of antibiotic production licensing aligns with national antimicrobial resistance action plans. Bulk drug manufacturing clusters in Jiangsu and Zhejiang provinces supply global generic markets with beta-lactam and nitrofuran intermediates. Environmental compliance mandates from MEE reshape fermentation facility economics and capacity utilization.
United Kingdom
NHS antimicrobial stewardship programs constrain empiric prescribing patterns through integrated care system formularies. MHRA post-Brexit regulatory autonomy maintains alignment with EMA resistance monitoring protocols. London-based health technology assessment bodies evaluate point-of-care diagnostic integration with UTI prescribing workflows.
Uncomplicated Urinary Tract Infection Treatment Market Competitive Landscape
Vertically integrated pharmaceutical conglomerates and specialized generic manufacturers split the market into distinct capability tiers. Consolidation around fermentation-based production and backward integration into key intermediates defines competitive positioning. Three archetypes dominate: multinational innovators with stewardship technology portfolios, emerging market API-to-finished-dose integrators, and retail pharmacy chain captive suppliers. Capacity expansion in Indian manufacturing zones and strategic partnerships for point-of-care diagnostic convergence represent the dominant competitive moves.
Among the established multinational tier, GlaxoSmithKline exemplifies manufacturing footprint leverage in emerging markets, while Pfizer occupies a position anchored in fermentation-based bulk drug production control. Bayer AG represents backward integration into nitrofuran intermediates for nitrofurantoin supply security. These three companies illustrate how supply chain configuration and regulatory compliance scale differentiate positioning within the generic antibiotic segment.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Bayer AG |
| Pfizer |
| Novartis AG |
| AstraZeneca |
| Merck & Co. |
| F. Hoffmann-La Roche |
| Bristol-Myers Squibb |
| AbbVie |
| Others |
Value Network & Pricing Analysis
Indian API manufacturing clusters in Maharashtra and Gujarat concentrate fermentation-based bulk drug production, anchoring cost structures that transmit downstream through United States retail pharmacy formulary negotiations. Margin pools sit with vertically integrated manufacturers possessing captive intermediate synthesis, while pure-play finished-dose assemblers absorb pricing compression from consolidated buyers.
Pricing Analysis
FDA abbreviated new drug application pathways dictate the pricing tier structure for first-line antibiotics, separating originator-level nitrofurantoin from economy-tier ampicillin generics. Price differentiation hinges on susceptibility breakpoint certification status and volume scale commitments to pharmacy benefit managers. Cost compression in standard-tier oral formulations is intensifying because retail chains are consolidating formulary control through direct distribution contracts. Hospital procurement committees exhibit lowest price sensitivity due to administered reimbursement rates, while urgent care networks face acute margin pressure from same-day fulfillment requirements.
Supply Chain Analysis
Export control regimes limiting dual-use fermentation technology flows constrain capacity expansion outside established Asian manufacturing zones. Active pharmaceutical ingredient production draws from agricultural feedstock processing in India, chemical intermediate synthesis in China, and finished formulation in United States compounding facilities. Single-source vulnerability concentrates in Jiangsu province beta-lactam intermediate output. Distribution runs through pharmacy benefit manager-controlled wholesale channels to retail fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Uncomplicated UTI treatment sits in early-cycle expansion as telehealth platforms penetrate young adult female demographics previously requiring clinic visits. Single-dose fosfomycin adoption and point-of-care diagnostic convergence represent named tailwinds accelerating penetration beyond traditional empiric prescribing workflows.
For Market Incumbents: Insulate nitrofurantoin supply security through backward integration into nitrofuran intermediates, countering Indian API cost advantages threatening margin structures. Deepen formulary control by embedding stewardship compliance technology within retail pharmacy chain electronic health record systems, neutralizing generic entrants lacking regulatory affairs scale. For New Entrants and Emerging Players: Establish a beachhead in pregnant women segments where EMA pharmacovigilance requirements create compliance moats against undifferentiated generic competition. Target telehealth-integrated pharmacy platforms with single-dose fosfomycin packaging optimized for direct-to-consumer delivery logistics, bypassing traditional wholesale distribution. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian API-to-finished-dose integrators consolidating Maharashtra manufacturing zones. Five-to-ten year viability depends on resistance-pattern therapy portfolios rather than commoditized first-line exposure. Watch FDA susceptibility breakpoint revisions as inflection indicators for nitrofurantoin demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care Diagnostic Integration | Rapid susceptibility testing at urgent care sites enables targeted therapy selection before culture results return. |
| Telehealth Platform Partnership | Asynchronous consultation workflows capture young adult female volume through same-day prescription fulfillment. |
| Backward Integration into Intermediates | Captive nitrofuran synthesis secures supply continuity against Indian API concentration risks. |
| Antimicrobial Stewardship Technology Deployment | AI-enabled resistance prediction algorithms reduce inappropriate broad-spectrum exposure across health systems. |
| Single-Dose Formulation Development | Fosfomycin granule packaging optimized for direct-to-consumer delivery addresses compliance-constrained patient segments. |
Research Methodology
A standing panel of formulary directors, regulatory affairs leads, hospital procurement managers, and payer access specialists provided ongoing calibration against market developments throughout the study period. Primary interviews with these stakeholders combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and pharmacy benefit manager formulary databases. Bottom-up prescription volume modeling and top-down manufacturer revenue triangulation anchored segment-level estimates.
Scenario bracketing around resistance-pattern adoption curves and generic entry timelines structured the analytical framework across the analysis window. Segmentation dimensions modeled include molecular class, delivery mode, patient population, and treatment setting. CAGRs derived from prescription volume trajectories and average selling price evolution, with antimicrobial stewardship mandate intensity and telehealth penetration rates as industry-specific forecast inputs.
Stress conditions across EMA regulatory timeline compression, Indian API supply disruption, and retail pharmacy consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding resistance surveillance protocol evolution and susceptibility breakpoint revision timing. Cross-checking against CMS Medicare Part D utilization data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Urology Surgery Supplies Market
Urology
Transrectal Ultrasound Market
Urology
Varicocele Treatment Market
Urology
Primary Aldosteronism Market
Urology
Global Urinary Tract Infections Therapeutics Market
Urology
Urinary Incontinence Treatment Drugs Market
Urology
Uraemia Treatment Market
Urology
Male Urinary Incontinence Market
Urology
Urinary Tract Infection (UTI) Market
Urology
Urology Lasers Market
Urology
Urology Robotic Surgery Market
Urology
Self-Intermittent Catheters Market
Urology
Nocturia Market
Urology
Urinary Tract Infection Testing Market
Urology
Middle East and Africa Bladder Disorders Market
Urology
Urinary Incontinence Therapeutics Market