
 North America Transrectal Ultrasound Market | 2026-2036
North America Transrectal Ultrasound Market Size, Share, and Industry Trends Forecast 2026-2036
North America Transrectal Ultrasound Market Insights
Aftermarket service revenue is reconfiguring margin pools across the North America transrectal ultrasound landscape. GE HealthCare leverages its extensive installed base to sustain recurring service contracts across major hospital systems. Exact Imaging specializes in high-resolution micro-ultrasound systems that differentiate its portfolio in biopsy guidance applications.
Transrectal ultrasound encompasses endocavitary imaging modalities employing high-frequency transducers, typically operating between 5-12 MHz, to generate real-time visualization of the prostate gland and surrounding tissue for diagnostic and interventional procedures. The technology serves primary commercial purposes in prostate cancer screening, infertility evaluation, and precision-guided tissue sampling. Digital technology segments now lead hardware shipments across the region, while 3D ultrasound systems represent the fastest-expanding product category as clinics adopt volumetric reconstruction for improved lesion characterization. Wireless technology integration is emerging as a distinct margin pool as ambulatory surgical centers prioritize cable-free workflow flexibility.
FDA 510(k) clearance pathways and HIPAA privacy frameworks govern device commercialization and data handling across the United States, while Health Canada and PMRA oversee parallel regulatory requirements for Canadian market access. These frameworks elevate compliance costs for new entrants while reinforcing established manufacturers with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving AI diagnostic algorithm classification guidance from FDA and provincial reimbursement policy shifts in Canada to anticipate access dynamics.
Market Dynamics
AI-enabled image reconstruction is compressing diagnostic timelines across urology practices, forcing established manufacturers to reconfigure hardware-software integration roadmaps while ambulatory surgical centers demand wireless workflow flexibility.
Growth Catalysts
- FDA 510(k) clearance pathway:Pre-market notification requirements for moderate-risk devices accelerate time-to-revenue for manufacturers with established regulatory infrastructure, particularly those targeting prostate biopsy guidance systems.
- Prostate cancer screening protocols:Elevated PSA testing rates among aging male populations in the United States and Canada generate sustained demand for precision-guided tissue sampling capabilities.
- Micro-ultrasound resolution advances:High-frequency transducer arrays operating above 12 MHz now enable real-time visualization of prostatic lesions previously undetectable with conventional imaging.
Market Restraints
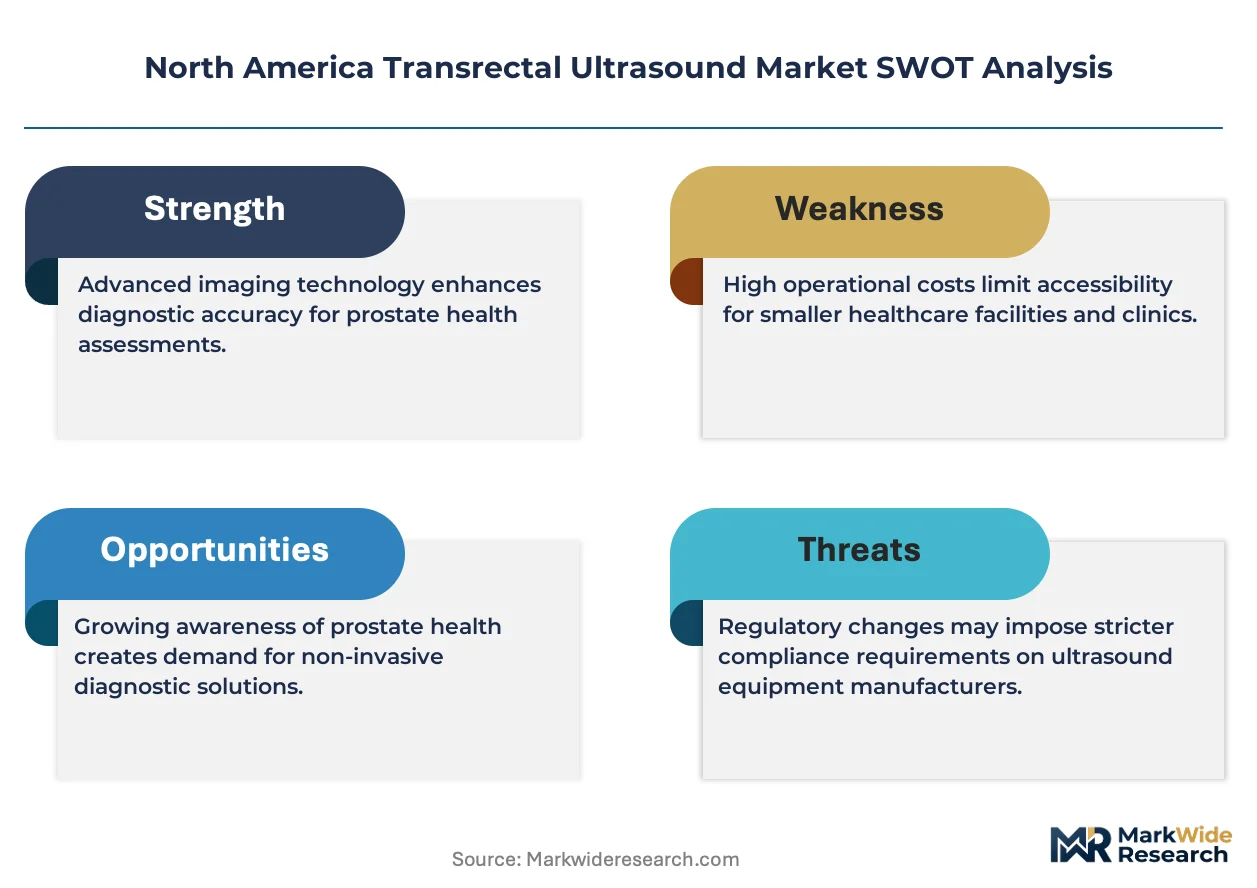
- Capital equipment intensity:Digital 3D ultrasound systems require substantial upfront investment, limiting penetration in independent urology clinics and smaller metropolitan hospital networks.
- HIPAA compliance architecture:Privacy framework mandates elevate data handling costs for AI-enabled diagnostic platforms, particularly those employing cloud-based image reconstruction.
- Specialized operator dependency:High-resolution micro-ultrasound demands trained sonographers with endocavitary imaging expertise, creating bottlenecks in rural and underserved geographies.
Strategic Opportunities
- Canadian provincial reimbursement expansion:Health Canada and PMRA alignment on AI diagnostic algorithm classification creates pathway for technology premium capture in Ontario and British Columbia health systems.
- Ambulatory surgical center wireless integration:Cable-free transducer systems address workflow constraints in same-day biopsy facilities across Texas, Florida, and Arizona metropolitan clusters.
- AI volumetric reconstruction convergence:Machine learning algorithms paired with 3D acquisition hardware enable automated lesion characterization, reducing inter-operator variability in biopsy targeting.
Industry Challenges
- Sonographer certification timelines:Endocavitary ultrasound credentialing through ARDMS and CCI creates workforce pipeline constraints as demand accelerates in specialized prostate cancer centers.
- Legacy PACS integration complexity:Wireless transducer systems require DICOM compatibility layers with existing hospital imaging archives, extending deployment cycles in established health networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Transrectal Ultrasound Market |
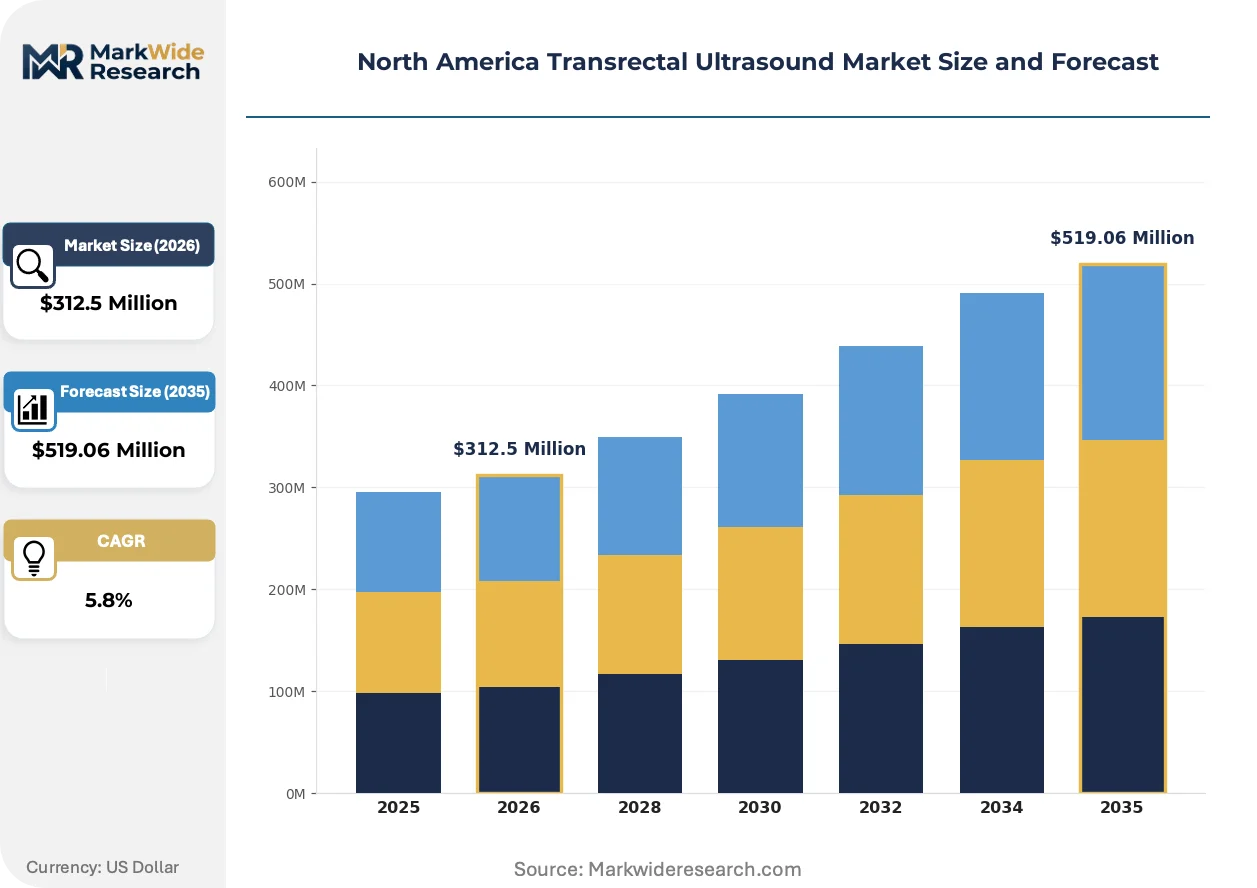
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Ultrasound, 3D Ultrasound, 4D Ultrasound, Doppler Ultrasound End User: Hospitals, Fertility Clinics, Diagnostic Centers, Ambulatory Surgical Centers Technology: Analog Technology, Digital Technology, Hybrid Technology, Wireless Technology Application: Prostate Analysis, Infertility Assessment, Biopsy Guidance, Tumor Detection |
| Companies Covered | GE HealthCare, BK Medical Holding Company, Inc., KOELIS, Exact Imaging, FUJIFILM Corporation, Strata Imaging, Siemens Healthineers, Philips, Canon Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Transrectal Ultrasound Market Trends and Innovations
Real-time fusion imaging capabilities are redefining procedural workflows across North American urology practices, compressing the gap between diagnostic imaging and interventional execution while regulatory frameworks scramble to classify emerging AI diagnostic functions.
Micro-ultrasound systems employing transducer frequencies exceeding 29 MHz are collapsing the resolution differential between transrectal imaging and magnetic resonance for prostatic lesion detection. Major metropolitan hospital networks in California and New York are deploying these platforms for targeted biopsy guidance. The technology is collapsing reliance on multiparametric MRI pre-screening, enabling same-day diagnostic-therapeutic pathways in high-volume urology clinics.
FDA draft guidance on AI-enabled diagnostic algorithms is reshaping software-as-medical-device classification for image reconstruction platforms. Manufacturers must now navigate predicate device selection for machine learning-based lesion detection functions. Canadian provincial health technology assessment bodies are observing FDA determinations closely, creating harmonization pressure for cross-border product submissions.
Aftermarket service unbundling is disrupting traditional equipment financing models across United States hospital networks. Purchasers now separate hardware acquisition from preventive maintenance contracts, pressuring manufacturers to demonstrate remote diagnostics capabilities and compressed technician dispatch timelines. This shift concentrates margin pressure on vendors with limited field service infrastructure in secondary metropolitan markets.
North America Transrectal Ultrasound Market Segmentation
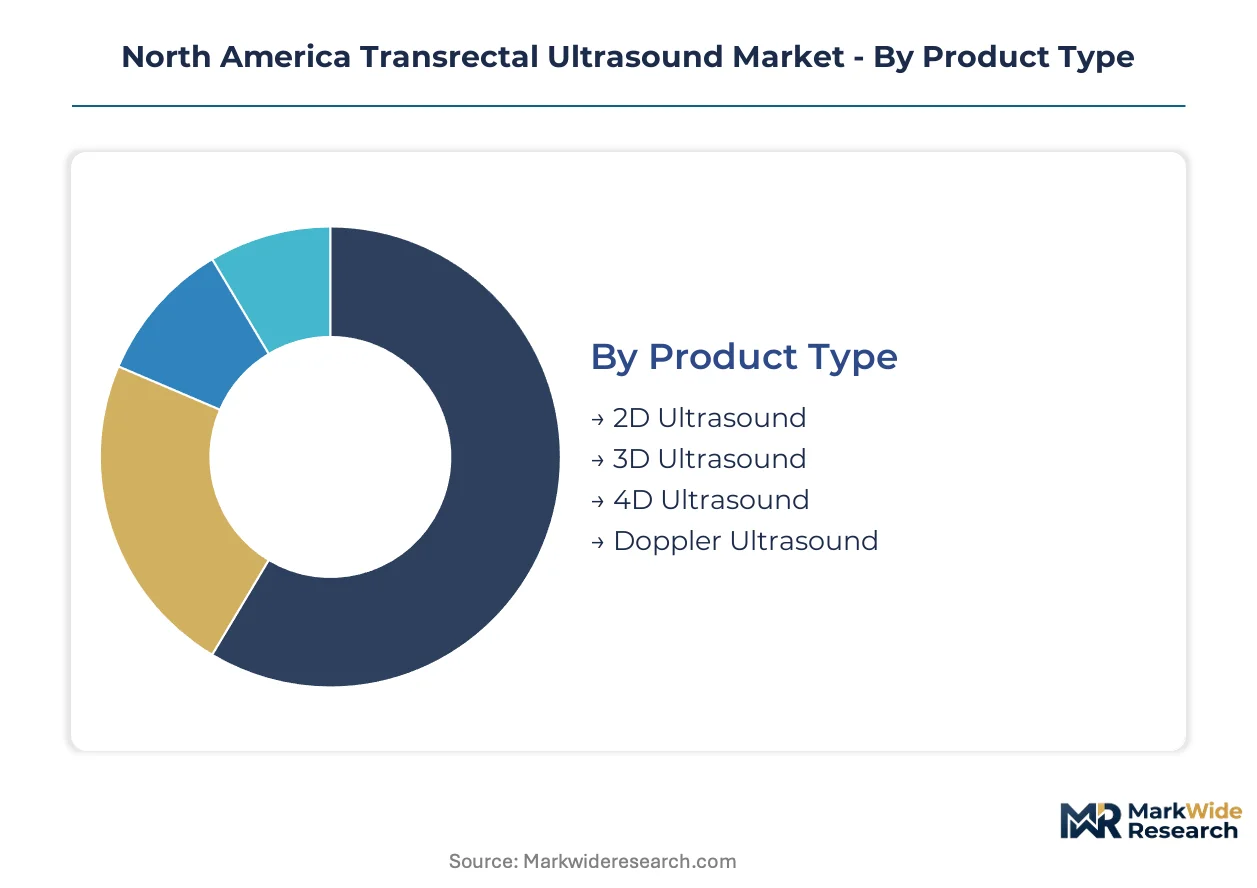
Segmentation in transrectal ultrasound reveals distinct procurement rhythms across hardware generations and care settings. Equipment refresh cycles vary dramatically between hospital networks with capital budgets and ambulatory centers prioritizing workflow flexibility over feature depth.
Product Type:
Replacement cycles stretch from three years for entry 2D systems to seven-plus years for premium 3D platforms, creating asynchronous demand pulses across the installed base.
- 2D Ultrasound:Conventional B-mode imaging systems employing linear array transducers at 5-12 MHz for grayscale prostate visualization. Demand concentrates in independent urology practices across Texas and Arizona where capital constraints delay upgrade timelines. Budget pressure from reimbursement compression extends replacement decisions.
- 3D Ultrasound:Volumetric acquisition platforms reconstructing multiplanar prostate views from rotational or matrix transducer sweeps. Major metropolitan hospital networks in California and New York deploy these for fusion biopsy registration with MRI datasets. Lesion characterization accuracy drives preference over conventional imaging.
- 4D Ultrasound:Real-time volumetric rendering enabling dynamic visualization during interventional procedures. Fertility clinics in Ontario leverage temporal resolution for seminal vesicle assessment.
- Doppler Ultrasound:Color and power Doppler modes mapping prostatic vascularity for tumor angiogenesis assessment. Academic medical centers employ these for research protocols.
2D Ultrasound anchors the volume base while 3D Ultrasound gains share at the steepest rate.
End User:
Procurement authority fragments across centralized hospital supply chains and decentralized clinic ownership, reshaping vendor access economics.
- Hospitals:Integrated delivery networks with dedicated urology departments and in-house pathology. Systems in Illinois and Pennsylvania negotiate enterprise contracts bundling hardware, software, and multi-year service. Capital budget cycles drive concentrated purchasing windows.
- Fertility Clinics:Specialized reproductive medicine centers requiring seminal vesicle and ejaculatory duct imaging. Facilities in Florida and British Columbia prioritize compact footprint systems for limited procedure room space. Patient volume seasonality creates irregular demand patterns.
- Diagnostic Centers:Independent imaging facilities performing outsourced prostate screening. Medicare reimbursement rates determine equipment tier selection.
- Ambulatory Surgical Centers:Same-day biopsy facilities demanding wireless transducer systems for rapid room turnover. Arizona and Texas metropolitan clusters lead adoption.
Hospitals command the largest revenue pool while Ambulatory Surgical Centers expand most quickly.
Technology:
Migration curves from analog to digital architectures diverge by customer sophistication and legacy infrastructure lock-in.
- Analog Technology:Legacy beamforming systems with hardware-dependent image processing. Rural and underserved geographies retain these for cost containment.
- Digital Technology:Software-defined platforms with programmable transmit-receive chains and post-processing flexibility. Digital Technology leads hardware shipments across the region as clinics replace aging analog systems.
- Hybrid Technology:Mixed-signal architectures blending analog front-ends with digital back-ends for cost-optimized performance. Mid-tier hospital networks balance capability against budget constraints.
- Wireless Technology:Cable-free transducer-to-console links using proprietary or standard wireless protocols. Wireless Technology integration is emerging as a distinct margin pool as ambulatory surgical centers prioritize cable-free workflow flexibility.
Digital Technology dominates current procurement while Wireless Technology climbs the fastest.
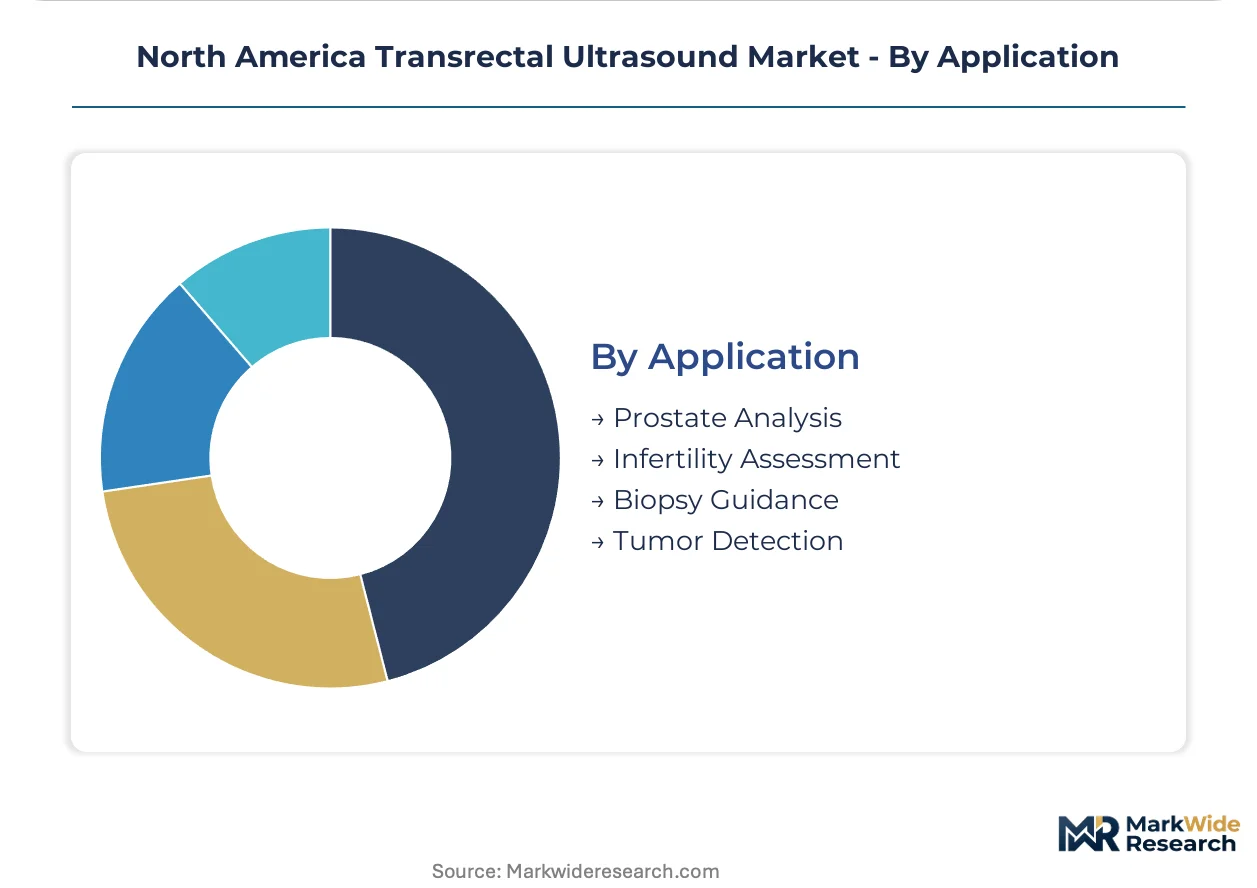
Application:
Clinical utility intensity varies from screening workflows with high throughput to interventional procedures demanding precision instrumentation.
- Prostate Analysis:General gland assessment for benign prostatic hyperplasia, volume measurement, and morphology evaluation. High screening volumes in United States metropolitan networks sustain baseline demand.
- Infertility Assessment:Evaluation of seminal vesicles, ejaculatory ducts, and vas deferens patency. Canadian fertility networks in Ontario and Quebec drive specialized system configurations.
- Biopsy Guidance:Real-time needle tracking for systematic or targeted tissue sampling. Biopsy Guidance applications are seeing rising adoption among urology practices as fusion imaging becomes standard.
- Tumor Detection:Lesion identification and characterization for cancer staging. Academic centers employ high-frequency micro-ultrasound for research applications.
Prostate Analysis underpins installed base utilization while Biopsy Guidance captures the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across North American procurement channels. Hospital networks in major metropolitan areas absorb premium pricing for advanced imaging platforms, while independent urology practices in secondary markets defer capital expenditures amid reimbursement compression.
United States
FDA 510(k) clearance pathways accelerate commercialization for biopsy guidance systems targeting elevated PSA screening volumes. HIPAA privacy frameworks elevate compliance costs for cloud-based AI reconstruction platforms. Major metropolitan hospital networks in California and New York deploy high-frequency micro-ultrasound for same-day diagnostic pathways.
Canada
Provincial health technology assessment bodies in Ontario and British Columbia observe FDA AI classification determinations for harmonized submissions. Health Canada and PMRA oversight creates cross-border alignment pressure for software-as-medical-device registrations. Specialized prostate cancer centers in Toronto and Vancouver concentrate adoption of fusion imaging capabilities.
Mexico
COFEPRIS regulatory pathways for moderate-risk devices attract manufacturers seeking abbreviated approval timelines relative to FDA processes. Public hospital procurement through INSABI channels prioritizes cost-optimized 2D systems over premium 3D platforms. Guadalajara and Monterrey metropolitan clusters emerge as private healthcare imaging demand centers.
North America Transrectal Ultrasound Market Competitive Landscape
Diversified imaging conglomerates and specialized urology equipment developers split the market across distinct capability vectors. Consolidation pressure concentrates around installed base leverage and regulatory affairs infrastructure, with tiered competition separating premium fusion imaging providers from value-positioned hardware suppliers. Dominant competitive moves include strategic partnerships for AI algorithm integration and geographic expansion through regional distributor networks.
Among diversified healthcare technology conglomerates, GE HealthCare and Siemens Healthineers occupy positions reflecting extensive field service infrastructure and enterprise contract negotiation scale. Specialized urology imaging developers including Exact Imaging and KOELIS exemplify focused innovation archetypes targeting high-resolution biopsy guidance applications. FUJIFILM Corporation and Canon Medical Systems represent diversified imaging portfolio players with cross-modal technology transfer capabilities. Philips anchors the premium-tier vector through integrated diagnostic workflow solutions spanning ultrasound through MRI fusion platforms.
| Leading Market Players |
|---|
| GE HealthCare |
| BK Medical Holding Company, Inc. |
| KOELIS |
| Exact Imaging |
| FUJIFILM Corporation |
| Strata Imaging |
| Siemens Healthineers |
| Philips |
| Canon Medical Systems |
| Others |
Pricing and Supply Chain Analysis
FDA 510(k) premarket notification chokepoints concentrate regulatory leverage among established manufacturers, compressing pricing tier spreads between premium fusion imaging systems and entry-level 2D platforms while forcing supply chain consolidation around compliant component sourcing.
Pricing Analysis
Aftermarket service contracts and extended warranty tiers drive lifetime value capture across the installed base. Three-tier pricing structure across premium, standard, and economy levels separates AI-enabled 3D fusion systems from digital mid-range platforms and legacy analog hardware. Price differentiation hinges on FDA clearance tier and field service infrastructure density. Cost compression in the standard tier intensifies because ambulatory surgical centers unbundle preventive maintenance from hardware acquisition. Independent urology practices in secondary metropolitan markets exhibit highest price sensitivity, while integrated delivery networks in California and New York absorb premium positioning.
Supply Chain Analysis
Export-control restrictions on high-frequency transducer arrays and precision piezoelectric ceramics limit component flows from specialized Asian manufacturing hubs. Supply concentration centers on Japan, South Korea, and Germany for transducer fabrication, with China dominating rare-earth magnet sourcing for Doppler assemblies. Raw material dependencies include lead zirconate titanate crystals, medical-grade silicone housings, and FPGA chipsets for beamforming. Single-source vulnerability in 29 MHz micro-ultrasound transducer supply creates bottleneck risk for next-generation biopsy guidance platforms. Distribution runs through authorized dealer networks serving hospital GPO contracts and direct manufacturer relationships with specialized prostate cancer centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA 510(k) clearance infrastructure creates a defensive moat that rewards early compliance investment and punishes late entrants lacking predicate device portfolios.
For Market Incumbents: Build switching-cost moats through embedded AI algorithm training on hospital-specific imaging datasets. Deepen backward integration into transducer manufacturing to secure supply continuity against Asian component bottlenecks. Consolidate position by acquiring specialized micro-ultrasound developers before Health Canada harmonizes AI classification pathways. Threat substitution from MRI fusion platforms demands continuous resolution advancement in the 20-30 MHz range. For New Entrants and Emerging Players: Establish a beachhead in wireless transducer systems for ambulatory surgical centers across Texas and Arizona metropolitan clusters. Target the Canadian provincial reimbursement expansion pathway in Ontario and British Columbia where FDA alignment creates accelerated market access. Penetrate the fertility clinic segment in Florida and British Columbia with compact footprint systems designed for limited procedure room space. Go-to-market leverage rests on demonstrating DICOM compatibility with legacy PACS infrastructure. For Investors and Strategic Acquirers: FDA draft guidance on AI-enabled diagnostic algorithms reshapes the acquisition landscape toward software-as-medical-device capabilities. Long-term viability favors platforms combining hardware-software integration with recurring service revenue streams. Target acquisition archetype: specialized urology imaging developers with Health Canada submissions pending and established clinical validation datasets. Signal to watch: provincial health technology assessment body determinations on AI diagnostic premium reimbursement.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm FDA Submission | Machine learning-based lesion detection functions require predicate device navigation under draft FDA guidance. |
| Wireless Transducer Development | Cable-free systems address workflow constraints in Arizona and Texas ambulatory surgical center clusters. |
| Hospital System Partnership | Enterprise contracts with Illinois and Pennsylvania integrated delivery networks bundle hardware, software, and service. |
| Canadian Provincial Reimbursement Strategy | Health Canada and PMRA alignment on AI classification creates premium capture pathways in Ontario health systems. |
| Micro-Ultrasound Resolution Advancement | Transducer frequencies exceeding 29 MHz collapse the resolution differential with multiparametric MRI pre-screening. |
Research Methodology
Two parallel data streams informed the analysis: primary intelligence gathering and secondary source validation. Primary interviews with urology department heads, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and ARDMS-certified sonographers captured procurement dynamics and workflow constraints. Secondary sources included FDA 510(k) clearance databases, Health Canada MDALL registrations, hospital procurement contract disclosures, CMS Medicare reimbursement schedules, and GPO equipment utilization reports. Bottom-up installed base modeling and top-down market sizing triangulated volume and value estimates.
Forecast inputs spanned technology migration curves from analog to digital architectures, replacement cycle timing across 2D and 3D platform generations, and provincial reimbursement policy trajectories in Canada. Segmentation dimensions modeled included product type, end user category, technology generation, and application intensity across the projection horizon. CAGRs derived from equipment shipment trends, service contract renewal rates, and AI-enabled upgrade penetration assumptions. Industry-specific inputs incorporated sonographer certification pipeline constraints and PACS integration deployment timelines.
Stress conditions across FDA AI classification timeline delays, transducer component tariff exposure, and provincial reimbursement compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on technology substitution rates and regulatory harmonization progress. Material shifts in Health Canada AI diagnostic algorithm classification or HIPAA cloud infrastructure mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Global Lithotripsy Market
Urology
Cystectomy Market
Urology
India Urology Market
Urology
Self-Intermittent Catheters Market
Urology
Middle East and Africa Bladder Disorders Market
Urology
Genitourinary Cancers Treatment Market
Urology
Hematuria Treatment Market
Urology
Voiding Cystourethrogram Market
Urology
Urethral Stricture Market
Urology
Urinary Bag Market
Urology
Ureteral Obstruction Market
Urology
Obstructive Uropathy Treatment Market
Urology
Pelvic Cancer Induced Hemorrhegic Cystitis Market
Urology
Nephrology and Urology Incontinence Devices Market
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market
Urology
Uncomplicated Urinary Tract Infection Treatment Market