
 Heart Defect Closure Devices Market | 2026-2036
Heart Defect Closure Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Defect Closure Devices Market Analysis
A capital-intensity divergence between established manufacturers and emerging competitors is reorganizing competitive dynamics in heart defect closure devices. Abbott Laboratories leverages vertically integrated nitinol supply chains to sustain manufacturing scale across septal occluder portfolios. Boston Scientific Corporation anchors its position through catheter-based delivery system specialization. MicroPort Scientific Corporation competes on cost-optimized production for Asia-Pacific distribution.
Heart defect closure devices are implantable cardiac prostheses, typically constructed from nitinol wire mesh with polyester fabric patches, designed to achieve hemodynamic isolation of congenital septal defects or patent ductus arteriosus through transcatheter or surgical placement. These devices function by promoting endothelialization across the defect while maintaining structural integrity under cardiac cycle stress. Septal occluders dominate current revenue pools due to established reimbursement for atrial septal defect closure, while biodegradable devices represent the fastest-expanding technology segment as absorbable polymers eliminate permanent foreign body retention. Pediatric applications command premium positioning due to smaller anatomical requirements and longer device dwell times, though adult patient volumes exceed pediatric cases in absolute terms.
FDA premarket approval requirements and EU MDR conformity assessment procedures impose substantial clinical trial burdens on novel device entrants, effectively filtering market access to well-capitalized manufacturers. China's NMPA innovation pathway accelerates review for domestically developed transcatheter devices, reshaping competitive geography. ISO 13485 quality management certification remains mandatory for supply eligibility to hospital procurement systems across all major markets. Stakeholders must monitor evolving biodegradable polymer durability data and regional reimbursement decisions for hybrid closure techniques.
Market Dynamics
Biodegradable polymer technology is bifurcating device development pipelines, forcing established nitinol-dependent manufacturers to dual-track absorbable and permanent implant portfolios while navigating divergent regulatory evidence requirements.
Growth Catalysts
- EU MDR conformity assessment:The tightened clinical evidence framework for implantable cardiac devices elevates barriers for marginal competitors, consolidating procurement decisions around manufacturers with robust quality management systems.
- Pediatric catheterization lab expansion:Tertiary cardiac centers in the United States, Germany, and China are adding dedicated pediatric interventional suites, creating concentrated demand nodes for smaller-diameter delivery systems.
- Transcatheter technique maturation:Improved imaging guidance and operator training protocols reduce procedure variability, expanding treatable patient populations beyond traditional surgical candidates.
Market Restraints
- Nitinol raw material concentration:Superelastic nickel-titanium alloy supply chains concentrate among specialized metallurgical processors, exposing device manufacturers to input cost volatility and alloying specification inconsistencies.
- FDA premarket approval timelines:The PMA pathway for novel septal occluder designs demands extended follow-up periods, compressing effective patent life and delaying revenue recognition for innovation investments.
- Biodegradable durability uncertainty:Absorbable polymer mechanical performance under cyclic cardiac loading remains incompletely characterized, limiting insurer willingness to extend coverage parity with established permanent devices.
Strategic Opportunities
- China NMPA innovation pathway:The accelerated review track for domestically developed transcatheter devices enables faster market entry for manufacturers with localized clinical trial infrastructure and manufacturing partnerships.
- Hybrid closure technique reimbursement:Emerging procedural codes combining surgical and catheter-based approaches in select European markets create new service-line revenue pools for integrated cardiac centers.
- Adult congenital heart disease:The expanding survivor population from pediatric interventions requires defect closure or re-intervention, representing an underpenetrated application segment with distinct anatomical and device sizing requirements.
Industry Challenges
- Pediatric interventional cardiologist scarcity:The specialized training pipeline produces insufficient operators to match catheterization lab capacity expansion, creating procedural throughput bottlenecks.
- ISO 13485 certification maintenance:The quality management system standard requires continuous audit readiness and documentation control, consuming operational resources disproportionately for smaller device developers.
- Biodegradable endothelialization modeling:Predictive simulation of tissue ingrowth kinetics for absorbable polymers lacks validated computational frameworks, complicating device design optimization and regulatory submission preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Defect Closure Devices Market |
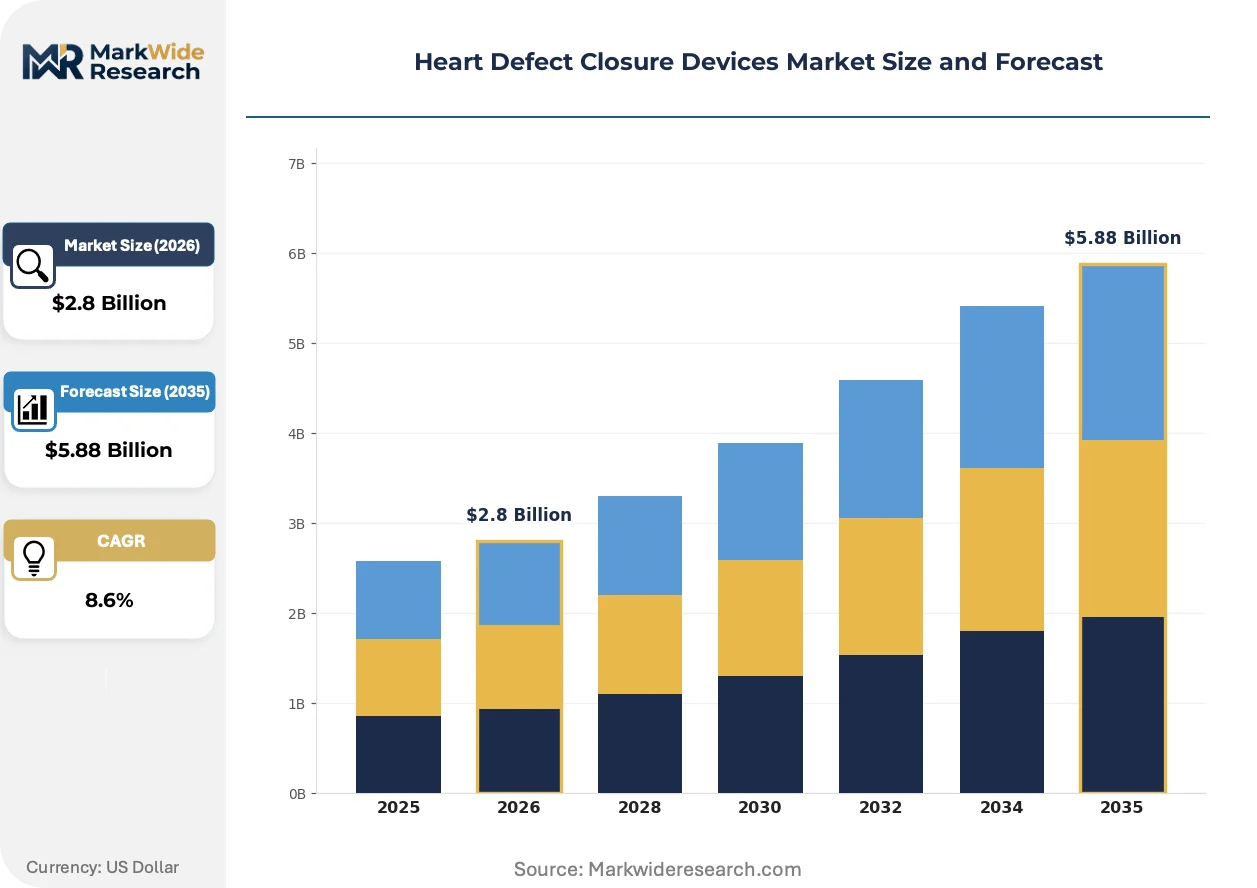
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Septal Occluders, Patent Ductus Arteriosus Devices, Atrial Septal Defect Devices, Ventricular Septal Defect Devices End User: Hospitals, Cardiology Clinics, Surgical Centers, Research Institutions Technology: Transcatheter Closure, Surgical Closure, Hybrid Techniques, Biodegradable Devices Application: Pediatric Patients, Adult Patients, Emergency Cases, Elective Procedures |
| Companies Covered | W. L. Gore & Associates, LifeTech Scientific, Abbott Laboratories, MicroPort Scientific Corporation, Lepu Medical Technology, Boston Scientific Corporation, Occlutech, Cardia Inc, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Defect Closure Devices Market Emerging Trajectories
Device architecture is diverging along material permanence lines, with absorbable polymers challenging nitinol dominance while regulatory frameworks struggle to adapt evidence standards to degradable implant lifecycles.
Biodegradable septal occluders constructed from polylactic acid and polycaprolactone copolymers are bifurcating the product development landscape. Pediatric cardiology centers in Germany and Switzerland are piloting these devices in younger patients where permanent foreign body retention carries lifetime complication risks. The technology is bifurcating manufacturer R&D allocation, forcing parallel investment in both absorbable platforms and next-generation nitinol designs rather than sequential replacement strategies.
The EU MDR framework is tightening post-market surveillance obligations for Class III implantable cardiac devices. Manufacturers must now maintain systematic clinical follow-up registries and periodic safety update reporting, increasing compliance infrastructure costs. Pediatric applications face the steepest documentation burdens due to longer device dwell times and evolving anatomical growth considerations.
Hospital procurement is consolidating around value-analysis committees that bundle device selection with operator training and procedural support commitments. Tertiary cardiac centers in the United States are negotiating multi-year supply agreements incorporating case volume guarantees and outcomes data sharing. This restructuring most visibly concentrates purchasing authority at academic medical centers with established congenital heart programs.
Heart Defect Closure Devices Market Segmentation
Device selection in heart defect closure flows through distinct procurement channels shaped by procedure complexity, reimbursement pathways, and center specialization. Segmentation reveals where pricing power concentrates and which patient populations drive volume expansion.
Product Type:
Channel distribution varies sharply by product complexity, with septal occluders flowing through high-volume catheterization labs while specialized defect devices concentrate at surgical referral centers.
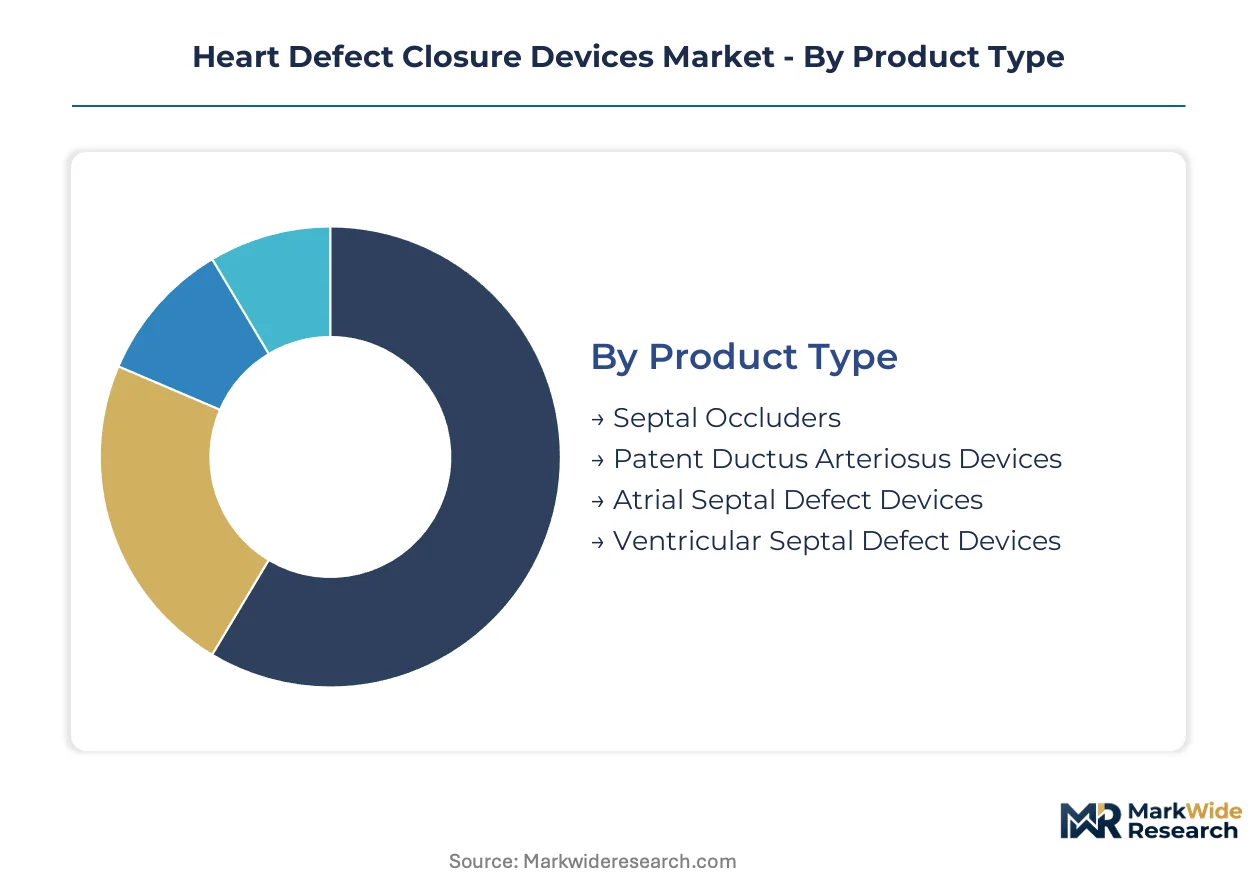
- Septal Occluders:Nitinol wire mesh constructs with polyester fabric patches dominate catheter-based atrial and ventricular septal defect closures. Demand concentrates at tertiary pediatric cardiology centers in the United States, Germany, and China where transcatheter volumes justify dedicated inventory contracts.
- Patent Ductus Arteriosus Devices:Coil and plug configurations designed for ductal anatomy require smaller delivery systems. Growth concentrates in neonatal intensive care units where minimally invasive approaches reduce surgical morbidity in premature infants.
- Atrial Septal Defect Devices:Self-expanding double-disc designs with waist configurations adapt to variable septal anatomy.
- Ventricular Septal Defect Devices:Higher-profile constructs address thicker muscular or perimembranous septal tissue with greater structural loading requirements.
By volume, septal occluders lead. By growth pace, patent ductus arteriosus devices are climbing the fastest as neonatal intervention protocols expand.
End User:
Procurement authority shifts toward value-analysis committees at integrated delivery networks, compressing margins for standalone surgical centers while academic hospitals negotiate bundled service agreements.
- Hospitals:Tertiary cardiac centers with congenital heart programs perform the highest procedural volumes and maintain captive device inventories. Pediatric catheterization lab expansion at academic medical centers in the United States and Germany creates concentrated demand nodes for manufacturer field support teams.
- Cardiology Clinics:Outpatient-based interventional cardiology practices handle diagnostic workup and post-procedural surveillance. These sites drive referral patterns to surgical centers but rarely maintain implant stock.
- Surgical Centers:Freestanding facilities focus on elective adult congenital cases with lower complexity profiles.
- Research Institutions:Academic medical centers with NIH or EU-funded trials pilot biodegradable device platforms and hybrid techniques.
Hospitals capture the revenue concentration. Cardiology clinics are expanding their procedural influence fastest through referral network consolidation.
Technology:
Cost tier stratification separates established permanent implants from emerging absorbable platforms, with hybrid techniques commanding premium reimbursement in select European markets.
- Transcatheter Closure:Catheter-based deployment through femoral or jugular access has become the standard of care for suitable anatomies. Operator training protocols and imaging guidance improvements at centers in Switzerland and the Netherlands reduce procedure variability and expand treatable populations.
- Biodegradable Devices:Polylactic acid and polycaprolactone copolymers eliminate permanent foreign body retention. Pediatric applications in Germany and Switzerland are piloting these platforms where lifetime complication risks from permanent implants weigh heaviest.
- Surgical Closure:Direct suture or patch repair remains necessary for complex anatomies unsuitable for catheter approaches.
- Hybrid Techniques:Combined surgical and catheter-based approaches in single procedures.
Transcatheter closure leads by procedure volume. Biodegradable devices are gaining share fastest as pediatric centers prioritize absorbable platforms.
Application:
Patient age and acuity determine device sizing requirements, reimbursement coding, and the regulatory evidence burden for manufacturers seeking expanded indications.
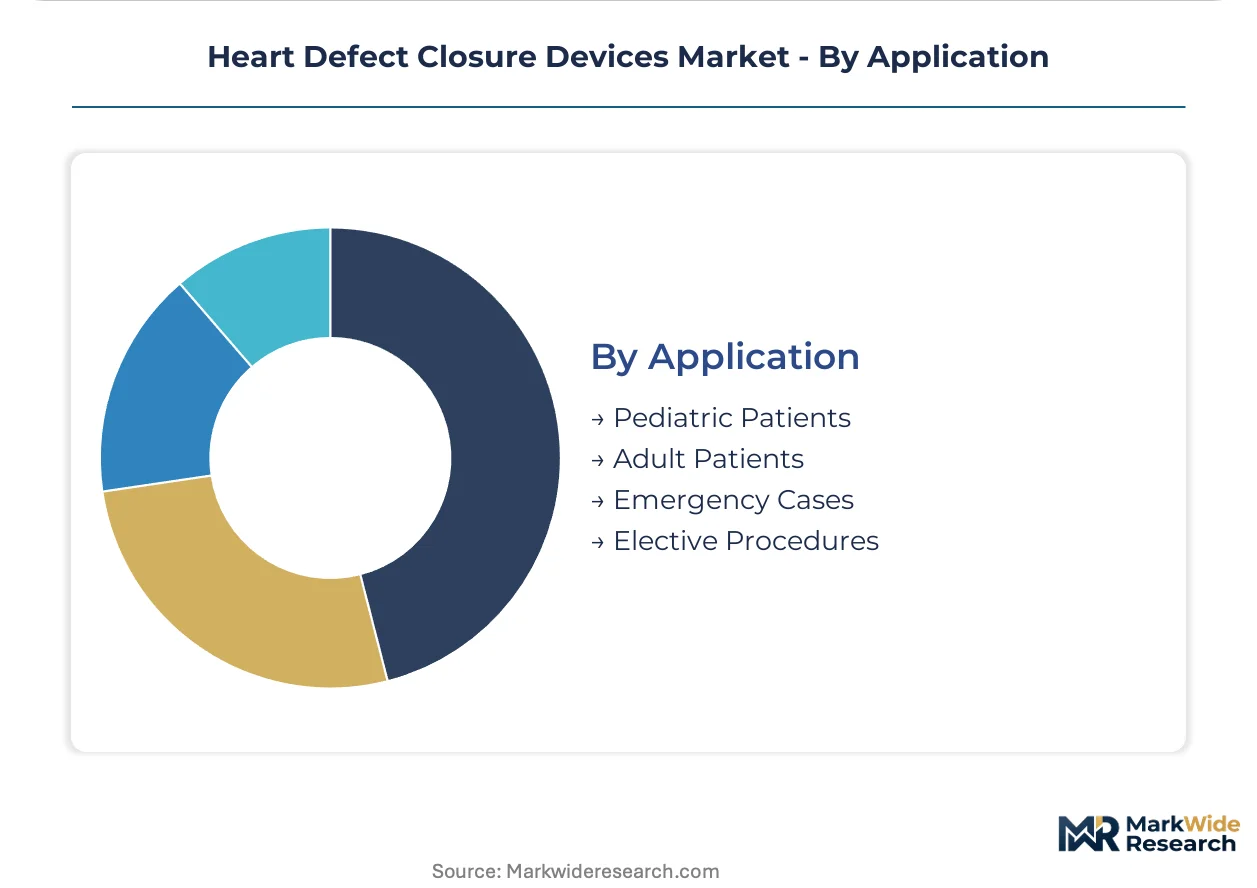
- Pediatric Patients:Smaller anatomical requirements and longer device dwell times command premium positioning and specialized delivery system diameters. Centers in the United States and China are adding dedicated pediatric interventional suites to match operator training pipeline output.
- Adult Patients:The expanding survivor population from prior pediatric interventions requires defect closure or re-intervention with distinct anatomical considerations. This segment exceeds pediatric cases in absolute volume but faces reimbursement compression.
- Emergency Cases:Acute presentations requiring urgent defect stabilization.
- Elective Procedures:Scheduled interventions with comprehensive pre-procedural imaging and patient optimization.
Adult patients lead by absolute volume. Pediatric applications are expanding most quickly as catheterization lab capacity additions outpace general cardiac procedure growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss tertiary cardiac centers where bundled reimbursement for hybrid procedures commands premiums, while Chinese procurement through provincial volume-based purchasing compresses margins for standard septal occluders.
United States
Pediatric catheterization lab expansion at academic medical centers drives concentrated demand for smaller-diameter delivery systems. FDA premarket approval pathways impose extended clinical follow-up requirements that filter market access to well-capitalized manufacturers. Boston and Philadelphia anchor the highest procedural volumes through established congenital heart programs.
Germany
Biodegradable device pilot programs at pediatric centers in Munich and Heidelberg reshape procurement priorities for absorbable polymer platforms. EU MDR conformity assessment procedures elevate quality management system requirements for implantable cardiac devices. The country's statutory health insurance system maintains reimbursement parity between transcatheter and hybrid closure techniques.
China
Provincial volume-based purchasing for standard septal occluders compresses pricing while the NMPA innovation pathway accelerates review for domestically developed transcatheter devices. Shanghai and Beijing tertiary cardiac centers perform the highest absolute volumes of pediatric closures. Local manufacturing partnerships enable faster market entry for regional competitors.
Switzerland
Pediatric cardiology centers in Zurich and Geneva pioneer biodegradable septal occluder applications where lifetime foreign body retention risks weigh heaviest. Swissmedic maintains alignment with EU MDR standards while offering streamlined review for breakthrough device designations. The country's concentrated purchasing authority at university hospitals enables rapid adoption of novel platforms.
Japan
PMDA consultation pathways for novel implantable devices require extensive durability data that extends premarket timelines for biodegradable platforms. Tokyo and Osaka academic medical centers concentrate the national volume of adult congenital heart disease re-interventions. Reimbursement pricing for transcatheter closures remains tethered to surgical procedure benchmarks.
Heart Defect Closure Devices Market Vendor Landscape
Concentration sits with diversified medical technology conglomerates that leverage vertically integrated nitinol supply chains and established catheter-based delivery system expertise. The vendor base organizes around three strategic archetypes: integrated nitinol processors commanding manufacturing scale, catheter specialization firms anchoring interventional technique maturation, and cost-optimized regional manufacturers competing on Asia-Pacific distribution economics. Dominant competitive moves include dual-track R&D allocation across permanent and biodegradable portfolios and multi-year supply agreements bundling device procurement with operator training commitments.
Among diversified medical technology conglomerates, Abbott Laboratories and Boston Scientific Corporation exemplify the integrated-device archetype, while MicroPort Scientific Corporation occupies a position within the cost-optimized regional tier. Abbott Laboratories represents backward integration into superelastic alloy processing, Boston Scientific Corporation anchors catheter-based delivery specialization, and MicroPort Scientific Corporation exemplifies Asia-Pacific manufacturing scale. These three firms illustrate how competitive positioning fragments across material control, interventional technique, and geographic cost structure rather than consolidating around a single dominant model.
| Leading Market Players |
|---|
| W. L. Gore & Associates |
| LifeTech Scientific |
| Abbott Laboratories |
| MicroPort Scientific Corporation |
| Lepu Medical Technology |
| Boston Scientific Corporation |
| Occlutech |
| Cardia Inc |
| Medtronic plc |
| Others |
Supply Flow & Price Mechanics
Biodegradable polymer substitution for nitinol wire mesh is redrawing procurement geography and compressing premium pricing tiers as absorbable platforms eliminate permanent foreign body value propositions. German and Swiss pediatric centers now pilot polylactic acid devices at price points that undercut established nitinol constructs, while Chinese provincial volume-based purchasing accelerates cost convergence for standard septal occluders.
Pricing Analysis
Configured-to-order pricing for patient-specific device sizing commands substantial premiums over standard catalog configurations, particularly in pediatric applications requiring smaller-diameter delivery systems. Price differentiation hinges on ISO 13485 certification tier and bundled operator training commitments, with academic medical centers negotiating multi-year agreements that embed procedural support services. Cost compression in standard septal occluders is intensifying because Chinese provincial procurement aggregates demand across tertiary cardiac centers. Neonatal intensive care units exhibit highest price sensitivity due to constrained reimbursement bandwidth, while hybrid closure centers in Germany demonstrate lowest sensitivity given statutory reimbursement parity.
Supply Chain Analysis
Inventory cycles for nitinol raw materials extend delivery timelines for specialized alloy specifications, forcing manufacturers to maintain captive safety stock against metallurgical processor scheduling constraints. Superelastic nickel-titanium alloy supply concentrates in the United States, Germany, and China, with device fabrication drawing from polyester fabric patch suppliers in Switzerland and polymer resin processors in Japan. Single-source vulnerability pervades superelastic alloy specification control, where minor compositional variations compromise device fatigue resistance. Distribution runs through hospital value-analysis committees at integrated delivery networks, compressing standalone surgical center access to manufacturer field support teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent manufacturers face substitution defense imperatives as biodegradable platforms threaten to commoditize permanent implant value propositions and erode nitinol-dependent margin structures.
For Market Incumbents: Compound defensive positioning through dual-track R&D allocation across absorbable polymer platforms and next-generation nitinol fatigue-resistant architectures. Secure backward integration into superelastic alloy processing to insulate against raw material specification volatility. Prioritize ISO 13485 certification maintenance as EU MDR post-market surveillance obligations elevate compliance infrastructure costs for marginal competitors.
For New Entrants and Emerging Players: Lead with adult congenital heart disease re-intervention applications where anatomical complexity from prior surgical repairs creates white-space demand underserved by established pediatric-focused portfolios. Target cardiology clinic referral networks that channel patients to surgical centers but lack direct implant procurement authority, embedding device selection influence upstream of hospital value-analysis committees.
For Investors and Strategic Acquirers: Capital is best deployed toward catheter-based delivery system specialists with proprietary imaging integration capabilities that anchor interventional technique maturation. Long-term viability across the analysis window favors manufacturers with demonstrated biodegradable polymer endothelialization data and regulatory submission experience in multiple jurisdictions. Monitor NMPA innovation pathway approval velocity as inflection indicator for China market access competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Extended clinical follow-up requirements filter market access to well-capitalized manufacturers with trial infrastructure. |
| EU MDR Conformity Assessment | Post-market surveillance obligations for Class III devices elevate compliance costs and consolidate procurement authority. |
| Hospital System Partnership | Multi-year supply agreements bundling device procurement with operator training commitments concentrate purchasing power. |
| Biodegradable Platform Development | Absorbable polymer R&D addresses lifetime foreign body retention risks in pediatric applications with longest dwell times. |
| Reimbursement Strategy | Hybrid closure technique coding in select European markets creates premium service-line revenue pools for integrated centers. |
Methodological Framework
A standing panel of pediatric interventional cardiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA premarket approval filings, EU MDR technical documentation databases, NMPA innovation pathway decisions, and hospital procurement contract registries. Bottom-up procedure volume estimates from catheterization lab capacity surveys triangulated against top-down device shipment data from national regulatory filings.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window, with segmentation modeling spanning product type complexity tiers, end-user procurement channel authority, technology permanence categories, and patient age-acuity applications. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns, incorporating biodegradable polymer durability data maturation and regional reimbursement decision timelines as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA, EU MDR, and NMPA regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Tinnitus Maskers Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
Dysphagia Management Market
Medical Devices
South America Single-Use Medical Device Reprocessing Market
Medical Devices
China Anesthesia Devices Market
Medical Devices
North America Sperm Separation Devices Market
Medical Devices
Radial Compression Devices Market
Medical Devices
Global Spinal Motion Preservation Device Market
Medical Devices
Electronic Nasal Spray Devices Market
Medical Devices
Airway Management Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Neurofeedback Systems Market
Medical Devices
MRI Safe Defibrillator Market
Medical Devices
Global High-Flow Nasal Cannula Market
Medical Devices
Repositioning and Offloading Devices Market
Medical Devices
Liquid Oxygen Devices Market