
 Global Glucose Monitoring Devices Market | 2026-2036
Global Glucose Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Glucose Monitoring Devices Market Analysis
Silicon-based MEMS fabrication is broadening the economic viability of microneedle glucose sensors against traditional electrochemical strips. Dexcom, Inc. leverages proprietary factory automation to sustain cost leadership in continuous glucose monitor production. Abbott Laboratories anchors its competitive position through vertically integrated sensor chemistry and consumer-facing pharmacy distribution. Medtronic plc navigates hospital procurement complexity with institutional sales teams that control access to integrated insulin pump ecosystems.
Glucose monitoring devices are electrochemical or optical instruments that measure interstitial fluid or capillary blood glucose concentration, typically operating within a measurement range of 20 to 600 mg/dL with calibration protocols that vary by sensing modality. Their primary commercial purpose is to enable real-time glycemic management for insulin-dependent and non-insulin-dependent diabetes patients across clinical and non-clinical environments. Continuous glucose monitors command the dominant margin pool due to recurring sensor replacement cycles, while flash glucose monitoring systems represent the fastest-expanding category as pharmacy channels in Europe and North America expand over-the-counter availability. Blood glucose meters retain volume leadership in emerging markets where cost sensitivity shapes procurement decisions by ministries of health.
The FDA regulates these devices under 21 CFR Part 820 quality system requirements and increasingly applies software-as-a-medical-device frameworks to algorithm-driven glucose prediction tools. EMA's Medical Device Regulation enforces stricter clinical evidence standards for CE-marked continuous monitoring systems entering European markets. ISO 15197 accuracy standards for blood glucose meters shape competitive differentiation as payers in Germany and France tie reimbursement to independent laboratory validation. Stakeholders must monitor how FDA pre-certification pathways for artificial-intelligence-enabled glucose prediction alter the competitive balance between established sensor manufacturers and digital health entrants.
Market Dynamics
Reimbursement policy divergence between single-payer and multi-payer health systems is fragmenting commercial strategy for continuous glucose monitor manufacturers, forcing parallel regulatory filings and pricing architectures.
Growth Catalysts
- MDR Clinical Evidence Requirements:The European Medical Device Regulation mandates robust performance validation for CE-marked continuous monitoring systems, accelerating quality differentiation among compliant suppliers.
- Homecare Self-Management:Patients with Type 1 and Type 2 diabetes are migrating monitoring activity from clinical settings to residential environments, expanding addressable volume for consumer-form-factor devices.
- Silicon MEMS Fabrication:Semiconductor manufacturing processes are reducing unit economics for microneedle sensor arrays against legacy electrochemical strip production.
Market Restraints
- Precious Metal Input Volatility:Platinum and silver electrode materials expose sensor manufacturers to commodity price swings that compress gross margins on disposable components.
- Single-Source Enzyme Supply:Glucose oxidase and glucose dehydrogenase biochemistry concentrates among three specialized fermentation suppliers, creating qualification bottlenecks for new market entrants.
- Calibration Protocol Heterogeneity:Incompatible factory-calibration standards between continuous and flash monitoring systems prevent interoperability and lock patients into single-vendor ecosystems.
Strategic Opportunities
- Pharmacy Channel Expansion:Over-the-counter availability in German and French retail pharmacy networks is opening direct-to-consumer pathways previously blocked by prescription requirements.
- Algorithm-Enabled Prediction:FDA pre-certification pathways for software-as-a-medical-device glucose forecasting tools are lowering regulatory barriers for digital health entrants with AI-driven analytics.
- Integrated Insulin Delivery:Closed-loop pump-sensor combinations represent unpenetrated white space in hospital procurement contracts where institutional sales relationships control access.
Industry Challenges
- Biocompatibility Engineering Talent:Scarce expertise in foreign-body response mitigation for long-wear subcutaneous sensors constrains product development timelines.
- ISO 15197 Certification Delays:Independent laboratory validation for blood glucose meter accuracy ties up working capital for 18-24 months before payer reimbursement eligibility.
- Legacy Meter Data Portability:Proprietary data formats from installed base devices resist interoperability with emerging continuous monitoring platforms, complicating patient migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Glucose Monitoring Devices Market |
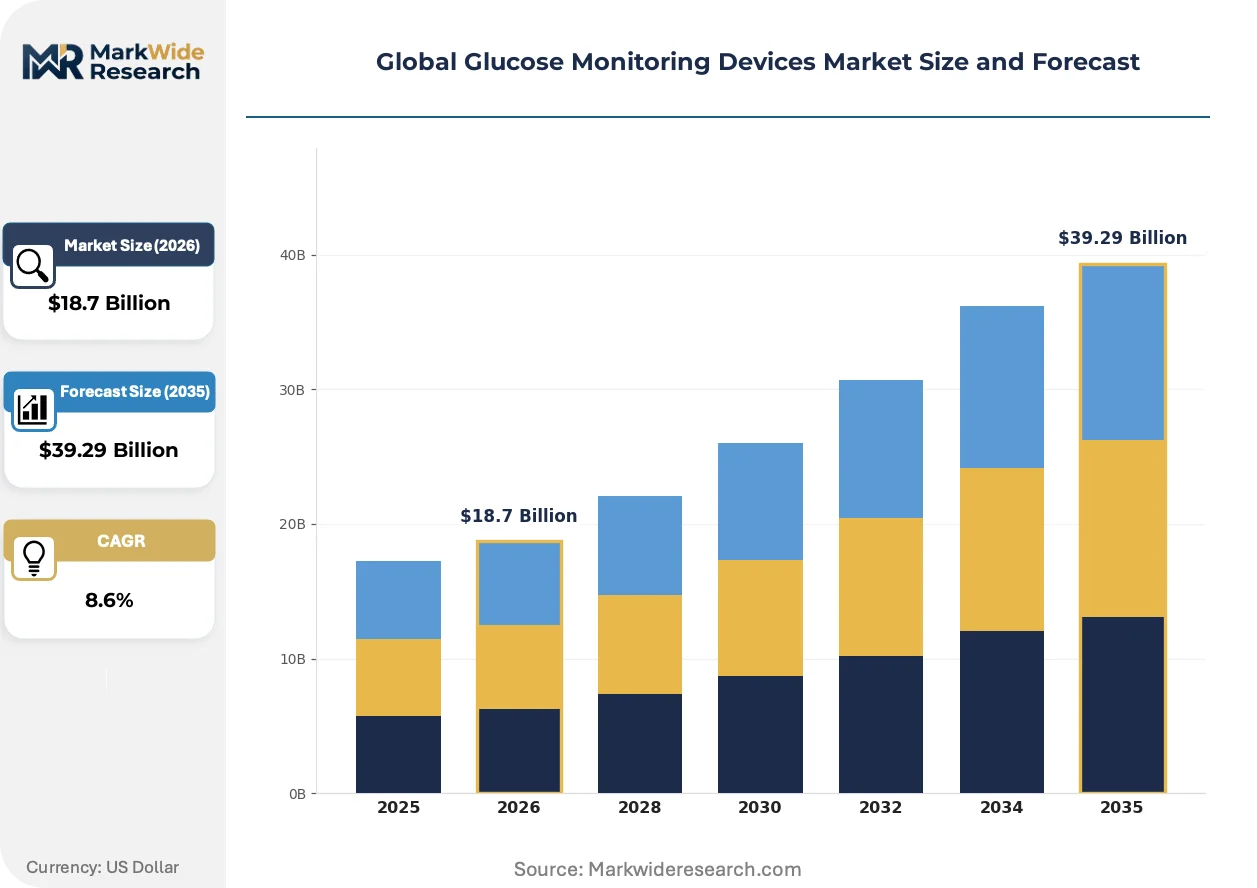
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Glucose Monitors, Blood Glucose Meters, Flash Glucose Monitoring Systems, Wearable Sensors End User: Hospitals, Diabetes Clinics, Homecare, Pharmacies Technology: Enzymatic Sensors, Optical Sensors, Microneedle Sensors, Telemetry Systems Distribution Channel: Online Retail, Direct Sales, Distributors, Medical Supply Stores |
| Companies Covered | Abbott Laboratories, Dexcom, Inc., Medtronic plc, F. Hoffmann-La Roche Ltd, Senseonics Holdings, Inc., Ascensia Diabetes Care Holdings AG, B. Braun SE, LifeScan IP Holdings, LLC, Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Glucose Monitoring Devices Market Emerging Trajectories
Optical sensing modalities and factory-calibration algorithms are compressing the functional gap between invasive and non-invasive glucose measurement, while regulatory frameworks race to adapt validation standards.
Microneedle array technology is converging with optical interferometry to enable minimally invasive glucose quantification through interstitial fluid extraction. Early-stage adopters in Scandinavian homecare pilot programs are validating wear-time extension beyond fourteen days. This convergence is compressing the price-performance boundary between premium continuous monitors and economy flash systems.
FDA's evolving digital health guidance is accelerating software-enabled device approvals through pre-certification pilot programs for algorithm-driven glucose prediction. Manufacturers must now submit real-world performance data alongside traditional clinical trials. Continuous monitoring systems with embedded predictive analytics face the steepest compliance burden as FDA applies learning-based device frameworks.
Patients are consolidating glucose data management through smartphone-integrated platforms that aggregate readings from multiple sensor generations. Pharmacy benefit managers in the United States are responding with formulary tiers that favor vertically integrated device-app ecosystems. This behavioral shift is most visible in employer-sponsored insurance pools where remote patient monitoring incentives reduce premium costs.
Global Glucose Monitoring Devices Market Segmentation
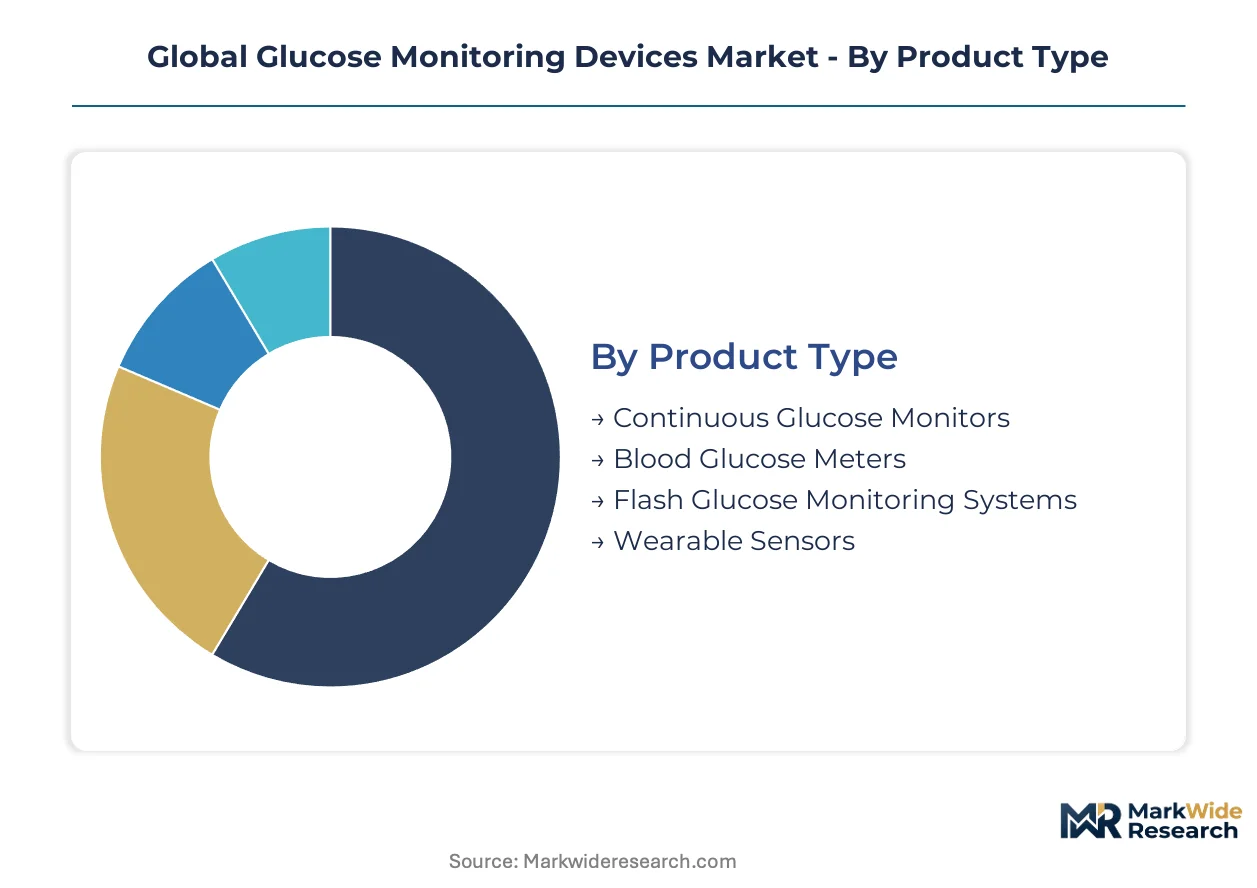
Product architecture in glucose monitoring splits between disposable consumables and durable hardware, with recurring revenue models favoring sensor-based systems. End-user concentration and technology modality together determine margin structure and regulatory pathway complexity.
Product Type:
Customization intensity varies from factory-calibrated disposable sensors to patient-configurable durable receivers across this category.
- Continuous Glucose Monitors:Subcutaneous electrochemical sensors paired with transmitter-receiver systems measure interstitial glucose every 1-5 minutes. Demand concentrates in United States employer-sponsored insurance pools where remote patient monitoring incentives reduce premium costs for plan sponsors. Manufacturers capture recurring revenue through 7-14 day sensor replacement cycles.
- Blood Glucose Meters:Portable electrochemical analyzers using finger-prick capillary samples remain the volume anchor in India and Brazil where public health ministries prioritize procurement cost over feature sophistication. Test strip economics dominate total cost of ownership calculations in price-sensitive institutional tenders.
- Flash Glucose Monitoring Systems:Factory-calibrated wearable sensors with on-body scanners eliminate finger-prick calibration requirements. German and French pharmacy networks are expanding over-the-counter availability.
- Wearable Sensors:Smartphone-integrated form factors target fitness-adjacent wellness consumers in Scandinavian homecare pilot programs.
Most installed capacity flows through Continuous Glucose Monitors. Expansion is steepest in Flash Glucose Monitoring Systems.
End User:
Procurement authority shifts from centralized hospital purchasing committees to individual patient decision-making across this cost-to-convenience spectrum.
- Hospitals:Acute care settings deploy multi-parameter monitors with integrated glucose modules for perioperative glycemic control. United States health systems favor closed-loop pump-sensor combinations under bundled payment contracts.
- Diabetes Clinics:Specialized outpatient facilities prescribe continuous monitoring systems with embedded predictive analytics for intensive insulin management. EMA MDR compliance requirements shape supplier qualification in European clinic networks.
- Homecare:Residential self-migration of Type 1 and Type 2 patients drives consumer-form-factor device demand. United Kingdom NHS remote monitoring pilots are validating 14-day wear-time extensions.
- Pharmacies:Retail channel expansion in Germany and France enables direct-to-consumer pathways bypassing prescription requirements.
Volume leadership sits with Homecare. Margin concentration favors Hospitals.
Technology:
Manufacturing process maturity ranges from established enzymatic biochemistry to emerging semiconductor fabrication approaches.
- Enzymatic Sensors:Glucose oxidase and glucose dehydrogenase biochemistry dominates commercial production with three specialized fermentation suppliers controlling enzyme supply. ISO 15197 accuracy standards shape competitive differentiation in German and French reimbursement eligibility.
- Optical Sensors:Near-infrared spectroscopy and Raman scattering approaches target non-invasive measurement through skin transdermal analysis. FDA software-as-a-medical-device frameworks apply to algorithm-driven signal processing components.
- Microneedle Sensors:Silicon-based MEMS fabrication reduces unit economics against legacy electrochemical strip production. Early-stage Scandinavian pilots validate wear-time extension beyond fourteen days.
- Telemetry Systems:Wireless data transmission protocols enable smartphone-integrated platforms aggregating multi-generational sensor readings. United States pharmacy benefit managers favor vertically integrated device-app ecosystems in formulary tier design.
Enzymatic Sensors carry the dominant installed base. Microneedle Sensors are gaining share fastest.
Distribution Channel:
Channel control intensity decreases from direct manufacturer-patient relationships to fragmented third-party retail.
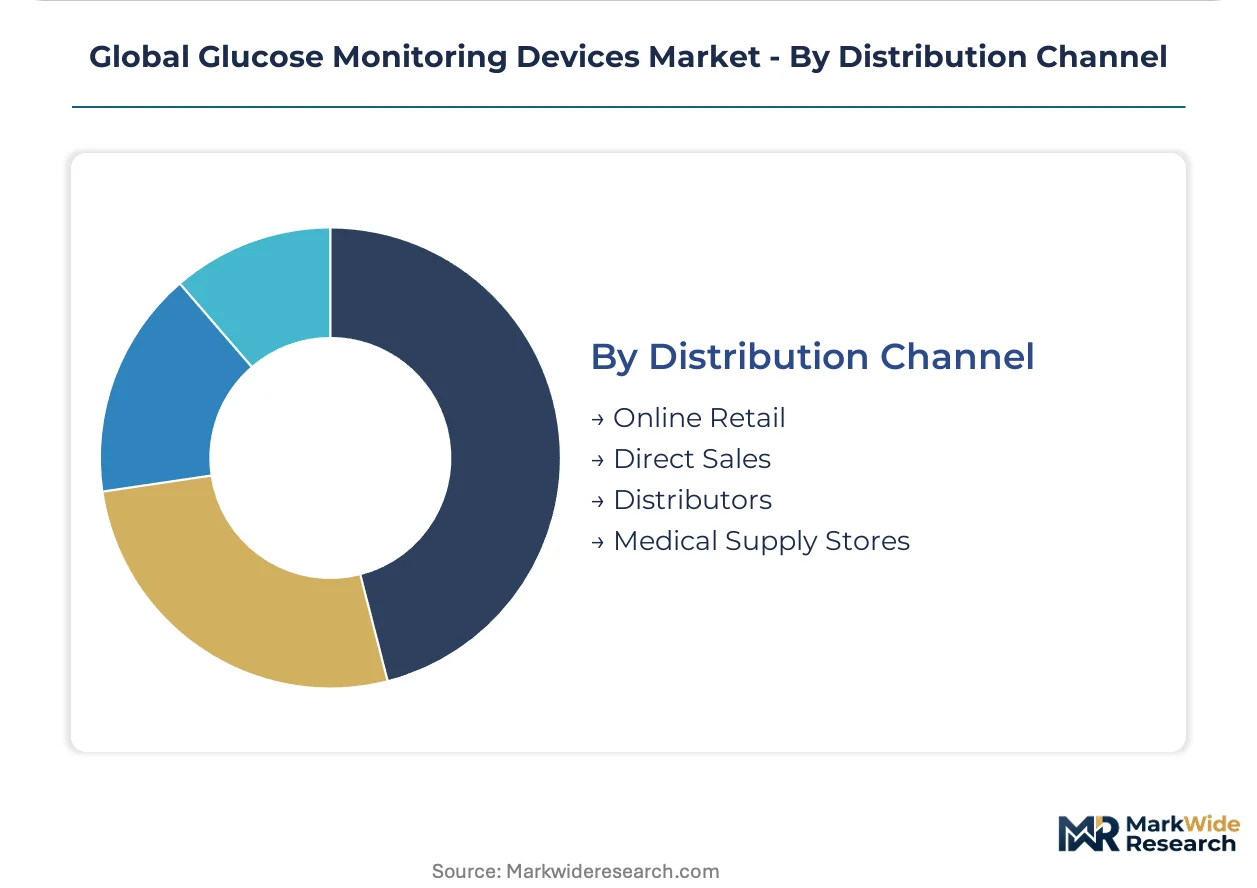
- Online Retail:E-commerce platforms enable subscription-based sensor replenishment with automated insurance prior authorization. United States direct-to-consumer brands bypass traditional durable medical equipment suppliers.
- Direct Sales:Institutional sales teams navigate hospital procurement complexity controlling access to integrated insulin pump ecosystems. Medtronic plc leverages this channel for closed-loop system contracts.
- Distributors:Regional medical device wholesalers manage inventory and logistics for blood glucose meters in emerging markets. Indian and Brazilian public health tenders route through government-authorized distribution networks.
- Medical Supply Stores:Brick-and-mortar durable medical equipment retailers serve Medicare and Medicaid beneficiaries requiring in-person fitting and training services.
Direct Sales captures the highest-margin contracts. Online Retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Diego anchors the global glucose monitoring devices industry through Dexcom's vertically integrated manufacturing campus. The United States concentrates the dominant share of continuous glucose monitor production capacity. Regulatory frameworks in Germany, Japan, and India are reshaping commercial access and reimbursement pathways.
United States
Employer-sponsored insurance pools drive demand for remote patient monitoring systems that reduce premium costs for plan sponsors. FDA pre-certification pathways for software-as-a-medical-device frameworks accelerate algorithm-enabled glucose prediction approvals. The Minneapolis-St. Paul corridor hosts Medtronic's institutional sales operations controlling hospital procurement contracts for integrated insulin pump ecosystems.
Germany
Retail pharmacy networks are expanding over-the-counter availability of flash glucose monitoring systems, bypassing prescription requirements. EMA Medical Device Regulation enforces stricter clinical evidence standards for CE-marked continuous monitoring systems entering European markets. The Baden-Württemberg industrial cluster concentrates enzymatic sensor fermentation capacity serving ISO 15197 accuracy validation requirements.
Japan
PMDA software-as-a-medical-device frameworks apply to algorithm-driven signal processing components in next-generation optical sensors. METI industrial policy supports semiconductor fabrication approaches for microneedle array manufacturing. The Kansai region around Osaka hosts precision MEMS foundries reducing unit economics against legacy electrochemical production.
India
Public health ministries prioritize procurement cost over feature sophistication in blood glucose meter tenders for volume anchor positioning. CDSCO medical device regulations shape competitive differentiation for imported continuous monitoring systems seeking market authorization. The Maharashtra pharmaceutical corridor concentrates glucose oxidase biochemistry supply serving domestic test strip manufacturing.
United Kingdom
NHS remote monitoring pilots are validating 14-day wear-time extensions for homecare self-management applications. MHRA post-Brexit regulatory divergence from EMA MDR creates parallel filing requirements for continuous glucose monitor manufacturers. The Cambridge technology cluster anchors optical interferometry research programs targeting non-invasive glucose measurement.
Global Glucose Monitoring Devices Market Vendor Landscape
Strategic partnerships dominate the current landscape as sensor manufacturers seek algorithm capabilities and digital health entrants pursue hardware distribution. The vendor base concentrates around three tiers: vertically integrated multinationals controlling enzyme supply and factory automation, specialized continuous monitor firms with proprietary transmitter-receiver architectures, and regional blood glucose meter suppliers competing on test strip economics. Archetypes include the integrated health conglomerate, the pure-play sensor technologist, and the pharmacy-channel flash system specialist. M&A activity and technology licensing agreements represent the dominant competitive moves as firms address biocompatibility engineering talent scarcity.
Among US-based integrated health conglomerates, Abbott Laboratories and Johnson & Johnson Services, Inc. exemplify the backward-integrated archetype with captive sensor chemistry and consumer-facing distribution networks. Dexcom, Inc. occupies a position as the pure-play continuous monitor specialist with factory automation leadership. Roche's Ascensia Diabetes Care Holdings AG represents the European pharmacy-channel incumbent navigating EMA MDR compliance requirements. Medtronic plc anchors the institutional sales tier with hospital procurement relationships controlling access to closed-loop pump-sensor combinations.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom, Inc. |
| Medtronic plc |
| F. Hoffmann-La Roche Ltd |
| Senseonics Holdings, Inc. |
| Ascensia Diabetes Care Holdings AG |
| B. Braun SE |
| LifeScan IP Holdings, LLC |
| Johnson & Johnson Services, Inc. |
| Others |
Supply Flow & Price Mechanics
United States employer-sponsored insurance pools concentrate procurement authority for continuous glucose monitors, locking in subscription-based sensor replenishment models that prioritize remote patient monitoring incentives over per-unit transactional pricing. This buyer concentration feeds upstream into factory automation investments at vertically integrated manufacturers, compressing unit economics for disposable components while expanding margin capture through recurring revenue cycles.
Pricing Analysis
Platinum and silver electrode material costs pass through directly to disposable sensor pricing, with enzymatic biochemistry suppliers indexing contracts to precious metal spot markets. Pricing stratifies across premium, standard, and economy tiers based on ISO 15197 certification status and factory-calibration sophistication. Cost compression in economy blood glucose meter segments intensifies as Indian and Brazilian public health ministries consolidate tender volumes. Pharmacy-channel flash systems in Germany and France show the lowest price sensitivity due to over-the-counter convenience premiums.
Supply Chain Analysis
Reverse-logistics flows for transmitter-receiver refurbishment concentrate at Dexcom's San Diego campus and Medtronic's Minneapolis-St. Paul corridor operations, extending hardware lifecycle value. Manufacturing gravity centers on the United States, Germany, and Japan, with the Baden-Württemberg cluster anchoring glucose oxidase fermentation capacity. Supply chains draw from single-source enzyme suppliers in the Maharashtra pharmaceutical corridor, creating qualification bottlenecks for new entrants. Tariff exposure on semiconductor-grade silicon wafers threatens microneedle sensor cost targets. Distribution runs through pharmacy benefit manager formulary tiers in the United States and retail pharmacy networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where homecare self-migration and FDA software-as-a-medical-device pre-certification pathways are elevating demand toward factory-calibrated, algorithm-enabled premium specifications over legacy finger-prick systems.
For Market Incumbents: Deepen backward integration into glucose oxidase biochemistry through captive fermentation capacity or long-term supply agreements with Maharashtra-based suppliers, defending against single-source enzyme bottlenecks. Expand factory automation in San Diego and Minneapolis-St. Paul corridors to sustain cost leadership against silicon MEMS fabrication entrants. Prioritize ISO 15197 certification maintenance for German and French reimbursement eligibility as EMA MDR clinical evidence requirements tighten quality differentiation. For New Entrants and Emerging Players: Scandinavian homecare pilot programs represent the most penetrable white space for wearable sensor form factors targeting 14-day wear-time extensions. Pharmacy channel expansion in German and French retail networks enables direct-to-consumer pathways bypassing prescription gatekeepers. Algorithm-enabled glucose prediction tools leveraging FDA pre-certification pathways offer the lowest regulatory barrier entry point against established sensor manufacturers. For Investors and Strategic Acquirers: Digital health conglomerates with software-as-a-medical-device capabilities are the most active acquirer in this space, seeking hardware distribution access to vertically integrated device-app ecosystems. Long-term viability centers on five-to-ten year windows for closed-loop pump-sensor combinations in United States hospital procurement contracts. Target acquisition profiles emphasize biocompatibility engineering talent pools and proprietary transmitter-receiver architectures. Monitor NHS remote monitoring pilot outcomes for 14-day wear-time validation signals.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway | Accelerates software-enabled glucose prediction approvals through real-world performance data submissions. |
| CE Marking Pathway | EMA MDR compliance unlocks German and French pharmacy network access for flash monitoring systems. |
| Hospital System Partnership | Institutional sales relationships control access to closed-loop pump-sensor bundled payment contracts. |
| Software Companion Development | Smartphone-integrated platforms aggregate multi-generational sensor readings for formulary tier preference. |
| Reimbursement Strategy | Remote patient monitoring incentives in United States employer pools reduce plan sponsor premium costs. |
Methodological Framework
Coverage spans the United States, Germany, Japan, India, and the United Kingdom, with primary inputs from each market combining interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists with secondary validation. Sources include FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, CMS Medicare reimbursement data, and ISO 15197 laboratory validation reports. Bottom-up sensor shipment modeling triangulates against top-down healthcare expenditure allocation estimates.
Granularity-level modeling disaggregates volume and value across product type, end user, technology modality, and distribution channel dimensions, with additional segmentation by regional regulatory cluster and payer type. CAGRs derive from installed base replacement cycle analysis, wear-time extension adoption curves, and pharmacy channel penetration rates across the projection horizon. Industry-specific inputs include enzymatic sensor fermentation capacity utilization, precious metal commodity price trajectories, and software-as-a-medical-device approval velocity.
Underlying measurement precision varies by segment; continuous glucose monitor shipment data carries tighter precision than emerging optical sensor pilot volumes. Forecasts reflect assumptions regarding EMA MDR compliance timelines, FDA digital health guidance evolution, and NHS remote monitoring program scale-up. Practitioners should monitor CDSCO medical device regulation implementation in India and METI microneedle fabrication subsidy outcomes for early demand inflection signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Japan Oral Anti-Diabetic Drug Market
Diabetes Care
China Continuous Glucose Monitoring Devices Market
Diabetes Care
Australia Self-Monitoring Blood Glucose Market
Diabetes Care
Insulin Resistance Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
Saudi Arabia Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Type 2 Diabetes Market
Diabetes Care
Continuous Glucose Monitoring in Philippines Market
Diabetes Care
Self-Monitoring Blood Glucose Strips Market
Diabetes Care
Antidiabetics Market
Diabetes Care
Asia Pacific Blood Glucose Test Strip Market
Diabetes Care
Japan Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Diabetes Care Devices Market
Diabetes Care
Alternatives for Injectable Diabetes Care Market
Diabetes Care
APAC Insulin Infusion Pumps Market
Diabetes Care
Mexico Diabetes Care Devices Market