
 Prostate Cancer Treatment Market | 2026-2036
Prostate Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Prostate Cancer Treatment Market Intelligence
Specialty oncology clinics are recalibrating treatment protocols toward precision medicine, expanding their share of advanced prostate cancer cases. Johnson & Johnson leverages its urology franchise to sustain leadership in androgen receptor pathway inhibitors. Pfizer competes through broad oncology infrastructure, while Astellas Pharma anchors its position with established hormonal therapy portfolios across major markets.
Prostate cancer treatment encompasses therapeutic interventions targeting malignant neoplasms of the prostate gland, spanning pharmaceutical agents, radiation modalities, and surgical adjuncts designed to inhibit tumor progression, manage symptoms, and extend survival in localized through metastatic disease states. Hormonal therapy dominates current prescribing patterns as the foundational intervention across disease stages, while immunotherapy represents the fastest-expanding category driven by checkpoint inhibitor development in castration-resistant populations. Oral delivery modes capture substantial volume through patient convenience advantages, though intravenous administration retains priority for cytotoxic and biologic agents in hospital and outpatient clinic settings where infusion monitoring protocols apply.
The FDA and EMA govern pivotal trial endpoints and approval standards for novel prostate cancer therapeutics, with FDA breakthrough therapy designation accelerating market access for agents demonstrating substantial survival advantages over existing standards. The EU's MDR imposes strengthened clinical evidence requirements on companion diagnostics and radiation delivery systems, extending development timelines for integrated therapeutic platforms. Stakeholders must monitor evolving reimbursement negotiations between national health technology assessment bodies and manufacturers, as these determinations increasingly dictate commercial viability ahead of regulatory clearance itself.
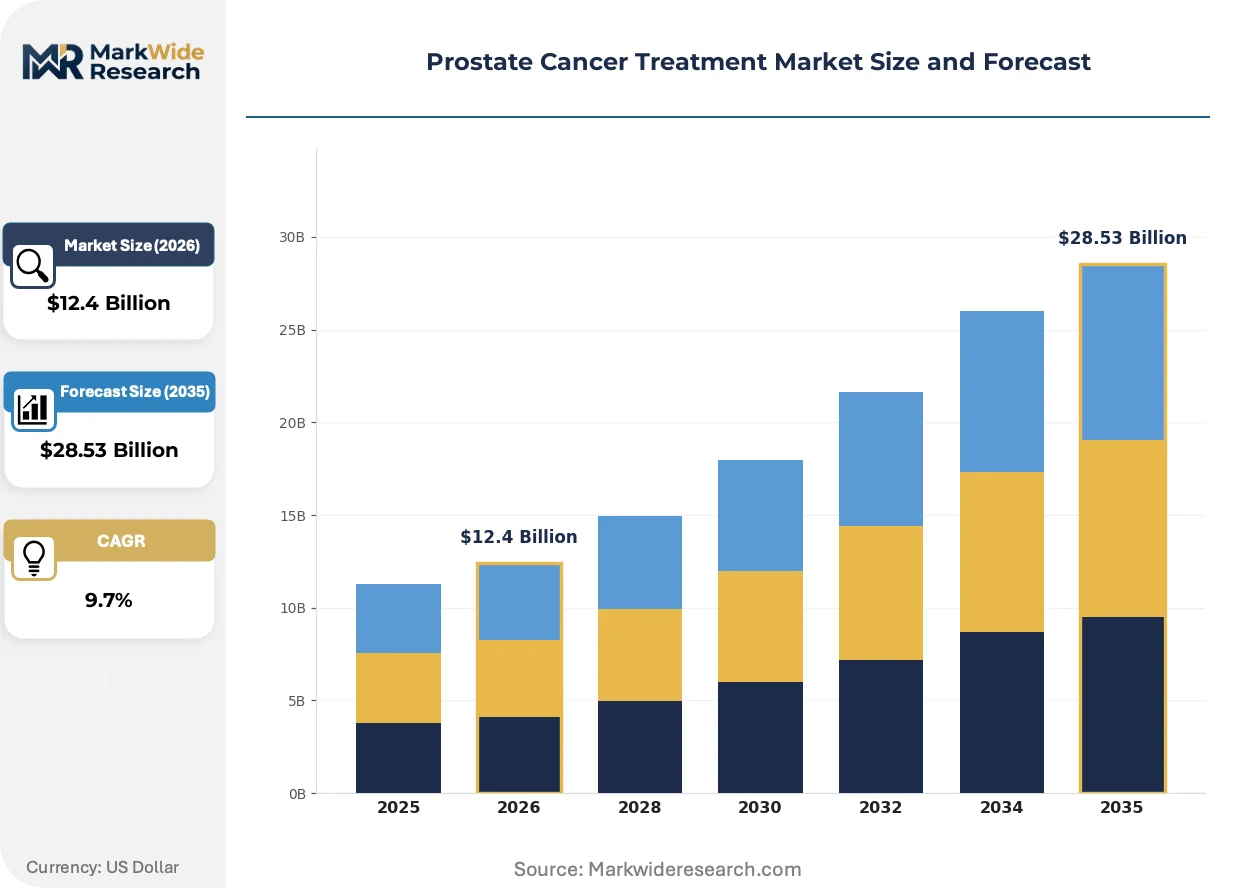
Market Dynamics
FDA breakthrough therapy designation is compressing development timelines for novel androgen receptor inhibitors, forcing incumbents to accelerate pipeline investments or cede positioning to faster-moving competitors in the castration-resistant segment.
Growth Catalysts
- Accelerated Approval Pathways:FDA breakthrough and fast-track programs compress Phase III-to-launch timelines for agents demonstrating overall survival advantages over enzalutamide or abiraterone standards.
- Specialty Oncology Clinic Expansion:Freestanding cancer centers in Texas, Florida, and California are consolidating advanced prostate cancer volumes and driving adoption of precision-matched combination protocols.
- Liquid Biopsy Integration:Circulating tumor DNA testing is expanding eligibility screening for PARP inhibitors and immunotherapy across community urology practices previously limited to tissue-based assays.
Market Restraints
- Reimbursement Compression:Medicare's inflation rebate provisions under the Inflation Reduction Act are narrowing net pricing flexibility for oral hormonal agents dispensed through Part D.
- Radiopharmaceutical Supply Concentration:Lutetium-177 production depends on a limited network of cyclotron facilities in Belgium, Canada, and South Africa, creating dose allocation vulnerability.
- Cross-Resistance Mechanisms:Sequential androgen receptor pathway inhibition produces overlapping resistance mutations that reduce efficacy of second-line hormonal strategies.
Strategic Opportunities
- Biomarker-Driven Patient Stratification:Homologous recombination deficiency testing in community oncology settings remains underpenetrated, creating white space for diagnostic-therapeutic platform bundling.
- Theranostic Convergence:Paired diagnostic imaging and targeted radioligand therapy is rewriting treatment protocols in metastatic castration-resistant disease, with PSMA-PET directing lutetium-177-PSMA-617 sequencing.
- EU MDR Companion Diagnostic Pathway:Strengthened clinical evidence requirements for integrated diagnostic-therapeutic platforms create first-mover advantage for manufacturers with pre-positioned PMA/CE dossiers.
Industry Challenges
- Radiopharmaceutical Logistics Complexity:Short half-life isotopes require same-day synthesis-to-infusion coordination that strains cold chain capabilities at community infusion centers.
- Biomarker Test Standardization Gaps:Discordant BRCA1/2 and ATM testing results between tissue and liquid platforms complicate treatment selection and clinical trial enrollment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prostate Cancer Treatment Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $28.53 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal Therapy, Radiation Therapy, Chemotherapy, Immunotherapy Delivery Mode: Oral, Injectable, Intravenous, Topical Care Setting: Hospitals, Outpatient Clinics, Home Care, Specialty Clinics Patient Type: Localized, Advanced, Recurrent, Castration-Resistant |
| Companies Covered | Johnson & Johnson, Astellas Pharma, Pfizer, Bayer, Novartis, AstraZeneca, Merck & Co., Sanofi, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prostate Cancer Treatment Market Strategic Shifts & Innovations
Precision medicine infrastructure is rewriting competitive positioning in prostate cancer, with biomarker-directed therapy selection displacing empirical sequencing and forcing manufacturers to integrate diagnostic capabilities or surrender access to integrated delivery networks.
PSMA-targeted radioligand therapy is rewriting the metastatic castration-resistant treatment algorithm. Academic medical centers in Germany and the United States are expanding lutetium-177-PSMA-617 capacity threefold since FDA approval in 2022. The technology is compressing chemotherapy referral volumes and redirecting infusion center investment toward radiopharmaceutical handling infrastructure.
EMA's strengthened MDR requirements for companion diagnostics are extending development timelines for integrated therapeutic platforms. Manufacturers must now generate prospective clinical evidence linking diagnostic performance to therapeutic outcomes, not just analytical validation. The radioligand therapy segment faces the steepest compliance burden, with PSMA imaging agents now requiring Class III device certification.
Patient advocacy organizations are compressing traditional physician-patient information asymmetry. Prostate cancer-specific foundations in the United States and United Kingdom are distributing treatment decision aids that reference NCCN and ESMO guidelines directly, accelerating second-opinion seeking and trial enrollment outside originating institutions.
Prostate Cancer Treatment Market Segmentation
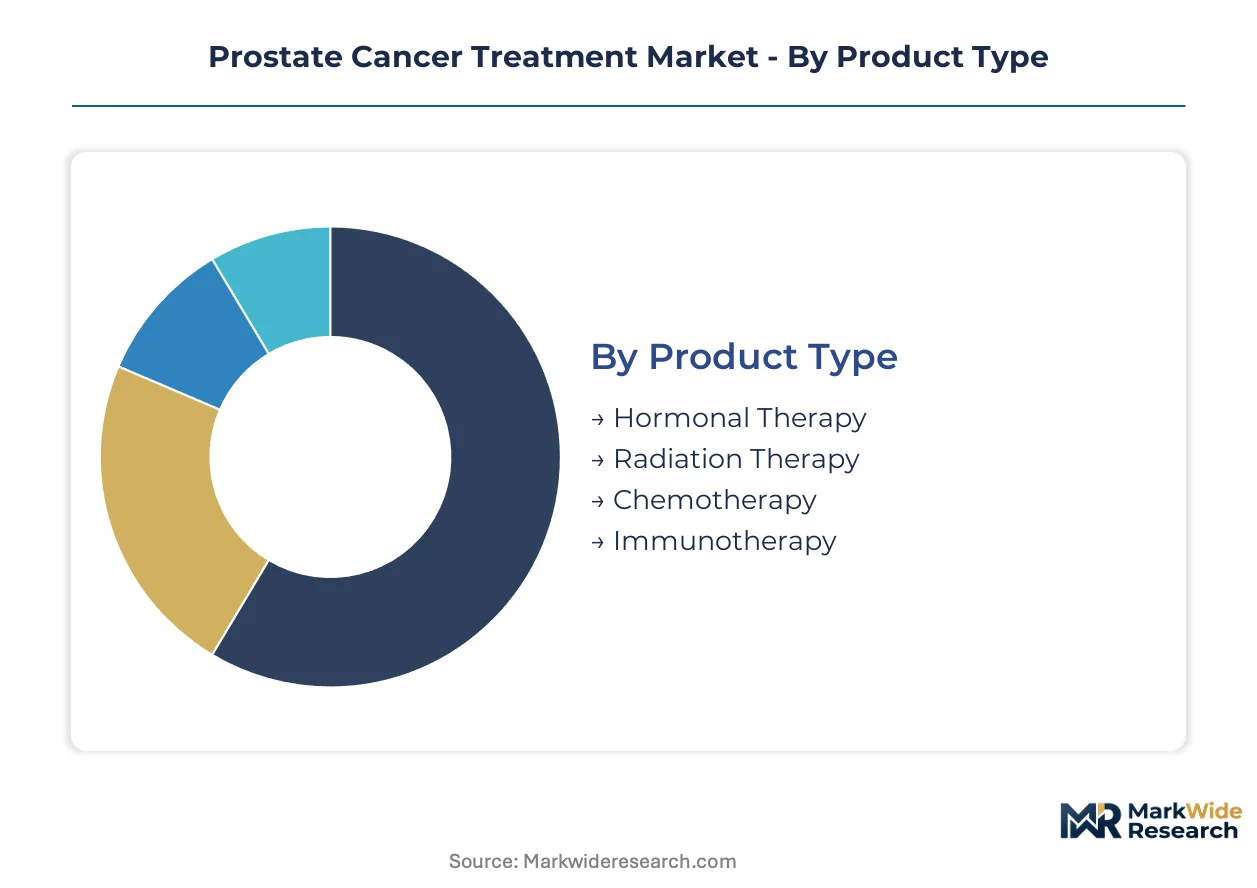
Prostate cancer treatment segmentation reflects divergent regulatory pathways and reimbursement mechanics across therapeutic modalities. Each category carries distinct FDA and EMA certification burdens that shape manufacturer investment priorities and commercial timelines.
Product Type:
FDA breakthrough therapy designation and EMA accelerated assessment programs apply unevenly across therapeutic categories, with immunotherapy and novel hormonal agents commanding priority review while radiation modalities face parallel device clearance requirements.
- Hormonal Therapy:Androgen deprivation regimens and androgen receptor inhibitors constitute the foundational prescribing category across disease stages. Medicare Part D reimbursement structures in the United States favor oral formulations, though the Inflation Reduction Act's inflation rebate provisions are compressing net pricing flexibility for established agents like enzalutamide and abiraterone.
- Immunotherapy:Checkpoint inhibitors targeting PD-1/PD-L1 pathways represent the steepest regulatory ascent, with FDA fast-track and breakthrough designations compressing Phase III-to-launch intervals for agents demonstrating survival advantages in castration-resistant populations. Sipuleucel-T and pembrolizumab have established precedent for accelerated pathways in prostate-specific indications.
- Radiation Therapy:External beam and brachytherapy platforms require FDA 510(k) or PMA clearance alongside CMS reimbursement establishment, with PSMA-targeted radioligand therapy adding NDA complexity through combined drug-device regulation.
- Chemotherapy:Taxane-based cytotoxic regimens carry established FDA approval pathways but face biosimilar competition pressure and narrowing utilization as precision alternatives expand.
Hormonal therapy sits at the top of the volume ranking, with immunotherapy climbing the fastest.
Delivery Mode:
Route of administration determines site-of-care economics and cold chain infrastructure requirements, with oral agents enabling community dispersion while parenteral formats concentrate treatment in hospital and infusion center settings.
- Oral:Small-molecule hormonal agents and targeted therapies dominate patient convenience preferences, driving prescription volume through retail pharmacy and specialty distributor channels. FDA approval of fixed-dose combinations is expanding oral share in metastatic disease management.
- Intravenous:Cytotoxic chemotherapy, monoclonal antibodies, and radioligand therapies require infusion center capacity with nursing oversight and adverse event monitoring protocols. Lutetium-177-PSMA-617 administration demands same-day synthesis-to-infusion coordination that strains community oncology infrastructure.
- Injectable:LHRH agonists and antagonists sustain substantial volume through depot formulations administered in urology and oncology clinics, with leuprolide and degarelix maintaining established reimbursement codes.
- Topical:Limited to palliative skin metastasis management and localized radiation dermatitis, with minimal revenue concentration relative to systemic modalities.
Oral formulations command the greatest prescription volume, though intravenous delivery is gaining share fastest in metastatic castration-resistant segments.
Care Setting:
Site-of-care migration is redistributing treatment volume toward lower-acuity environments as oral therapies expand and risk-based contracting pressures hospital systems to shift infusion services.
- Specialty Clinics:Freestanding oncology centers in Texas, Florida, and California are consolidating advanced prostate cancer volumes and driving adoption of precision-matched combination protocols. These facilities invest in liquid biopsy infrastructure and radiopharmaceutical handling capabilities that community hospitals lack.
- Hospitals:Academic medical centers retain priority for clinical trial enrollment, complex surgical oncology, and radioligand therapy administration requiring nuclear medicine infrastructure. German and United States academic centers have expanded lutetium-177-PSMA-617 capacity substantially since FDA approval.
- Outpatient Clinics:Community urology practices are expanding into medical oncology through oral therapy dispensing and LHRH injection administration, capturing follow-on care from hospital-based diagnoses.
- Home Care:Limited to oral medication adherence support and palliative symptom management, with minimal therapeutic administration due to safety monitoring requirements.
Hospitals retain the highest acuity case volume, with specialty clinics expanding most quickly through consolidation of precision therapy administration.
Patient Type:
Disease stage stratification determines therapeutic intensity and reimbursement tier, with localized disease management concentrating in urology practices and metastatic populations migrating toward medical oncology and specialty clinic settings.
- Castration-Resistant:Metastatic disease progression despite androgen suppression represents the highest unmet need segment, driving PARP inhibitor and immunotherapy development. FDA has granted multiple breakthrough therapy designations for agents targeting homologous recombination deficiency and microsatellite instability subpopulations.
- Advanced:Metastatic hormone-sensitive disease commands combination therapy protocols integrating androgen deprivation with novel hormonal agents or docetaxel, with NCCN guidelines directing treatment selection.
- Localized:Organ-confined disease management concentrates in urology practices through active surveillance, radical prostatectomy, or definitive radiation, with rising adoption of focal therapy alternatives.
- Recurrent:Biochemical relapse after primary therapy requires imaging-directed restaging with PSMA-PET, with treatment selection dependent on metastasis location and prior therapy exposure.
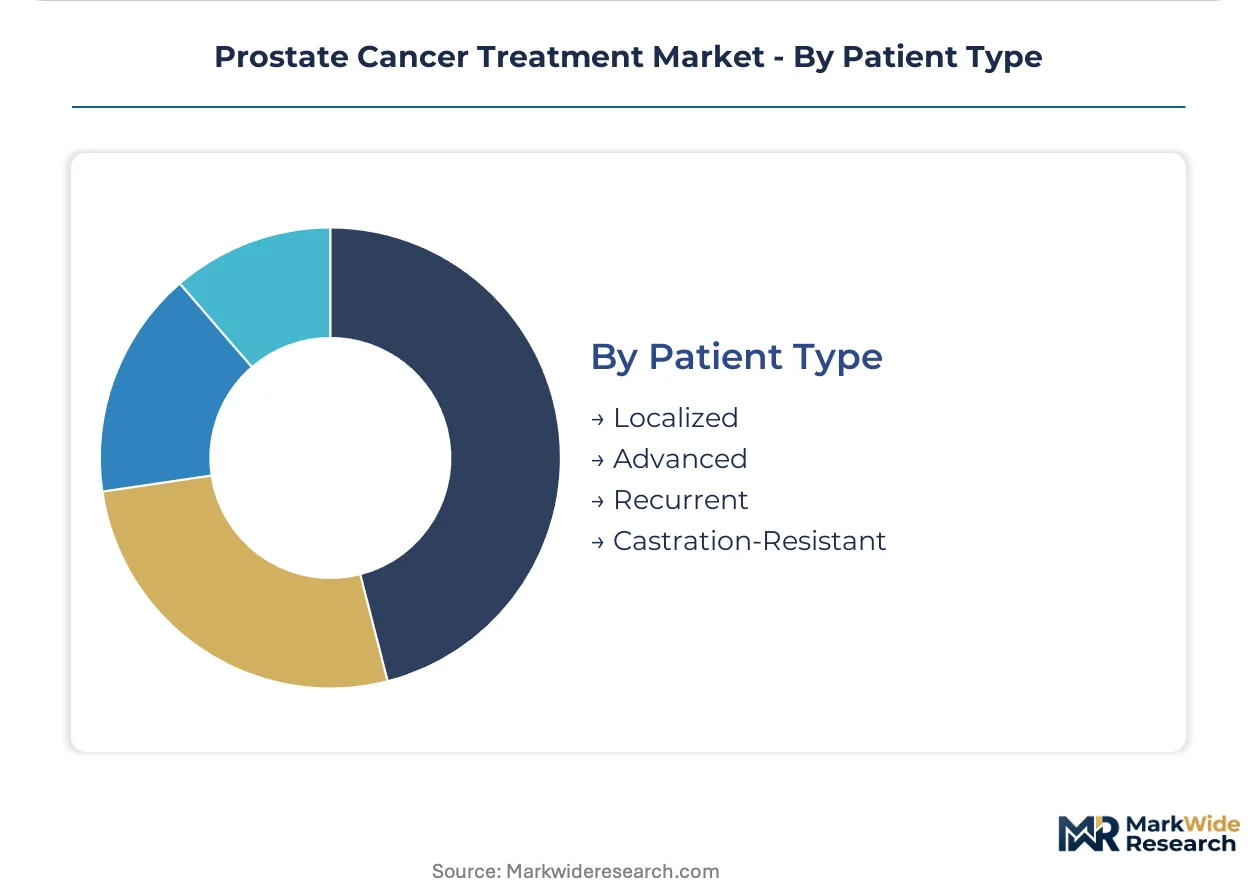
Localized disease accounts for the greatest diagnosed case volume, with castration-resistant segments showing the steepest expansion trajectory for novel therapeutic investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough therapy designation creates a cost-of-compliance gap that concentrates novel agent development in the United States, while EMA's strengthened MDR requirements extend European timelines and redirect investment toward diagnostic-therapeutic integration.
United States
Medicare Part D reimbursement structures favor oral hormonal agents, though the Inflation Reduction Act's inflation rebate provisions compress net pricing flexibility. The FDA's accelerated approval pathways for agents demonstrating overall survival advantages over enzalutamide standards compress Phase III-to-launch timelines. Specialty oncology clinics in Texas, Florida, and California are consolidating advanced prostate cancer volumes and driving adoption of precision-matched combination protocols.
Germany
Academic medical centers in Germany have expanded lutetium-177-PSMA-617 capacity substantially since FDA approval in 2022, compressing chemotherapy referral volumes. The EU's MDR imposes strengthened clinical evidence requirements on companion diagnostics and radiation delivery systems, extending development timelines for integrated therapeutic platforms. The theranostic convergence of PSMA-PET imaging and targeted radioligand therapy is rewriting treatment protocols in metastatic castration-resistant disease.
United Kingdom
Patient advocacy organizations are distributing treatment decision aids that reference NCCN and ESMO guidelines directly, accelerating second-opinion seeking and trial enrollment. The country's national pharmaceutical regulator aligns with EMA accelerated assessment programs for immunotherapy agents. London and the Southeast concentrate precision medicine infrastructure, with liquid biopsy integration expanding eligibility screening for PARP inhibitors across community urology practices.
Japan
PMDA review timelines for novel androgen receptor inhibitors remain conservative relative to FDA pathways, creating regulatory lag for breakthrough-designated agents. The national health technology assessment body negotiates reimbursement determinations that increasingly dictate commercial viability ahead of regulatory clearance. Osaka and Nagoya clusters anchor urology franchise development, with domestic manufacturers prioritizing hormonal therapy portfolio expansion.
Switzerland
Swissmedic maintains alignment with EMA centralized procedures while offering parallel national pathways for radiopharmaceutical innovations. The country's diagnostic-therapeutic platform developers leverage proximity to German and French manufacturing networks for lutetium-177 supply chain coordination. Basel and Zurich concentrate pharmaceutical R&D investment, with manufacturers pre-positioning PMA/CE dossiers to capture first-mover advantage under strengthened MDR companion diagnostic requirements.
Prostate Cancer Treatment Market Key Industry Players
Portfolio diversification dominates the current landscape, with manufacturers integrating diagnostic capabilities or surrendering access to integrated delivery networks. The vendor base clusters around three strategic archetypes: diversified pharmaceutical conglomerates with urology franchises, precision oncology specialists with biomarker-driven platforms, and radiopharmaceutical developers with theranostic convergence capabilities. M&A activity targets liquid biopsy and PSMA imaging assets, while capacity expansion concentrates on radioligand therapy handling infrastructure at specialty clinic networks.
Within the diversified pharmaceutical tier, Johnson & Johnson and Pfizer exemplify contrasting strategic positions. Johnson & Johnson leverages its urology franchise to sustain leadership in androgen receptor pathway inhibitors. Pfizer competes through broad oncology infrastructure spanning hormonal, immunotherapy, and radiopharmaceutical modalities. Astellas Pharma anchors the established hormonal therapy segment with portfolio depth across major markets, occupying a position that precision medicine transition pressures to expand biomarker-directed capabilities.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Astellas Pharma |
| Pfizer |
| Bayer |
| Novartis |
| AstraZeneca |
| Merck & Co. |
| Sanofi |
| Eli Lilly and Company |
| Others |
Cost & Logistics Intelligence
Captive radiopharmaceutical production networks anchor both supply security and pricing power for lutetium-177 therapies, with Novartis and Bayer maintaining in-house cyclotron partnerships in Belgium and Canada that insulate dose allocation from spot-market volatility while commanding premium reimbursement through Medicare's pass-through payment structure.
Pricing Analysis
Specialty distributor margins on oral hormonal agents compress under Medicare Part D inflation rebate provisions, while hospital outpatient departments retain pricing leverage for infused radioligand therapies through pass-through reimbursement codes. Three-tier pricing structure across branded novel hormonal agents, biosimilar alternatives, and generic LHRH agonists reflects patent status and formulation complexity. Cost compression in oral androgen receptor inhibitors is intensifying because of IRA rebate mechanics, with community oncology practices showing greatest price sensitivity and academic medical centers least affected by net pricing fluctuations.
Supply Chain Analysis
Domestic-content mandates for radiopharmaceutical manufacturing are reshaping sourcing patterns in Germany and the United States, where EMA MDR and FDA NDA requirements favor localized isotope production. Lutetium-177 supply draws from cyclotron facilities concentrated in Belgium, Canada, and South Africa, with cold-chain logistics for short half-life isotopes resting on same-day synthesis networks. Single-source vulnerability at the isotope production tier strains community infusion center capacity. Distribution runs through nuclear medicine pharmacies integrated with academic medical center radiology departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The prostate cancer treatment market compounds steadily as aging demographics expand the addressable patient pool and precision medicine transitions extend treatment duration across disease stages.
For Market Incumbents: Hedge against biosimilar erosion in hormonal therapy by accelerating radiopharmaceutical infrastructure investment in Texas, Florida, and California specialty clinic networks. Secure captive lutetium-177 supply agreements with Belgian and Canadian cyclotron operators before dose allocation constraints tighten. FDA breakthrough therapy designation velocity for competing androgen receptor inhibitors threatens first-mover positioning in castration-resistant segments. For New Entrants and Emerging Players: Capture white space in community urology liquid biopsy integration, where homologous recombination deficiency testing penetration remains below academic center benchmarks. Target the recurrent disease segment with PSMA-PET directed therapy sequencing protocols that community practices lack infrastructure to deploy independently. Partner with specialty oncology clinic networks for radiopharmaceutical handling certification rather than building de novo nuclear medicine capacity. For Investors and Strategic Acquirers: Consolidation pressure builds where diagnostic-therapeutic platform bundling creates integrated delivery network lock-in and excludes standalone pharmaceutical developers. Five-to-ten year viability favors manufacturers with pre-positioned PMA/CE dossiers for companion diagnostics under strengthened MDR requirements. Watch FDA radiopharmaceutical approval velocity as the inflection signal for theranostic convergence investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III enrollment for novel androgen receptor inhibitors accelerates competitive entry against enzalutamide standards. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines and commands priority formulary review. |
| Manufacturing Scale-Up | Cyclotron capacity expansion in Belgium and Canada secures lutetium-177 supply for metastatic castration-resistant protocols. |
| Pipeline Diversification | PARP inhibitor and immunotherapy assets reduce reliance on hormonal mechanism cross-resistance vulnerabilities. |
| Strategic Partnership | Liquid biopsy platform alliances enable biomarker-driven patient stratification in community urology settings. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Comparable historical periods anchored the projection horizon, with segmentation modeling across treatment line, administration route, patient population, and regional regulatory cluster. CAGRs derived from patent expiry curves, biosimilar entry assumptions, and precision medicine adoption S-cycles. Forecast inputs incorporated NCCN guideline revision velocity and Medicare coverage determination timelines for novel therapeutic modalities.
Regulatory approval delays, radiopharmaceutical supply disruptions, and reimbursement compression beyond IRA baseline assumptions are the dominant revision risks to modeled projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market
Urology
Global Castrate Resistant Prostate Cancer Market
Urology
Urinary Incontinence Market
Urology
Self-Intermittent Catheters Market
Urology
Uropathy Treatment Market
Urology
Botulinum Toxin in Urology Market
Urology
Global Bladder Cancer Therapeutics Market
Urology
Urology Ultrasound Market
Urology
Varicocele Treatment Market
Urology
Voiding Cystourethrogram Market
Urology
Urinary Tract Infection (UTI) Treatment Market
Urology
Ureter Cancer Treatment Market
Urology
Urology Forceps Market
Urology
LAMEA Transrectal Ultrasound Market
Urology
Global Lithotripsy Market
Urology
Disposable Ureteroscope Market