
 Global Bladder Cancer Therapeutics Market | 2026-2036
Global Bladder Cancer Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bladder Cancer Therapeutics Market Analysis
The bladder cancer therapeutics market is consolidating around a sharp split between premium checkpoint inhibitors and commodity chemotherapy agents. Bristol-Myers Squibb leverages its Opdivo franchise to dominate the adjuvant nivolumab segment for muscle-invasive disease. Merck & Co. sustains competitive pressure through broad Keytruda labeling across urothelial carcinoma lines. Pfizer anchors the targeted therapy tier with its antibody-drug conjugate portfolio.
Bladder cancer therapeutics comprise pharmaceutical agents designed to eliminate or control malignant urothelial cell growth, spanning intravesical biologics, systemic monoclonal antibodies, and small-molecule kinase inhibitors that modulate tumor immune evasion or angiogenic signaling. Immunotherapy now leads product type segmentation as PD-1/PD-L1 inhibitors displace platinum-based chemotherapy in first-line metastatic settings. The systemic delivery mode captures the fastest growth trajectory, reflecting expanded outpatient infusion capacity and oral tyrosine kinase kinase adoption.
The FDA accelerates market entry through breakthrough therapy and priority review designations for urothelial carcinoma candidates, while the EMA's conditional marketing authorization pathway shapes European access timelines. The EU Green Deal's pharmaceutical sustainability requirements are forcing reformulation of intravesical agents to reduce environmental discharge. Stakeholders must monitor how evolving CMS coverage determinations for combination regimens reshape prescribing economics across integrated delivery networks.
Market Dynamics
Checkpoint inhibitors are consolidating clinical pathways across muscle-invasive and metastatic bladder cancer, compressing platinum-based chemotherapy into salvage settings and forcing wholesale restructuring of hospital oncology formularies.
Growth Catalysts
- Accelerated FDA Pathways:Breakthrough therapy and priority review designations compress development timelines for PD-1/PD-L1 inhibitors, enabling faster commercialization of urothelial carcinoma candidates.
- Hospital Infusion Expansion:Outpatient oncology centers are building dedicated immuno-oncology suites, expanding capacity for systemic monoclonal antibody administration beyond traditional inpatient settings.
- Medicare Reimbursement:CMS coverage determinations for intravesical BCG alternatives drive adoption of novel bladder-preserving regimens across integrated delivery networks.
Market Restraints
- BCG Supply Concentration:Global production of bacillus Calmette-Guérin concentrates among two manufacturers, creating vulnerability for non-muscle-invasive disease protocols.
- Platinum Input Costs:Cisplatin and carboplatin formulations face raw material volatility and manufacturing site constraints, pressuring margin structures for remaining chemotherapy indications.
- EMA Conditional Authorization:European access timelines for novel agents extend under post-approval evidence requirements, delaying revenue recognition compared to FDA markets.
Strategic Opportunities
- Combination Regimen White Space:PD-1 inhibitors paired with antibody-drug conjugates represent underexplored protocol development, with Merck and Pfizer anchoring early clinical positioning.
- EU Green Deal Reformulation:Pharmaceutical sustainability mandates are forcing intravesical agent redesign to reduce environmental discharge, creating first-mover advantage for compliant suppliers.
- Community Oncology Penetration:United States community-based infusion centers remain underpenetrated for adjuvant immunotherapy, offering volume expansion outside academic medical centers.
Industry Challenges
- Biomarker Testing Capacity:PD-L1 companion diagnostic throughput constraints create bottlenecks for patient stratification, delaying treatment initiation.
- Cross-Border Reimbursement Complexity:Parallel trade and reference pricing across EU member states compress realized pricing for innovative agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bladder Cancer Therapeutics Market |
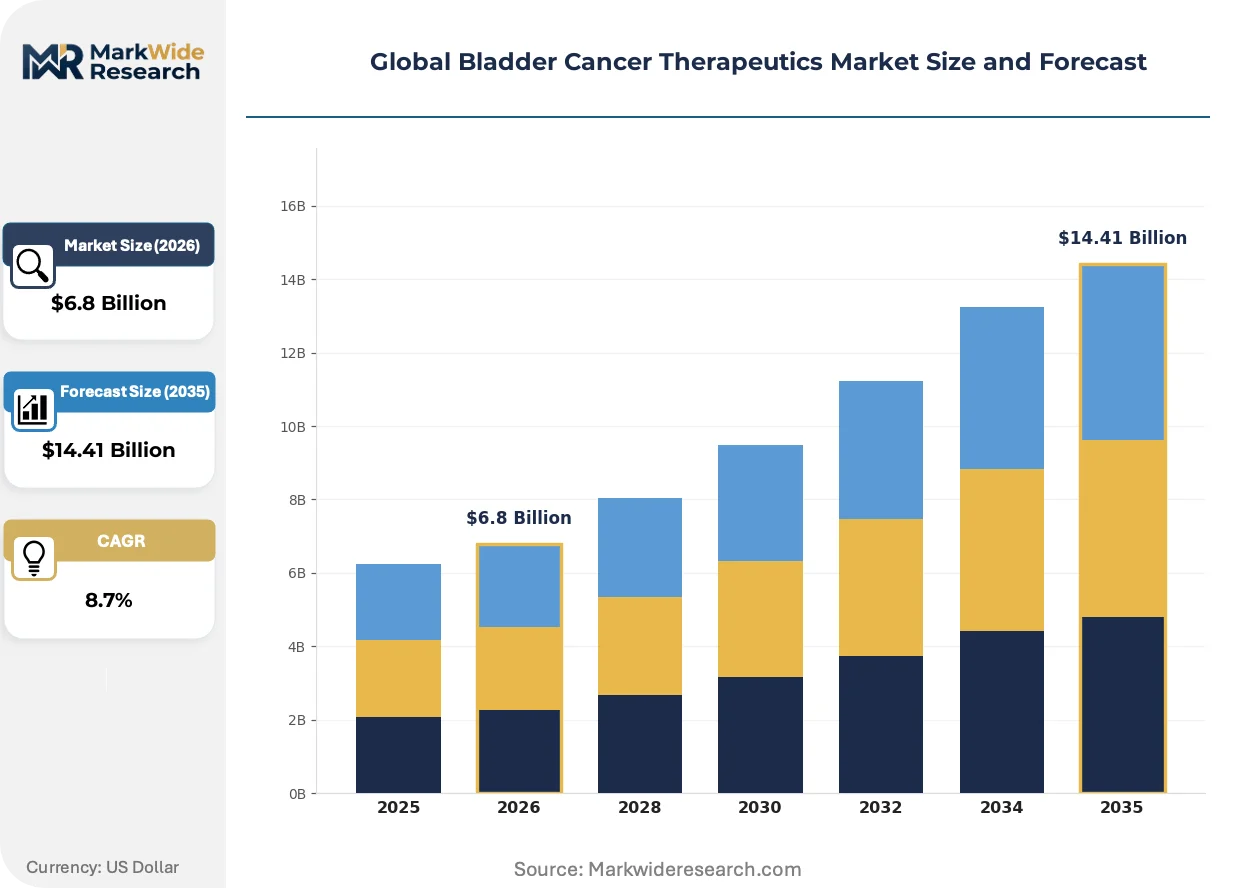
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Radiation Therapy Delivery Mode: Intravesical, Systemic, Oral, Combination End User: Oncology Clinics, Hospitals, Research Institutes, Homecare Treatment Stage: Early Stage, Advanced Stage, Recurrent, Maintenance |
| Companies Covered | Bristol-Myers Squibb Company, Merck & Co., Inc., Johnson & Johnson, F. Hoffmann-La Roche Ltd, Astellas Pharma Inc., Pfizer Inc., AstraZeneca plc, GlaxoSmithKline PLC, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bladder Cancer Therapeutics Market Emerging Trajectories
Novel antibody-drug conjugate architectures are fragmenting the traditional chemotherapy-immunotherapy binary, enabling precision targeting of urothelial carcinoma subpopulations previously managed with blunt cytotoxic protocols.
Subcutaneous nivolumab formulations are decentralizing treatment delivery from hospital infusion centers to community oncology practices and, in select markets, home administration settings. Community-based practices in the United States are piloting these protocols to reduce chair time and facility overhead. This shift is compressing the traditional site-of-care hierarchy and redistributing margin capture away from academic medical centers.
The EU Green Deal's pharmaceutical sustainability requirements are mandating reformulation of intravesical biologics to reduce active pharmaceutical ingredient discharge into wastewater systems. Manufacturers serving European markets must redesign BCG and alternative instillations with biodegradable carrier matrices or closed-system administration devices. Germany and France are enforcing the strictest implementation timelines, with ANSM and BfArM coordinating inspection protocols.
Integrated delivery networks are consolidating oncology procurement under centralized pharmacy and therapeutics committees, displacing individual physician preference as the dominant prescribing determinant. Hospital systems are negotiating system-wide contracts for checkpoint inhibitors, bundling adjuvant and metastatic indications. This concentration is most advanced in the United States, where Medicare Advantage penetration accelerates risk-based contracting for episode-of-care oncology management.
Global Bladder Cancer Therapeutics Market Segmentation
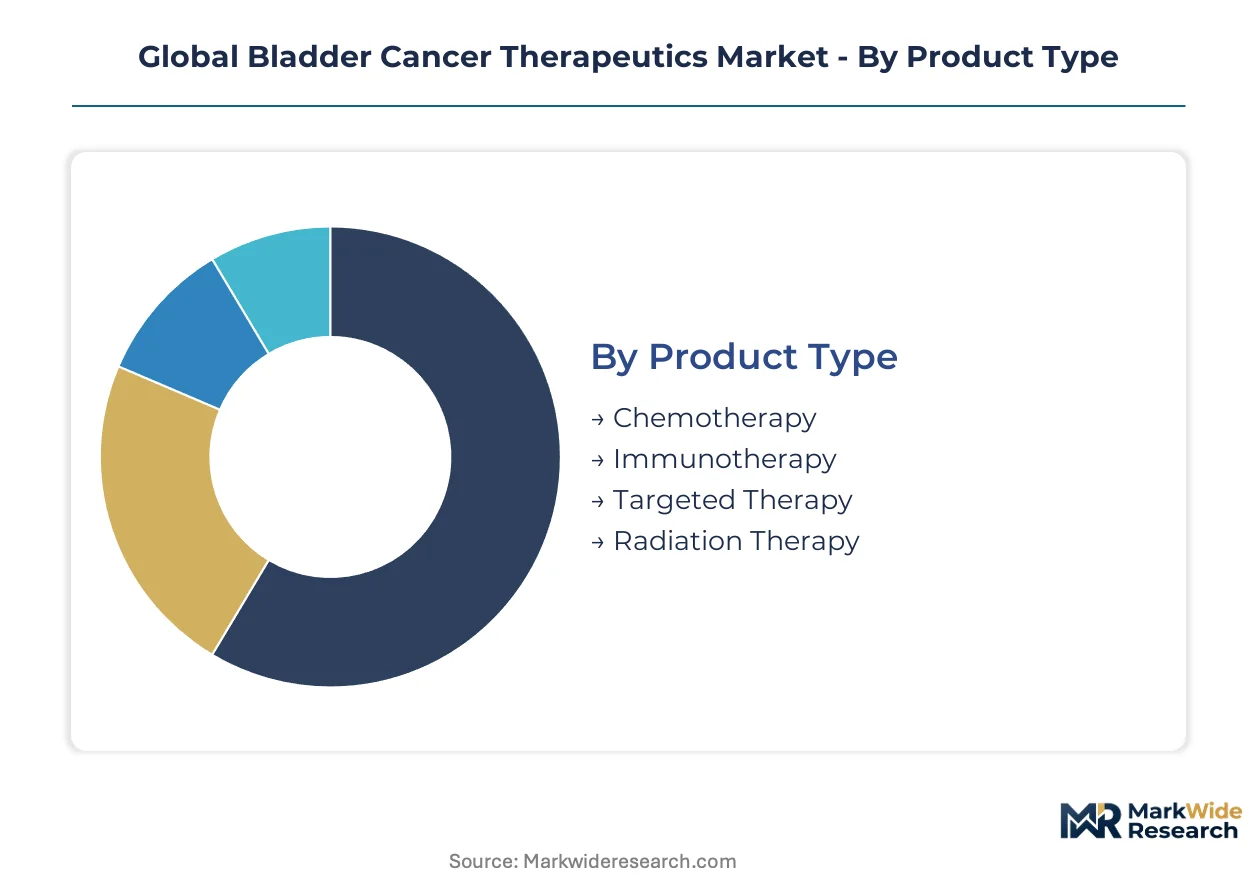
Bladder cancer therapeutics segmentation reflects divergent regulatory pathways and site-of-care economics. Each category channels distinct procurement behaviors across hospital systems, outpatient networks, and emerging home administration models.
Product Type:
FDA breakthrough therapy designation concentrates approval velocity in immunotherapy and targeted therapy segments, while chemotherapy and radiation therapy follow traditional NDA pathways with longer review cycles.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors dominate muscle-invasive and metastatic protocols. Demand clusters in United States academic medical centers where Medicare reimbursement for adjuvant nivolumab has displaced platinum-based first-line standards.
- Targeted Therapy:Antibody-drug conjugates deliver cytotoxic payloads to urothelial carcinoma cells expressing specific surface antigens. United States integrated delivery networks are consolidating procurement of these agents under risk-based contracts with episode-of-care guarantees.
- Chemotherapy:Platinum-based regimens retreat into salvage settings and BCG-unresponsive non-muscle-invasive disease. Manufacturing concentration for cisplatin and carboplatin APIs creates supply vulnerability.
- Radiation Therapy:External beam and brachytherapy modalities preserve bladder function in select early-stage patients. Adoption tracks hospital capital equipment cycles and radiation oncology workforce density.
Immunotherapy sits at the top of the volume ranking, with targeted therapy climbing the fastest.
Delivery Mode:
Cost tier stratification separates hospital-based infusion from lower-acuity administration settings, with oral agents capturing margin through pharmacy benefit management channels.
- Systemic:Intravenous monoclonal antibodies require infusion center infrastructure and cold-chain logistics. United States outpatient oncology suites are expanding chair capacity to accommodate checkpoint inhibitor volume.
- Intravesical:Direct bladder instillation of BCG and alternatives demands specialized urology nursing protocols. European sustainability mandates under EU Green Deal are forcing reformulation to reduce pharmaceutical discharge.
- Oral:Tyrosine kinase inhibitors enable patient self-administration outside facility settings. United States community oncology practices are piloting these protocols to reduce overhead.
- Combination:Sequential or concurrent multimodal regimens complicate reimbursement and prior authorization workflows. Integrated delivery networks are developing standardized pathways to manage utilization.
Systemic delivery commands the largest revenue base, though oral administration is gaining share fastest as subcutaneous formulations decentralize care.
End User:
Customer type determines contracting leverage, with hospital systems extracting volume discounts unavailable to smaller oncology clinics or emerging homecare channels.
- Hospitals:Academic medical centers anchor clinical trial enrollment and protocol development. Pharmacy and therapeutics committees centralize formulary decisions across multi-site systems.
- Oncology Clinics:Community-based infusion centers compete on chair time and patient access. United States Medicare Advantage penetration accelerates risk-based contracting in this channel.
- Research Institutes:Phase I-II trial sites drive pipeline visibility for novel mechanisms. FDA breakthrough therapy designation prioritizes these centers for early access programs.
- Homecare:Subcutaneous nivolumab and oral agents enable administration outside traditional facilities. Germany and France are piloting reimbursement frameworks for home-based immuno-oncology.
Hospitals retain the highest procedure volume, with homecare expanding most quickly as subcutaneous formulations mature.
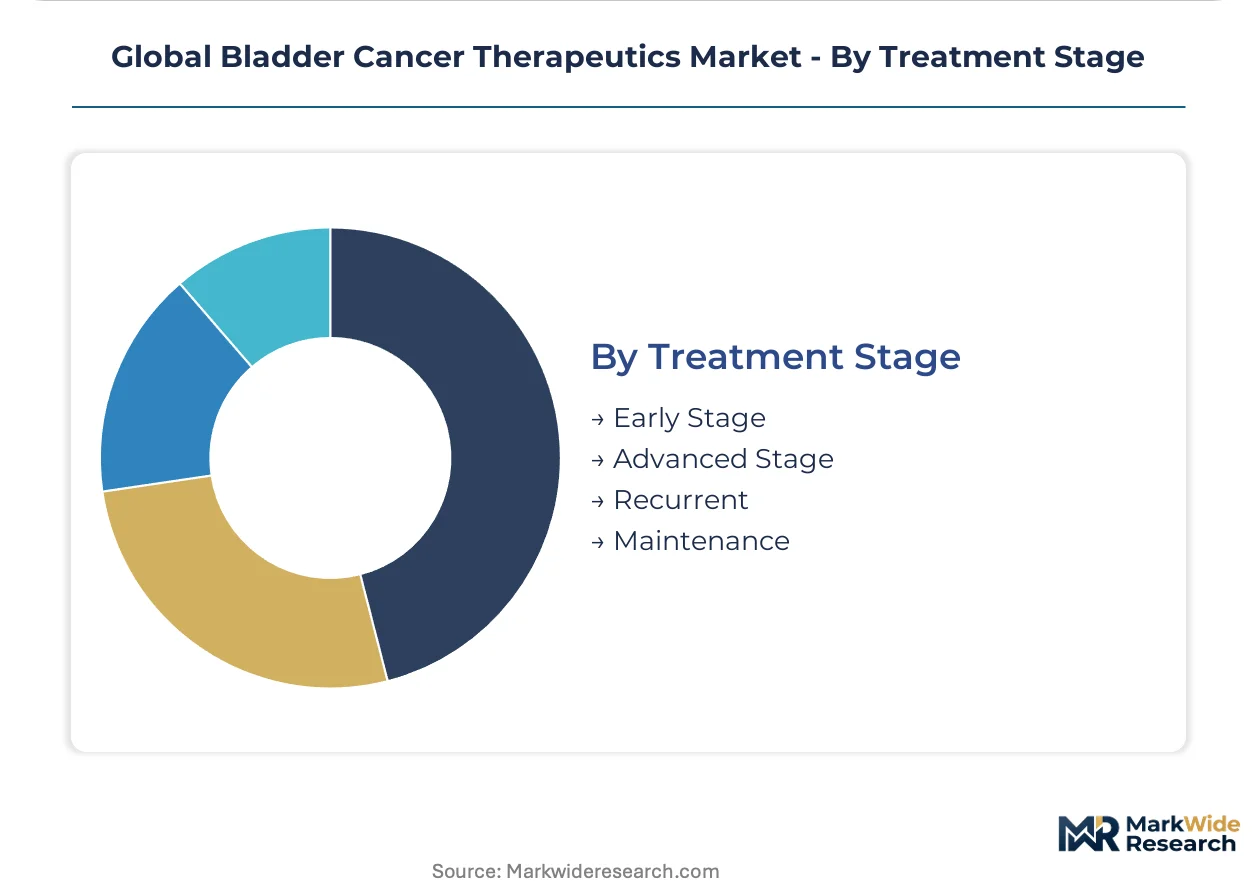
Treatment Stage:
Application urgency shapes pricing tolerance, with advanced and recurrent disease segments commanding premium access compared to maintenance protocols where cost-effectiveness scrutiny intensifies.
- Advanced Stage:Metastatic urothelial carcinoma drives checkpoint inhibitor utilization and combination trial enrollment. FDA accelerated approval pathways compress time-to-market for these indications.
- Early Stage:Non-muscle-invasive disease relies on intravesical BCG and emerging alternatives. BCG supply concentration between two global manufacturers creates protocol vulnerability.
- Recurrent:Second-line and later settings expose patients to sequential immunotherapy and targeted therapy. Biomarker testing capacity constraints delay treatment initiation.
- Maintenance:Adjuvant nivolumab following radical cystectomy extends disease-free intervals. United States Medicare coverage determinations shape adoption across integrated delivery networks.
Advanced stage holds the largest patient population, while maintenance therapy is climbing fastest as adjuvant immunotherapy labels expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology specialists concentrate in Boston, Basel, and the Research Triangle, anchoring clinical trial infrastructure and protocol development for muscle-invasive disease regimens.
United States
Medicare reimbursement for adjuvant nivolumab and intravesical BCG alternatives drives hospital procurement restructuring. The FDA's breakthrough therapy pathway compresses approval timelines for PD-1 inhibitors. MD Anderson Cancer Center and Memorial Sloan Kettering anchor multi-site immuno-oncology trials across the Sun Belt corridor.
Germany
Hospital pharmacy and therapeutics committees centralize formulary decisions for checkpoint inhibitors under statutory health insurance frameworks. The BfArM coordinates with ANSM on EU Green Deal implementation timelines for intravesical agent reformulation. Heidelberg and Munich university hospitals lead adjuvant protocol enrollment in the Baden-Württemberg and Bavaria clusters.
Japan
PMDA's Sakigake designation accelerates local development of antibody-drug conjugates for urothelial carcinoma. METI's healthcare export initiative supports domestic pharma expansion into Southeast Asian markets. Tokyo and Osaka academic medical centers concentrate biomarker testing capacity for PD-L1 companion diagnostics.
United Kingdom
NICE technology appraisals shape NHS England access for premium immunotherapy across metastatic indications. The MHRA's post-Brexit recognition pathway diverges from EMA conditional authorization timelines. London's Royal Marsden and Manchester's Christie Hospital anchor the early-stage trial site network.
China
NMPA's priority review pathway for oncology therapies compresses domestic development timelines for PD-1 inhibitors. National reimbursement list negotiations determine hospital procurement volumes for novel agents. Beijing and Shanghai cancer centers lead investigator-initiated trials for combination regimens.
Global Bladder Cancer Therapeutics Market Vendor Landscape
Capital-heavy biopharmaceutical manufacturers compete with asset-light biotech developers for clinical asset control and commercialization rights. The market structure consolidates around three to five dominant checkpoint inhibitor franchises, with mid-tier players pursuing antibody-drug conjugate differentiation. Strategic archetypes include integrated pharma giants with oncology infrastructure, biotech specialists with platform technologies, and regional generics manufacturers with BCG production capacity. Competitive moves center on combination regimen patent estates and subcutaneous formulation development.
Among US-based integrated manufacturers, Bristol-Myers Squibb and Merck & Co. occupy positions anchoring the adjuvant and metastatic immunotherapy tiers. Pfizer represents the targeted therapy archetype through antibody-drug conjugate portfolio concentration. These three entities exemplify the scale-driven competitive vector where hospital system contracting leverage and Medicare coverage determination relationships determine formulary placement.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| Johnson & Johnson |
| F. Hoffmann-La Roche Ltd |
| Astellas Pharma Inc. |
| Pfizer Inc. |
| AstraZeneca plc |
| GlaxoSmithKline PLC |
| Eli Lilly and Company |
| Others |
Supply Flow & Price Mechanics
Integrated delivery network consolidation under risk-based Medicare Advantage contracts shapes both supply procurement and pricing discipline across hospital systems. This concentration compresses margin capture for manufacturers while amplifying volume leverage for formulary gatekeepers.
Pricing Analysis
Bundled episode-of-care contracts dominate hospital procurement, separating premium checkpoint inhibitor pricing from unbundled intravesical agent reimbursement. Three-tier pricing structure across innovator biologics, biosimilar candidates, and commodity chemotherapy anchors differentiation by FDA breakthrough designation status and companion diagnostic requirements. Pricing pressure stems from CMS national coverage determination timelines for combination regimens. Community oncology clinics exhibit highest price sensitivity due to Medicare fee-for-service reimbursement compression.
Supply Chain Analysis
Specialized oncology nursing workforce shortages in Germany, Japan, and the United States constrain infusion center capacity expansion for monoclonal antibody administration. Active pharmaceutical ingredient production for platinum agents concentrates in India and China, while sterile fill-finish capabilities cluster in Switzerland and Singapore. Single-source vulnerability for BCG bulk manufacturing creates protocol disruption risk. Distribution runs through cold-chain logistics networks serving hospital outpatient departments and specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bladder cancer therapeutics market functions as a stable compounder anchored by Medicare reimbursement expansion for adjuvant immunotherapy across aging demographics.
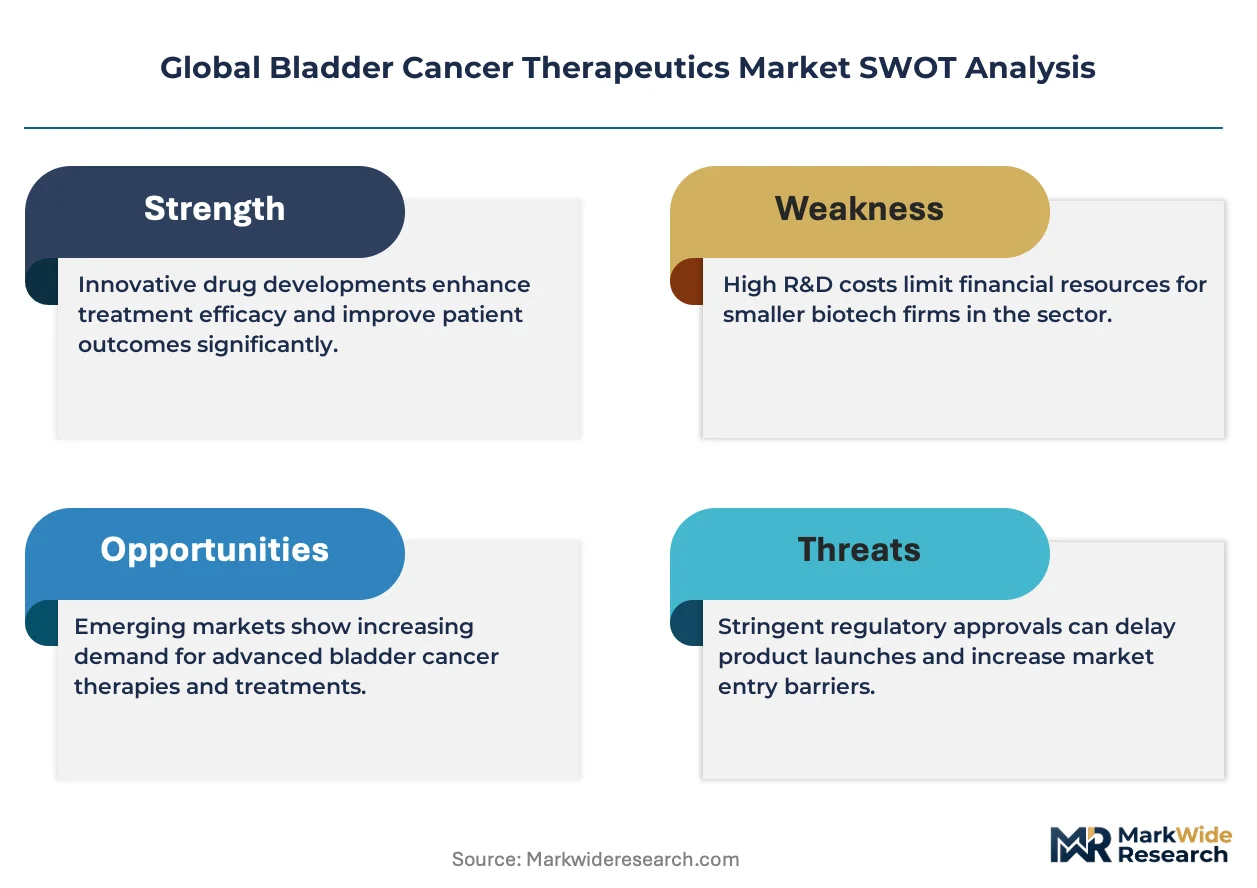
For Market Incumbents: Hedge platinum-based chemotherapy exposure by accelerating antibody-drug conjugate pipeline investment. Secure backward integration into companion diagnostic development to bypass PD-L1 testing capacity bottlenecks. Lock in multi-year hospital system contracts before biosimilar nivolumab entry. For New Entrants and Emerging Players: Capture subcutaneous formulation white space in community oncology settings underserved by academic medical center infusion capacity. Target EU Green Deal-compliant intravesical reformulation as first-mover sustainability positioning. Pursue licensing partnerships with established immuno-oncology franchises for combination trial access. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier antibody-drug conjugate specialists lacking commercial infrastructure but holding differentiated payloads. Five-to-ten-year viability hinges on bladder-preserving protocol adoption displacing radical cystectomy. Monitor FDA breakthrough therapy designation velocity for inflection signals on portfolio quality.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III enrollment for PD-1 and ADC combinations anchors future label expansion. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for urothelial carcinoma candidates. |
| Licensing Agreement | Companion diagnostic partnerships secure biomarker testing capacity for patient stratification. |
| Manufacturing Scale-Up | Subcutaneous formulation capacity expansion decentralizes care delivery to community settings. |
| Pipeline Diversification | BCG alternative development addresses supply concentration vulnerability in non-muscle-invasive disease. |
Methodological Framework
Multiple input streams — formulary director interviews, hospital procurement database analysis, and regulatory filing review — were reconciled to construct market estimates. Primary fieldwork engaged drug development executives, regulatory affairs leads, payer access specialists, and GPO contracts managers across the United States, Germany, and Japan. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS national coverage determination archives. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation were cross-checked for convergence.
Data-stream reconciliation across the projection horizon applied treatment line, administration route, and regional regulatory cluster segmentation. CAGRs were derived from modeled patient incidence flows, protocol penetration curves, and pricing trajectory assumptions. Forecast inputs included biomarker testing capacity expansion rates and Medicare Advantage penetration by integrated delivery network.
Regulatory approval delays, BCG supply disruption, and biomarker testing capacity constraints are the dominant revision risks to modeled outputs. Forecasts reflect assumptions on CMS coverage determination timing and EMA conditional authorization pathways. Practitioners should monitor FDA breakthrough therapy designation grants and BCG manufacturing inspection outcomes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Ureterorenoscopes Market
Urology
Primary Aldosteronism Market
Urology
Europe Urology Devices Market
Urology
India Urology Market
Urology
Urology Devices Market
Urology
Ureteral Obstruction Market
Urology
Varicocele Treatment Market
Urology
Global Urinary Tract Infections Therapeutics Market
Urology
Urology Surgery Supplies Market
Urology
Penile Cancer Market
Urology
Nordic Urinary Catheters Market
Urology
Urology Robotic Surgery Market
Urology
Nocturia Market
Urology
Male Urinary Incontinence Market
Urology
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market
Urology
Urology Ultrasound Market