
 Esource and Clinical Trials Market | 2026-2036
Esource and Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
Esource and Clinical Trials Market Analysis
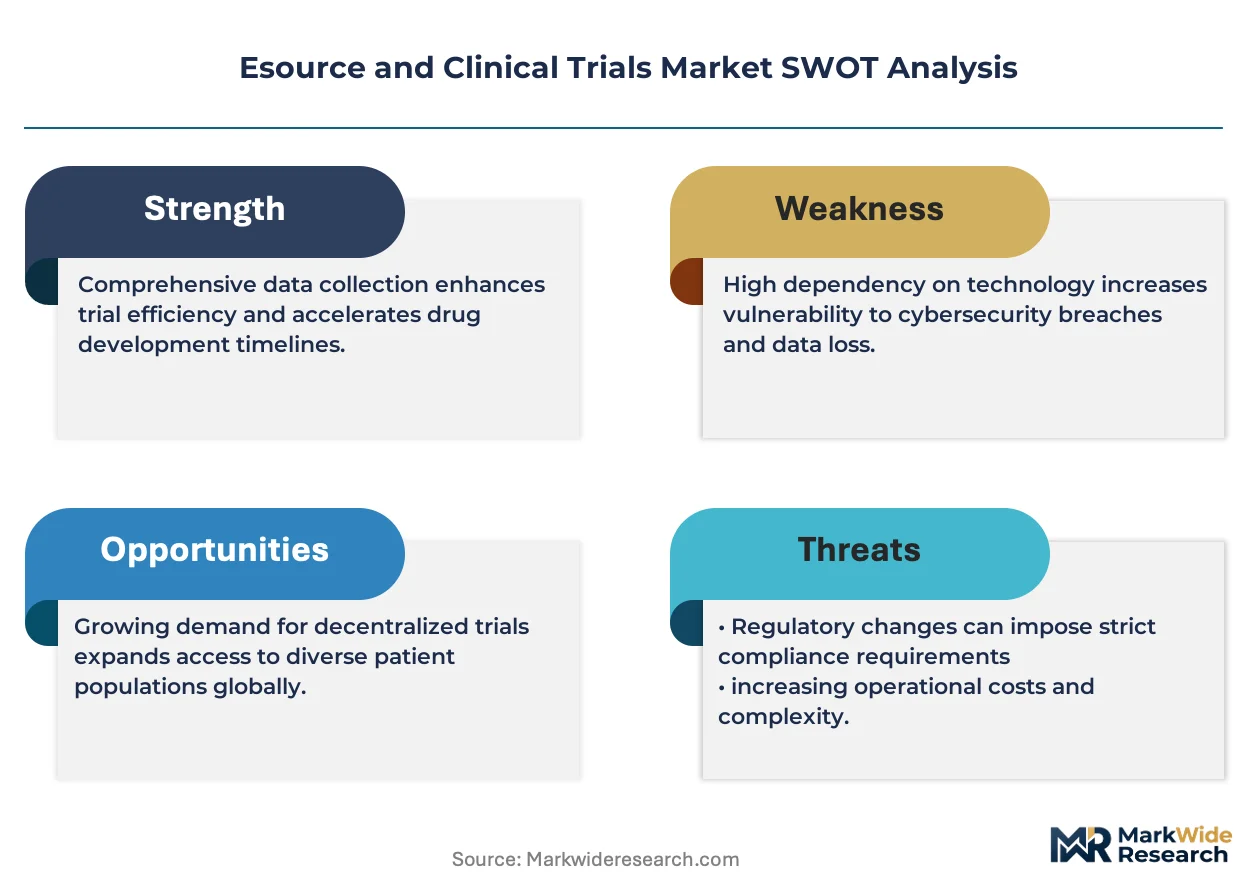
Subscription-based SaaS financing is tilting competitive dynamics toward asset-light vendors that bypass heavy on-premises infrastructure. IQVIA Inc. leverages its integrated data ecosystem to anchor enterprise relationships across trial phases. Oracle Corporation sustains platform stickiness through deep database architecture that research institutions depend upon for multi-site studies. Medidata Solutions Inc. specializes in patient-facing cloud tools that differentiate its offering from backend-heavy competitors.
eSource and clinical trials encompass digital systems that capture, manage, and transmit clinical research data electronically, replacing paper case report forms with validated electronic data capture platforms that enforce audit trails, real-time edit checks, and ALCOA+ compliance standards. Cloud-based platforms lead technology adoption due to elastic scalability and reduced validation overhead for mid-sized sponsors, while artificial intelligence segments represent the fastest-growing margin pool as machine learning automates protocol deviation detection and patient recruitment matching. Software as a Service dominates delivery models through predictable recurring revenue structures that appeal to pharmaceutical finance departments, whereas managed services retain strongholds among device firms lacking internal informatics teams.
FDA enforces 21 CFR Part 11 electronic records requirements that dictate validation protocols for any system handling submission-grade clinical data, while EMA coordinates Good Clinical Practice inspections that harmonize eSource acceptability across EU member states. ISO 14155 standards for medical device clinical investigations impose additional traceability demands that shape platform architecture decisions. Stakeholders must monitor evolving FDA guidance on decentralized trial elements and EMA policy on artificial intelligence in regulatory submissions to anticipate compliance-driven procurement cycles.
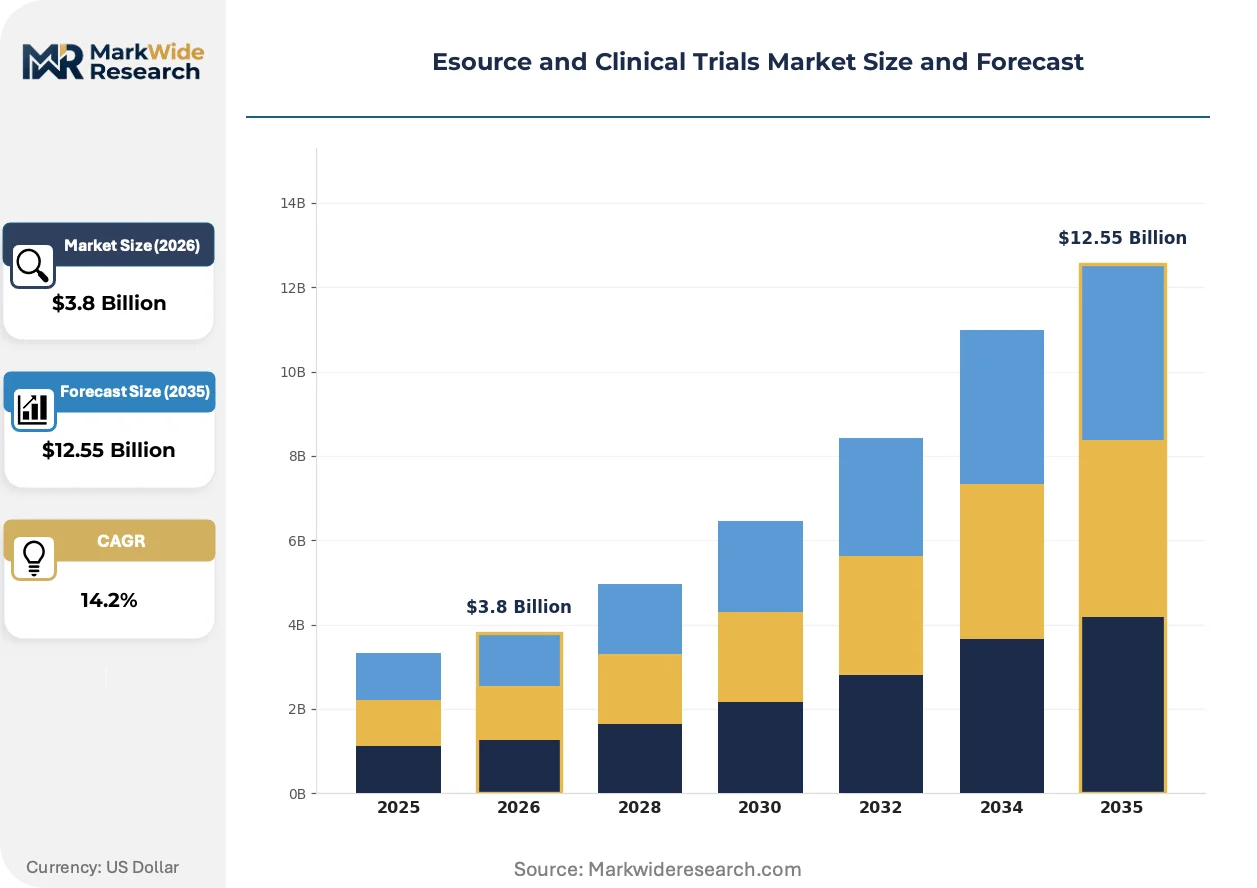
Market Dynamics
Biopharmaceutical sponsors are consolidating data infrastructure around cloud-native platforms that collapse the latency between patient encounter and database lock, compressing study timelines by eliminating transcription bottlenecks and source data verification cycles.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records validation mandates force sponsors to replace paper processes with compliant eSource platforms, creating procurement urgency across Phase II-III pipelines.
- Wearable sensor integration:Continuous glucose monitors, accelerometers, and ECG patches generate real-time digital biomarkers that eSource platforms aggregate for decentralized trial designs.
- EMA Good Clinical Practice harmonization:Cross-border inspection alignment reduces validation redundancy for multi-national studies, accelerating platform deployment across EU member states.
Market Restraints
- Legacy EHR interoperability gaps:Site-specific data format fragmentation forces expensive custom API development for each hospital system integration.
- Specialized informatics talent scarcity:Clinical data scientists with dual competency in regulatory science and cloud architecture command premium compensation that mid-sized CROs cannot match.
- Validation cost concentration:FDA computer system validation requirements impose documentation burdens that consume 18-24 months of implementation runway for new deployments.
Strategic Opportunities
- India CDSCO regulatory pathway:Streamlined clinical trial approval timelines and cost-competitive site networks attract sponsors seeking geographic diversification beyond traditional US-EU corridors.
- Artificial intelligence protocol optimization:Machine learning models that predict enrollment bottlenecks and site performance are converging with eSource platforms to automate study design.
- Direct-to-patient recruitment channels:Social media and telehealth platforms bypass traditional site-based enrollment, opening access to underrepresented populations.
Industry Challenges
- ALCOA+ compliance engineering:Attributable, legible, contemporaneous, original, and accurate data standards require architectural redesign of audit trail systems to capture metadata at millisecond granularity.
- Multi-modal data fusion complexity:Integrating EHR extracts, wearable streams, and patient-reported outcomes into unified datasets demands specialized data engineering pipelines that most sponsors lack in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Esource and Clinical Trials Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Esource Solutions, Clinical Data Management, Patient Engagement Tools, Trial Design Software Technology: Cloud-Based Platforms, Mobile Applications, Artificial Intelligence, Blockchain End User: Pharmaceutical Companies, CROs, Research Institutions, Medical Device Firms Delivery Model: Software as a Service, On-Premises Solutions, Managed Services, Open Source Platforms |
| Companies Covered | IBM Corporation, Oracle Corporation, IQVIA Inc., Icon PLC, Medidata Solutions Inc., Parexel International Corporation, Syneos Health Inc., Medpace Holdings Inc., Clario, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Esource and Clinical Trials Market Emerging Trajectories
Real-time data streaming architectures are displacing batch-oriented EDC systems, enabling continuous monitoring that collapses the gap between data collection and safety signal detection.
Federated learning frameworks are collapsing the traditional model where raw patient data must centralize for analysis. Biopharmaceutical sponsors and academic medical centers deploy edge-computing nodes that train algorithms locally, transmitting only model parameters to preserve privacy while enabling multi-site analytics. FDA guidance on decentralized trial elements validates this architecture, accelerating adoption among sponsors with sensitive therapeutic areas.
EMA policy coordination on artificial intelligence in regulatory submissions is compressing uncertainty timelines for machine learning-enabled eSource tools. The regulator's qualification pathway for AI/ML-based software as medical devices clarifies validation requirements, enabling vendors to pre-position algorithmic patient matching and protocol deviation detection for formal acceptance. Sponsors in oncology and rare disease trials, where recruitment timelines determine program viability, are prioritizing these capabilities in platform selections.
Site economics are forcing procurement model evolution from perpetual licenses toward consumption-based pricing. Mid-sized hospital systems and independent investigator sites, facing margin compression from staffing costs, reject fixed-fee platform contracts that assume full utilization. Vendors responding with per-patient, per-visit pricing capture volume from sponsors running adaptive trial designs with variable enrollment trajectories. This shift is most visible in the United States, where site consolidation has concentrated negotiating leverage among large academic research organizations.
Esource and Clinical Trials Market Segmentation
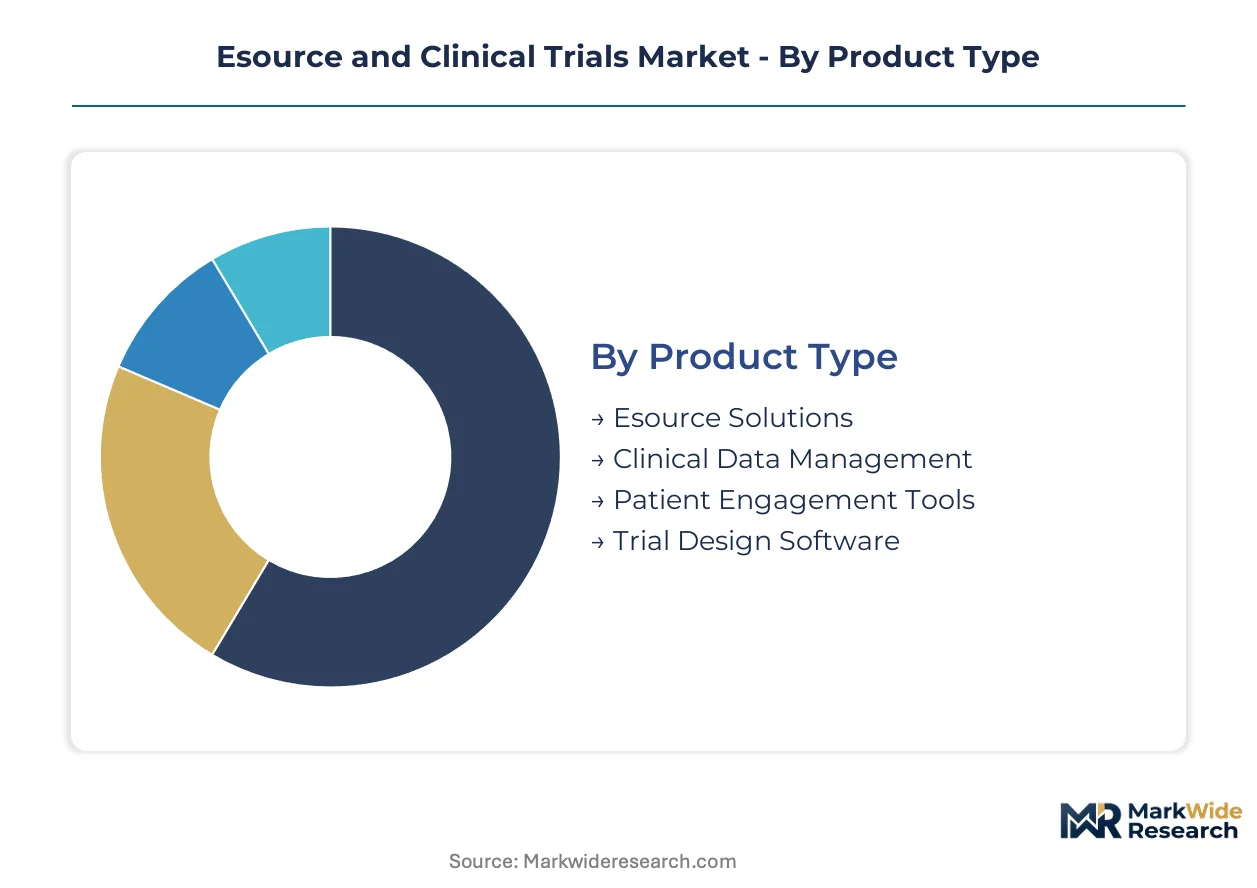
eSource and clinical trials segmentation reflects divergent procurement priorities across sponsor sophistication levels. Technology choices determine validation burden, while delivery models shape capital allocation for mid-sized versus enterprise-scale operations.
Product Type:
Cost tier stratification separates enterprise-grade integrated suites from modular point solutions targeting budget-constrained sites.
- Esource Solutions:Direct electronic data capture from source systems eliminates transcription latency between patient encounter and database lock. Pharmaceutical sponsors in the United States prioritize these platforms to compress Phase II-III timelines and reduce source data verification overhead.
- Clinical Data Management:Centralized repositories enforce ALCOA+ compliance through automated audit trails and real-time edit checks. Demand concentrates among CROs managing multi-site oncology studies where data integrity failures risk regulatory rejection.
- Patient Engagement Tools:Decentralized trial enablement through eConsent and telehealth portals.
- Trial Design Software:Protocol optimization and simulation engines for adaptive study architectures.
Esource solutions command the established base. The steepest expansion runs through patient engagement tools.
Technology:
Application maturity varies sharply, with production deployments trailing pilot enthusiasm for emerging architectures.
- Cloud-Based Platforms:Elastic infrastructure eliminates on-premises validation overhead while enabling real-time multi-site collaboration. Research institutions across Germany and the United Kingdom favor these deployments for their reduced IT staffing requirements and automatic software updates.
- Artificial Intelligence:Machine learning automates patient recruitment matching and protocol deviation detection in decentralized trials. Sponsors in rare disease therapeutic areas deploy these tools to collapse enrollment timelines that otherwise threaten program viability.
- Mobile Applications:Patient-facing data capture for bring-your-own-device trial designs.
- Blockchain:Immutable audit trails for regulatory-grade data provenance verification.
Cloud-based platforms anchor current procurement volumes. Artificial intelligence applications are climbing the fastest as regulatory qualification pathways clarify.
End User:
Customer type dictates platform complexity, with enterprise sponsors demanding integration depth that mid-sized buyers cannot justify.
- Pharmaceutical Companies:Enterprise-scale deployments spanning discovery through post-market surveillance require validated integrations with legacy safety databases. Headquarters clusters in Massachusetts and New Jersey drive specification standards that cascade through vendor roadmaps.
- CROs:Multi-tenant architectures enabling simultaneous study management for competing sponsors without data commingling. These organizations in India and Eastern Europe prioritize cost-competitive per-patient pricing models.
- Research Institutions:Grant-funded academic medical centers with constrained capital budgets.
- Medical Device Firms:ISO 14155-compliant traceability requirements for investigational device studies.
Pharmaceutical companies retain procurement volume leadership. CROs are gaining share fastest as sponsor outsourcing accelerates.
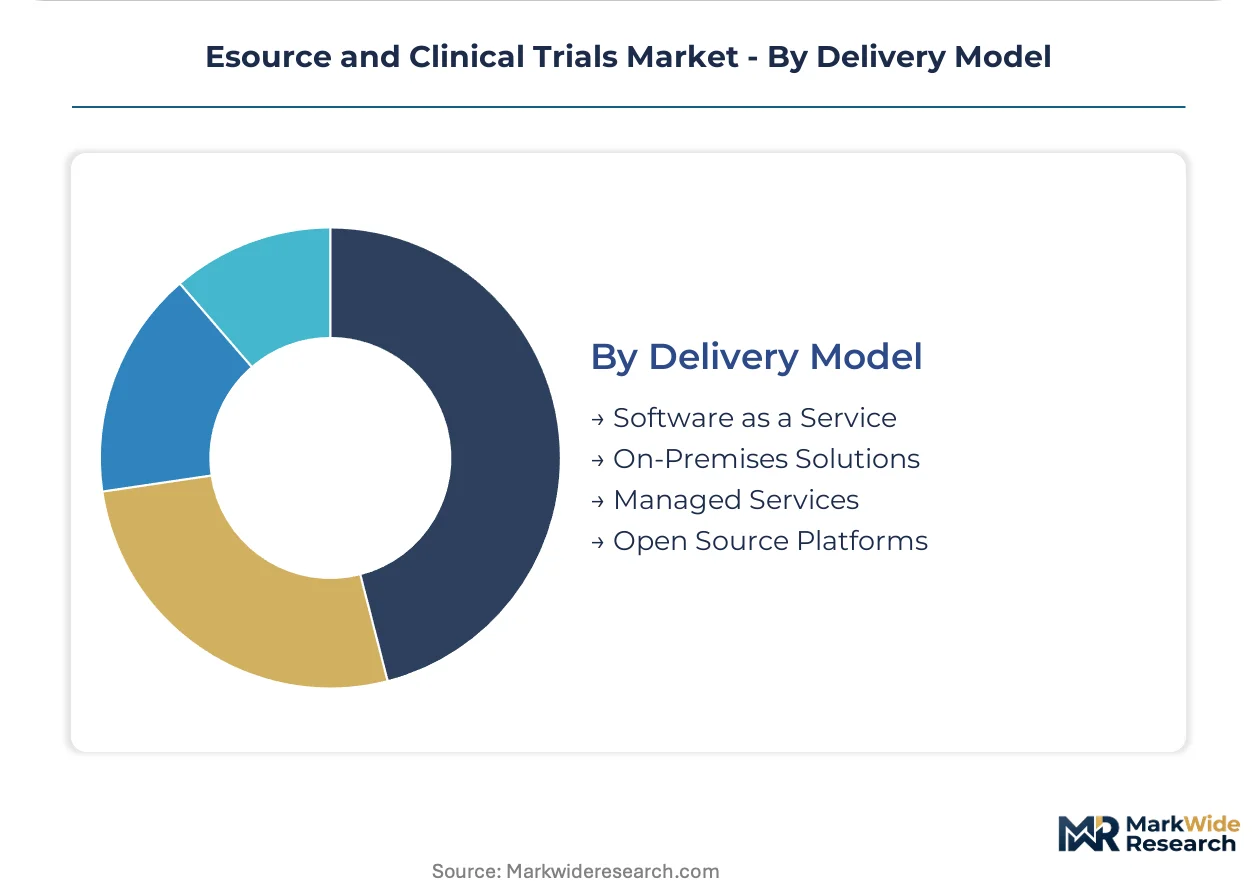
Delivery Model:
Margin structure and revenue predictability diverge across deployment architectures, reshaping vendor competitive positioning.
- Software as a Service:Subscription pricing aligns vendor incentives with sponsor success through recurring revenue structures. Finance departments at mid-sized biopharmaceutical firms favor these models for their predictable operational expenditure profiles.
- Managed Services:Full-stack outsourcing including validation, hosting, and data management for organizations lacking internal informatics capabilities. Medical device manufacturers in Minnesota and California clusters rely on these arrangements to navigate FDA computer system validation requirements.
- On-Premises Solutions:Air-gapped deployments for sponsors with data sovereignty constraints.
- Open Source Platforms:Community-supported alternatives for academic and non-commercial research.
Software as a Service dominates new contract value. Managed services retain defensive positions among device-focused sponsors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical headquarters concentration in the United States drives enterprise-scale procurement, while cost-competitive trial networks in India and regulatory harmonization across Germany and the United Kingdom shape deployment patterns.
United States
Massachusetts and New Jersey biotech clusters generate concentrated demand for validated eSource platforms spanning Phase II-III oncology trials. FDA 21 CFR Part 11 enforcement creates procurement urgency for electronic records compliance. Large academic research organizations in Boston and San Francisco negotiate consumption-based pricing models that cascade through vendor roadmaps.
Germany
Research institutions across Bavaria and North Rhine-Westphalia favor cloud-based deployments to reduce IT staffing overhead. EMA Good Clinical Practice harmonization accelerates multi-national study validation without redundant inspections. The Heidelberg-Mannheim medical technology corridor anchors decentralized trial pilot programs integrating wearable biomarkers.
United Kingdom
London-based CROs and Cambridge biotech firms prioritize platforms with real-time multi-site collaboration capabilities. NHS Digital interoperability frameworks shape EHR integration requirements for site networks. The Oxford-London-Bristol triangle concentrates adaptive trial design software procurement for rare disease studies.
India
CDSCO regulatory pathway streamlining attracts sponsors seeking geographic diversification beyond traditional US-EU corridors. Hyderabad and Bangalore CRO clusters drive demand for cost-competitive per-patient pricing models. Mumbai pharmaceutical headquarters outsource data management to domestic vendors with managed service capabilities.
Switzerland
Basel-based pharmaceutical giants specify integration standards that cascade through vendor development priorities. Swissmedic alignment with EMA inspection protocols reduces validation redundancy for EU-facing studies. The Zurich-Geneva corridor concentrates post-market surveillance platform deployments for device firms.
Esource and Clinical Trials Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where enterprise-scale integrated suites command premium positioning against modular point solutions. Consolidation pressure intensifies as biopharmaceutical sponsors reduce vendor counts to streamline validation overhead. Two archetypes dominate: database-architecture incumbents leveraging institutional stickiness, and patient-facing cloud specialists capturing decentralized trial growth. Competitive moves center on federated learning partnerships and consumption-based pricing pivots to capture mid-sized site volume.
Within the integrated-data-ecosystem tier, IQVIA Inc. and Oracle Corporation exemplify channel-controlling positioning through multi-phase trial infrastructure. Medidata Solutions Inc. occupies the patient-facing specialization vector with cloud tools differentiated from backend-heavy alternatives. These three anchors represent the strategic spectrum from enterprise relationship depth to decentralized trial enablement.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| IQVIA Inc. |
| Icon PLC |
| Medidata Solutions Inc. |
| Parexel International Corporation |
| Syneos Health Inc. |
| Medpace Holdings Inc. |
| Clario |
| Others |
Supply Flow & Price Mechanics
Frankfurt-Dubai air freight corridors channel high-value clinical trial kits and temperature-controlled biologics, with per-kilogram rates directly indexing into SaaS platform pricing tiers that sponsors negotiate across United States and European deployments. This logistics backbone concentrates vendor pricing power among cloud-hosting providers with redundant data center footprints, while forcing mid-sized CROs toward consumption-based models that pass through freight volatility.
Pricing Analysis
Cost-plus contracts with consumer price indexation dominate enterprise SaaS agreements, anchoring multi-year subscriptions to inflation benchmarks that pharmaceutical finance departments favor for budget predictability. Three-tier pricing structure across premium, standard, and economy levels separates validated 21 CFR Part 11-compliant suites from modular point solutions targeting academic sites. Pricing pressure stems from site consolidation among large academic research organizations demanding per-patient, per-visit terms. Mid-sized biopharmaceutical sponsors exhibit highest price sensitivity due to constrained operational expenditure budgets, while Basel-based pharmaceutical giants prioritize integration depth over unit cost.
Supply Chain Analysis
Export control regimes restricting high-performance GPU and quantum-resistant encryption technology flows from United States and Netherlands shape platform architecture decisions for vendors serving multi-national studies. Software development concentrates in United States, Ireland, and India, with cloud infrastructure drawing from hyperscaler regions across Germany, United Kingdom, and Singapore. Supply chain risk centers on single-source vulnerability for specialized clinical data scientists with dual competency in regulatory science and cloud architecture. Distribution runs through direct enterprise sales teams for pharmaceutical sponsors and channel partnerships with CROs for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where EHR interoperability standards and federated learning frameworks are collapsing traditional data centralization models. Vendors capturing API ecosystem control will anchor procurement decisions across sponsor organizations.
For Market Incumbents: Insulate enterprise relationships by deepening integration with legacy safety databases and clinical data warehouses that sponsors cannot easily migrate. Acquire specialized patient-facing cloud tools to defend against decentralized trial specialists. Prioritize certification investment in FDA computer system validation documentation that accelerates procurement cycles for Phase II-III pipelines. For New Entrants and Emerging Players: Build out federated learning infrastructure for academic medical centers seeking privacy-preserving multi-site analytics without raw data centralization. Target India CDSCO regulatory pathway services where cost-competitive site networks attract geographic diversification beyond traditional corridors. Pursue channel partnerships with Hyderabad and Bangalore CRO clusters as the primary go-to-market angle. For Investors and Strategic Acquirers: AI-enabled protocol optimization specialists with regulatory qualification pathway progress represent the most compelling acquisition target archetype in this market. Long-term viability hinges on vendors capturing recurring revenue from adaptive trial designs with variable enrollment trajectories. Watch for FDA guidance finalization on decentralized trial elements as the signal indicating accelerated procurement for compliant platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Federated learning partnerships with academic medical centers collapse data centralization requirements while preserving privacy. |
| Regulatory Approval Pathway | FDA 21 CFR Part 11 validation documentation accelerates procurement cycles for Phase II-III oncology sponsors. |
| Strategic Partnership | EHR interoperability alliances with Epic and Cerner reduce site-specific API development costs for hospital system integrations. |
| Geographic Expansion | India CDSCO regulatory services capture geographic diversification demand from sponsors seeking cost-competitive site networks. |
| Acquisition of Specialist Firm | Patient-facing cloud tools extend enterprise suites into decentralized trial enablement for rare disease recruitment. |
Methodological Framework
Initial hypotheses were tested against primary input from clinical data management executives, regulatory affairs leads at biopharmaceutical sponsors, CRO procurement officers, and hospital IT directors, and refined through secondary validation against FDA 21 CFR Part 11 guidance documents, EMA Good Clinical Practice inspection reports, ClinicalTrials.gov registry data, and ISO 14155 medical device standards. Bottom-up segmentation modeling triangulated against top-down market sizing from pharmaceutical R&D expenditure disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning technology deployment model, sponsor organization size, therapeutic area regulatory cluster, and regional adoption pattern. CAGRs were derived from elasticity-adjusted growth rate calibration against historical platform procurement cycles. Forecast inputs incorporated CDSCO approval timeline trends and EMA AI qualification pathway progression.
Stress conditions across FDA enforcement intensity, EMA inspection harmonization pace, and site consolidation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cloud infrastructure cost curves and clinical informatics talent availability. Material shifts in decentralized trial regulatory guidance or EMA AI policy finalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Omics-Based Clinical Trials Market
Clinical Research
US Clinical Trials Market
Clinical Research
India CRO Market
Clinical Research
Global Clinical Trial Supply Management Market
Clinical Research
North America Contract Research Organization Market
Clinical Research
Clinical Trials Site Management Organizations Market
Clinical Research
Clinical Trial Investigative Site Network Market
Clinical Research
Generative AI in Clinical Trials Market
Clinical Research
US Virtual Clinical Trials Market
Clinical Research
Global in Silico Clinical Trials Market
Clinical Research
Clinical Trial Patient Recruitment Services Market
Clinical Research
Global Virtual Clinical Trials Market
Clinical Research
Global Healthcare Contract Research Outsourcing Market
Clinical Research
Global Clinical Trial Management Systems Market
Clinical Research
Edema Clinical Trials Market
Clinical Research
Humanized Mice Model Market