
 Ureteral Obstruction Market | 2026-2036
Ureteral Obstruction Market Size, Share, and Industry Trends Forecast 2026-2036
Ureteral Obstruction Market Outlook
Modular stent-delivery kits is recalibrating buyer preference across procurement departments. Boston Scientific Corporation leverages its integrated manufacturing footprint to control cost structures in balloon-expandable platforms. Richard Wolf GmbH specializes in rigid endoscopic systems that anchor its position in laparoscopic ureteral interventions. Cook Medical sustains broad SKU coverage across stent geometries and material durometers.
Ureteral obstruction denotes any impediment to urine flow from the renal pelvis to the bladder, encompassing intrinsic luminal narrowing from calculi, extrinsic compression by pelvic tumors, or congenital strictures at the ureteropelvic junction; devices address this through mechanical dilation, temporary scaffolding, or definitive surgical correction. Stents command the largest product-type position due to repeat exchange cycles and biofilm-resistant polymer formulations. Minimally invasive delivery modes capture the fastest expansion as fluoroscopy-guided and ultrasound-assisted placements reduce operative time and recovery intervals. Ambulatory surgical centers represent an emerging margin pool where procedure bundling and same-day discharge protocols concentrate purchasing power.
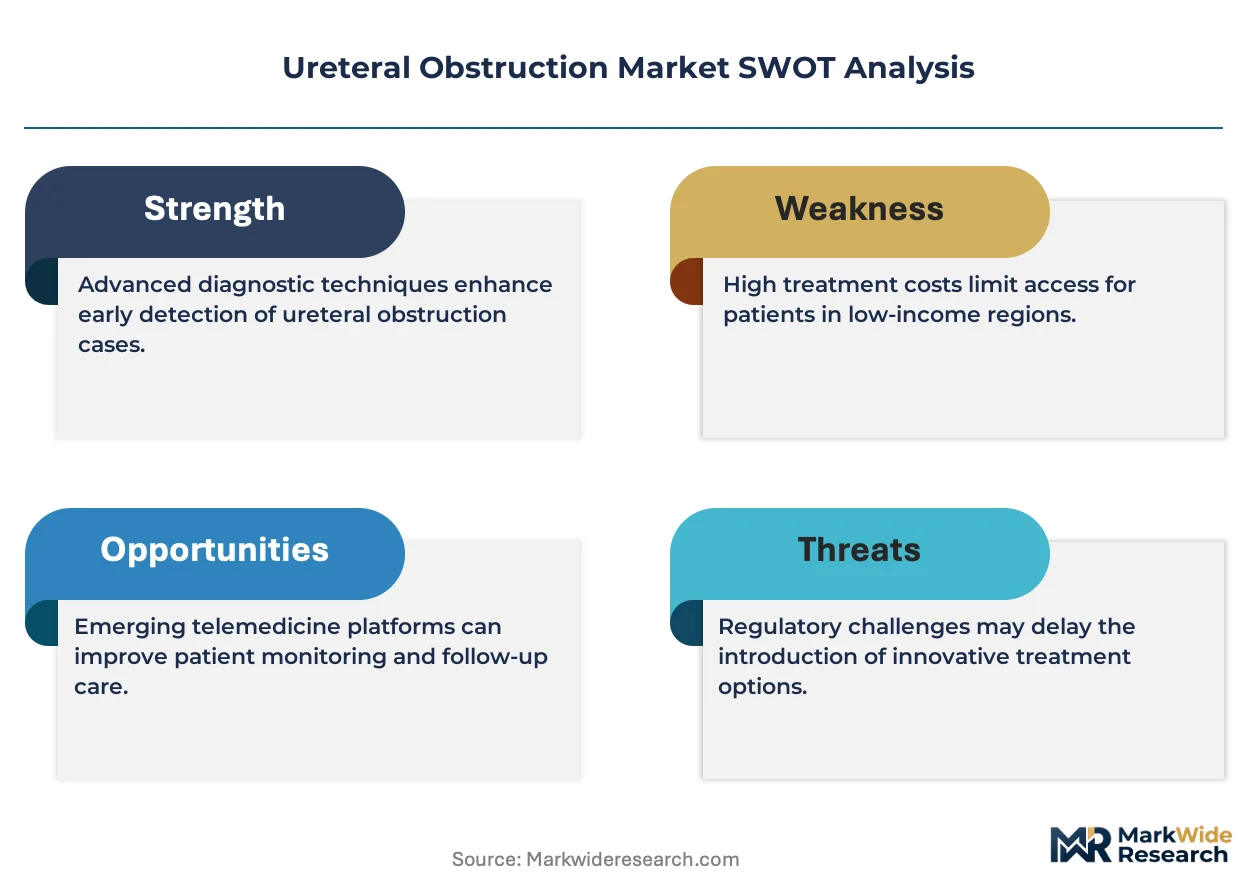
The FDA governs device safety and effectiveness through 510(k) premarket notification and PMA pathways, while ISO 13485 quality-management standards shape supplier audit requirements across OEM relationships. Health Technology Assessment bodies in Germany and France evaluate cost-effectiveness for reimbursement eligibility, directing R&D investment toward clinical-economic evidence generation. Stakeholders must monitor evolving bioabsorbable polymer regulations and real-world performance registry mandates that will reshape competitive differentiation beyond traditional mechanical specifications.
Market Dynamics
Outpatient migration is compressing inpatient procedural economics and redistributing purchasing authority toward ambulatory surgical centers across the United States. This structural force is reshaping device specifications, bundling requirements, and supplier relationship models throughout the ureteral obstruction value chain.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's abbreviated premarket notification pathway accelerates ureteral stent approvals and truncates commercialization timelines for polymer innovations.
- Aging Demographics:Elevated kidney stone prevalence among Medicare-eligible populations in the United States sustains procedural volume expansion and repeat intervention cycles.
- Fluoroscopy-Guided Placement:Real-time imaging integration reduces operative time and recovery intervals, driving adoption across outpatient urology practices.
Market Restraints
- Specialty Polymer Cost Volatility:Biofilm-resistant silicone and proprietary polymer feedstocks expose manufacturers to petrochemical price swings and formulation stability risks.
- Supplier Concentration in Indiana and Massachusetts:Domestic stent manufacturing clusters create geographic vulnerability to regional logistics disruptions and labor market tightness.
- Health Technology Assessment Gatekeeping:German IQWiG and French HAS cost-effectiveness thresholds restrict reimbursement for novel stent geometries absent robust clinical-economic evidence.
Strategic Opportunities
- Same-Day Discharge Protocols:Ambulatory surgical centers in Texas and Florida are consolidating purchasing power through procedure bundling and vendor rationalization programs.
- Bioabsorbable Polymer Convergence:Magnesium alloy scaffolds combined with controlled-release drug coatings eliminate retrieval procedures and capture premium positioning.
- Rural Health Clinic Expansion:Federally qualified health centers in Appalachia and the Mississippi Delta remain underserved for ureteral interventions, creating whitespace for mobile lithotripsy deployment.
Industry Challenges
- Interventional Radiology Skill Compression:Shortages of fluoroscopy-certified urologists and radiology technicians constrain procedure throughput in community hospital settings.
- Real-World Performance Registry Mandates:Emerging FDA post-market surveillance requirements for ureteral stents demand costly data infrastructure and longitudinal patient tracking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ureteral Obstruction Market |
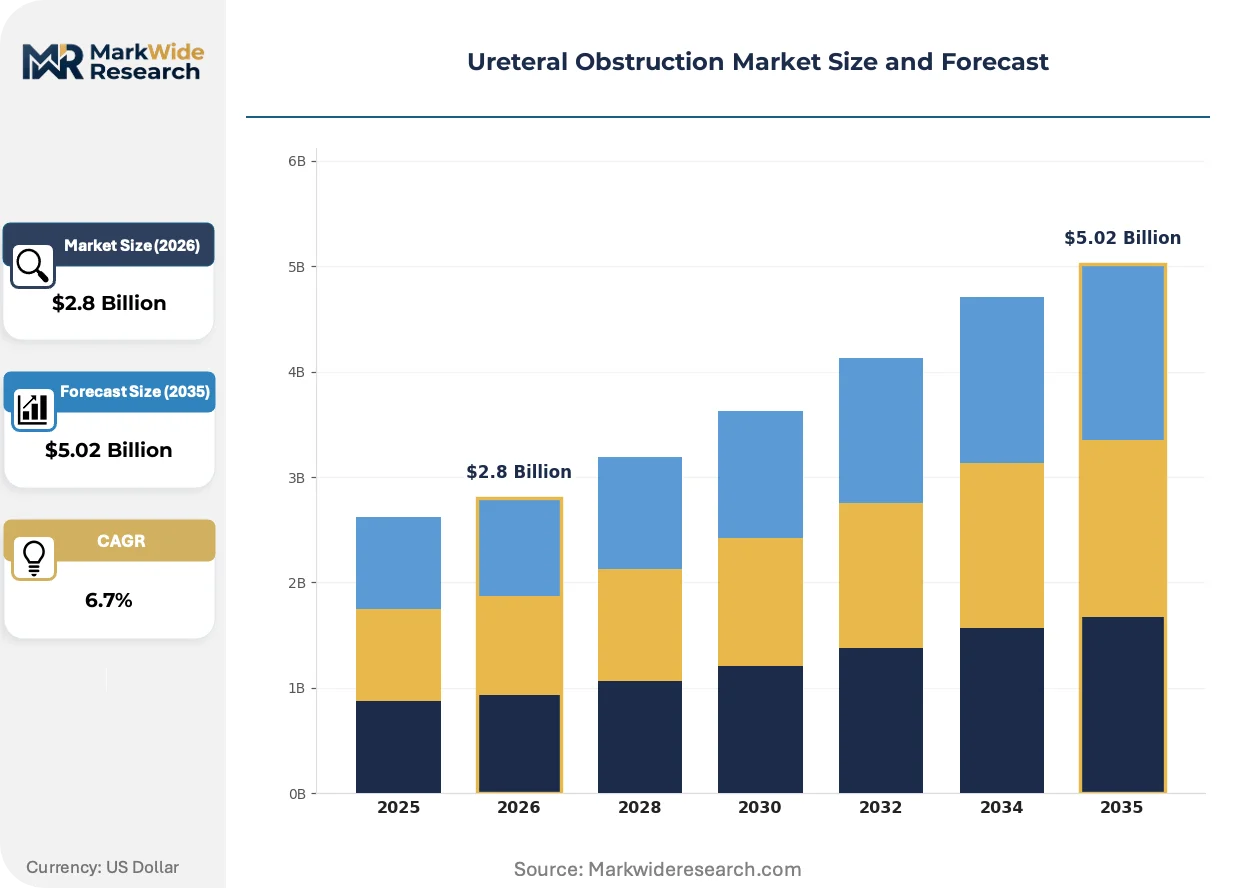
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Catheters, Balloons, Other Tools End User: Hospitals, Ambulatory Surgical Centers, Clinics, Home Care Settings Indication: Kidney Stones, Tumors, Congenital Defects, Other Conditions Delivery Mode: Open Surgery, Minimally Invasive Procedures, Laparoscopic Surgery, Other Approaches |
| Companies Covered | Becton Dickinson and Company, Olympus Corporation, Boston Scientific Corporation, Stryker Corporation, Richard Wolf GmbH, B. Braun Melsungen AG, Teleflex Incorporated, Coloplast Corporation, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ureteral Obstruction Market Strategic Shifts
Device architecture is fragmenting into configurable component systems that permit intraoperative customization without inventory proliferation. This modularization is compressing SKU complexity while expanding clinical versatility across stone burden variations.
Stent-delivery platforms are modularizing around interchangeable catheter shafts, balloon dimensions, and guidewire compatibility specifications. Ambulatory surgical centers in the Southwestern United States are standardizing on these systems to reduce capital commitment and sterilization overhead. The structural consequence is compressing distributor margins while elevating direct manufacturer relationships for consumable replenishment.
The FDA's evolving guidance on bioabsorbable ureteral devices is tightening preclinical testing requirements for polymer degradation profiles and tissue interaction studies. Manufacturers must now submit longitudinal histopathology data that extends approval timelines by twelve to eighteen months. Urology divisions at academic medical centers are responding by front-loading clinical trial partnerships to secure early access pathways.
Hospital procurement committees are consolidating vendor relationships through master service agreements that bundle stents, retrieval devices, and technical support into per-procedure fees. This displaces traditional capital equipment purchases and discrete consumable ordering. The shift is most visible in integrated delivery networks across Pennsylvania and Ohio, where supply chain rationalization targets twenty-percent cost reduction.
Ureteral Obstruction Market Segmentation
Ureteral obstruction devices serve distinct clinical workflows that impose divergent regulatory and reimbursement requirements. Procurement committees evaluate segments through the lens of FDA pathway complexity, sterilization protocols, and procedure bundling economics.
Product Type:
FDA 510(k) clearance timelines vary substantially across this category, with permanent implants facing PMA-level scrutiny while temporary devices navigate abbreviated pathways.
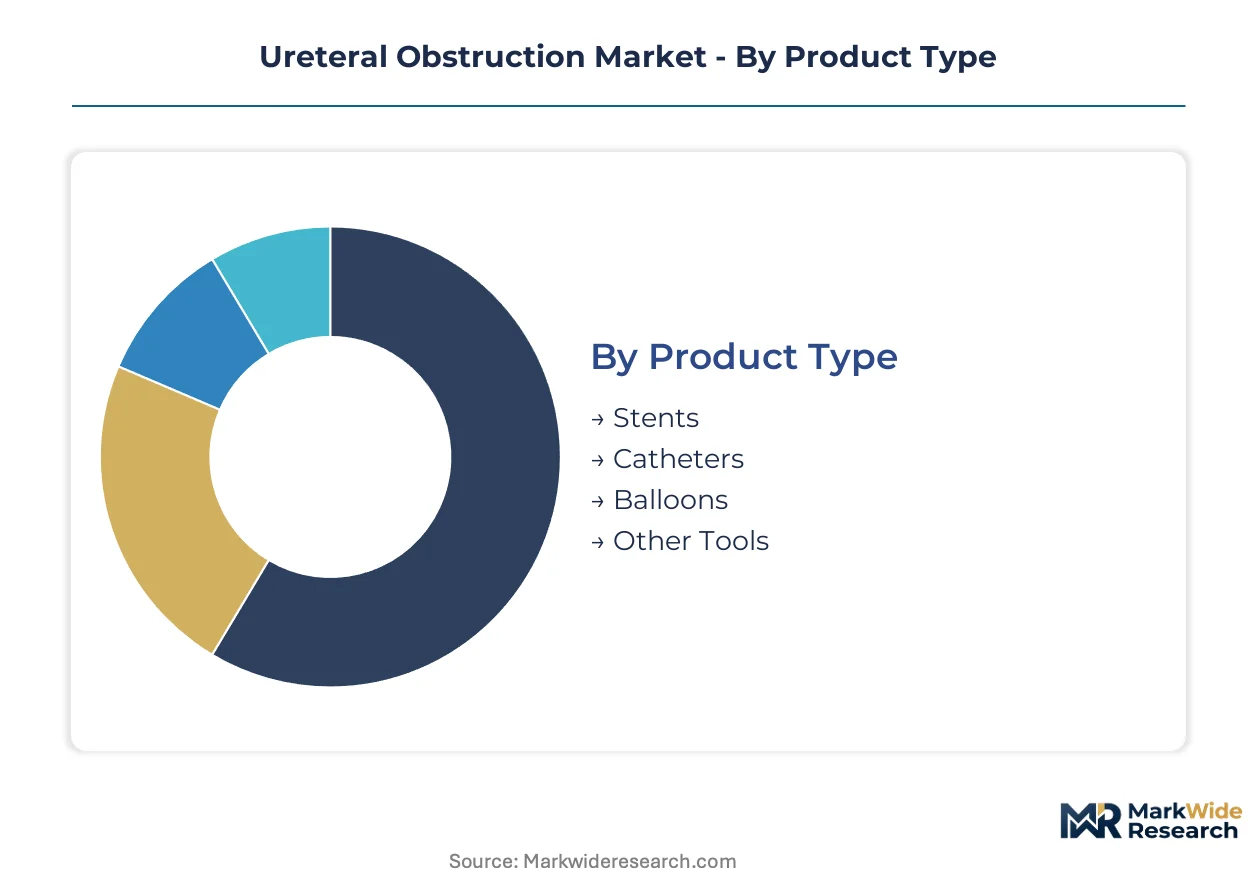
- Stents:Double-J and multi-length configurations dominate procedural volumes through biofilm-resistant silicone and proprietary polymer formulations. Demand concentrates in ambulatory surgical centers across Texas and Florida where same-day exchange protocols drive repeat purchasing cycles.
- Balloons:High-pressure dilation platforms address stricture recalcitrance with rated burst pressures exceeding 20 atmospheres. Academic medical centers in Pennsylvania and Ohio prioritize these systems for complex ureteropelvic junction revisions.
- Catheters:Drainage and access devices with hydrophilic coatings reduce insertion trauma in emergency department settings.
- Other Tools:Guidewires, retrieval snares, and irrigation systems complete procedural kits for lithotripsy suites.
Stents sit at the top of the volume ranking, with balloons climbing the fastest as high-pressure platforms displace sequential dilation techniques.
End User:
Capital intensity and sterilization infrastructure separate institutional buyers, with reimbursement differentials reshaping purchasing authority across settings.
- Ambulatory Surgical Centers:Procedure bundling and vendor rationalization programs concentrate negotiating leverage for disposable stent systems. Texas and Florida facilities lead outpatient migration through same-day discharge protocols that compress per-case costs.
- Hospitals:Integrated delivery networks maintain captive sterilization capacity for reusable endoscopic platforms. Academic centers anchor complex reconstructive volumes requiring hybrid operating room infrastructure.
- Clinics:Urology group practices in suburban markets handle diagnostic stent placements with limited fluoroscopy suites.
- Home Care Settings:External drainage systems serve palliative populations with nephrostomy tube management outside institutional walls.
Ambulatory surgical centers sit at the top of the volume ranking, with home care settings climbing the fastest as remote monitoring technologies expand catheter management capabilities.
Indication:
Clinical presentation dictates device selection, with stone burden algorithms and oncologic staging creating distinct specification requirements.
- Kidney Stones:Calculous obstruction generates the highest procedural frequency through seasonal recurrence patterns and metabolic syndrome prevalence. Medicare-eligible populations in the United States sustain volumes through repeat intervention cycles.
- Tumors:Extrinsic compression from gynecologic and colorectal malignancies demands longer indwelling durations with drug-eluting stent technologies.
- Congenital Defects:Pediatric ureteropelvic junction obstructions require smaller-diameter platforms with growth-accommodating designs.
- Other Conditions:Retroperitoneal fibrosis and iatrogenic strictures comprise the residual indication set.
Kidney stones sit at the top of the volume ranking, with tumors climbing the fastest as oncologic stenting protocols extend device dwell times.
Delivery Mode:
Surgeon training pipelines and facility reimbursement structures determine adoption velocity across invasive spectrums.
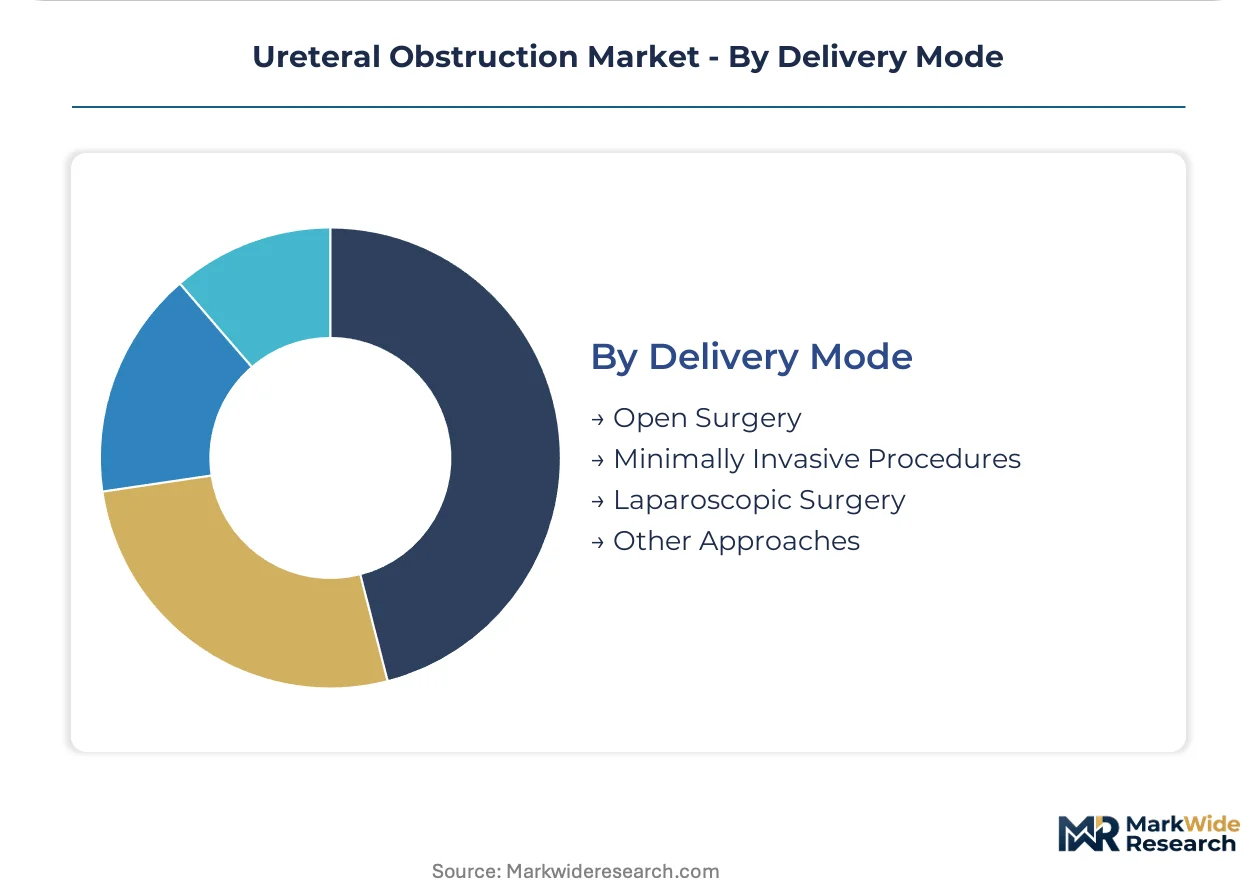
- Minimally Invasive Procedures:Fluoroscopy-guided and ultrasound-assisted placements reduce operative time and recovery intervals. Outpatient urology practices standardize on these modalities to maximize case throughput.
- Laparoscopic Surgery:Robotic-assisted reconstruction addresses complex strictures with intracorporeal suturing capabilities. Academic centers anchor these volumes through fellowship-trained reconstructive specialists.
- Open Surgery:Definite repair of congenital anomalies and trauma reconstruction retains indication in specific anatomical variants.
- Other Approaches:Combined antegrade-retrograde rendezvous techniques salvage failed primary access attempts.
Minimally invasive procedures sit at the top of the volume ranking, with laparoscopic surgery climbing the fastest as robotic platform penetration expands reconstructive capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ureteral obstruction device manufacturing traces its commercial origins to post-war Massachusetts and Indiana, where polymer chemistry expertise from defense contractors transferred to medical applications. These clusters remain active today, though competitive dynamics now span multiple continents.
United States
Medicare reimbursement codes for outpatient urological procedures sustain procedural volumes among aging populations with elevated kidney stone prevalence. FDA 510(k) premarket notifications dominate device approvals, compressing commercialization timelines for polymer innovations. Manufacturing concentrates in Indiana and Massachusetts clusters, where regional labor market tightness creates periodic supply vulnerabilities.
Germany
IQWiG cost-effectiveness thresholds direct procurement toward devices with robust clinical-economic evidence, filtering reimbursement eligibility for novel stent geometries. CE marking under EU MDR governs market access, with notified body capacity constraints extending certification timelines. Industrial activity clusters in Baden-Württemberg and Bavaria, where academic medical centers anchor complex reconstructive volumes.
Japan
PMDA marketing authorization requirements emphasize longitudinal safety data for polymer degradation profiles, extending approval timelines relative to US pathways. METI industrial policy supports domestic manufacturing of high-value medical devices. Tokyo and Osaka metropolitan areas concentrate urology specialist practices and fluoroscopy-equipped outpatient facilities.
United Kingdom
NICE technology appraisals evaluate cost-per-quality-adjusted-life-year for ureteral interventions, shaping hospital procurement committee decisions. MHRA post-Brexit regulatory autonomy permits divergence from EU MDR implementation timelines. Greater London and the Southeast maintain the highest density of lithotripsy suites and ambulatory surgical centers.
India
CDSCO medical device rules classify ureteral stents as Class C devices, requiring import licenses and quality system documentation for foreign manufacturers. PLI scheme incentives for domestic medical device production attract contract manufacturing investments. Karnataka and Maharashtra host emerging clusters of urology consumables fabrication serving South Asian markets.
Ureteral Obstruction Market Competitive Environment
Premium-margin players sit above commodity-margin players across polymer formulation sophistication and sterilization validation capabilities. The vendor base organizes into three tiers: integrated multinationals with captive sterilization infrastructure, specialized urology device firms with focused SKU portfolios, and regional contract manufacturers serving emerging markets. Consolidation pressure operates through hospital procurement committee vendor rationalization programs and ambulatory surgical center master service agreements. Two dominant competitive moves are portfolio diversification into bioabsorbable polymers and geographic expansion through distributor acquisition in Asia-Pacific markets.
Within the integrated multinational tier, Boston Scientific Corporation and Stryker Corporation exemplify scale-driven positioning across disposable stent and capital equipment categories. Richard Wolf GmbH occupies a specialist position in rigid endoscopic systems, anchoring its competitive presence in laparoscopic ureteral interventions. Cook Medical represents the diversified device archetype with broad SKU coverage across stent geometries and material durometers.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Olympus Corporation |
| Boston Scientific Corporation |
| Stryker Corporation |
| Richard Wolf GmbH |
| B. Braun Melsungen AG |
| Teleflex Incorporated |
| Coloplast Corporation |
| Cook Medical |
| Others |
Value Chain & Pricing Dynamics
Polymer chemist concentrations in Indiana and Massachusetts create labor-cost differentials that widen spreads between premium biofilm-resistant stents and economy-grade silicone alternatives. Procurement committees exploit this tiered supply base through vendor rationalization programs that compress middle-tier pricing.
Pricing Analysis
Per-procedure bundling now dominates hospital and ambulatory surgical center contracting, with master service agreements collapsing discrete capital and consumable purchases into single-case fees. Price differentiation hinges on FDA 510(k) clearance tier and sterilization validation depth, with academic medical centers least sensitive and rural clinics most reactive to out-of-pocket cost exposure. Cost compression in standard silicone stents is intensifying because Indiana and Massachusetts manufacturers face overlapping wage pressure and logistics congestion.
Supply Chain Analysis
Specialty polymer feedstock supply rests on German and Japanese petrochemical producers for medical-grade silicone and proprietary polyurethane formulations. Ureteral obstruction device manufacturing draws from Indiana and Massachusetts production clusters, with secondary fabrication emerging in Karnataka and Maharashtra under India's PLI scheme. Single-source vulnerability concentrates in balloon-expandable platform components, where rated burst pressure validation requires captive sterilization infrastructure. Distribution runs through integrated delivery network procurement committees and ambulatory surgical center group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ureteral obstruction market compounds steadily as aging demographics sustain procedural volume expansion across Medicare-eligible populations. Device innovation cycles and outpatient migration create predictable reinvestment opportunities.
For Market Incumbents: Anticipate bioabsorbable polymer convergence by front-loading clinical trial partnerships with academic medical centers, securing early access pathways before FDA degradation-profile requirements extend approval timelines. Defend against ambulatory surgical center vendor rationalization by anchoring master service agreements with technical support bundling, not price alone. Prioritize backward integration into specialty polymer formulation to offset petrochemical price volatility. For New Entrants and Emerging Players: Rural health clinics in Appalachia and the Mississippi Delta represent the most penetrable buyer archetype, with federally qualified health centers lacking fluoroscopy-equipped intervention capacity. Capture whitespace through mobile lithotripsy deployment partnerships and external drainage system distribution. Enter via GPO contracts managers who control procurement committee access in integrated delivery networks. For Investors and Strategic Acquirers: Integrated multinationals with captive sterilization infrastructure are the most active acquirers in this space, targeting specialized urology device firms with focused SKU portfolios and CE marking readiness. Long-term viability frames around bioabsorbable scaffold platforms that eliminate retrieval procedures and capture premium positioning. Watch FDA post-market surveillance registry mandates as the inflection signal—compliance infrastructure becomes a scarce, defensible asset.| Strategic Initiative | Industry Significance |
|---|---|
| Bioabsorbable Polymer Convergence | Magnesium alloy scaffolds with controlled-release coatings eliminate retrieval procedures and command premium hospital reimbursement. |
| Hospital System Partnership | Master service agreements with Pennsylvania and Ohio integrated delivery networks displace traditional capital equipment purchasing. |
| CE Marking Pathway | EU MDR notified body capacity constraints make early certification engagement a competitive moat for European market access. |
| Software Companion Development | Remote monitoring platforms for home care nephrostomy management expand addressable market beyond institutional settings. |
| Reimbursement Strategy | Health Technology Assessment evidence generation for German IQWiG and French HAS unlocks eligibility for novel stent geometries. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with urologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers against secondary validation from FDA 510(k) filings, CMS Medicare procedure data, hospital procurement databases, and CE marking registries. Bottom-up stent and balloon shipment analysis triangulated against top-down reimbursement code valuation to anchor volume and value estimates.
Historical procedural volumes across the analysis window anchored forward projections, with segmentation modeling across product type, end user, indication, and delivery mode dimensions. CAGRs derived from regression-adjusted trend extrapolation incorporating fluoroscopy-guided placement adoption curves, ambulatory surgical center migration rates, and bioabsorbable polymer regulatory timeline assumptions.
Underlying measurement precision varies by segment; stent volumes carry tighter precision than emerging bioabsorbable categories where commercialization timelines remain uncertain. Forecasts reflect documented assumptions about FDA pathway efficiency and Medicare reimbursement stability. Regulatory shifts, polymer formulation breakthroughs, and interventional radiology workforce shortages warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market
Urology
Continence Care Market
Urology
Urethral Stricture Market
Urology
Acute Pyelonephritis Treatment Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Transrectal Ultrasound Market
Urology
Urology Lasers Market
Urology
Self-Intermittent Catheters Market
Urology
Renal Cyst Treatment Market
Urology
India Urology Market
Urology
US Urology Devices Market
Urology
North America Bladder Disorders Market
Urology
Urology Ultrasound Market
Urology
Urinary Incontinence Therapeutics Market
Urology
Nordic Urinary Catheters Market
Urology
Global Hydronephrosis Market