
 Genitourinary Cancers Treatment Market | 2026-2036
Genitourinary Cancers Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Genitourinary Cancers Treatment Market Analytics
Aftermarket service revenue from companion diagnostics and patient monitoring is fragmenting across multiple vendor ecosystems. Bristol-Myers Squibb leverages its immuno-oncology infrastructure to sustain leadership in checkpoint inhibitor combinations for renal cell carcinoma. AstraZeneca anchors its position through targeted therapy development, while Merck & Company competes on PD-1 pathway dominance across bladder and prostate indications.
Genitourinary cancers treatment encompasses therapeutic interventions for malignancies of the urinary tract and male reproductive system, including systemic agents formulated as monoclonal antibodies, small molecule inhibitors, and cytotoxic compounds administered via intravenous infusion or oral dosing regimens. These interventions aim to interrupt tumor proliferation, metastatic spread, and hormone-driven growth pathways in affected organs. Immunotherapy commands the fastest expansion as PD-1 and PD-L1 inhibitors reshape first-line standards for bladder and renal cancers, while hormonal therapy retains entrenched utility in prostate cancer despite emerging competitive pressures from PARP inhibitors and radioligand approaches. The intravenous route still dominates administration for biologics, though subcutaneous formulations are gaining traction for patient convenience in outpatient settings.
The FDA's accelerated approval framework and Breakthrough Therapy designation compress development timelines for novel agents, while the EMA's centralized marketing authorization process governs commercial access across European Union member states. The EU AI Act introduces compliance obligations for algorithmic diagnostic tools used in treatment selection and response monitoring. Stakeholders must weigh portfolio bets between established hormonal platforms and emerging antibody-drug conjugates as clinical data reshapes standard-of-care hierarchies across major indications.
Market Dynamics
The FDA's Breakthrough Therapy designation compresses development timelines for novel antibody-drug conjugates, while academic medical centers concentrate trial enrollment for combination regimens in metastatic prostate and renal cell carcinoma.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's expedited review mechanisms compress Phase II-to-approval timelines for checkpoint inhibitor combinations, enabling earlier commercial access for PD-1/PD-L1 agents in bladder cancer.
- Academic Center Infrastructure:Oncology departments at major teaching hospitals are expanding dedicated genitourinary malignancy divisions, concentrating patient volume and trial enrollment capacity for novel agents.
- Radioligand Manufacturing Scale-Up:Specialized radioisotope production facilities in the United States and Germany are expanding capacity for prostate-specific membrane antigen-targeted therapies.
Market Restraints
- Reimbursement Compression:Medicare's prospective payment systems create pricing pressure on intravenous biologic administration in hospital outpatient departments.
- Radioisotope Supply Concentration:Molybdenum-99 production concentrates at five aging nuclear reactors globally, creating vulnerability for radioligand therapy supply chains.
- Clinical Trial Complexity:Biomarker stratification requirements fragment eligible patient populations, extending enrollment timelines for targeted therapy studies.
Strategic Opportunities
- Subcutaneous Formulation Conversion:Self-administration platforms for checkpoint inhibitors reduce infusion center burden and capture patient preference in community oncology settings.
- Companion Diagnostic Integration:FDA co-approval pathways for tissue-agnostic biomarkers create synchronized commercial opportunities for targeted agents and their diagnostic partners.
- Community Oncology Networks:Independent practice associations in the United States are consolidating purchasing for oral oncolytics, creating channel leverage for specialty pharmacy distribution.
Industry Challenges
- Interdisciplinary Care Coordination:Urologists, medical oncologists, and radiation oncologists maintain fragmented electronic health record systems, complicating longitudinal treatment sequencing.
- Biospecimen Collection Standardization:Variable pre-analytical handling across community sites degrades circulating tumor DNA quality for minimal residual disease monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genitourinary Cancers Treatment Market |
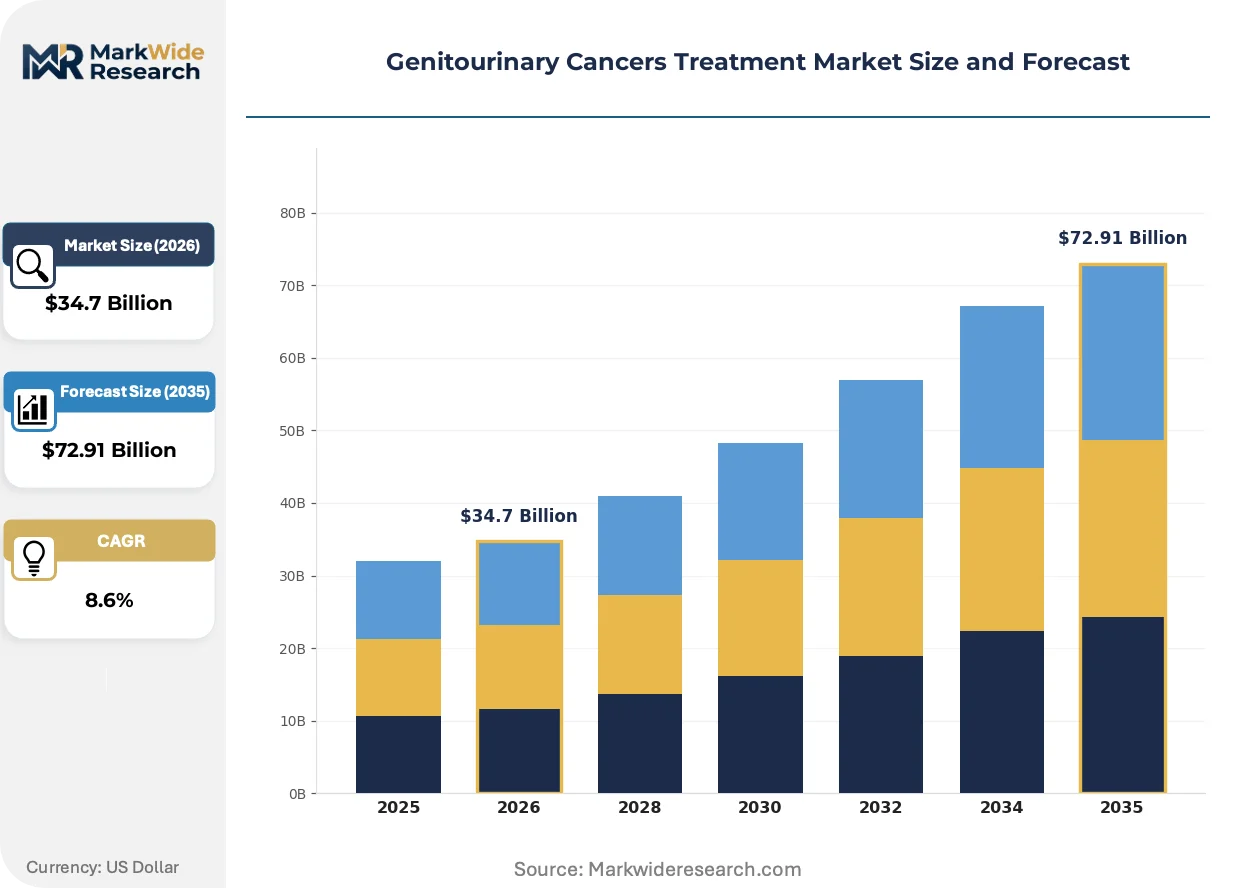
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Hormonal Therapy End User: Hospitals, Clinics, Specialty Centers, Research Institutions Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular Indication: Bladder Cancer, Prostate Cancer, Renal Cell Carcinoma, Testicular Cancer |
| Companies Covered | Roche Holding, Bristol-Myers Squibb, Novartis, Johnson & Johnson, Pfizer, Merck & Company, AbbVie, AstraZeneca, Eli Lilly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genitourinary Cancers Treatment Market Evolving Landscape
Antibody-drug conjugates are displacing cytotoxic backbones in second-line bladder cancer, while radioligand therapy infrastructure investments reshape site-of-care economics for metastatic castration-resistant prostate cancer.
PARP inhibitor combinations with androgen receptor pathway blockers are hybridizing first-line treatment paradigms for metastatic castration-sensitive prostate cancer. Academic consortiums are adopting these regimens ahead of formal guideline updates, compressing the window between data presentation and community standard-of-care shifts. The convergence is forcing reconfiguration of clinical trial control arms and creating biomarker-defined subpopulation complexity.
The EU AI Act imposes conformity assessment obligations on algorithmic tools used for treatment response prediction and radiographic progression monitoring. Device manufacturers must demonstrate clinical validation and post-market surveillance for machine learning-based decision support integrated into imaging workflows. German university hospitals are piloting compliant deployment frameworks ahead of the 2026 enforcement deadline.
Specialty pharmacy networks are consolidating oral oncolytic dispensing for prostate cancer hormonal agents, displacing traditional retail channel distribution. Three national pharmacy benefit managers now require mandatory specialty pharmacy enrollment for abiraterone and enzalutamide prescriptions. This concentration is most visible in the United States, where prior authorization automation and patient adherence monitoring create service differentiation.
Genitourinary Cancers Treatment Market Segmentation
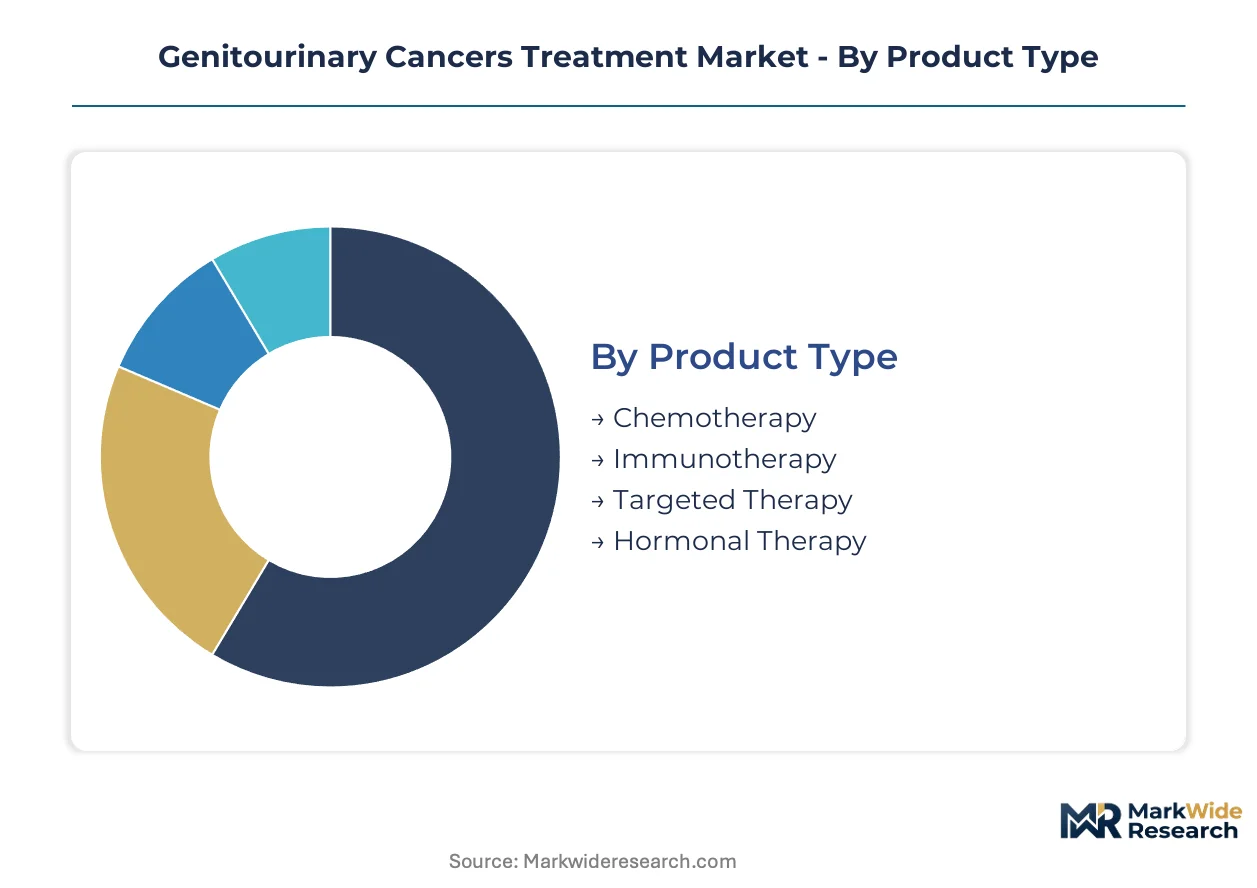
Genitourinary cancers treatment segmentation reveals how therapeutic modality, care setting, and disease biology interact to shape commercial opportunity. Each dimension carries distinct regulatory, reimbursement, and competitive dynamics that determine portfolio prioritization for developers.
Product Type:
Use-case spectrum spans curative-intent cytotoxic regimens through chronic maintenance with oral hormonal agents, creating divergent margin profiles and manufacturing requirements across the category.
- Immunotherapy:PD-1 and PD-L1 checkpoint inhibitors dominate first-line bladder and renal cell carcinoma protocols. Demand concentrates at academic medical centers in the United States where Medicare reimbursement for combination infusions sustains treatment intensity.
- Targeted Therapy:PARP inhibitors and tyrosine kinase inhibitors interrupt specific oncogenic signaling pathways. Prescription volume clusters in prostate cancer biomarker-defined populations where germline testing identifies eligible patients.
- Hormonal Therapy:Androgen receptor pathway blockers remain foundational for metastatic prostate cancer management.
- Chemotherapy:Platinum-based cytotoxic agents persist in neoadjuvant bladder cancer and testicular germ cell protocols.
The dominant share belongs to Immunotherapy, while Targeted Therapy is closing the gap fastest.
End User:
Site-of-care economics vary sharply between infusion-dependent biologics and self-administered oral agents, fragmenting purchasing authority across institutional and retail channels.
- Hospitals:Academic medical centers concentrate trial enrollment for novel antibody-drug conjugates and radioligand therapies. Outpatient departments capture Medicare prospective payments for intravenous biologic administration.
- Specialty Centers:Dedicated urology-oncology practices concentrate surgical and systemic therapy coordination for prostate and bladder malignancies. Volume growth reflects patient preference for integrated multidisciplinary care.
- Clinics:Community oncology settings handle stable patients on oral hormonal maintenance.
- Research Institutions:National Cancer Institute-designated centers generate pivotal trial data for regulatory submissions.
Hospitals command the largest patient volume, though Specialty Centers are expanding share through care consolidation.
Administration Route:
Patient convenience and site-of-care capacity constraints are shifting development investment toward formulations that reduce infusion center burden.
- Intravenous:Remains standard for checkpoint inhibitors and antibody-drug conjugates requiring controlled administration. Hospital outpatient departments in the United States capture the majority of volume under Medicare reimbursement.
- Subcutaneous:Self-injection platforms for PD-1 agents are gaining formulary acceptance. German university hospitals pilot compliant deployment frameworks ahead of EU AI Act enforcement timelines.
- Oral:Hormonal agents and targeted small molecules enable home administration.
- Intramuscular:Limited to depot hormonal formulations in prostate cancer.
Intravenous retains institutional dominance, but Subcutaneous is gaining share fastest through patient preference and capacity relief.
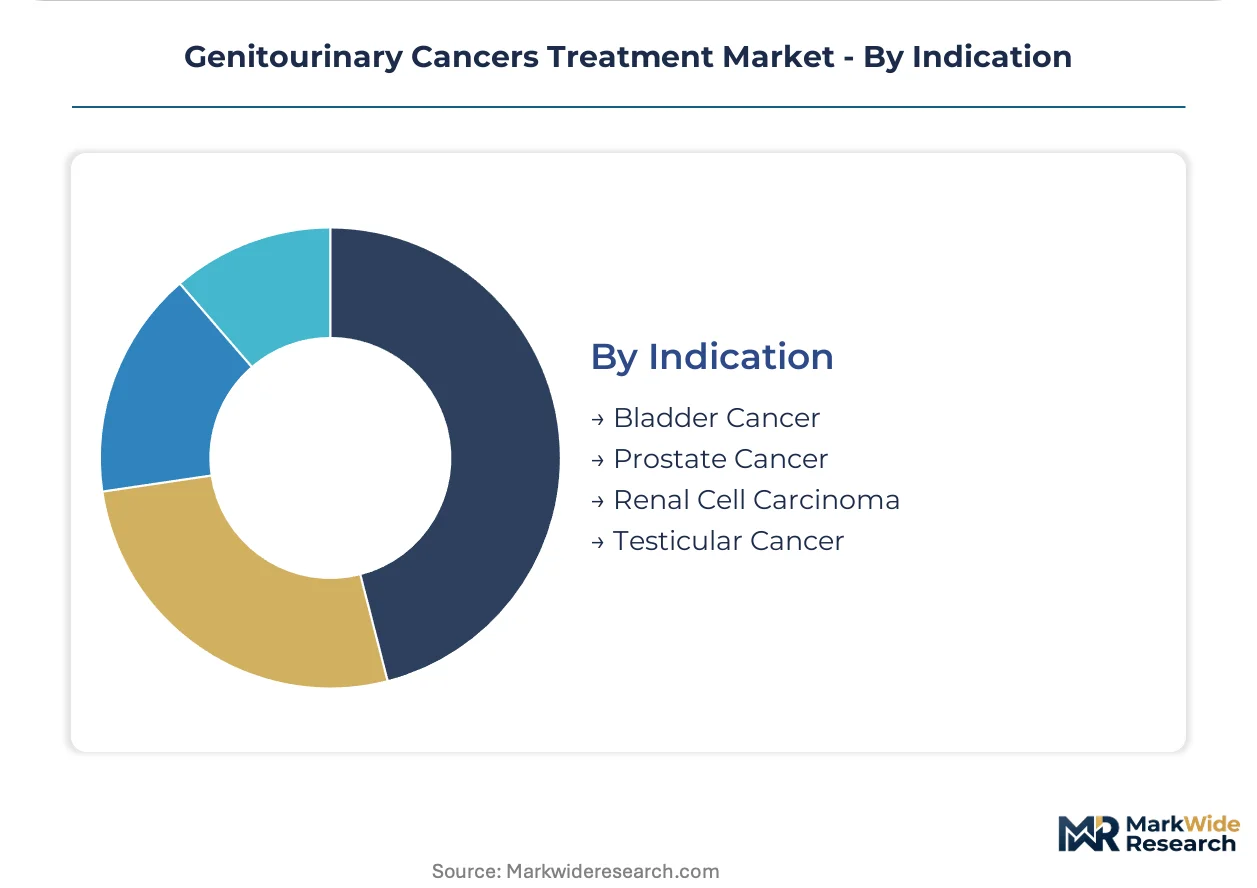
Indication:
Disease-specific biology determines addressable patient populations and the competitive intensity of treatment sequencing.
- Prostate Cancer:Hormonal therapy backbone faces disruption from PARP inhibitor combinations and radioligand approaches. The FDA's accelerated approval pathways compress development timelines for novel agents in metastatic castration-resistant settings.
- Bladder Cancer:Checkpoint inhibitors reshaped first-line standards for platinum-ineligible patients. Academic consortiums adopt antibody-drug conjugate combinations ahead of formal guideline updates.
- Renal Cell Carcinoma:Dual immunotherapy and TKI-IO combinations dominate frontline practice.
- Testicular Cancer:Platinum-based chemotherapy retains curative-intent dominance with limited novel agent penetration.
Prostate Cancer generates the highest absolute revenue, while Bladder Cancer is expanding most quickly through immunotherapy adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized radioisotope production facilities cluster in the United States and Germany, creating supply-chain dependency for radioligand therapies while FDA and EMA accelerated approval pathways compress development timelines across both markets.
United States
Medicare reimbursement policies sustain treatment intensity for prostate and bladder malignancies in hospital outpatient departments. The FDA's Breakthrough Therapy designation enables earlier commercial access for PD-1/PD-L1 agents. Academic medical centers in Boston and Houston concentrate trial enrollment for novel antibody-drug conjugates.
Germany
University hospitals pilot EU AI Act-compliant deployment frameworks for algorithmic diagnostic tools ahead of 2026 enforcement. The EMA's centralized marketing authorization governs commercial access across EU member states. Frankfurt and Munich anchor radioligand manufacturing scale-up for prostate-specific membrane antigen-targeted therapies.
United Kingdom
NHS specialized commissioning frameworks concentrate genitourinary cancer care in designated tertiary centers. MHRA recognition of FDA approvals accelerates market entry for novel immunotherapy combinations. The Royal Marsden and Christie Hospital networks generate pivotal trial data for regulatory submissions.
Japan
PMDA's Sakigake designation system compresses review timelines for innovative oncology agents. Aging demographics expand the addressable patient population for metastatic prostate cancer therapies. Tokyo and Osaka medical centers adopt subcutaneous checkpoint inhibitor formulations for outpatient capacity relief.
China
NMPA priority review pathways accelerate approval for locally manufactured PD-1 inhibitors. Domestic biotech firms develop biosimilar and novel antibody-drug conjugates for bladder and renal indications. Shanghai and Beijing academic hospitals expand dedicated urology-oncology divisions for combination regimen trials.
Genitourinary Cancers Treatment Market Competitive Landscape
Large-cap pharmaceutical conglomerates and mid-size oncology specialists split the market between broad immunology infrastructure and focused genitourinary development programs. The competitive terrain rewards checkpoint inhibitor dominance, radioligand manufacturing scale, and PARP inhibitor portfolio depth. Three archetypes prevail: integrated immuno-oncology platforms, targeted therapy specialists, and radiopharmaceutical developers. Consolidation activity concentrates on antibody-drug conjugate assets and companion diagnostic partnerships.
Within the integrated platform tier, Bristol-Myers Squibb and Merck & Company occupy positions defined by PD-1 pathway breadth across bladder and prostate indications. AstraZeneca anchors the targeted therapy vector through PARP inhibitor and androgen receptor pathway development. These three firms exemplify how regulatory acceleration and academic center relationships determine competitive standing in this indication cluster.
| Leading Market Players |
|---|
| Roche Holding |
| Bristol-Myers Squibb |
| Novartis |
| Johnson & Johnson |
| Pfizer |
| Merck & Company |
| AbbVie |
| AstraZeneca |
| Eli Lilly |
| Others |
Value Network & Pricing Analysis
Radioisotope production undercapacity across aging European reactors and constrained North American cyclotron networks drives both supply rationing and premium pricing for radioligand therapies. Manufacturers respond by consolidating long-term offtake agreements while hospital outpatient departments absorb Medicare reimbursement compression through volume concentration.
Pricing Analysis
Aftermarket service revenue from companion diagnostics and patient monitoring contracts drives lifetime value capture for developers. Three-tier pricing structure across premium biologics, standard small molecules, and economy cytotoxic generics stratifies the market by administration complexity and biomarker dependency. Cost compression in intravenous infusion services stems from Medicare prospective payment system adjustments. Community oncology settings exhibit highest price sensitivity due to formulary budget constraints, while academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Upstream feedstock concentration for molybdenum-99 and lutetium-177 radioisotopes centers on five aging nuclear reactors in the Netherlands, Belgium, and South Africa. Active pharmaceutical ingredient manufacturing for PARP inhibitors and androgen receptor blockers draws from facilities in India, Ireland, and Singapore. Single-source vulnerability for radioisotope supply creates acute disruption risk for radioligand therapy programs. Distribution runs through specialty pharmacy networks for oral hormonal agents and hospital-based nuclear medicine departments for radiopharmaceuticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards concentrated expertise in radiopharmaceutical manufacturing logistics and biomarker-driven trial design, creating asymmetric returns for firms possessing both capabilities. Developers lacking either competency face exclusion from the fastest-expanding therapeutic modalities.
For Market Incumbents: Pre-empt biosimilar entry in hormonal therapy by securing exclusive distribution through specialty pharmacy networks and investing in subcutaneous formulation conversions. Backward integration into radioisotope production or captive supply agreements with cyclotron operators defends margin position against supply concentration risk. FDA Breakthrough Therapy designation pursuit accelerates competitive moat construction in antibody-drug conjugates. For New Entrants and Emerging Players: Pursue white-space opportunities in subcutaneous checkpoint inhibitor formulations for community oncology capacity relief and algorithmic treatment response monitoring tools compliant with EU AI Act frameworks. Oral oncolytic dispensing through consolidated independent practice associations represents the most penetrable channel. Go-to-market execution should emphasize prior authorization automation partnerships with national pharmacy benefit managers. For Investors and Strategic Acquirers: Long-term, this sits as a manufacturing-capability play because radioligand therapy scale-up requires irreplaceable radioisotope infrastructure and regulatory navigation expertise. Acquisition targets should display vertical integration into cyclotron operations or antibody-drug conjugate payload-linker technology. The signal to watch is radioligand therapy site-of-care economics data from German university hospital pilots.| Strategic Initiative | Industry Significance |
|---|---|
| Radioligand Manufacturing Scale-Up | Specialized cyclotron capacity in Germany and the United States secures supply chain control for prostate-specific membrane antigen therapies. |
| Companion Diagnostic Co-Development | FDA synchronized approval pathways with tissue-agnostic biomarkers accelerate commercial access for PARP inhibitor combinations. |
| Subcutaneous Formulation Conversion | Self-administration platforms reduce infusion center burden and capture formulary preference in community oncology settings. |
| EU AI Act Compliance Investment | Conformity assessment for algorithmic progression monitoring tools enables deployment in German academic medical centers. |
| Specialty Pharmacy Network Consolidation | Mandatory enrollment requirements from national pharmacy benefit managers concentrate channel leverage for oral hormonal agents. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underlying this analysis. Primary interviews with payer access specialists and biomedical engineers were cross-validated against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored volume and value estimates.
Demand-supply-balance framing across therapeutic modality, administration route, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from treatment line penetration curves and biomarker-defined eligible population expansion. Dosage form preferences and site-of-care shift dynamics informed segmentation-specific growth trajectories throughout the forecast period.
Sensitivities concentrate around radioligand therapy supply disruptions, Medicare reimbursement policy adjustments, and EU AI Act enforcement timelines. Forecasts reflect assumptions regarding clinical trial success rates and regulatory approval velocities. Quarterly review of radioisotope production capacity utilization, companion diagnostic co-approval momentum, and subcutaneous formulation formulary adoption is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Global Bladder Cancer Market
Urology
Urinary Catheters Market
Urology
Ureter Cancer Treatment Market
Urology
Urinary Tract Infection Testing Market
Urology
Urology Lasers Market
Urology
Voiding Cystourethrogram Market
Urology
Obstructive Uropathy Treatment Market
Urology
Asia-Pacific Bladder Disorders Market
Urology
Nocturia Market
Urology
Chronic Pyelonephritis Treatment Market
Urology
Self-Intermittent Catheters Market
Urology
Urinary Retention Therapeutics Market
Urology
Urology Devices Market
Urology
Disposable Ureteroscope Market
Urology
Urology Forceps Market
Urology
LAMEA Transrectal Ultrasound Market