
 Cystoscope Market | 2026-2036
Cystoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Cystoscope Market Analysis
Market Context with Strategic Players
The EU Medical Device Regulation is broadening compliance requirements for reusable endoscopic instruments across European urology practices. KARL STORZ leverages its integrated manufacturing campus in Germany to sustain full control over optical component production. Olympus Corporation anchors its competitive stance through proprietary image-processing platforms that dominate high-definition visualization in flexible systems. Ambu A/S differentiates by specializing in single-use cystoscopes that eliminate cross-contamination risks and reprocessing liability.
Technical Definition and Structural Segments
A cystoscope is a slender tubular instrument, typically 2.7 mm to 4 mm in outer diameter for pediatric variants and 16 Fr to 22 Fr for adult rigid models, designed for transurethral visualization of the bladder and urethral mucosa using fiberoptic or digital camera technology to diagnose hematuria, strictures, and bladder lesions. Flexible cystoscopes lead procedural volume in outpatient settings due to patient tolerance and maneuverability around the membranous urethra, while digital cystoscopes represent the fastest-expanding technology segment as CMOS sensor costs decline and hospitals replace aging fiberoptic inventories. Rigid cystoscopes occupy the mature operative segment where resectoscope compatibility and irrigation flow rates sustain margin pools in transurethral resection procedures.
Regulatory Frame and Forward Outlook
FDA 510(k) clearance pathways and the EU MDR's renewed clinical evidence requirements shape product development timelines and market access costs for cystoscope manufacturers entering either jurisdiction. The EPA regulates sterilization effluent discharge from hospital reprocessing departments, influencing whether facilities adopt single-use alternatives or invest in closed-loop washer-disinfector systems. Stakeholders must monitor how reimbursement policy for office-based cystoscopy versus facility-based procedures shifts capital allocation between flexible digital platforms and disposable instruments.
Market Dynamics
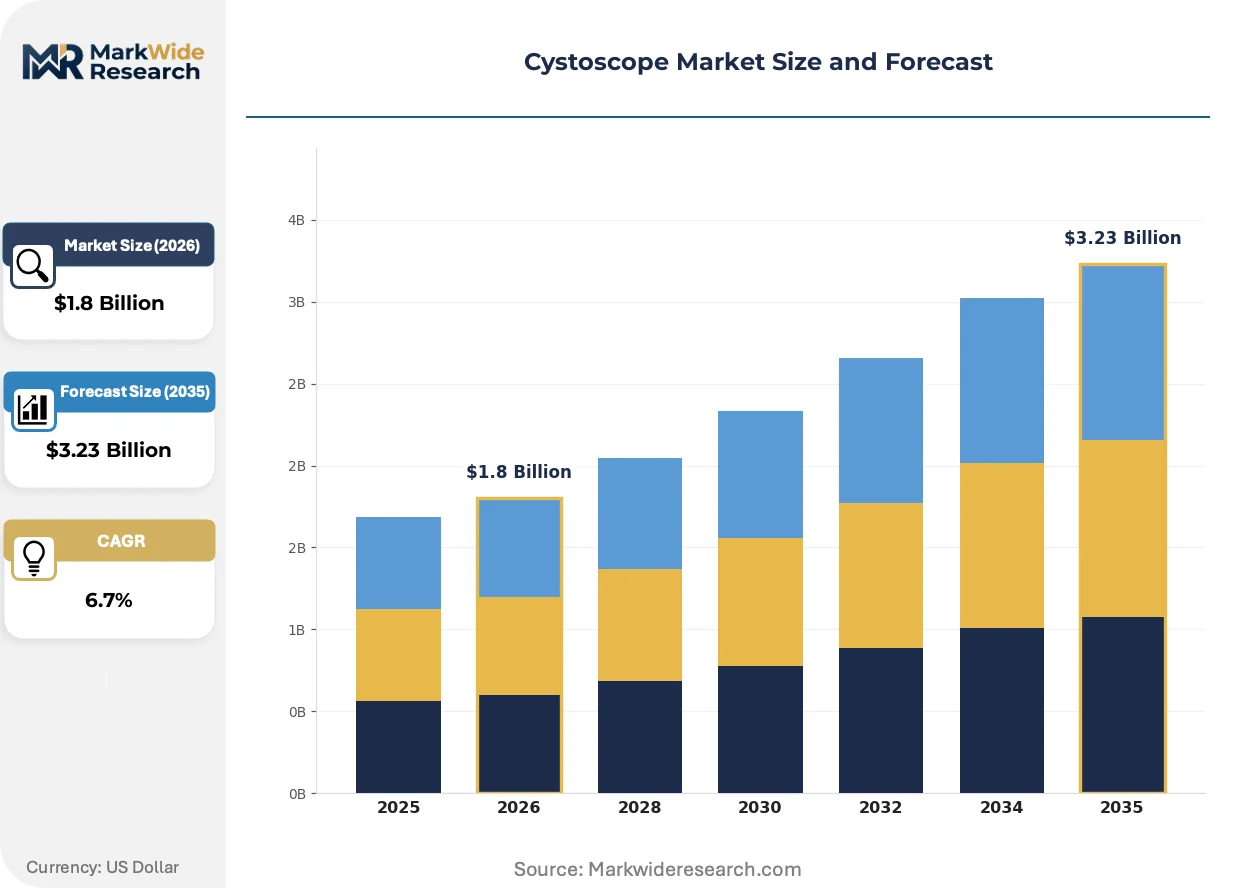
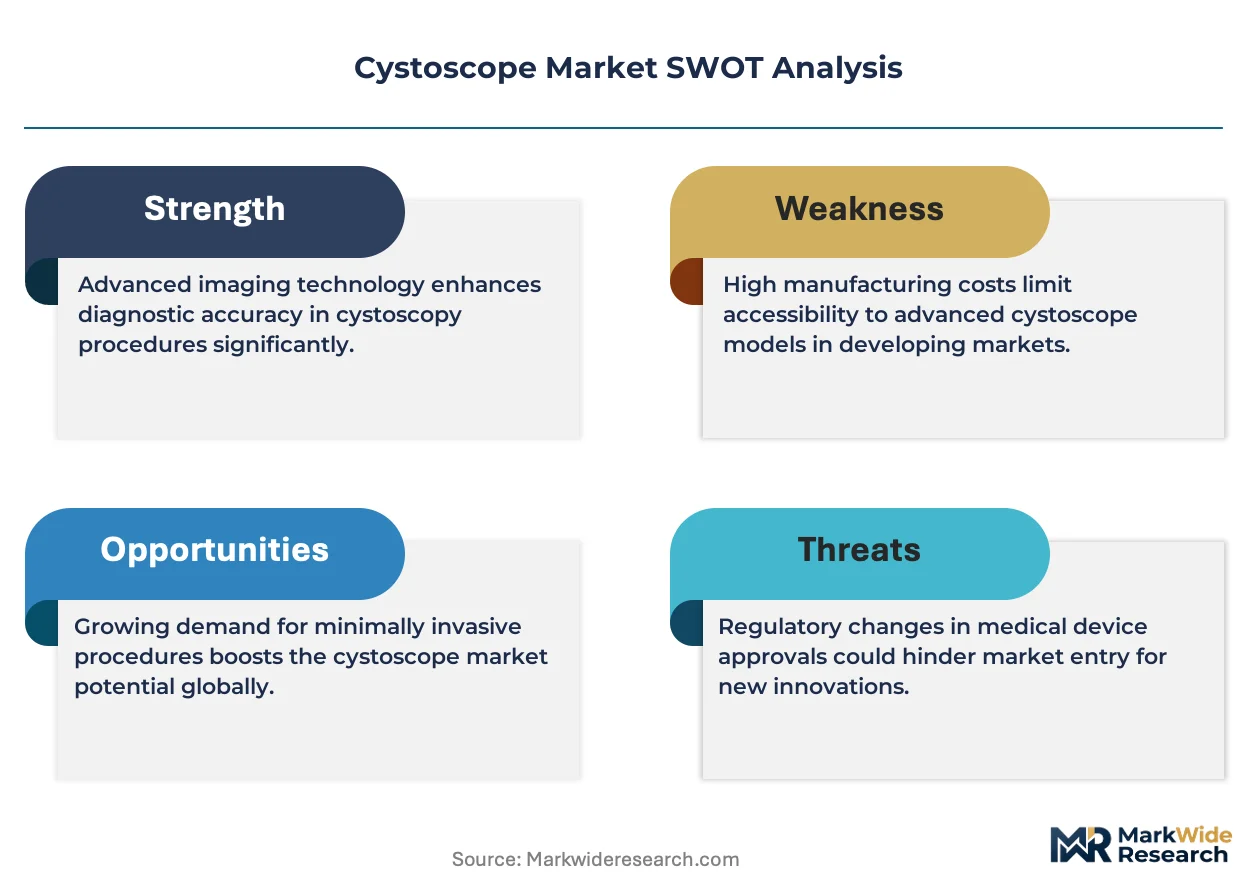
The cystoscope market pivots on a fundamental equipment transition: digital CMOS sensor technology is displacing fiberoptic bundles in flexible systems, forcing manufacturers to rebuild supply chains around semiconductor sourcing while hospitals face parallel pressure from EU MDR sterilization mandates to reconsider single-use alternatives.
Growth Catalysts
- EU MDR sterilization mandates:The regulation's tightened reprocessing standards push hospitals toward single-use cystoscopes that eliminate cross-contamination liability and documentation burdens.
- Outpatient procedural migration:Ambulatory surgery centers in Germany and the United States expand flexible cystoscopy volumes as reimbursement shifts favor lower-acuity settings.
- Aging demographics in Japan:The country's super-aged population sustains elevated hematuria workup rates, maintaining procedural demand for diagnostic cystoscopy.
Market Restraints
- CMOS sensor supply concentration:Image sensor fabrication concentrates among Taiwan and South Korean foundries, exposing manufacturers to geopolitical supply interruptions.
- Capital intensity of digital platforms:Hospital procurement committees face extended payback periods when replacing functional fiberoptic fleets with CMOS-based systems.
- Reprocessing infrastructure lock-in:Facilities with recent investments in closed-loop washer-disinfector systems resist single-use migration despite regulatory pressure.
Strategic Opportunities
- Office-based diagnostic expansion:Urology practices in the United States deploy compact flexible systems to capture facility fee revenue previously directed to hospital outpatient departments.
- AI-enhanced image analysis:Integration of computer-aided detection algorithms with digital cystoscope outputs creates premium positioning for bladder lesion identification.
- Japan's procedural volume growth:The national health insurance system's coverage stability supports predictable replacement cycles for aging endoscope inventories.
Industry Challenges
- Biocompatibility certification timelines:Novel polymer formulations for single-use sheaths face extended ISO 10993 testing protocols before EU MDR conformity.
- Service technician scarcity:Digital platform maintenance demands electro-optical repair skills that outpace training pipeline output in European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cystoscope Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Cystoscopes, Flexible Cystoscopes, Digital Cystoscopes, Pediatric Cystoscopes End User: Hospitals, Clinics, Ambulatory Surgery Centers, Diagnostic Laboratories Technology: Image Acquisition, Light Source, Visualization System, Biopsy Tools Application: Urology, Oncology, Gynecology, Diagnostics |
| Companies Covered | KARL STORZ, BD, Olympus Corporation, HOYA Corporation, Richard Wolf Medical Instruments, Boston Scientific Corporation, Stryker, NeoScope Inc., Ambu A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cystoscope Market Emerging Trajectories
Digital imaging architecture is restructuring competitive advantage around semiconductor partnerships rather than optical engineering heritage, while regulatory pressure on reprocessing costs accelerates business model experimentation across disposable and reusable formats.
CMOS sensor miniaturization is decentralizing high-definition visualization from centralized hospital endoscopy suites into ambulatory urology practices. Smaller practices in Germany and the United States now acquire compact digital flexible systems that previously required capital budgets reserved for academic medical centers. This technology is decentralizing diagnostic capacity and compressing the traditional hierarchy between tertiary and community-based urology services.
The EU MDR's renewed clinical evidence requirements for reusable endoscopic instruments are extending product development timelines and inflating regulatory submission costs. Manufacturers must now generate post-market surveillance data that fiberoptic-era products never required, favoring incumbents with established notified body relationships. Flexible cystoscope portfolios face the steepest compliance burden, as their complex channel geometries complicate sterilization validation protocols.
Hospital purchasing consortia are consolidating procurement authority for endoscopic equipment across multi-hospital systems. Independent urology practices in the United States increasingly lease rather than own flexible cystoscope inventories, transferring obsolescence risk to distributors. Germany's hospital sector exhibits the most advanced concentration, with regional purchasing cooperatives negotiating system-wide digital platform conversions that marginalize smaller manufacturers lacking service network scale.
Cystoscope Market Segmentation
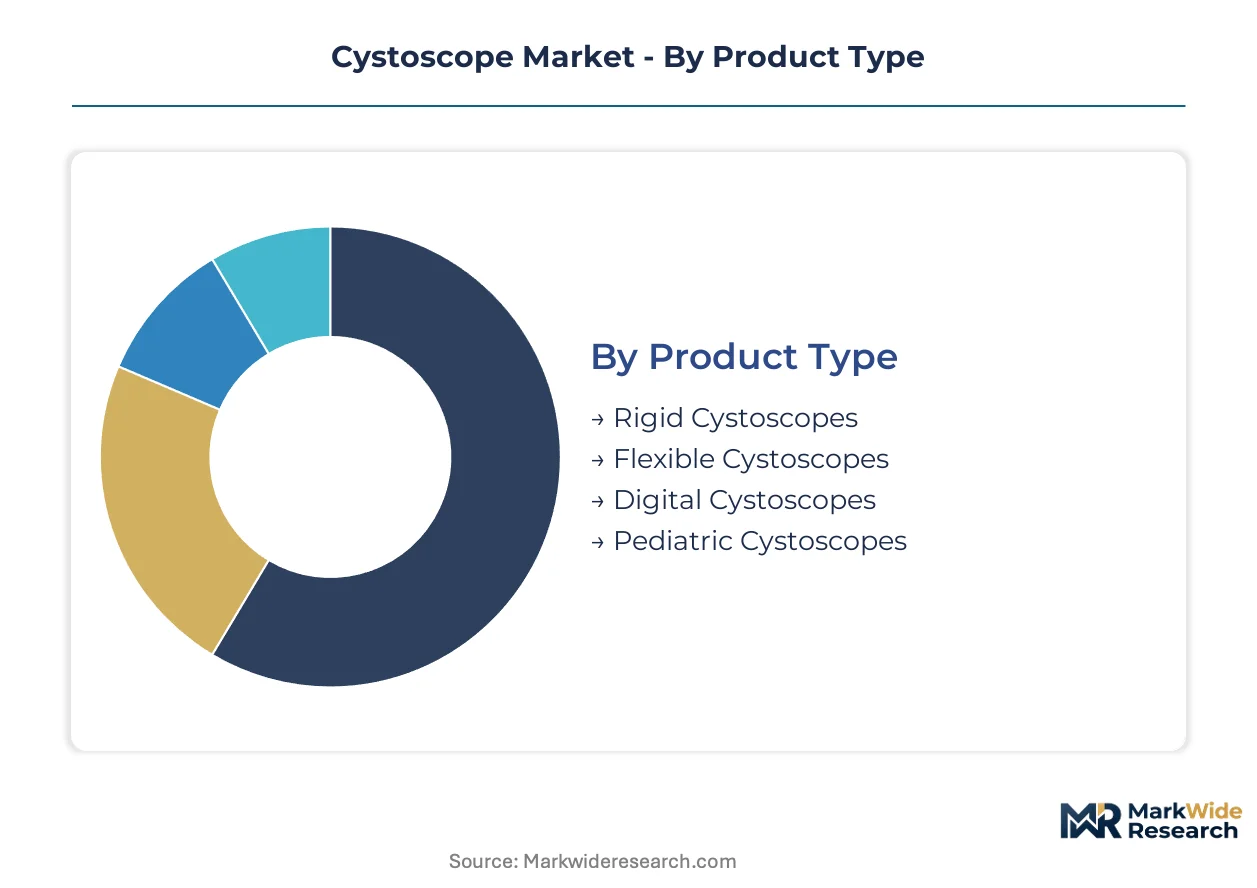
Cystoscope procurement decisions split between capital-intensive reusable platforms and disposable alternatives, with technology choices cascading through sterilization infrastructure, maintenance staffing, and reimbursement capture. Understanding how segments interlock reveals where margin pools concentrate and which transitions reshape competitive advantage.
Product Type:
Flexible and digital cystoscopes embed into hospital outpatient workflows as integrated visualization systems, while rigid and pediatric variants often function as standalone instruments in operative suites.
- Flexible Cystoscopes:Fiberoptic or CMOS-based instruments with steerable distal tips navigate the membranous urethra with minimal patient discomfort. Demand concentrates in German and United States ambulatory settings where outpatient reimbursement favors rapid turnover procedures.
- Digital Cystoscopes:Solid-state CMOS sensors replace fiberoptic bundles, enabling direct digital image capture without ocular adapters. Japanese hospitals drive replacement cycles as aging fiberoptic inventories face EU MDR revalidation burdens.
- Rigid Cystoscopes:Stainless steel sheaths with rod-lens optical systems maintain dominance in transurethral resection procedures requiring high irrigation flow rates.
- Pediatric Cystoscopes:2.7 mm to 4 mm outer diameter variants address congenital urological anomalies in specialized children's hospitals.
Flexible cystoscopes lead volumes today; digital cystoscopes are gaining share fastest.
End User:
Capital allocation patterns diverge sharply: hospitals absorb full platform costs while clinics and ambulatory centers prioritize lease arrangements and per-procedure disposable economics.
- Hospitals:Academic medical centers in Germany and Japan maintain centralized endoscopy suites with dedicated reprocessing departments and factory-trained technicians. These institutions face the steepest EU MDR compliance costs for reusable instrument validation.
- Ambulatory Surgery Centers:United States freestanding facilities exploit site-of-service differential reimbursement by performing diagnostic cystoscopy outside hospital outpatient departments. Single-use instruments eliminate reprocessing infrastructure investments.
- Clinics:Community urology practices deploy compact flexible systems for office-based hematuria workups.
- Diagnostic Laboratories:Pathology-focused settings utilize cystoscopes primarily for biopsy procurement rather than therapeutic intervention.
Hospitals dominate installed base; ambulatory surgery centers are expanding most quickly.
Technology:
Component modularity determines whether manufacturers capture full system margins or cede value to subsystem suppliers.
- Image Acquisition:CMOS sensor modules and fiberoptic bundles constitute the core value layer where semiconductor partnerships displace traditional optical engineering capabilities.
- Visualization System:Integrated display processors and image enhancement algorithms differentiate premium platforms from commodity instruments.
- Light Source:LED and xenon illumination systems require separate regulatory clearance pathways in FDA and EU MDR frameworks.
- Biopsy Tools:Working channel instruments including graspers, forceps, and cytology brushes generate recurring consumable revenue streams.
Image acquisition commands the largest technology margin; visualization systems are climbing fastest as software-defined features proliferate.
Application:
Procedural reimbursement codes and complication risk profiles shape which cystoscope configurations penetrate each clinical domain.
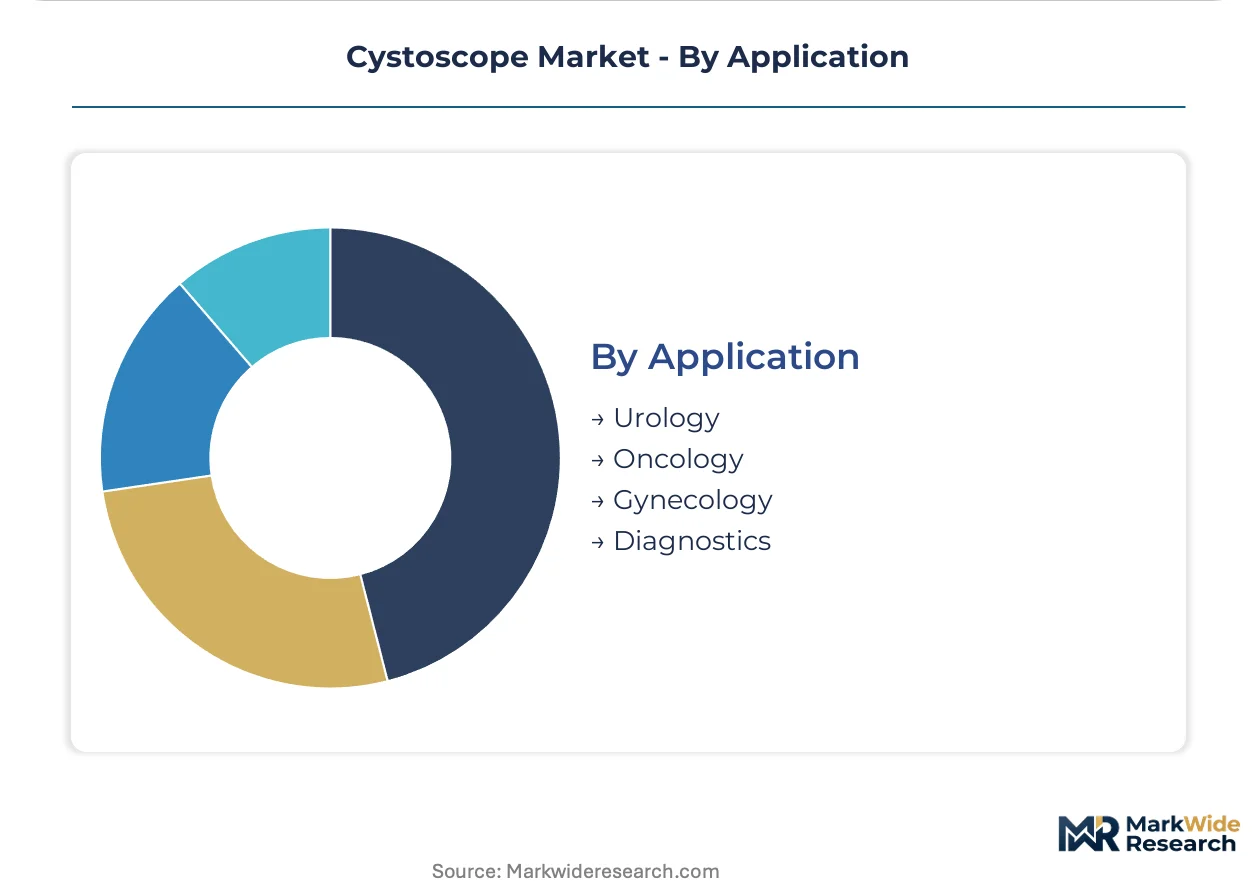
- Urology:Benign prostatic hyperplasia evaluation, urethral stricture assessment, and bladder tumor surveillance constitute the procedural core where flexible digital platforms achieve highest utilization rates.
- Oncology:Hematuria workups and bladder cancer surveillance demand superior image resolution for lesion characterization, driving premium CMOS adoption.
- Gynecology:Urethral and bladder neck evaluation during pelvic floor procedures employs modified cystoscope configurations.
- Diagnostics:Unexplained urinary symptoms and recurrent infections generate screening volumes in primary care referral pathways.
Urology anchors procedural volumes; oncology applications are expanding fastest as cancer surveillance protocols intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized urology workforces concentrate in Germany, the United States, and Japan, anchoring procedural volumes and sustaining replacement cycles for digital cystoscope platforms. These talent clusters drive regional demand patterns while regulatory frameworks reshape procurement decisions.
United States
Ambulatory surgery centers in Texas and Florida exploit site-of-service reimbursement differentials to expand outpatient cystoscopy volumes. FDA 510(k) clearance pathways shape product development timelines for manufacturers entering the market. Boston and the Research Triangle host clusters of digital imaging startups partnering with semiconductor suppliers.
Germany
Regional purchasing cooperatives in Bavaria and North Rhine-Westphalia negotiate system-wide digital platform conversions for hospital networks. The EU MDR's sterilization mandates compel facilities to reconsider single-use alternatives despite recent washer-disinfector investments. Tuttlingen remains the densest global concentration of endoscope manufacturing capability.
Japan
Super-aged demographics in Kansai and Kanto regions sustain elevated hematuria workup rates for diagnostic surveillance. METI industrial policy supports domestic CMOS sensor development to reduce import dependency. Nagoya hosts specialized repair technician training programs addressing service capacity constraints.
United Kingdom
NHS England's procurement frameworks centralize flexible cystoscope acquisition across hospital trusts. MHRA post-Brexit regulatory pathways diverge from EU MDR timelines, creating parallel submission requirements. The Oxford-Cambridge corridor attracts AI-enhanced imaging ventures targeting bladder lesion detection.
South Korea
MFDS fast-track approval programs accelerate market entry for digital platforms with proven FDA or PMDA clearances. Seoul National University Hospital anchors tertiary referral volumes driving premium equipment adoption. Busan medical device clusters specialize in CMOS module integration for Asian market variants.
Cystoscope Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the cystoscope market, creating a tiered structure where integrated optical manufacturers face modular semiconductor entrants. The vendor base concentrates among diversified medtech conglomerates and specialized endoscopy houses. Three archetypes dominate: heritage optical engineering firms with captive manufacturing, disposable instrument specialists eliminating reprocessing liability, and diversified health technology platforms leveraging imaging software ecosystems. M&A activity targets digital imaging capabilities while strategic partnerships with Taiwan and South Korean foundries secure CMOS sensor supply.
Within the heritage manufacturing tier, KARL STORZ and Olympus Corporation exemplify integrated production models with German and Japanese origins respectively. Ambu A/S occupies a distinct position representing single-use specialization. These three anchors illustrate how competitive positioning splits between reprocessing-dependent reusable platforms and contamination-risk-eliminating disposable alternatives.
| Leading Market Players |
|---|
| KARL STORZ |
| BD |
| Olympus Corporation |
| HOYA Corporation |
| Richard Wolf Medical Instruments |
| Boston Scientific Corporation |
| Stryker |
| NeoScope Inc. |
| Ambu A/S |
| Others |
Supply Flow & Price Mechanics
Specialized endoscope repair technician pools in Nagoya and Tuttlingen create labor-cost differentials that widen pricing spreads between premium factory-serviced platforms and third-party-maintained alternatives across European and Asian hospital procurement tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates cystoscope procurement, with FDA clearance tier and CMOS sensor resolution grade serving as primary price differentiation drivers. Pricing pressure stems from hospital purchasing consortia consolidating multi-hospital system contracts and demanding volume discounts. Ambulatory surgery centers exhibit highest price sensitivity due to per-procedure margin constraints, while academic medical centers prioritize image quality and service response over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States operate hub-and-spoke patterns to serve hospital networks with rapid replacement unit availability. CMOS sensor fabrication concentrates in Taiwan and South Korea, while optical component machining and final assembly anchor in Germany and Japan. Supply chain risk centers on single-source vulnerability for specialized semiconductor foundry capacity. Distribution runs through manufacturer-direct field service organizations and specialized medical device distributors with factory-trained technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR compliance costs in Germany diverge sharply from MFDS fast-track pathways in South Korea, creating cost-advantaged entry points for manufacturers willing to navigate parallel regulatory submissions.
For Market Incumbents: Deepen captive CMOS sensor supply arrangements with Taiwan and South Korean foundries to insulate against geopoliticized supply interruptions threatening flexible digital platform production. Fortify factory-trained technician networks in Nagoya and Tuttlingen to defend service-contract revenue against third-party repair entrants exploiting EU MDR documentation burdens. For New Entrants and Emerging Players: Direct-to-urology-practice digital channels offer the most penetrable route for compact flexible systems targeting United States office-based diagnostic expansion. Target ambulatory surgery centers in Texas and Florida with single-use instrument leasing models that eliminate capital expenditure barriers and capture site-of-service reimbursement differentials. For Investors and Strategic Acquirers: Diversified health technology platforms with imaging software ecosystems are the most active acquirers in this space, seeking digital imaging capabilities to complement endoscopic hardware portfolios. Acquisition targets should display semiconductor partnership depth and EU MDR notified body relationships. The signal to watch is hospital purchasing consortia consolidation velocity as an indicator of pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Pathway | Post-market surveillance data requirements favor incumbents with established notified body relationships in Germany. |
| CMOS Foundry Partnership | Taiwan and South Korean semiconductor supply agreements secure sensor fabrication capacity for digital platform transitions. |
| Hospital System Partnership | Regional purchasing cooperative agreements in Bavaria and North Rhine-Westphalia lock in multi-year digital conversion contracts. |
| Software Companion Development | AI-enhanced bladder lesion detection algorithms integrated with digital cystoscope outputs command premium positioning. |
| Reimbursement Strategy | Site-of-service differential capture in United States ambulatory settings shifts procurement toward single-use economics. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with urology department heads, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR notified body databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up procedure volume estimates and top-down equipment replacement cycle analysis were triangulated for consistency.
Historical reference periods anchored the forecast window to observed replacement cycles and regulatory implementation timelines across the projection horizon. Segmentation dimensions modeled include product type, end-user setting, technology layer, and application area, with geographic regulatory clusters treated as distinct adoption environments. CAGRs were derived from fitted growth curves applied to procedural volume trajectories and equipment penetration rates, incorporating CMOS cost decline curves and EU MDR compliance cost inflation as industry-specific inputs.
Regulatory enforcement intensity, semiconductor supply disruption events, and reimbursement policy shifts are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about procedural migration patterns and technology substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Global Hydronephrosis Market
Urology
Global Castrate Resistant Prostate Cancer Market
Urology
Asia-Pacific Bladder Disorders Market
Urology
Europe Urology Devices Market
Urology
Global Nephrology and Urology Devices Market
Urology
Chronic Pyelonephritis Treatment Market
Urology
Global Lithotripsy Market
Urology
Renal Cyst Treatment Market
Urology
Complicated Urinary Tract Infections Treatment Market
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market
Urology
North America Transrectal Ultrasound Market
Urology
Hematuria Treatment Market
Urology
Male Urinary Incontinence Market
Urology
Continence Care Market
Urology
Urinary Retention Therapeutics Market
Urology
Self-Intermittent Catheters Market