
 Sugar-Free Confectionery Market | 2026-2036
Sugar-Free Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar-Free Confectionery Market Intelligence
The e-commerce distribution channel is tilting the competitive landscape, providing direct-to-consumer access for niche brands and challenging established retail models. The Hershey Company leverages its brand strength to maintain shelf space in traditional supermarkets. In contrast, Lily's Sweets LLC specializes in stevia-sweetened products, differentiating itself within health stores and online segments. Mondelez International competes across multiple channels with a broad portfolio of sugar-free options.
Sugar-free confectionery refers to sweets formulated without sucrose, instead utilizing sugar alcohols like erythritol or high-intensity sweeteners such as stevia. These products are designed to provide a sweet taste with fewer calories and a lower glycemic impact for consumers. Chocolate and chewing gum represent mature product types with consistent demand. The market's growth, however, is being led by the Gummy Candy category, which is seeing rapid innovation in textures and flavors using novel ingredient types like monk fruit.
Product formulation and labeling are governed by agencies like the US FDA and the European Food Safety Authority (EFSA), which set standards for the use and declaration of sugar substitutes. In India, the FSSAI oversees similar regulations, impacting market access and consumer trust. Stakeholders must now decide whether to invest in proprietary sweetener blends or rely on third-party ingredient suppliers to navigate this complex regulatory environment.
Market Dynamics
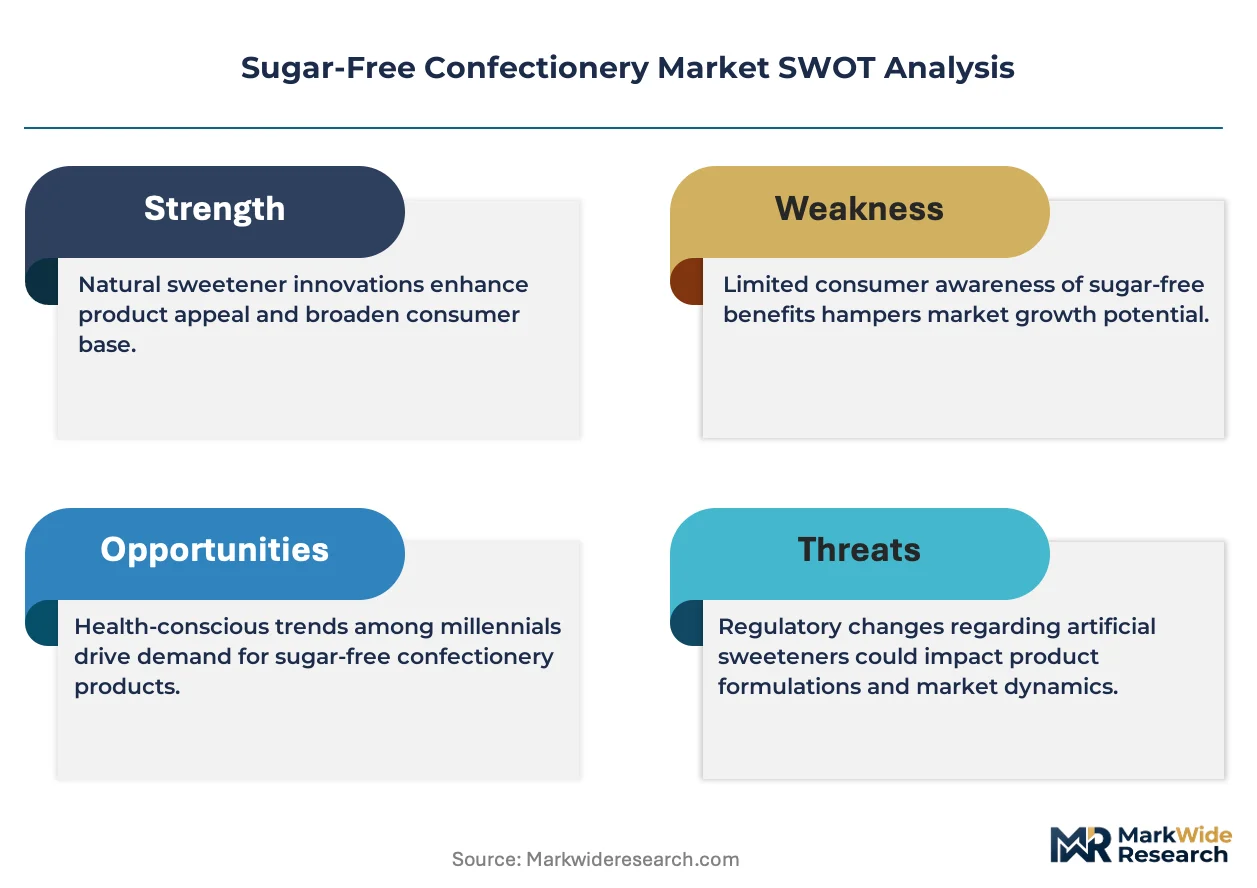
The central dynamic shaping the sugar-free confectionery market is the convergence of consumer-led wellness demand with government-led public health policy. Regulatory pressure, such as sugar taxes, directly incentivizes the product innovation that health-conscious consumers are already seeking.
Growth Catalysts
- Government Taxation Policies:Sugar taxes implemented in countries including the United Kingdom and Mexico create a direct financial incentive for manufacturers to reformulate products, boosting the relative attractiveness of sugar-free alternatives.
- Ingredient Innovation:The commercialization and improved formulation of natural, high-intensity sweeteners like stevia and monk fruit are expanding the range of possible textures and flavors, especially within the gummy candy segment.
- Concentrated Consumer Demand:A strong consumer preference for healthier options, combined with a highly developed retail infrastructure in Germany, creates a significant and stable source of demand for sugar-free products.
Market Restraints
- Cost Disparity:The unit cost for sugar alcohols like erythritol and xylitol remains substantially higher than that of sucrose, creating margin pressure and limiting adoption in more price-sensitive consumer segments.
- Physiological Effects:The potential for gastrointestinal side effects from the consumption of certain polyols acts as a deterrent for a subset of consumers and complicates product formulation and labeling requirements.
- Sourcing Volatility:Supply chains for key natural ingredients, such as high-purity stevia extracts, are geographically concentrated, exposing manufacturers to potential price fluctuations and sourcing vulnerabilities.
Strategic Opportunities
- Functional Product Development:An opportunity exists to create confectionery that incorporates functional ingredients such as vitamins, minerals, or botanical extracts, appealing to consumers seeking multi-purpose health and wellness products. *
- Emerging Market Penetration:As health awareness and disposable incomes rise in India, regulations from the FSSAI create a structured environment for introducing sugar-free products to a large, underpenetrated consumer base.
- Direct-to-Consumer Channels:Establishing dedicated e-commerce platforms enables brands to bypass traditional retail gatekeepers, build direct relationships, and serve niche consumer preferences for specific sweetener types or product formats.
Industry Challenges
- Navigating Regulatory Fragmentation:Managing and complying with the diverse and evolving labeling standards for sugar substitutes set by authorities like the US FDA and the European Food Safety Authority (EFSA) is a significant operational burden.
- Formulation Expertise Gap:Replicating the sensory and functional properties of sugar requires specialized food science talent and R&D capabilities, which can be a barrier for smaller manufacturers or new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar-Free Confectionery Market |
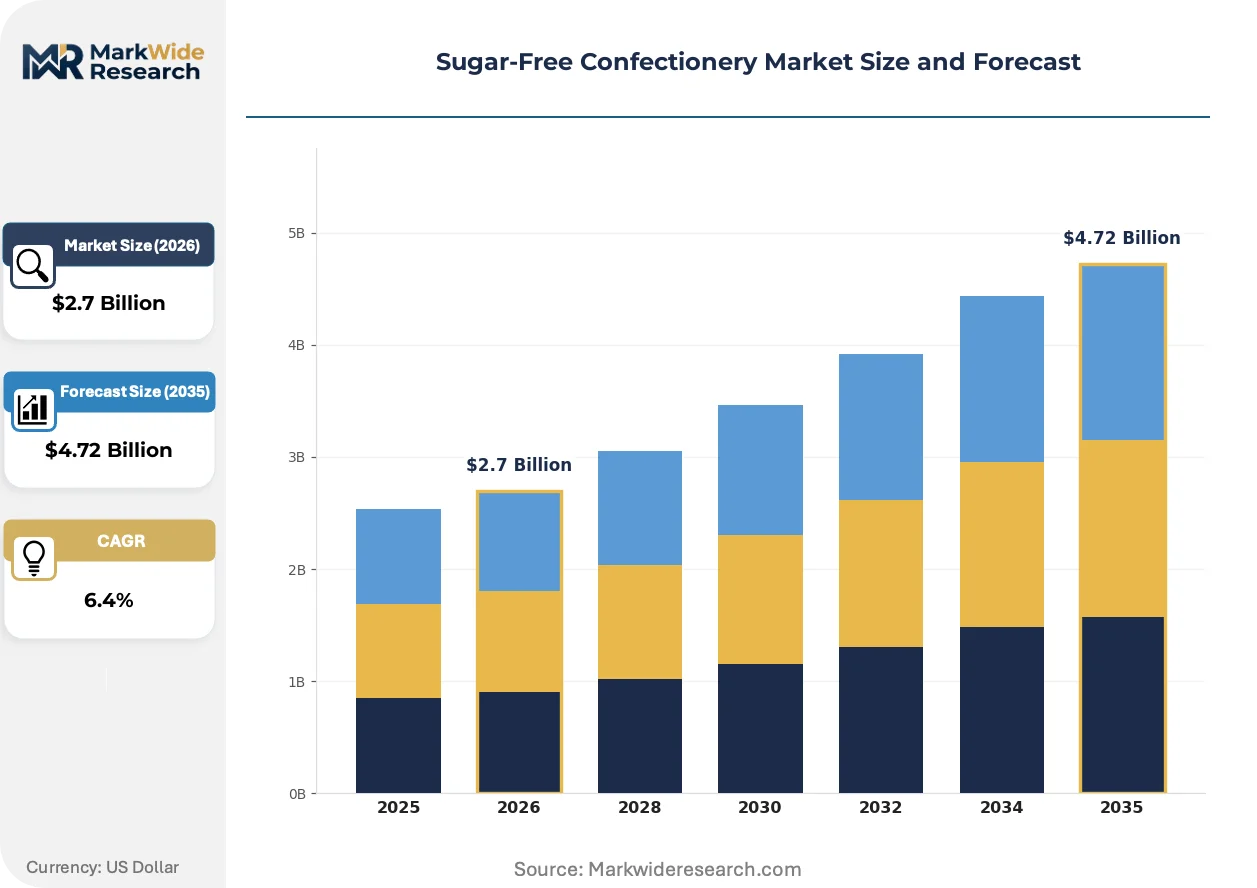
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Candy, Chewing Gum, Chocolate, Gummy Candy End User: Adults, Children, Health-Conscious Consumers, Diabetics Distribution Channel: Supermarkets, Health Stores, E-commerce, Specialty Shops Ingredient Type: Stevia, Erythritol, Xylitol, Monk Fruit |
| Companies Covered | Mars Incorporated, Nestlé S.A., The Hershey Company, Mondelez International, Ferrero S.p.A., Lindt & Sprüngli, Unilever PLC, Haribo GmbH & Co. KG, Lily's Sweets LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar-Free Confectionery Market Strategic Shifts & Innovations
Ingredient science and digital retail are jointly redefining market boundaries. Advances in sweetener systems are improving product quality, while e-commerce channels are changing how consumers discover and purchase these specialized goods, challenging established distribution and marketing models.
Advanced Sweetener Systems
Advanced sweetener blending combines multiple agents like stevia and erythritol to achieve a clean, sugar-like taste profile. Confectionery manufacturers are rapidly adopting these systems to improve product parity. This technology is collapsing the perceived taste and texture gap between sugar-free and full-sugar products for mainstream consumers.
Front-of-Pack Labeling Mandates
Mandatory front-of-pack nutrition labeling systems in several European countries and Mexico are creating direct incentives for reformulation. These policies visually penalize high-sugar content, impacting consumer choice at the point of sale. Mass-market chocolate and candy categories are most affected, accelerating the launch of sugar-free variants.
Planned-Purchase Behavior
Consumer purchasing is shifting from impulse buys at checkout counters to planned purchases via online and specialty health channels. This behavior disrupts the traditional retail model dominated by large supermarket chains. The shift is most pronounced in the US, where consumers actively seek specific sweetener types like stevia online.
Sugar-Free Confectionery Market Segmentation
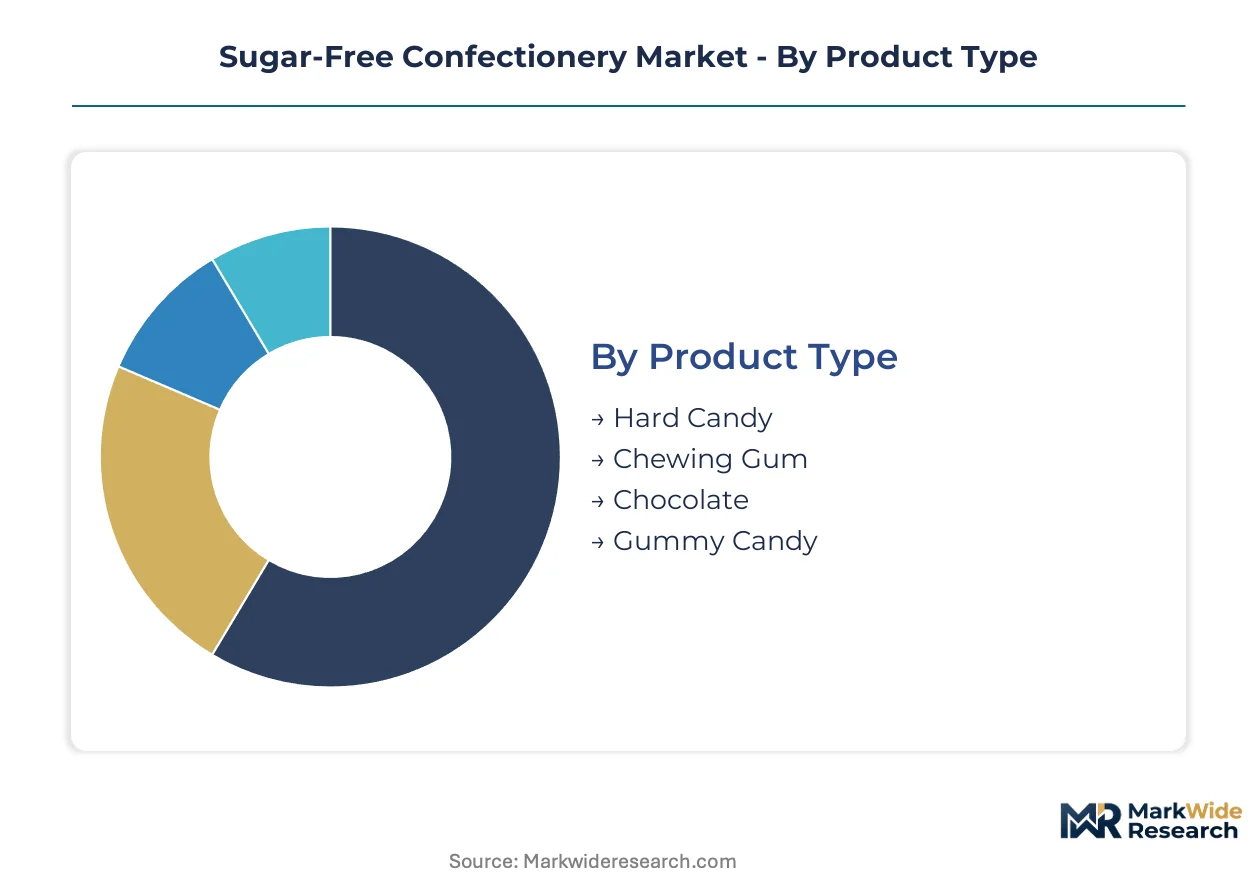
Segmentation provides a granular view of the sugar-free confectionery market, highlighting the diverse product offerings, consumer groups, distribution strategies, and ingredient innovations that collectively define its landscape. Understanding these segments is crucial for identifying areas of concentrated demand and emerging growth opportunities for stakeholders.
Product Type:
The product type segmentation reveals a mix of mature categories alongside rapidly innovating segments reshaping consumer expectations.
- Chocolate:Formulated without sucrose, often using sugar alcohols or high-intensity sweeteners to mimic traditional chocolate taste and texture. Consistent demand in Germany, driven by established consumer preference for healthier alternatives in a mature retail sector.
- Gummy Candy:Characterized by chewable, gelatin-based formulations that leverage novel sweeteners like monk fruit for diverse textures and flavors. Rapid innovation in this category, particularly in the US, is attracting health-conscious consumers seeking new sensory experiences.
- Chewing Gum:This segment relies heavily on polyols like xylitol for dental health benefits, maintaining a stable consumer base.
- Hard Candy:Traditional hard candy formats are being reformulated with non-nutritive sweeteners to reduce caloric content.
Chocolate retains volume leadership; Gummy Candy holds the steepest expansion curve.
End User:
End-user segmentation highlights distinct consumer motivations and dietary needs driving specific product development.
- Health-Conscious Consumers:Individuals actively seeking products with reduced sugar content, often prioritizing natural sweeteners and functional benefits. This segment drives innovation in e-commerce channels, particularly for brands specializing in stevia-sweetened options.
- Diabetics:Consumers requiring strict carbohydrate management, relying on sugar-free options to manage blood glucose levels without sacrificing taste. Demand for these products is stable in markets with high diabetes prevalence, supported by clear labeling from agencies like the US FDA.
- Adults:This broad demographic seeks sugar-free alternatives for general wellness and weight management, often preferring established brands.
- Children:Products for children focus on appealing flavors and textures while addressing parental concerns about sugar intake.
Primary consumption is driven by Health-Conscious Consumers, with Diabetics showing strong latent demand.
Distribution Channel:
Distribution channel dynamics illustrate how product accessibility and consumer purchasing behaviors are evolving across the market.
- E-commerce:Online platforms providing direct-to-consumer access, enabling niche brands to reach specific consumer segments with specialized product offerings. This channel is accelerating growth in the US, where consumers actively seek specific sweetener types like stevia online.
- Supermarkets:Traditional large-format retail stores offering broad product assortments and leveraging established brand recognition for wider consumer reach. The Hershey Company maintains significant shelf space in these channels, catering to mainstream consumer purchasing habits.
- Health Stores:These specialized outlets cater to consumers prioritizing organic, natural, or dietary-specific products, often featuring niche brands.
- Specialty Shops:Boutique confectionery stores offer premium or artisanal sugar-free products, appealing to consumers seeking unique experiences.
Supermarkets dominate volume, while E-commerce is gaining share rapidly.
Ingredient Type:
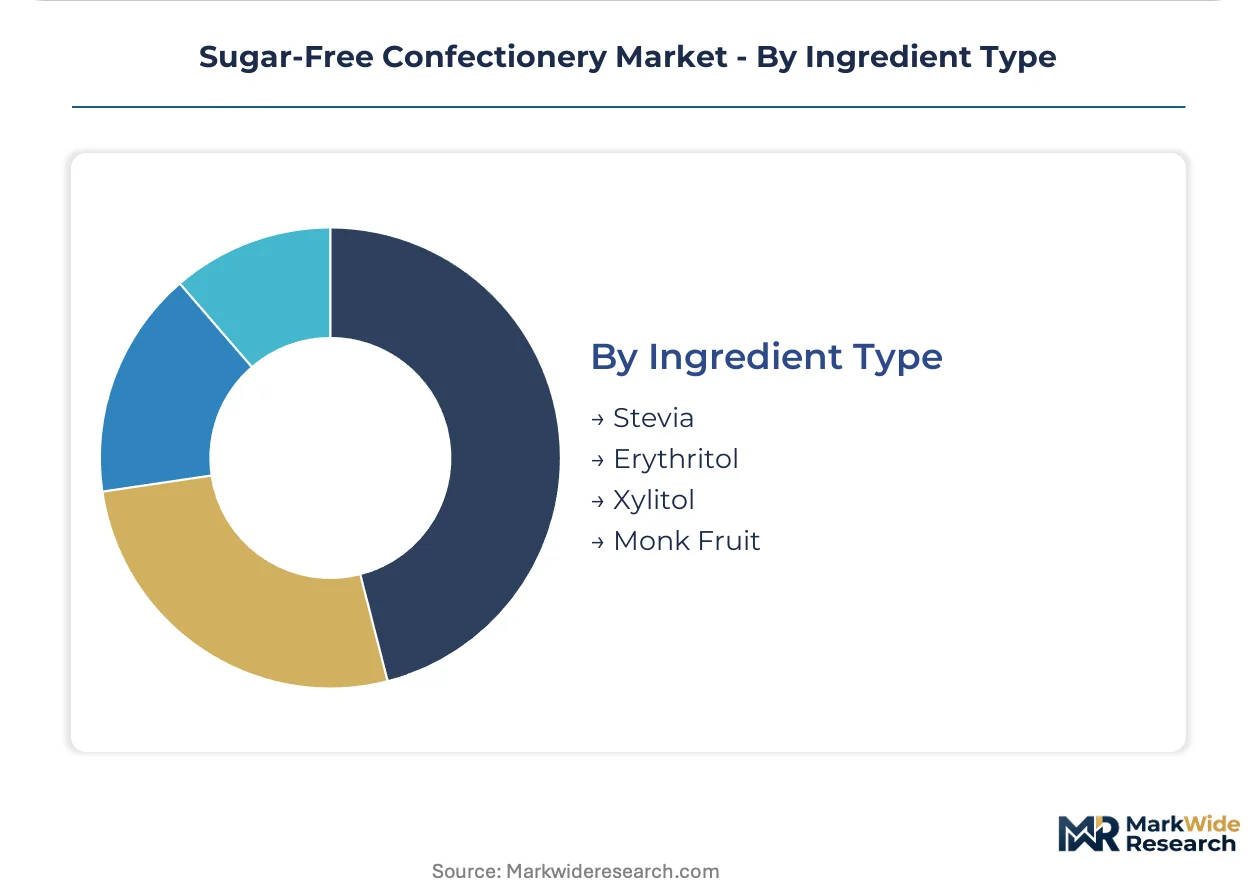
Ingredient type segmentation underscores the critical role of formulation science in achieving desired taste profiles and caloric reductions.
- Stevia:A natural, high-intensity sweetener derived from the stevia plant, providing significant sweetness with minimal caloric impact. Innovations in stevia blends are improving taste profiles, driving adoption in new product formulations, particularly in gummy candies.
- Erythritol:A sugar alcohol naturally found in some fruits, known for its clean taste profile and minimal gastrointestinal side effects compared to other polyols. Its application is widespread in chocolate and hard candies, driven by consumer preference for sugar-like texture and bulk.
- Monk Fruit:This natural, high-intensity sweetener is gaining traction for its clean taste and suitability in various confectionery applications.
- Xylitol:A sugar alcohol primarily used in chewing gum and dental products for its anti-cavity properties and cooling sensation.
Erythritol is foundational, with Stevia seeing significant research investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global sugar-free confectionery market leverages established retail and rapidly expanding digital infrastructure. Germany's mature retail sector provides a stable base for product distribution. E-commerce platforms in the United States accelerate niche brand access, driven by consumer demand for specialized options.
Germany
Germany's market shows strong consumer preference for healthier options, supported by a highly developed retail infrastructure. The European Food Safety Authority (EFSA) sets clear standards for sugar substitutes, ensuring consumer trust. Major urban centers like Berlin and Hamburg drive innovation in health-focused food trends and product availability.
United Kingdom
The United Kingdom's market is significantly influenced by health-conscious consumers and government policy. Sugar taxes implemented by the government create a direct financial incentive for manufacturers to reformulate products. London's diverse consumer base and strong e-commerce infrastructure support specialized sugar-free offerings and rapid product launches.
United States
Consumers in the United States actively seek specific sweetener types online, accelerating growth in e-commerce channels. The US FDA provides comprehensive guidelines governing product formulation and labeling for sugar substitutes. California's health-and-wellness culture fosters innovation in functional confectionery and specialized ingredient applications.
Mexico
Government public health policies in Mexico directly incentivize the reformulation of confectionery products. Sugar taxes and mandatory front-of-pack nutrition labeling create direct incentives for manufacturers. Mexico City's large urban population and extensive retail density drive demand for accessible sugar-free alternatives across product categories.
India
Emerging market penetration in India is driven by rising health awareness and increasing disposable incomes among consumers. The FSSAI oversees regulations for sugar substitutes, creating a structured environment for market entry. Major metropolitan areas like Mumbai and Bangalore show growing interest in wellness products and new sugar-free confectionery options.
Sugar-Free Confectionery Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, focusing on ingredient innovation. The sugar-free confectionery market exhibits a tiered structure, with established global players and agile niche brands. Archetypes include confectionery giants leveraging brand strength and specialized health-focused companies differentiating with novel sweeteners. Dominant competitive moves involve broad portfolio diversification into sugar-free variants and strategic partnerships for advanced sweetener technology. Geographic expansion into emerging markets also represents a key strategy.
Within the established brand tier, The Hershey Company represents traditional confectionery players leveraging strong brand recognition to maintain shelf space in supermarkets. Mondelez International exemplifies global enterprises with broad sugar-free portfolios, competing across multiple distribution channels. Lily's Sweets LLC occupies a position among specialized health-focused brands, differentiating itself with stevia-sweetened products within health stores and online segments. These companies collectively anchor diverse market approaches, from mass-market distribution to targeted niche offerings, reflecting the market's evolving competitive dynamics.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestlé S.A. |
| The Hershey Company |
| Mondelez International |
| Ferrero S.p.A. |
| Lindt & Sprüngli |
| Unilever PLC |
| Haribo GmbH & Co. KG |
| Lily's Sweets LLC |
| Others |
Cost & Logistics Intelligence
The concentrated stevia production in China directly influences global pricing power for high-intensity sweeteners, affecting downstream confectionery manufacturers and their product costs.
Pricing Analysis
Volume-based tiered pricing is common in the sugar-free confectionery ingredient market, differentiating costs for bulk purchasers versus smaller specialized brands. Price differentiation stems from the quality grade of sweetener extracts and the volume scale of procurement. Pricing pressure stems from the unit cost disparity between sugar alcohols like erythritol and traditional sucrose. Health-conscious consumers show lower price sensitivity for specialized products, while price-sensitive consumer segments hesitate due to higher unit costs.
Supply Chain Analysis
Sourcing volatility for high-purity stevia extracts in geographically concentrated regions like China and Paraguay creates significant supply chain risk for confectionery manufacturers. Raw material dependencies include erythritol, xylitol, and monk fruit, often sourced from specific agricultural zones. Commodity price fluctuations for these natural ingredients present a structural risk. Distribution runs through a mix of specialized ingredient distributors and direct procurement by large manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sugar-free confectionery market is at a platform-economics inflection, driven by the expanding ecosystem of natural sweetener innovations and digital retail channels.
For Market Incumbents:
Entrench market share by aggressively expanding sugar-free product lines across all core categories, directly countering the threat from agile niche brands. Invest heavily in proprietary sweetener blend development to reduce reliance on third-party ingredient suppliers. Leverage existing brand strength to maintain supermarket shelf space, ensuring broad consumer access. Focus R&D on replicating sugar's sensory properties to improve product parity.
For New Entrants and Emerging Players:
Build out specialized product portfolios targeting specific dietary needs or sweetener preferences, capitalizing on the underpenetrated demand for functional confectionery. The gummy candy segment offers the most penetrable market for novel ingredient applications. A direct-to-consumer go-to-market angle via e-commerce platforms enables direct relationships with health-conscious consumers. Differentiate through unique flavor profiles or specific health benefits.
For Investors and Strategic Acquirers:
Long-term, this sits as a consumer health and wellness play because fundamental shifts in dietary preferences and public health policies are irreversible. Target acquisition archetypes include specialized ingredient suppliers with proprietary technology or niche brands demonstrating strong online growth. A key signal to watch is the rate of new sugar tax implementations, which directly incentivizes market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation Investment | Accelerates market share gains in regions with front-of-pack labeling mandates. |
| Direct-to-Consumer Channel Expansion | Bypasses traditional retail gatekeepers and builds brand loyalty with health-conscious consumers. |
| Proprietary Sweetener Blend Development | Reduces reliance on third-party ingredient suppliers and enhances product differentiation. |
| Functional Confectionery Integration | Appeals to consumers seeking multi-purpose health and wellness products beyond taste. |
| Emerging Market Entry in India | Captures demand from a large, underpenetrated consumer base with rising health awareness. |
Research Approach
Desk research of regulatory filings, industry whitepapers, and scientific publications preceded structured interviews with food scientists, brand managers, and retail buyers. This approach combined primary insights from ingredient suppliers and regulatory experts with secondary data from market intelligence databases and company annual reports. Both bottom-up and top-down triangulation ensured comprehensive market sizing and validation.
Assumptions regarding economic stability and regulatory continuity were held fixed, while consumer preference shifts and ingredient innovation rates were varied across the analysis window. The analytical framework modeled market segmentation across product type, end user, distribution channel, ingredient type, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected market dynamics, incorporating R&D investment in sweeteners as a key input.
Stress conditions across raw material price volatility and new regulatory mandates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about market drivers and restraints, acknowledging that unforeseen supply chain disruptions could revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Sugar-Free Sweets Market
Confectionery
Global Non-Cocoa Confectionery Market
Confectionery
Chocolate Inclusions and Decorations Market
Confectionery
White Chocolate Market
Confectionery
Confectionery Fats Market
Confectionery
Fruit Jellies Market
Confectionery
United States Caramel Chocolate Market
Confectionery
Low Calorie Keto Desserts Market
Confectionery
Sugar Free Lollipops Market
Confectionery
Licorice Candy Market
Confectionery
Low-Calorie Candy Market
Confectionery
Vegan Candies Market
Confectionery
Bangladesh Candy Market
Confectionery
Confectionery Fillings Market
Confectionery
United Arab Emirates Chocolate Market
Confectionery
North America Confectionery Market