
 Sugar Alcohol Market | 2026-2036
Sugar Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Alcohol Market Intelligence
New production capacity coming online in China is recalibrating the supply landscape for bulk sugar alcohols like sorbitol. Global agribusiness giants such as Cargill Incorporated leverage extensive feedstock sourcing to maintain cost leadership. Roquette Frères differentiates through its deep expertise in polyol chemistry and application development for food and pharmaceutical clients. Archer Daniels Midland Company competes via its integrated processing model, converting agricultural commodities into functional ingredients.
Sugar alcohols, or polyols, are carbohydrates derived from the hydrogenation of sugars. They possess a lower caloric value and glycemic index compared to sucrose, making them suitable for diabetic-friendly and low-calorie food products. Sorbitol and maltitol represent mature, high-volume segments driven by confectionery and food applications. In contrast, erythritol is a higher-growth product, valued for its zero-calorie profile and superior digestive tolerance in dietary supplements and beverages.
Market access and labeling are governed by food additive regulations from bodies like the US FDA and the European Food Safety Authority (EFSA). In Asia, compliance with GB standards in China and guidelines from Japan's PMDA is essential for food and pharmaceutical applications. Producers must now navigate evolving consumer perceptions of 'natural' versus 'artificial' sweeteners to secure long-term brand loyalty.
Market Dynamics
The primary structural force shaping the sugar alcohol market is the escalating demand for sugar-reduced formulations in the food and beverage industry. This is amplified by stringent nutritional labeling mandates from regulators like the US FDA and Europe's EFSA, which compel product reformulation and create a direct pull for polyol-based ingredients.
Growth Catalysts
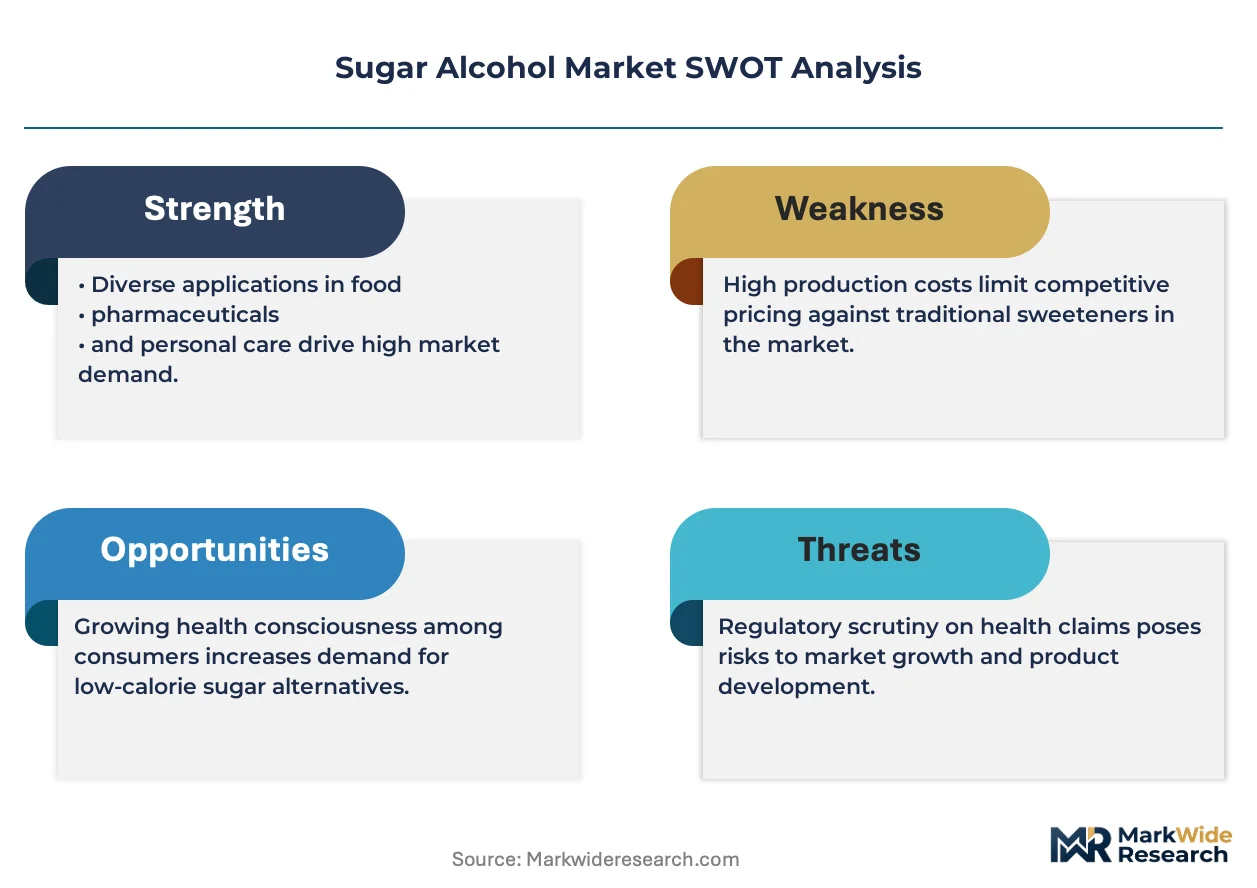
- Nutritional Labeling Mandates:Stricter rules from the US FDA and EFSA on sugar disclosure compel food producers to adopt sugar alcohols in product reformulations.
- Functional Food Demand:Consumer need for low-glycemic products expands the use of polyols like sorbitol and maltitol in the food and beverage industry.
- Erythritol's Properties:Its zero-calorie profile and better digestive tolerance are driving erythritol's adoption in premium beverages and dietary supplements.
Market Restraints
- Feedstock Cost Volatility:Production costs link directly to fluctuating prices of agricultural commodities like corn, creating margin instability for processors.
- Digestive Tolerance Limits:Potential gastrointestinal discomfort from polyols like sorbitol restricts their inclusion levels and can require warning labels under food safety regulations.
- "Natural" Sweetener Competition:Sugar alcohols face a substitution threat from ingredients like stevia that align with consumer demand for "clean label" products.
Strategic Opportunities
- Southeast Asian Expansion:Urbanizing economies in Southeast Asia present new growth as consumer demand for processed, low-sugar foods increases.
- Pharmaceutical Excipients:Using high-purity polyols as excipients in oral drug formulations is a stable, high-margin segment governed by pharmacopeia standards.
- Synergistic Blends:Combining polyols with high-intensity sweeteners creates customized systems that improve taste and functionality for specific food applications.
Industry Challenges
- Fragmented Regulatory Compliance:Producers face high compliance costs navigating disparate food additive regulations across jurisdictions, including standards from the US FDA, EFSA, and China's GB framework.
- Supply Chain Integration:Managing the integration of new large-scale production capacity from China without disrupting global pricing and logistics presents a significant operational hurdle for all market participants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Alcohol Market |
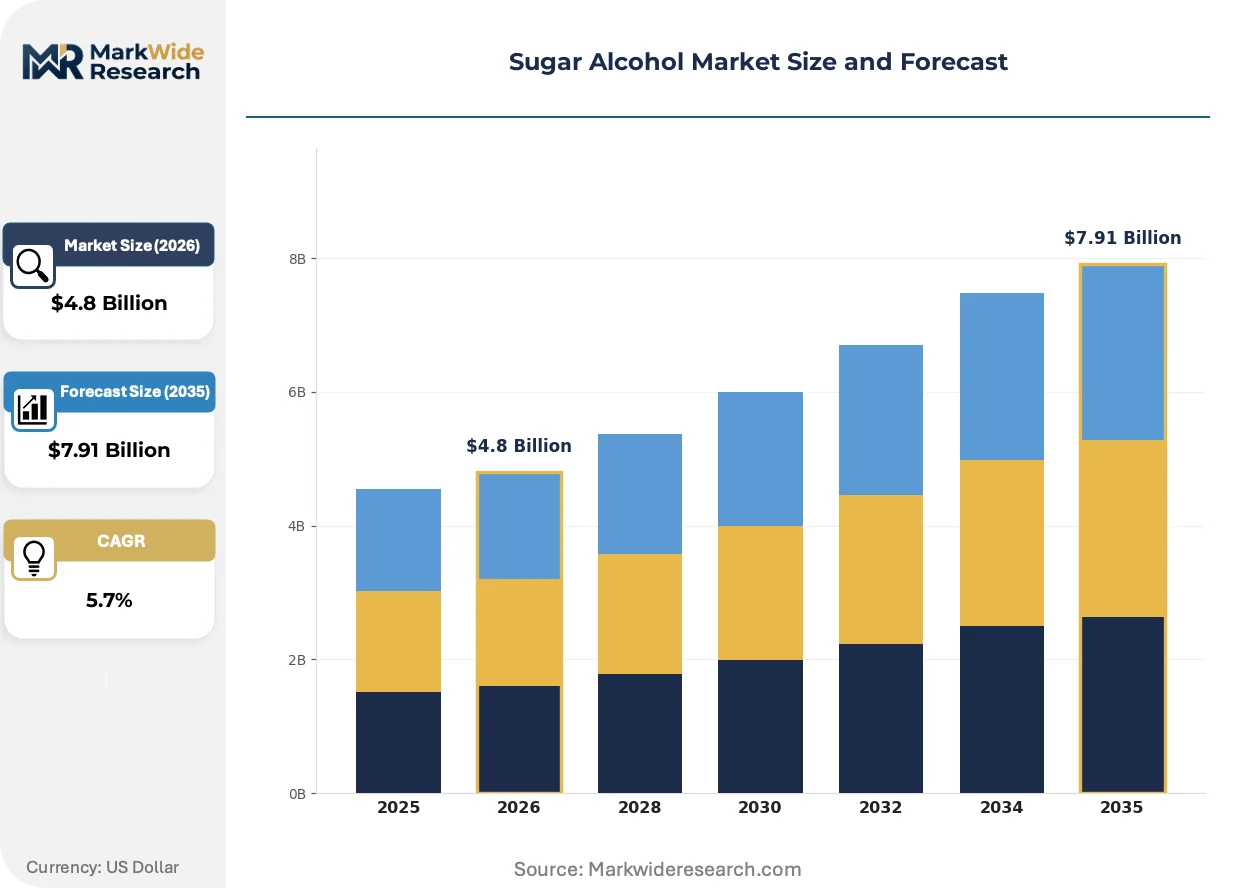
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbitol, Xylitol, Erythritol, Mannitol, Maltitol, Isomalt Application: Confectionery, Pharmaceuticals, Cosmetics, Food & Beverages, Oral Care, Animal Feed End User: Dietary Supplement Manufacturers, Pharmaceutical Companies, Cosmetics Producers, Food Processing Units, Dental Product Makers, Pet Nutrition Firms Packaging Type: Bulk Bags, Drums, Bottles, Sachets, Pails, Cartons |
| Companies Covered | Roquette Frères, Cargill Incorporated, Ingredion Incorporated, Archer Daniels Midland Company, Tate & Lyle, DuPont, Associated British Foods PLC, Mitsubishi Shoji Foodtech Co., Ltd., BENEO GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Alcohol Market Strategic Shifts & Innovations
Innovation in the sugar alcohol market is driven by the need to balance functionality with consumer sensory expectations. This dynamic pushes development toward more sophisticated polyol blends, novel production methods, and formulations that mimic the properties of sucrose more closely.
Fermentation-based production is an increasingly important method for manufacturing specific polyols like erythritol. Food and beverage companies are adopting these ingredients to support "natural" positioning on product labels. This trend in bioprocessing is converging with traditional hydrogenation chemistry, creating a two-tiered market based on production origin and associated consumer appeal.
China's updated GB standards for food additives are imposing stricter purity specifications and testing protocols for polyols. This regulatory tightening forces global suppliers to adapt their quality control processes to access one of the largest consumer markets. The sorbitol and maltitol segments, which are heavily used in Chinese food processing, are most directly impacted by these enhanced compliance requirements.
A notable shift in purchasing involves food manufacturers moving from sourcing individual polyols toward procuring complete, pre-blended sweetener systems. This disrupts commodity sales channels, favoring suppliers with application expertise who offer tailored solutions. This trend is most prominent in the beverage and confectionery sectors, where speed-to-market and optimized taste are critical.
Sugar Alcohol Market Segmentation
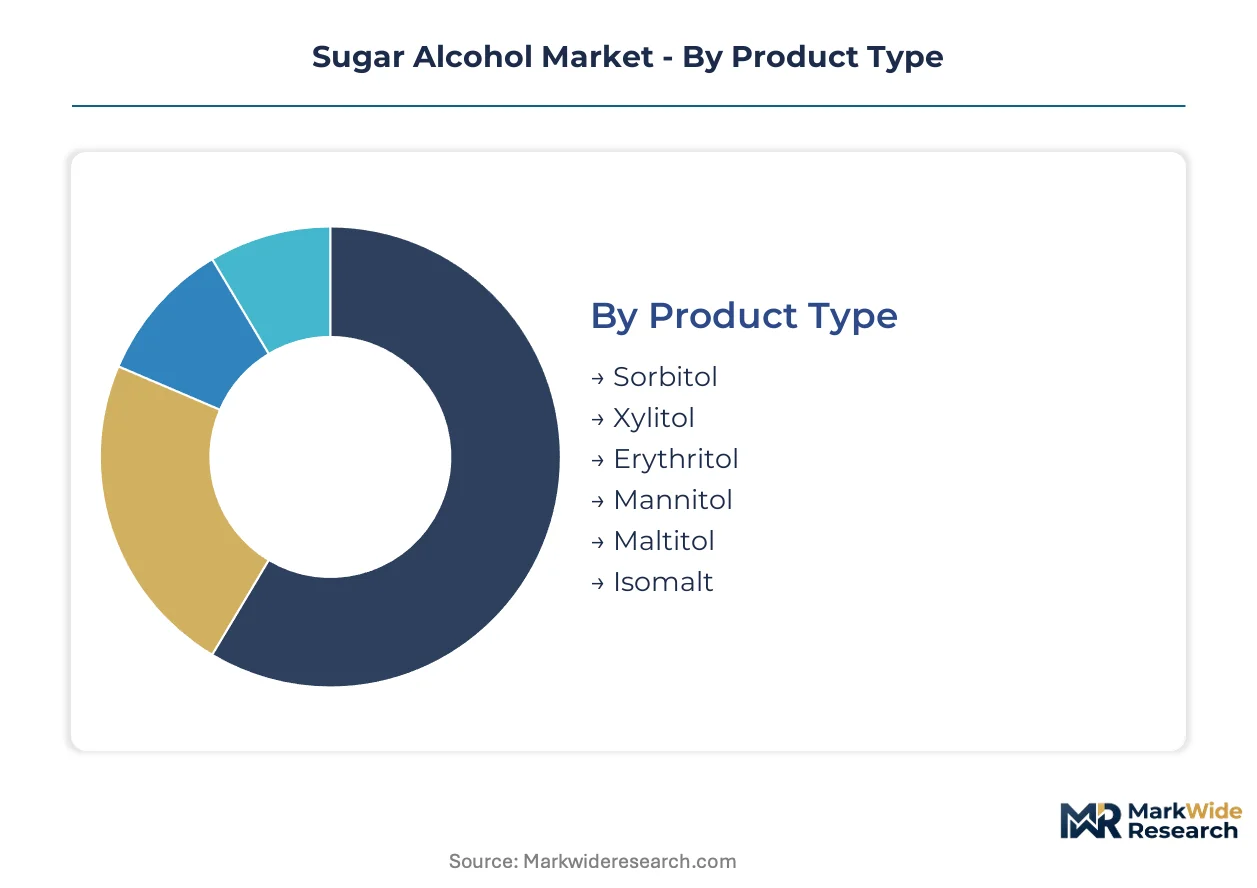
Understanding the segmentation of the sugar alcohol market is crucial for identifying specific demand drivers and supply concentrations. This granular breakdown reveals how different product types, applications, end-users, and packaging formats contribute to the overall market valuation and growth trajectory.
Product Type:
The customization-vs-standardization spectrum is evident in the diverse range of sugar alcohol product types available to manufacturers.
- Sorbitol:A polyol derived from glucose through hydrogenation, widely used as a bulk sweetener, humectant, and texturizing agent. Demand concentrates in confectionery and baked goods in the United States, driven by its cost-effectiveness and functional properties.
- Xylitol:A five-carbon sugar alcohol naturally present in many fruits and vegetables, valued for its non-cariogenic properties. It finds extensive use in oral care products and sugar-free chewing gum formulations.
- Erythritol:A zero-calorie sugar alcohol produced via fermentation, known for its high digestive tolerance and clean taste profile. Its adoption is accelerating in premium beverages and dietary supplements, particularly in health-conscious markets within Europe.
- Mannitol:A polyol with a characteristic cooling sensation, frequently utilized as a dusting powder for chewing gum and in pharmaceutical excipients.
- Maltitol:Derived from maltose, this sugar alcohol offers a sweet profile comparable to sucrose, making it suitable for chocolate and sugar-free candy formulations.
- Isomalt:A disaccharide alcohol produced from sucrose, valued for its non-hygroscopic properties and stability in hard candies and decorative confectionery.
Most installed capacity flows through Sorbitol. Expansion is steepest in Erythritol.
Application:
The volume dynamics significantly influence the market structure within this application category.
- Confectionery:Sugar alcohols replace sucrose in candies, chewing gum, and chocolates, offering reduced calories and non-cariogenic benefits. Demand is strong in developed markets like Germany and Japan, where low-sugar options are preferred.
- Pharmaceuticals:High-purity polyols serve as excipients, binders, and diluents in tablets, syrups, and oral drug formulations. These applications demand strict adherence to pharmacopeia standards.
- Cosmetics:Sugar alcohols impart moisturizing properties and improve texture in skincare lotions, creams, and various personal care products.
- Food & Beverages:Polyols function as sweeteners, texturizers, and humectants in dairy products, baked goods, and soft drinks. Reformulation efforts in the United States and China drive this segment due to stringent sugar labeling.
- Oral Care:Xylitol and sorbitol are integrated into toothpastes, mouthwashes, and chewing gums for their proven anti-cariogenic effects.
- Animal Feed:Polyols enhance palatability and provide essential energy in specialized pet food and livestock feed formulations.
Confectionery applications drive significant volume, while Food & Beverages demonstrate the fastest growth.
End User:
The specific application requirements of end-users dictate the functional properties of sugar alcohols procured.
- Dietary Supplement Manufacturers:These companies incorporate erythritol and other polyols into protein powders, functional foods, and nutritional bars for calorie reduction.
- Pharmaceutical Companies:These firms procure high-purity polyols for use as excipients in drug delivery systems and medical formulations. Strict pharmacopeia standards from entities like the US FDA and Europe's EMA govern their purchasing decisions.
- Cosmetics Producers:They utilize sugar alcohols as humectants, emollients, and texture modifiers in diverse personal care and beauty product lines.
- Food Processing Units:These entities integrate bulk sugar alcohols into a wide array of products, from baked goods to dairy and beverages. Their demand is concentrated in major food manufacturing hubs across Europe and North America, driven by regulatory compliance.
- Dental Product Makers:These manufacturers primarily source xylitol and sorbitol for anti-cavity toothpastes, mouthwashes, and other oral hygiene products.
- Pet Nutrition Firms:These businesses use polyols to improve the taste, texture, and nutritional profile of specialized animal feed and pet treats.
Food Processing Units represent the largest procurement base, with Dietary Supplement Manufacturers showing climbing growth.
Packaging Type:
The supply concentration in packaging types reflects the diverse logistical needs of industrial and consumer clients.
- Bulk Bags:Industrial-scale users, particularly food processing units and large pharmaceutical manufacturers, purchase sugar alcohols in multi-ton bulk bags. This packaging minimizes transportation costs and caters to high-volume production lines.
- Drums:Intermediate volumes of sugar alcohols, often for specialized applications or smaller batch productions, are supplied in drums. This format offers better handling and storage for specific industrial clients.
- Bottles:Smaller quantities of liquid or powdered sugar alcohols are packaged in bottles for retail or specific end-user applications.
- Sachets:Individual serving sizes of sugar alcohols are found in sachets, common in dietary supplements and consumer-facing products.
- Pails:Medium-sized industrial users or food service operations often receive sugar alcohols in pails for ease of dispensing.
- Cartons:Powdered or granulated sugar alcohols are sometimes packaged in cartons for consumer retail or smaller commercial use.
Bulk Bags dominate industrial procurement, and Sachets exhibit the steepest expansion trajectory in consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage influences global sugar alcohol supply. Production migration occurs due to differing compliance costs and market access requirements. This dynamic impacts pricing structures and regional manufacturing investments. Major food processing hubs experience varied demand pressures.
United States
Demand for sugar-reduced formulations drives significant sugar alcohol consumption. US FDA nutritional labeling mandates compel food producers to reformulate products. Food processing units across the Midwest, particularly around Chicago, integrate bulk sugar alcohols into beverages and baked goods.
New China
New production capacity for bulk sugar alcohols recalibrates the global supply landscape. China's GB standards for food additives impose stricter purity specifications. Food processing hubs in the Yangtze River Delta region, including Shanghai, adapt to enhanced compliance requirements.
Germany
Confectionery applications drive substantial sugar alcohol demand in Europe. EFSA regulations on food additives and labeling influence product development. Major food manufacturers in Bavaria, like those near Munich, prioritize low-sugar options for the European market.
Japanese Consumers
Japanese consumers highly value non-cariogenic sugar alcohols, particularly in oral care products. PMDA guidelines ensure quality and safety for pharmaceutical excipients. Food processing centers in the Kanto region, including Tokyo, integrate xylitol into chewing gums and specialized health foods.
Escalating India
Escalating consumer demand for processed, low-sugar foods propels market expansion. FSSAI regulations on food additives shape ingredient choices for local producers. Food manufacturing clusters in Maharashtra, particularly around Pune, increase their procurement of polyols for beverages and dairy products.
Sugar Alcohol Market Key Industry Players
Chinese producers anchor one tier of the sugar alcohol market; established global agribusiness giants hold another. The market exhibits a tiered structure, with commodity-scale manufacturers competing on price and specialized polyol chemistry firms differentiating through application expertise. Key archetypes include large-scale commodity suppliers, integrated agricultural processors, and innovation-driven polyol specialists. Strategic moves involve significant capacity expansion, securing cost-effective feedstock sourcing, and advanced application development.
On the integrated agribusiness vector, Cargill Incorporated and Archer Daniels Midland Company exemplify extensive feedstock sourcing and cost leadership. These entities leverage their agricultural commodity processing capabilities to produce bulk sugar alcohols efficiently, often integrating them into broader ingredient portfolios. Roquette Frères represents a distinct archetype, focusing on deep expertise in polyol chemistry and application development. This company provides tailored solutions for food and pharmaceutical clients, emphasizing differentiation through specialized formulations and a strong innovation pipeline for new polyol applications.
| Leading Market Players |
|---|
| Roquette Frères |
| Cargill Incorporated |
| Ingredion Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle |
| DuPont |
| Associated British Foods PLC |
| Mitsubishi Shoji Foodtech Co., Ltd. |
| BENEO GmbH |
Cost & Logistics Intelligence
Vertical integration into agricultural commodity processing by global agribusiness giants like Cargill Incorporated anchors both the supply position and pricing power for bulk sugar alcohols. This integration secures feedstock access and enables cost leadership, significantly influencing market pricing dynamics.
Pricing Analysis
Direct-to-OEM discounts are prevalent for bulk sugar alcohols, reflecting the large procurement volumes from industrial food processing units. Contract-based long-term offtake agreements dominate for industrial buyers, offering price stability against volatile feedstock costs. Quality grade, volume scale, and geographic delivery costs drive price differentiation across the market. Pricing pressure stems from new production capacity coming online in China. Food processing units are highly price-sensitive for commodity polyols, while pharmaceutical companies prioritize purity and consistency.
Supply Chain Analysis
Regional distribution centers optimize logistics for polyols, especially in major food processing hubs across the United States and Europe. Geographic supply concentrates significantly in China, the United States, and France. Production relies heavily on agricultural commodities like corn and wheat starch. Commodity price volatility for these feedstocks presents a structural risk to processor margins. Distribution runs through a mix of direct sales to large industrial clients and specialized ingredient distributors for smaller accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sugar alcohol market acts as a regulatory compounder. US FDA nutritional labeling mandates compel food producers to reformulate products, sustaining demand growth.
For Market Incumbents: Anticipate increased competition from lower-cost Chinese producers in bulk sorbitol and maltitol segments. Invest in application development for specialized polyol blends to differentiate beyond commodity pricing. Secure long-term feedstock contracts to mitigate agricultural commodity price volatility. This strategy helps counter the substitution threat from natural high-intensity sweeteners like stevia.
For New Entrants and Emerging Players: Specialty ingredient distributors offer a viable entry point for novel polyols or high-purity grades like erythritol. Focus on the dietary supplement segment in health-conscious European markets for premium product positioning. Develop fermentation-derived erythritol to align with "natural" positioning on product labels. Emphasize superior digestive tolerance and clean taste profiles as key go-to-market angles.
For Investors and Strategic Acquirers: Roll-up economics work for specialized polyol chemistry firms because application expertise creates defensible niches. The market demonstrates sustained growth driven by global health trends over the next decade. Target integrated processors with strong R&D in polyol blends and established food and pharmaceutical client relationships. Increased M&A activity involving fermentation-based polyol producers indicates market maturation, serving as a signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | New erythritol production facilities in China will alter global supply dynamics. |
| Application Development | Roquette Frères enhances tailored polyol blends for food and pharmaceutical clients. |
| Feedstock Sourcing Optimization | Cargill Incorporated maintains cost leadership through extensive agricultural commodity networks. |
| Regulatory Compliance Investment | Producers adapt quality control processes to China's stricter GB standards. |
| Bioprocessing Technology Adoption | Manufacturers shift towards fermentation-based production for specific polyols like erythritol. |
Research Approach
Bottom-up food and beverage end-use modeling reconciled against top-down polyol supply-side tracking forms the analytical core of this study. Primary interviews with food technologists, procurement leads, regulatory affairs specialists, and R&D directors informed market dynamics. Secondary validation involved customs data, company annual reports, US FDA filings, and EFSA scientific opinions. This approach ensures robust triangulation of volume and value projections.
An input-output matrix framework integrates historical data with future projections across the analysis window. Segmentation dimensions modeled include product type, application, end-user, packaging format, and regional regulatory frameworks. Compound Annual Growth Rates (CAGRs) were derived from a weighted average of segment-specific growth drivers. Key forecast inputs included sugar-reduced formulation adoption rates and new production capacity schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to feedstock price volatility and evolving regulatory mandates. Projections reflect current market conditions and anticipated technological shifts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Sorbitol Market
Sweeteners
Xylitol Market
Sweeteners
Nutritive Sweeteners Market
Sweeteners
Indonesia Food Sweetener Market
Sweeteners
High-Fructose Corn Syrup (HFCS) Market
Sweeteners
Sucrose Acetate Isobutyrate Market
Sweeteners
South America Sugar Substitutes Market
Sweeteners
Sweeteners Market
Sweeteners
Glucose Syrup Market
Sweeteners
Egypt Food Sweetener Market
Sweeteners
Compressible Sugar Market
Sweeteners
Mannitol Market
Sweeteners
Global Artificial Sweeteners Market
Sweeteners
United Kingdom Food Sweetener Market
Sweeteners
Argentina Food Sweetener Market
Sweeteners
Methyl Glucose Market