
 Chewing Gum Base Market | 2026-2036
Chewing Gum Base Market Size, Share, and Industry Trends Forecast 2026-2036
Chewing Gum Base Market Outlook
Specialized polymer chemists and food-grade elastomer technicians is rotating toward biodegradable and plant-derived formulations, tightening the talent pipeline for conventional synthetic base production. Cafosa leverages its vertical integration across ester gum and polyvinyl acetate supply chains to sustain cost advantages in European manufacturing. Maykim Gumbase anchors Middle Eastern demand through localized compounding facilities and halal-certified product lines. Daito Chemical Co., Ltd. competes on precision-controlled hydrogenation processes that yield consistent chew texture profiles for Japanese OEM customers.
Chewing gum base comprises an insoluble, non-nutritive matrix of food-grade elastomers, resins, waxes, and emulsifiers that provides cohesive chew texture and controlled flavor release, typically formulated with polyisobutylene, polyvinyl acetate, or natural chicle derivatives at precise melt viscosity ranges between 80 and 120 degrees Celsius. Synthetic gum dominates volume throughput due to established supply chains and predictable performance, though biodegradable gum commands expanding R&D allocation as European packaging waste directives intensify scrutiny of petroleum-derived ingredients. Sugar-free gum captures functional positioning among dental-health-positioned brands, while bulk packs remain the default packaging modality for industrial manufacturers supplying downstream confectioners.
FDA food additive regulations under 21 CFR 172 govern elastomer and plasticizer approvals for US-bound gum bases, while EFSA's re-evaluation of titanium dioxide and certain petroleum waxes is forcing reformulation across export-oriented producers. BIS standards in India and CDSCO food safety protocols add compliance layers for suppliers targeting pharmaceutical-grade nicotine gum applications. Stakeholders must monitor evolving polymer substitution pathways and regional certification divergence to preserve formulation flexibility across fragmented regulatory landscapes.
Market Dynamics
The shift toward biodegradable elastomers is compressing reformulation cycles across synthetic gum base manufacturers, as EFSA and FDA simultaneously tighten additive safety reviews while downstream confectioners demand petroleum-free ingredient decks.
Growth Catalysts
- Functional Confectionery Expansion:Dental-health-positioned sugar-free gum is pulling specialized base formulations with controlled-release microencapsulation systems into premium product lines.
- REACH Compliance Deadlines:ECHA's substance evaluation timeline for petroleum-derived waxes is accelerating substitution R&D among European compounders seeking regulatory pre-approval.
- Latin American Manufacturing Density:Brazil and Mexico are concentrating chewing gum production capacity, creating localized demand for halal-certified and tropical-stability-optimized base variants.
Market Restraints
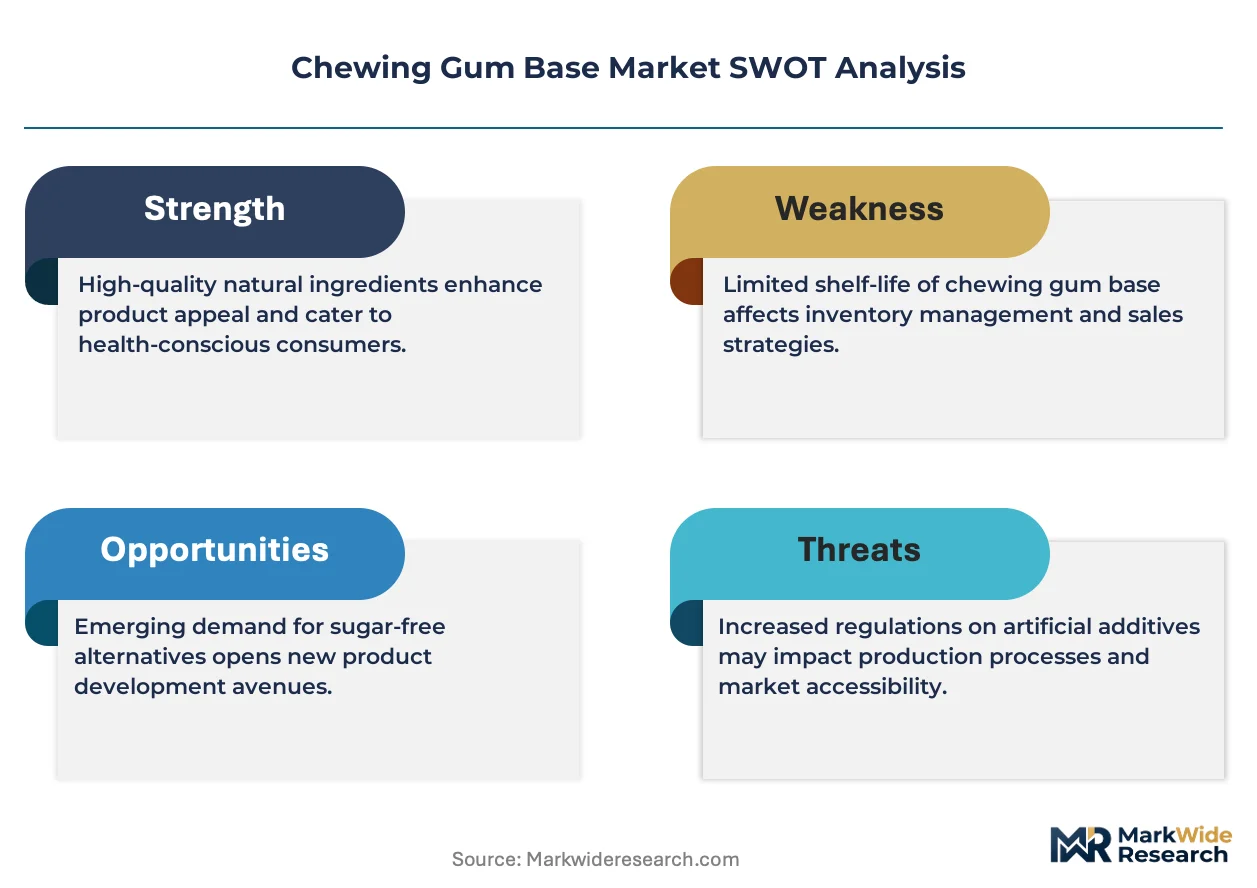
- Polyisobutylene Supply Concentration:Four petrochemical complexes in Texas and Louisiana control the majority of food-grade elastomer feedstock, exposing formulators to hurricane-season disruption risk.
- Chicle Harvest Volatility:Natural gum base output from Mexican and Guatemalan rainforest cooperatives fluctuates with precipitation patterns and land-use policy shifts.
- Titanium Dioxide Re-evaluation:EFSA's 2021 safety opinion removing E171 from approved food additives is forcing complete reformulation of white-pigmented gum bases for EU export.
Strategic Opportunities
- Pharmaceutical-Grade Nicotine Gum:CDSCO's expanded approval pathway for smoking-cessation products in India opens formulation contracts requiring GMP-certified base production.
- Biodegradable Polymer Convergence:Polyhydroxyalkanoate and plant-derived polyester elastomer technologies are crossing performance thresholds for commercial chew applications.
- Direct-to-Compound Sourcing:Mid-sized confectioners are bypassing distributors to contract directly with base manufacturers, compressing margin layers and enabling specification customization.
Industry Challenges
- Polymer Hydrogenation Expertise Scarcity:Precision-controlled catalytic processes for consistent chew texture require specialized technicians that synthetic rubber and food science programs are not producing at replacement rates.
- Dual Certification Burden:Simultaneous FDA food additive petitions and EFSA novel food applications are extending qualification timelines to 36-48 months for innovative base chemistries.
- Legacy Equipment Retrofit Costs:Conventional compounding extruders lack temperature control precision for plant-derived elastomer processing, requiring capital-intensive line upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chewing Gum Base Market |
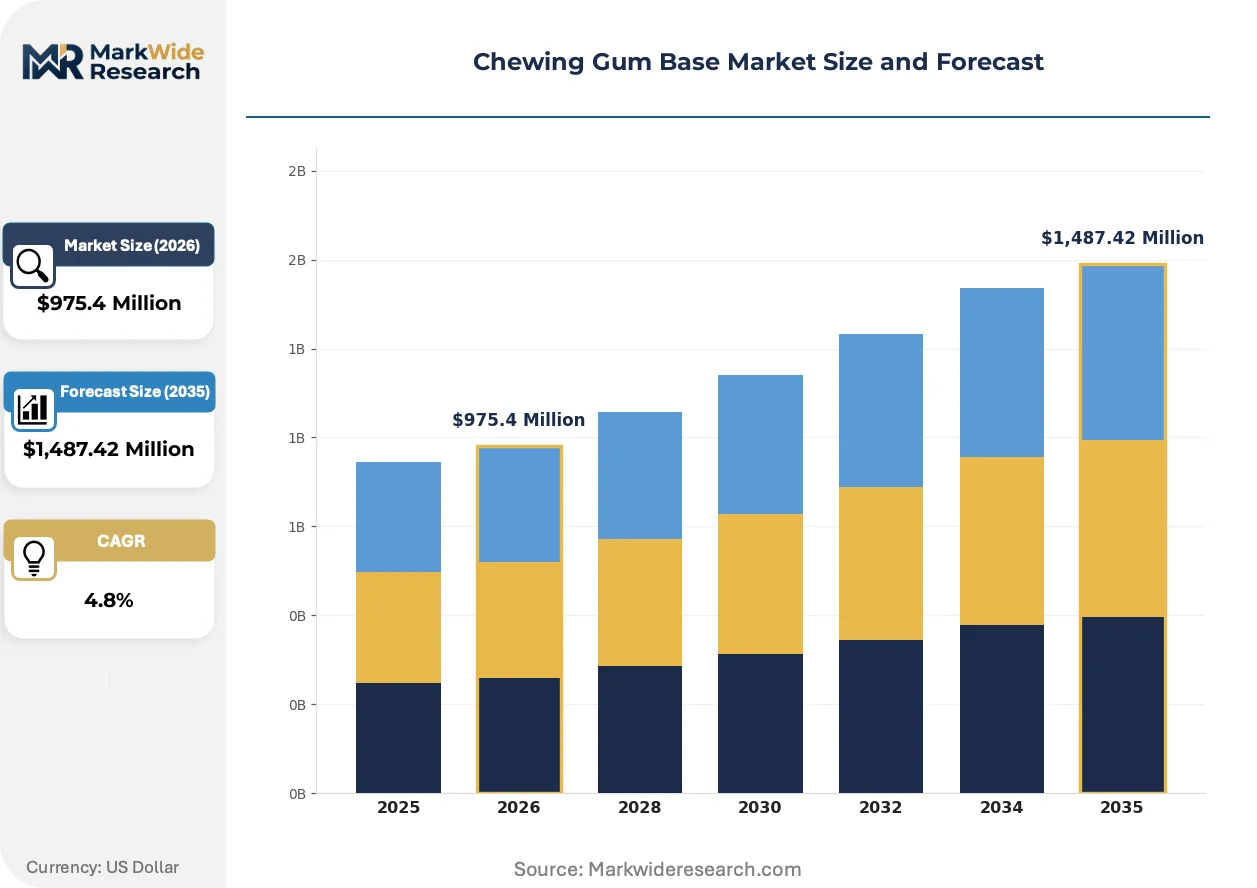
| Market Size in 2026 | $975.4 Million |
| Market Size in 2035 | $1,487.42 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Gum, Synthetic Gum, Biodegradable Gum, Sugar-free Gum Flavor Type: Mint, Fruit, Spice, Herbal Packaging Type: Bulk Packs, Stick Packs, Jars, Pouches End User: Retailers, Foodservice Providers, OEMs, Manufacturers |
| Companies Covered | Maykim Gumbase, Remik, Cafosa, Proaroma, Fimcobase, Gumlink Confectionery Company, Gumcorp, Daito Chemical Co., Ltd., Wuxi Sanxi Gum Base Manufacture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chewing Gum Base Market Strategic Shifts
Formulation science is pivoting toward petroleum independence while regulatory divergence between major jurisdictions forces parallel qualification tracks. Three developments are compressing competitive timelines.
Microencapsulation technology for flavor-release modulation is miniaturizing. Precision-engineered lipid and protein shell structures now enable burst, sustained, or layered release profiles within a single chew session. Japanese and Korean OEMs are adopting these systems for functional ingredient delivery at accelerated procurement cycles. This capability is miniaturizing the differentiation window between premium therapeutic gums and conventional confectionery, compressing brand refresh cycles to 18-month intervals.
REACH authorization requirements for microplastic-relevant polymers are tightening. ECHA's 2023 restriction proposal targeting intentionally added microplastics captures synthetic elastomer fragments from chewing gum waste. German and Dutch environmental regulators are advancing extended producer responsibility frameworks that assign collection and processing costs to base manufacturers. Export-oriented compounders are responding with accelerated biodegradability certification timelines and pre-emptive polymer substitution programs.
Flavor houses and base compounders are consolidating technical relationships. Previously discrete supply tiers are merging R&D functions to co-develop integrated texture-release systems that lock in formulation specifications. This pattern is most visible in Swiss and Italian confectionery clusters, where integrated development agreements now span 5-7 year horizons rather than transactional annual contracts. The shift is compressing supplier switching flexibility while raising barriers for non-integrated competitors.
Chewing Gum Base Market Segmentation
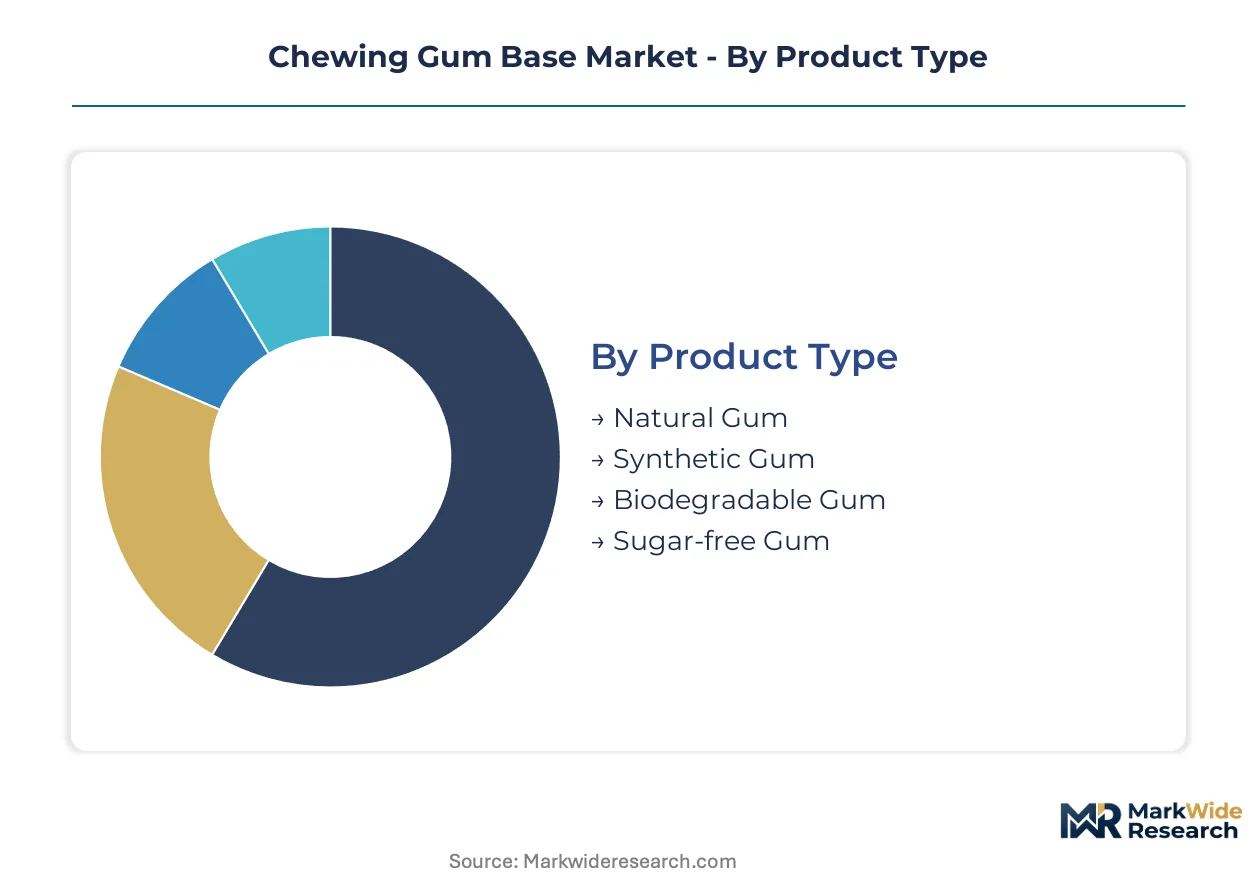
Chewing gum base segmentation tracks divergent formulation chemistries and packaging modalities that command distinct margin structures across confectionery supply chains. Manufacturers calibrate compounding investments against end-use specifications ranging from pharmaceutical-grade nicotine delivery to impulse-retail confectionery.
Product Type:
Margin pools concentrate in specialty elastomer formulations that meet dual-certification requirements for pharmaceutical and food-grade applications.
- Synthetic Gum:Polyisobutylene and polyvinyl acetate elastomers dominate volume throughput with melt viscosity specifications calibrated between 80-120°C for consistent chew texture. Demand concentrates among Brazilian and Mexican contract manufacturers supplying private-label confectioners, though EFSA's petroleum-derived wax scrutiny is compressing reformulation cycles for EU-bound exports.
- Biodegradable Gum:Polyhydroxyalkanoate and plant-derived polyester elastomers are crossing performance thresholds for commercial chew applications with controlled biodegradability certification. European compounders facing ECHA microplastic restrictions are rotating R&D allocation fastest toward this category, though capital-intensive extruder retrofits delay capacity scaling.
- Natural Gum:Chicle-derived bases from Mexican and Guatemalan rainforest cooperatives serve premium positioning and clean-label demand, constrained by precipitation-driven harvest volatility.
- Sugar-free Gum:Specialized bases with controlled-release microencapsulation support dental-health functional positioning among therapeutic and premium confectionery lines.
Synthetic gum holds installed capacity across Texas and Louisiana petrochemical corridors. Biodegradable gum is rotating up the share rankings among REACH-compliant European compounders.
Flavor Type:
Flavor-release engineering determines base formulation specifications, with mint and fruit commanding divergent lipid-compatibility requirements for microencapsulation systems.
- Mint:Menthol and peppermint oil formulations require polar-compatible elastomer matrices that resist flavor migration during shelf storage, concentrating demand among North American and European therapeutic gum manufacturers.
- Fruit:Ester-based flavor systems demand non-polar elastomer compatibility and acid-stable emulsifier packages, with procurement accelerating from Korean and Japanese OEMs developing layered-release functional confectionery.
- Spice:Cinnamon and clove oil formulations serve niche premium positioning with heat-stable base requirements for tropical climate distribution.
- Herbal:Botanical extract bases support wellness-positioned product lines requiring GRAS-certified elastomer matrices for regulatory pre-approval.
Mint flavor bases retain the largest installed formulation library across compounder technical centers. Fruit flavor bases are climbing the fastest among Asian OEM procurement specifications.
Packaging Type:
Packaging modality shapes base physical specifications, with bulk and stick formats demanding divergent melt-flow indices for downstream processing efficiency.
- Bulk Packs:Industrial totes and drums supply downstream confectioners with base slabs requiring re-melt processing, dominating volume throughput among contract manufacturers in Brazil's expanding production corridor.
- Stick Packs:Precut rectangular base formats integrate directly with high-speed wrapping equipment, concentrating demand among established North American and European brand manufacturers with dedicated packaging lines.
- Jars:Pelletized base formats serve artisanal and small-batch confectioners requiring manual dosing flexibility.
- Pouches:Flexible pillow-pack base formats support pilot-scale production and rapid formulation iteration among mid-sized compounders.
Bulk packs maintain the deepest installed capacity across Latin American manufacturing hubs. Stick packs are gaining share fastest as mid-sized confectioners bypass distributors for direct-to-compound sourcing.
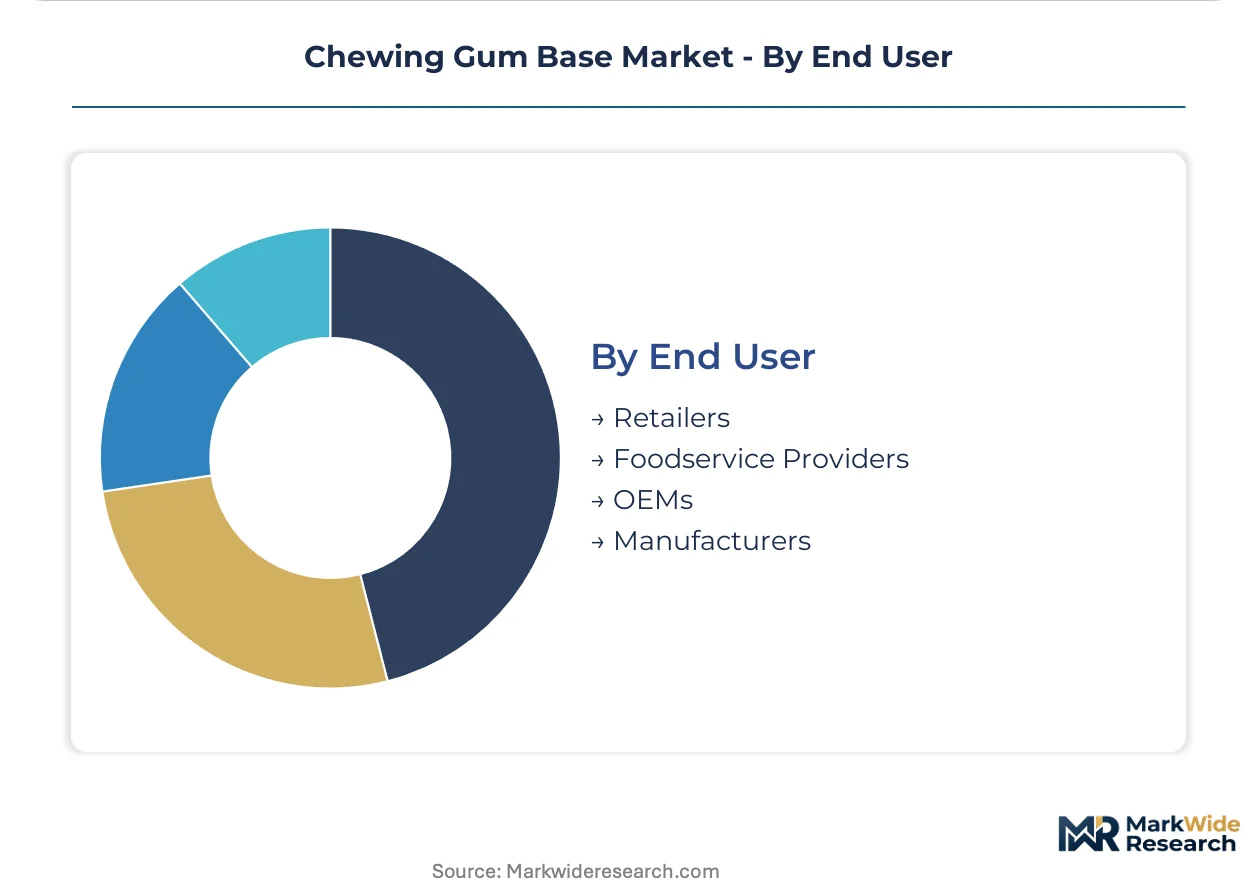
End User:
End-use specifications fragment base qualification requirements, with pharmaceutical and foodservice applications demanding divergent certification tracks.
- Manufacturers:Large-scale confectioners specify base formulations with validated process windows for continuous extrusion, representing the most concentrated procurement volume across integrated brand houses.
- OEMs:Contract manufacturers require rapid formulation iteration capabilities and regional certification support, with demand concentrating among Japanese and Korean functional confectionery developers.
- Retailers:Private-label programs demand cost-optimized base specifications with flexible minimum order quantities for seasonal product rotation.
- Foodservice Providers:Dispenser-compatible base formats serve hospitality and institutional channels with extended chew stability requirements for ambient storage conditions.
Manufacturer-directed specifications control the largest qualified formulation library across compounder technical service teams. OEM procurement is expanding most quickly as integrated development agreements extend to five-to-seven-year horizons.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. European manufacturers prioritize biodegradable elastomer certifications under REACH pressure, while Latin American producers optimize for tropical-stability formulations in high-humidity climates.
United States
FDA food additive petitions under 21 CFR 172 govern elastomer approvals for domestic gum base production. Hurricane-season disruption risk concentrates around Texas and Louisiana petrochemical corridors that supply food-grade polyisobutylene. Chicago and New Jersey house major compounding facilities serving North American confectioners.
Germany
ECHA microplastic restriction proposals accelerate substitution R&D among synthetic base manufacturers. REACH authorization deadlines for petroleum-derived waxes compress reformulation cycles to 24-month intervals. The Cologne-Düsseldorf industrial cluster anchors European gum base technical service capabilities.
Brazil
Halal-certified base variants command premium positioning among export-oriented confectioners serving Middle Eastern markets. ANVISA food additive regulations align with Mercosur technical standards for regional trade. São Paulo state concentrates private-label manufacturing capacity with direct-to-compound sourcing growth.
Japan
Precision-controlled hydrogenation processes yield consistent chew texture profiles for therapeutic and functional gum applications. METI industrial standards govern food-grade elastomer purity specifications. The Osaka-Kobe manufacturing corridor specializes in microencapsulation-integrated base formulations.
India
CDSCO expanded approval pathways for nicotine gum applications open pharmaceutical-grade base contracts requiring GMP certification. FSSAI food safety protocols add compliance layers for import substitution programs. Maharashtra and Gujarat states concentrate contract manufacturing for domestic and export markets.
Chewing Gum Base Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier that handles formulation customization and regional certification support. The market structure rewards backward integration into ester gum and polyvinyl acetate supply chains, while mid-sized compounders compete on rapid iteration timelines. Three archetypes dominate: petrochemical-integrated volume producers, biodegradable specialty formulators, and regional certification specialists. Competitive moves concentrate on capacity expansion in Latin American manufacturing corridors and strategic partnerships between flavor houses and base compounders.
Within the integrated tier, Cafosa exemplifies petrochemical-integrated production with European manufacturing scale. Maykim Gumbase anchors Middle Eastern demand through localized compounding presence. Daito Chemical Co., Ltd. occupies a position among precision-process specialists serving Japanese OEM requirements. These three represent distinct competitive vectors: supply chain control, geographic proximity, and technical specification depth.
| Leading Market Players |
|---|
| Maykim Gumbase |
| Remik |
| Cafosa |
| Proaroma |
| Fimcobase |
| Gumlink Confectionery Company |
| Gumcorp |
| Daito Chemical Co., Ltd. |
| Wuxi Sanxi Gum Base Manufacture |
| Others |
Value Chain & Pricing Dynamics
Scale economies at Texas and Louisiana petrochemical complexes concentrate food-grade polyisobutylene supply among four dominant producers, creating asymmetric pricing power that elevates floor prices for synthetic gum base formulations while compressing margin capture for mid-sized compounders lacking backward integration into elastomer feedstock.
Pricing Analysis
Long-term offtake contracts dominate procurement between Brazilian and Mexican contract manufacturers and Gulf Coast petrochemical suppliers, insulating volume purchasers from spot market volatility while spot transactions concentrate among artisanal confectioners sourcing natural chicle bases. Price differentiation separates pharmaceutical-grade GMP-certified bases from standard food-grade formulations, with halal certification adding further premium tiers. Cost compression in synthetic gum categories is intensifying as EFSA petroleum-derived wax scrutiny forces accelerated reformulation cycles. Private-label retailers exhibit highest price sensitivity, while Japanese therapeutic gum OEMs prioritize chew texture consistency over unit cost.
Supply Chain Analysis
Inventory lead times for natural chicle bases extend substantially during Guatemalan and Mexican dry seasons, forcing compounders to maintain buffer stocks that tie up working capital across the rainy harvest window. Geographic supply concentration centers on the United States for synthetic elastomers, Brazil for halal-certified compounding, and Japan for precision hydrogenation equipment. Raw material dependencies include polyisobutylene, polyvinyl acetate, and ester gum resins. Single-source vulnerability characterizes food-grade hydrogenation catalyst supply. Distribution runs through direct-to-compound channels that bypass traditional distributor tiers for mid-sized confectioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable elastomer performance thresholds crossing commercial viability represent a technological inflection that will displace incumbent petroleum-derived formulations, while ECHA microplastic restrictions compress the transition timeline.
For Market Incumbents: Fortify backward integration into ester gum and polyvinyl acetate supply chains to preserve cost advantages against biodegradable specialty formulators. Accelerate extruder retrofit programs for plant-derived elastomer processing before capital equipment lead times extend. Defend market position by locking integrated development agreements with flavor houses across five-to-seven-year horizons that raise switching costs for downstream confectioners.
For New Entrants and Emerging Players: Anchor in pharmaceutical-grade nicotine gum base production for Indian CDSCO-regulated smoking-cessation applications, where GMP certification requirements create barrier-protected margin pools. Target white-space opportunities in tropical-stability-optimized formulations for Brazil's expanding manufacturing corridor. Pursue direct-to-compound sourcing relationships with mid-sized Latin American confectioners seeking specification customization.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biodegradable specialty formulators with pre-qualified REACH-compliant polymer pathways over petrochemical-integrated volume producers facing stranded asset risk. Acquisition targets should demonstrate validated polyhydroxyalkanoate or plant-derived polyester elastomer performance at commercial scale. Monitor ECHA authorization timelines for petroleum-derived waxes as the critical inflection signal for substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer R&D Scale-Up | European compounders facing ECHA microplastic restrictions gain first-mover certification advantage. |
| Halal Certification Investment | Brazilian manufacturers unlock premium positioning in Middle Eastern export markets through ANVISA-aligned standards. |
| Direct-to-Compound Channel Development | Mid-sized confectioners bypass distributors, compressing margin layers and enabling specification customization. |
| Microencapsulation Technology Integration | Japanese OEMs adopt precision-engineered release systems for functional ingredient delivery applications. |
| GMP-Certified Production Capacity Addition | Indian CDSCO pathway expansion opens pharmaceutical-grade nicotine gum base contract opportunities. |
Study Parameters
Desk research of FDA food additive petitions, EFSA safety opinions, ECHA restriction proposals, and ANVISA regulatory filings preceded structured interviews with gum base compounder technical directors, confectionery procurement managers, elastomer plant engineers, and flavor house R&D leads. Primary fieldwork combined with secondary validation from customs trade data, SEC filings of petrochemical suppliers, and industry association technical reports. Bottom-up volume modeling triangulated against top-down market sizing across synthetic, biodegradable, natural, and sugar-free product categories.
Variance decomposition across the projection horizon isolates volume, price, and mix effects by segmentation dimension including product chemistry, flavor compatibility requirements, packaging modality, and end-use certification tier. Modeled CAGRs derive from elasticity-adjusted demand curves incorporating regulatory substitution scenarios and polymer innovation diffusion patterns. Forecast inputs include ECHA authorization timeline probabilities, Brazilian manufacturing capacity expansion announcements, and Japanese OEM microencapsulation adoption rates.
Decision-makers should treat outputs as directional under assumptions of continued EFSA petroleum-derived ingredient scrutiny and stable chicle harvest cooperative structures; material deviation in regulatory stringency or climate-induced supply disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Coconut Flour Market
Ingredients
Global Malt and Malt Extracts Market
Ingredients
Mexico Sodium Reduction Ingredients Market
Ingredients
Fermented Ingredients Market
Ingredients
Guar Gum Market
Ingredients
Brazil Corn Syrup Market
Ingredients
Alkalized Cocoa Powder Market
Ingredients
Fish Feed Ingredients Market
Ingredients
Hydrolyzed Oat Protein Market
Ingredients
Soybean Meal Market
Ingredients
Low-Fat Cocoa Powder Market
Ingredients
Pine Needle Oil Market
Ingredients
Arrowroot Starch Market
Ingredients
Baking Ingredients Market
Ingredients
Lactase Enzyme Market
Ingredients
RTD/High Strength Premixes Market