
 Fruit Jellies Market | 2026-2036
Fruit Jellies Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Jellies Market Foresight
The gap between premium artisanal fruit jellies and commodity-grade products is shifting from a price divide into a formulation and provenance split. HARIBO GmbH and Co. KG leverages its European manufacturing footprint to sustain economies in standard-tier production. Perfetti van Melle anchors its position through flavor innovation pipelines that differentiate gelled confectionery from spreadable formats. Ferrara Candy Company specializes in seasonal and gift-oriented jellies that command higher margins through controlled distribution.
Fruit jellies are gelled preparations produced by cooking fruit juice or pulp with sugar and pectin to a solids content typically between 65 and 70 degrees Brix, yielding a spreadable consistency at room temperature. The primary commercial purpose spans breakfast spreads, baking ingredients, and confectionery fillings where texture stability and fruit identity matter. Mixed fruit jelly and berry blend jelly categories are capturing faster growth as consumers seek complex flavor profiles beyond single-fruit options. Glass jars retain dominance in premium positioning while pouches gain traction in foodservice and on-the-go retail channels where portion control and reduced breakage drive selection.
FDA standards of identity for fruit preserves and EFSA guidance on added sugars create compliance thresholds that favor reformulated or reduced-sugar product lines. BIS certification requirements in India and FSSAI labeling mandates further shape export market access for multinational producers. Stakeholders must monitor evolving pectin sourcing constraints and regional sugar taxation proposals that could alter cost structures faster than formulation cycles can adapt.
Market Dynamics
Clean-label reformulations driven by FDA and EFSA sugar-reduction guidance are forcing manufacturers to rebuild formulation pipelines around alternative sweeteners and modified pectin systems, compressing traditional product development cycles.
Growth Catalysts
- EFSA Added Sugars Guidance:European reformulation mandates accelerate demand for reduced-sugar fruit jellies that retain texture stability through high-methoxyl pectin alternatives.
- Foodservice Channel Expansion:Gourmet markets and institutional bakeries in Germany and Japan are expanding artisanal procurement for premium breakfast and dessert applications.
- Pouch Packaging Technology:Portion-control flexible formats are displacing glass in on-the-go retail, reducing breakage costs and enabling new distribution economics.
Market Restraints
- Citrus Pectin Supply Concentration:Portuguese and Brazilian citrus peel processors control 70% of global high-grade pectin supply, creating input vulnerability for texture-critical formulations.
- FSSAI Labeling Friction:India's strict nutritional disclosure requirements delay export certification timelines for multinational producers targeting retail channels.
- Fruit Juice Concentrate Volatility:Weather-driven supply swings in Mediterranean berry and tropical fruit regions compress margin predictability for standard-tier products.
Strategic Opportunities
- US Premium Private-Label Shelf Space:Retailers in California and New York metro areas are expanding house-brand gourmet lines, creating white space for co-manufacturing partnerships.
- Baking Ingredient Crossover:Pastry chefs and artisan bread producers are adopting fruit jellies as laminating agents and filling bases, opening technical-grade demand.
- Dual Carbon Goals Convergence:China's national carbon neutrality targets are accelerating renewable energy adoption in processing facilities, lowering operational emissions for export-qualified production.
Industry Challenges
- Reformulation Talent Scarcity:Food technologists skilled in low-sugar pectin chemistry and clean-label stabilizer integration command premium compensation, constraining R&D scaling.
- BIS Certification Timelines:Indian standards body testing protocols for imported fruit preparations extend market entry lead times beyond typical product launch windows.
- Legacy Equipment Retrofit Costs:Transitioning from open-kettle to vacuum evaporation systems for reduced-heat processing requires capital deployment that mid-tier producers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Jellies Market |
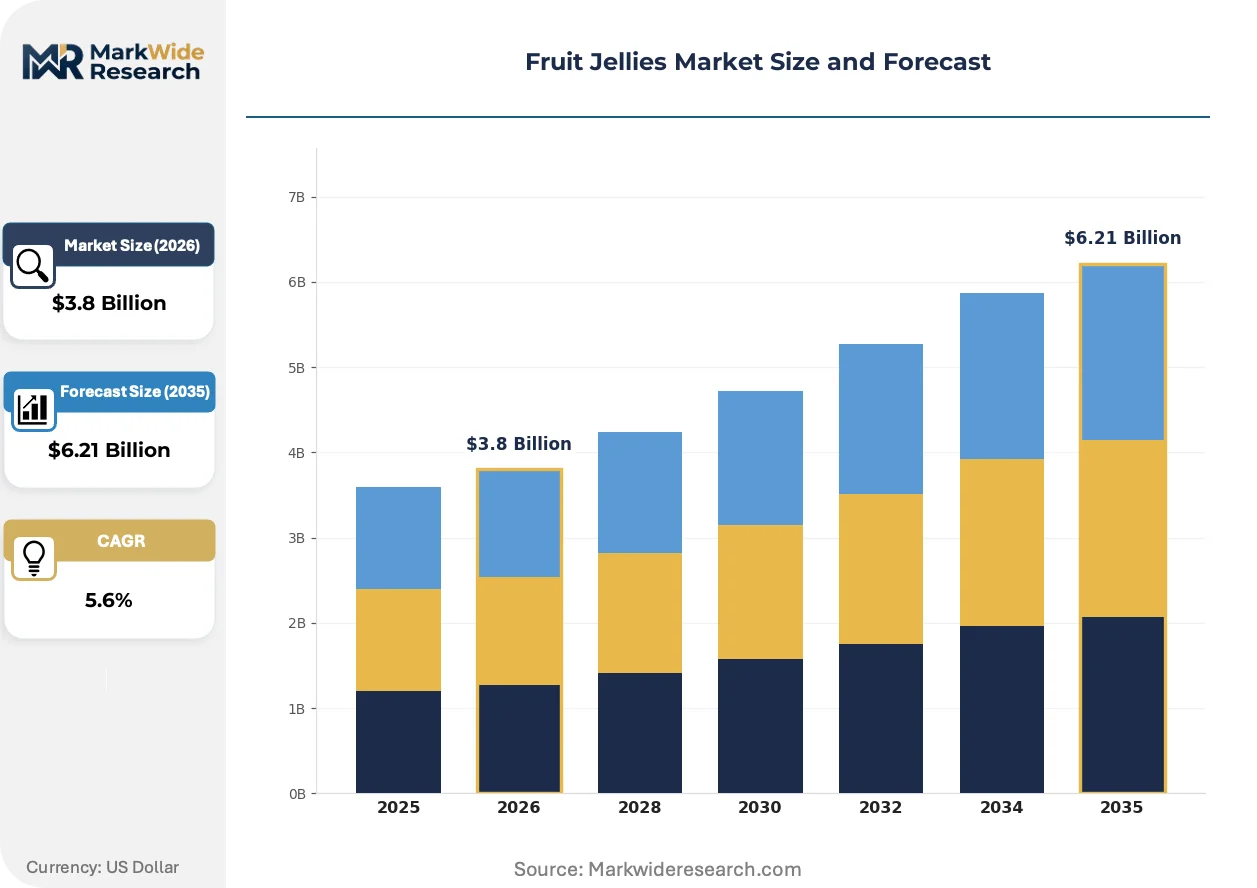
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apple Jelly, Grape Jelly, Mixed Fruit Jelly, Berry Blend Jelly Packaging Type: Glass Jars, Plastic Cups, Pouches, Tins Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops End User: Foodservice Providers, Retail Consumers, Catering Services, Gourmet Markets |
| Companies Covered | HARIBO GmbH and Co. KG, Perfetti van Melle, Ferrara Candy Company, Mars, Incorporated, Jelly Belly Candy Company, Cloetta AB, Just Born Inc., Mondelez International, Impact Confections, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Jellies Market Shifts & Advancements
Formulation science and packaging engineering are converging to redefine how fruit jellies deliver texture, transparency, and convenience across diverging consumption contexts.
High-pressure processing is unifying microbial safety with clean-label positioning by eliminating thermal degradation of volatile flavor compounds. Premium private-label lines in German and US coastal markets are adopting HPP for refrigerated distribution. This technology is compressing the traditional trade-off between extended shelf stability and ingredient simplicity that has constrained reduced-sugar variants.
REACH regulation extensions on food-contact materials are forcing European manufacturers to validate alternative jar coatings and pouch laminates for pectin-based acidity environments. Industrial consequence includes accelerated migration testing costs and reformulation of sealing compounds. Premium glass-dependent segments in France and Switzerland are responding by qualifying ceramic-coated closures that satisfy both chemical safety and premium aesthetic requirements.
Direct-to-foodservice procurement is bypassing traditional wholesale intermediaries as bakery chains and hotel groups build specification-direct relationships with co-manufacturers. This channel compression is most visible in Japan's convenience store bakery networks and US regional restaurant groups seeking proprietary flavor profiles. The shift demands that producers maintain dual commercial organizations serving divergent retail and foodservice technical requirements.
Fruit Jellies Market Segmentation
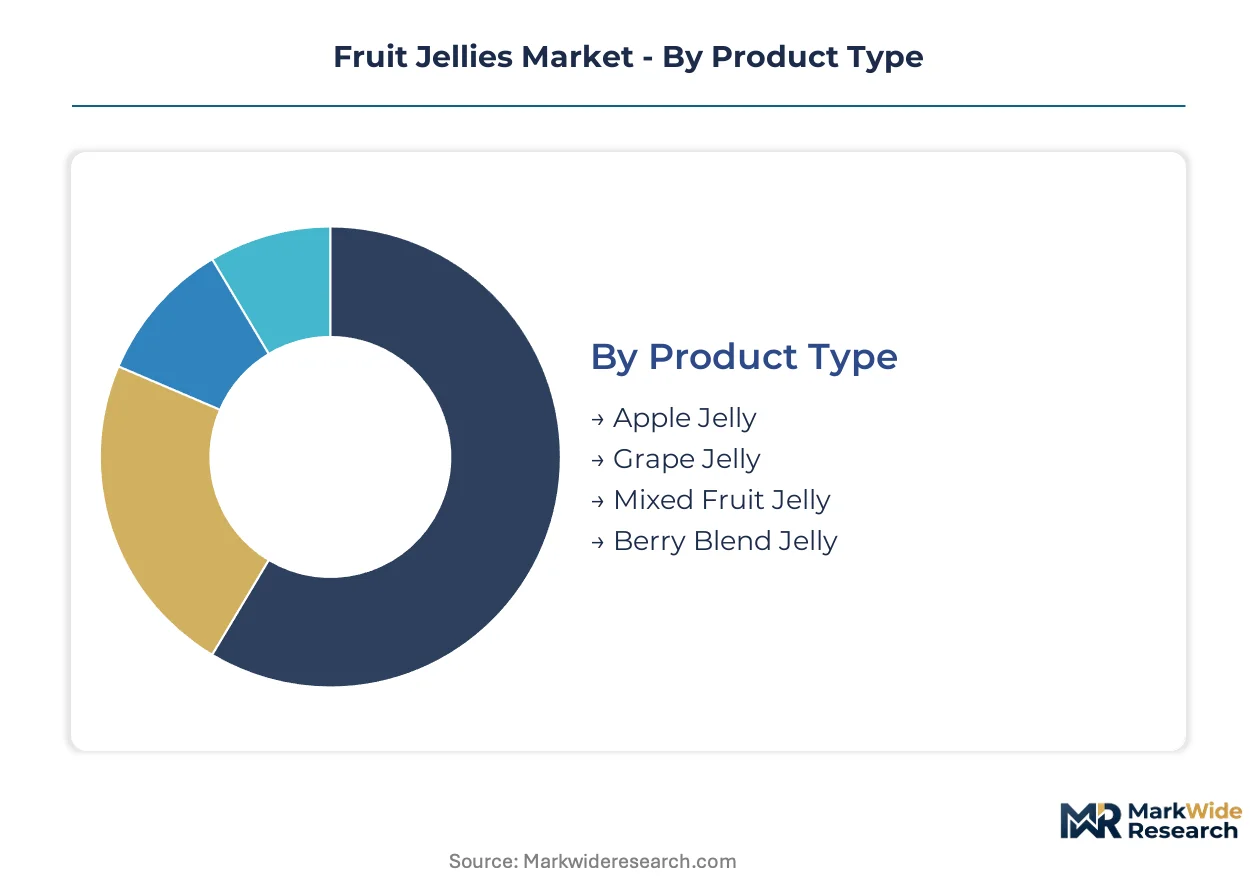
Formulation chemistry and packaging engineering diverge sharply across fruit jelly segments, creating distinct margin architectures that reward specialization over broad-line coverage. Procurement patterns in foodservice channels versus retail shelves drive fundamentally different specification requirements for texture stability and portion formats.
Product Type:
Buyers select fruit jelly varieties based on application-specific viscosity requirements and clean-label positioning relative to breakfast, baking, or confectionery end uses.
- Mixed Fruit Jelly:Formulated from blended juice concentrates to achieve complex flavor layering with 65-70 Brix solids content. German and US foodservice providers specify this category for dessert plating and pastry laminating where single-fruit profiles prove too narrow. Demand concentrates in institutional bakery procurement channels seeking operational flexibility through one SKU serving multiple applications.
- Berry Blend Jelly:Combines strawberry, raspberry, and blackberry pulps with high-methoxyl pectin for enhanced gel strength at reduced sugar levels. Japan's convenience store bakery networks and California premium private-label lines are expanding shelf space for this segment driven by antioxidant positioning and visual appeal in transparent packaging. The category captures the steepest expansion trajectory among all product types.
- Apple Jelly:Single-fruit formulation based on clarified apple juice with standardized pectin content for spreadable consistency at room temperature.
- Grape Jelly:Concord or Thompson seedless grape-based preparation with characteristic purple coloration and distinct aromatic profile.
Mixed fruit jelly leads on scale through foodservice volume contracts; berry blend jelly leads on momentum through premium retail expansion.
Packaging Type:
Cost-to-weight ratios and breakage risk tolerance determine format selection across retail, foodservice, and institutional procurement contexts.
- Pouches:Multi-layer flexible laminates with spout or tear-notch configurations enabling precise portion dispensing and reduced shipping weight. Japan's on-the-go retail channels and US college foodservice operations are displacing rigid formats where breakage costs and disposal logistics burden operational efficiency. The format gains share fastest in channels prioritizing convenience over shelf presence.
- Glass Jars:Traditional cylindrical or hexagonal containers with metal lug closures providing premium aesthetic and chemical inertness for acidic pectin formulations. French and Swiss retailers maintain glass dominance for gift-oriented and organic-certified lines where packaging substantiates price positioning. REACH regulation extensions on food-contact materials are accelerating migration testing costs for European manufacturers qualifying alternative coatings.
- Plastic Cups:Polypropylene or PET single-serve containers with peelable foil lids for portion-controlled institutional distribution.
- Tins:Metal canisters with rolled seams for extended shelf stability in ambient distribution environments.
Glass jars dominate absolute volume through established retail infrastructure; pouches climb the fastest as foodservice procurement bypasses traditional wholesale intermediaries.
Distribution Channel:
Channel selection reflects buyer search behavior ranging from planned stock-up purchasing to immediate need fulfillment and curated discovery.
- Online Retail:Direct-to-consumer platforms and third-party marketplaces enabling subscription replenishment and variety bundling. US coastal metro areas and German urban centers show concentration of reduced-sugar and organic-certified purchases through this channel, driven by detailed nutritional disclosure and review aggregation that physical retail cannot replicate.
- Specialty Shops:Gourmet food retailers and farm-direct outlets curating artisanal and small-batch productions with provenance documentation. Japan's depachika basement food halls and New York specialty grocers command premium shelf placement fees that filter for authentic formulation stories and regional fruit sourcing.
- Supermarkets:Mass-market retail with standardized planogram placement and promotional calendar dependency.
- Convenience Stores:High-velocity urban outlets prioritizing grab-and-go formats and impulse purchase positioning.
Supermarkets anchor absolute volume through promotional scale; online retail expands most quickly through subscription mechanics and clean-label search filtering.
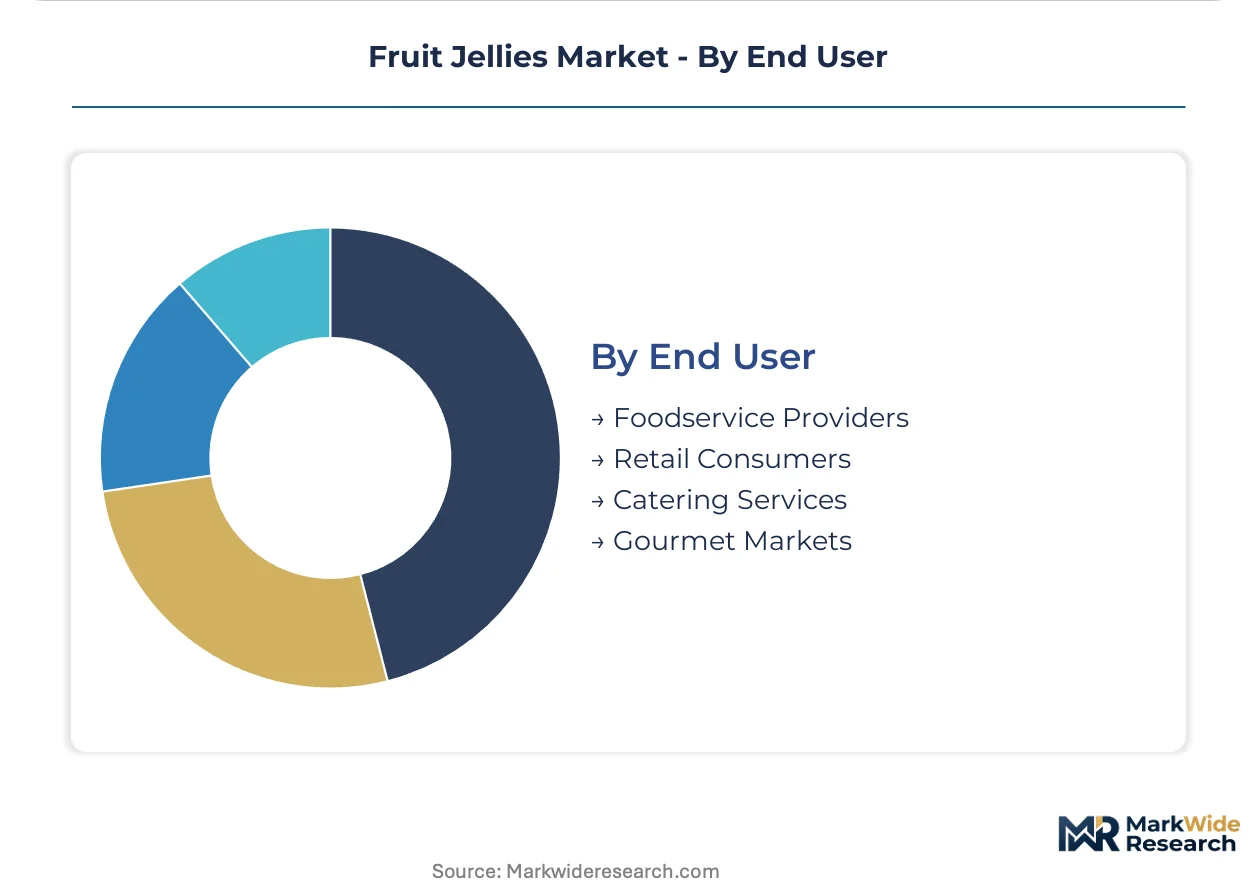
End User:
Operational requirements for texture consistency, portion precision, and supply reliability segment demand across professional and consumer contexts.
- Foodservice Providers:Bakery chains, hotel groups, and institutional caterers requiring technical-grade specifications for thermal stability and batch-to-batch consistency. US regional restaurant groups and Japan's convenience store networks are building specification-direct relationships with co-manufacturers, compressing traditional wholesale margins and demanding dual commercial organizations from suppliers.
- Gourmet Markets:Premium retailers and curated food halls selecting artisanal productions with documented provenance and limited-batch positioning. California and New York metro areas concentrate procurement of house-brand gourmet lines, creating white space for co-manufacturing partnerships with established texture science capabilities.
- Retail Consumers:Household purchasers selecting through supermarket, online, or specialty channels for home consumption.
- Catering Services:Event and institutional food providers requiring bulk formats and reliable delivery scheduling.
Foodservice providers dominate procurement volume through contract consolidation; gourmet markets gain share fastest through premium private-label expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's artisanal procurement networks contrast with Japan's convenience store bakery integration, illustrating divergent premiumization pathways across developed markets. Demand clusters in the United States, Germany, and Japan reflect distinct regulatory pressures and channel structures.
United States
Premium private-label expansion in California and New York metro areas drives gourmet line shelf space growth. FDA sugar-reduction guidance accelerates reformulation timelines for reduced-sugar variants. Co-manufacturing partnerships concentrate in the Northeast corridor to serve retailer house-brand programs.
Germany
Foodservice providers and institutional bakeries expand specification-direct procurement of mixed fruit jellies for dessert applications. EFSA added sugars guidance mandates clean-label reformulations using high-methoxyl pectin alternatives. Manufacturing clusters in Bavaria and North Rhine-Westphalia leverage European distribution infrastructure for standard-tier production.
Japan
Convenience store bakery networks build proprietary flavor relationships with co-manufacturers for berry blend jelly SKUs. METI standards influence packaging migration testing for pouch laminates. Tokyo and Osaka metropolitan areas anchor depachika procurement of artisanal productions with documented provenance.
India
Export-oriented producers navigate BIS certification and FSSAI labeling mandates for retail channel access. FSSAI nutritional disclosure requirements extend certification timelines beyond typical product launch windows. Maharashtra and Gujarat processing hubs face pectin sourcing constraints amid domestic formulation scaling.
China
Dual carbon goals accelerate renewable energy adoption in processing facilities for export-qualified production. SAMR food-contact material regulations shape jar coating validation requirements. Yangtze River Delta manufacturing clusters optimize vacuum evaporation systems for reduced-heat processing compliance.
Fruit Jellies Market Competitive Landscape
Top-tier vendors anchor premium artisanal positioning, while mid-scale producers compete on reformulation agility and regional distribution density. The market exhibits tiered concentration with European manufacturers sustaining economies in standard-tier production through integrated supply chains. Strategic archetypes include flavor innovation specialists, seasonal gift-oriented producers, and private-label co-manufacturers. Dominant competitive moves encompass geographic footprint expansion through manufacturing partnerships and portfolio diversification into reduced-sugar clean-label lines.
Within the European manufacturing tier, HARIBO GmbH and Co. KG and Perfetti van Melle occupy positions reflecting distinct competitive vectors—HARIBO leveraging German production infrastructure for scale efficiency, Perfetti van Melle exemplifying flavor innovation pipeline differentiation. Ferrara Candy Company represents the seasonal and gift-oriented archetype, anchoring higher-margin positioning through controlled distribution relationships. These three entities collectively illustrate how formulation specialization, geographic manufacturing strategy, and channel focus segment competitive positioning across the value chain.
| Leading Market Players |
|---|
| HARIBO GmbH and Co. KG |
| Perfetti van Melle |
| Ferrara Candy Company |
| Mars, Incorporated |
| Jelly Belly Candy Company |
| Cloetta AB |
| Just Born Inc. |
| Mondelez International |
| Impact Confections |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap producers across Portugal and Brazil anchor high-grade pectin supply, translating citrus peel processing dominance into pricing discipline for texture-critical formulations. Their concentrated ownership structure limits spot-market liquidity, forcing reformulation-driven buyers into long-term offtake negotiations that insulate input costs from commodity volatility.
Pricing Analysis
Bundled technical service contracts separate premium artisanal producers from unbundled commodity suppliers competing on per-kilogram spot rates. Three-tier pricing structure across premium, standard, and economy levels stratifies by pectin grade certification and provenance documentation, with California gourmet markets least sensitive and institutional foodservice most responsive to volume discounts. Cost compression in standard-tier SKUs is intensifying because Portuguese citrus processors are consolidating tolling agreements. Private-label co-manufacturers face the sharpest margin pressure as retailer house-brand programs demand price parity with branded lines.
Supply Chain Analysis
Single-source vulnerability sits with Portuguese and Brazilian citrus peel processors controlling seventy percent of global high-methoxyl pectin output. Manufacturing draws from German flavor houses, Indian fruit concentrate packers, and Chinese flexible packaging converters, creating tariff exposure at multiple nodes. Distribution runs through foodservice broadline distributors in the United States, depachika procurement networks in Japan, and specialty importers in German urban centers, each demanding divergent technical specifications and lot-traceability protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement shifts toward reduced-sugar clean-label specifications reward reformulation capabilities over scale economies. Berry blend jelly's premium retail expansion signals the demand trajectory incumbents must capture and entrants must intercept.
For Market Incumbents: Deepen backward integration into Portuguese pectin tolling arrangements to defend margin position against citrus supply concentration. Invest in vacuum evaporation retrofitting at Bavaria and North Rhine-Westphalia facilities to meet EFSA thermal-processing guidance while expanding co-manufacturing partnerships for California and New York metro private-label programs. For New Entrants and Emerging Players: High-pressure processing equipment leasing models offer a technology-first wedge against capital-constrained mid-tier competitors. Target Japan's convenience store bakery networks through specification-direct relationships, leveraging pouch packaging innovation and METI-compliant migration testing to bypass established wholesale intermediaries. For Investors and Strategic Acquirers: Valuations sit cheapest among reformulation-capable co-manufacturers lacking branded distribution but possessing FDA and EFSA compliance infrastructure. Five-to-ten-year viability hinges on clean-label pipeline depth; monitor BIS certification timeline compression in India as the inflection signal for export-ready production capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Pipeline | EFSA sugar-reduction guidance mandates high-methoxyl pectin alternatives that retain texture stability. |
| Pouch Packaging Technology Expansion | METI migration testing compliance opens Japan's convenience store channels to flexible format suppliers. |
| Foodservice Direct Procurement Relationships | Bypassing broadline distributors captures margin compression from Japan's bakery network consolidation. |
| Portuguese Pectin Supply Integration | Tolling agreements with citrus peel processors hedge against seventy percent supply concentration risk. |
| US Premium Private-Label Co-Manufacturing | California and New York metro retailer house-brand programs reward proven texture science capabilities. |
Research Methodology
Bottom-up foodservice procurement modeling reconciled against top-down pectin supply tracking forms the analytical core of this study. Primary interviews with fruit jelly brand managers, category buyers at German and US retailers, formulation technologists at Portuguese citrus processors, and foodservice procurement directors at Japanese convenience store operators combined with secondary validation from FDA standards filings, EFSA guidance documents, BIS certification registries, and FSSAI labeling mandates. Trade data from customs records and specialized confectionery industry publications provided cross-reference points for volume triangulation.
Input-output matrices mapped fruit juice concentrate availability, pectin grade specifications, and packaging format adoption across product type, packaging type, distribution channel, and end user dimensions over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption indicators and regulatory compliance cost trajectories. Forecast inputs incorporated EFSA reformulation timeline assumptions, BIS certification backlog estimates, and METI packaging regulation phase-in schedules.
The model holds under stable citrus peel supply and gradual sugar-tax implementation; deviation in Portuguese processor consolidation or abrupt FDA standards revision would shift trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
White Chocolate Market
Confectionery
Liquorice Shellac Market
Confectionery
Low-Calorie Jelly Market
Confectionery
Global Compound Chocolate Market
Confectionery
Italy Chocolate Market
Confectionery
Diet Candy Market
Confectionery
Global Sugar Free Chewing Gums Market
Confectionery
Middle-East and Africa Compound Chocolate Market
Confectionery
Europe Confectionery Market
Confectionery
China Chocolate Market
Confectionery
North America Sugar-Free Chewing Gum Market
Confectionery
Sugar-Free Gumballs Market
Confectionery
United States and Europe Macarons Market
Confectionery
United Arab Emirates Sugar Confectionery Market
Confectionery
India Industrial Chocolate Market
Confectionery
Middle East and Africa Chocolate Market