
 Confectionery Fats Market | 2026-2036
Confectionery Fats Market Size, Share, and Industry Trends Forecast 2026-2036
Confectionery Fats Market Analysis
Modular fat blending is restructuring how food manufacturers configure their confectionery ingredient portfolios, with buyers unbundling traditional all-in-one compound solutions to mix cocoa butter equivalents, shortenings, and specialty margarines in-house. Bunge Loders Croklaan leverages its European refining footprint to supply tailored fat fractions for premium chocolate makers. Cargill Incorporated anchors North American demand through integrated oilseed processing and confectionery fat formulation capabilities. AAK AB specializes in shea-based cocoa butter improvers that compete on sustainability credentials and melting profile precision.
Confectionery fats comprise refined vegetable oil blends, tropical fats, and modified lipids engineered to deliver specific melting curves, mouthfeel, and bloom resistance in finished sweets. These fats typically contain 30-60% saturated fatty acids and undergo interesterification or fractionation to mimic cocoa butter's polymorphic stability in chocolate coatings and fillings. Cocoa butter alternatives lead value contribution due to premium pricing in bean-to-bar chocolate, while compound fats represent the fastest-growing volume category as Asian food manufacturers seek cost-stable coating solutions. The semi-solid form dominates industrial procurement because it balances storage efficiency with ready-to-use functionality in tempering and enrobing lines.
EFSA evaluates novel fat modification processes for food safety clearance, while REACH governs chemical inputs in processing aids across European confectionery fat facilities. The EU Deforestation Regulation tightens due diligence on palm and shea sourcing, compelling manufacturers to restructure supplier audits and traceability systems. Stakeholders must monitor how evolving sustainability disclosure rules intersect with cocoa butter price volatility to determine whether backward integration into tropical fat origination or partnership with certified cooperatives offers more resilient margin protection.

Market Dynamics
The EU Deforestation Regulation and F-Gas mandates are forcing confectionery fat suppliers to restructure sourcing networks, while artisanal chocolate makers accelerate specialty fat adoption to differentiate premium positioning.
Growth Catalysts
- Regulatory-driven sustainability certification:The EU Deforestation Regulation compels manufacturers to adopt certified palm and shea supply chains, redirecting procurement toward traceable tropical fat sources.
- Artisanal confectionery expansion:Premium chocolate makers absorb cocoa butter equivalents at elevated rates to achieve precise melting profiles and bloom resistance in bean-to-bar production.
- Fractionation technology maturation:Advanced lipid modification processes enable tighter control over polymorphic stability, expanding application scope for modified tropical fats in enrobing and filling systems.
Market Restraints
- Cocoa butter price volatility:Bean supply fluctuations in West Africa transmit directly to cocoa butter costs, compressing margins for manufacturers dependent on natural fat inputs.
- Upstream processing concentration:Indonesia and Malaysia control critical fractionation capacity for confectionery fat intermediates, creating geographic supply risk.
- Technical substitution limits:Cocoa butter alternatives cannot fully replicate the snap and mouthfeel of natural cocoa butter in high-end chocolate applications.
Strategic Opportunities
- Shea-based improver expansion:West African shea sourcing offers deforestation-free credentials that satisfy EU regulatory requirements while delivering competitive melting characteristics.
- Modular blending adoption:Food manufacturers unbundle traditional compound solutions to configure custom fat portfolios in-house, creating demand for discrete fat fractions.
- Clean-label confectionery channel:Specialty retailers and direct-to-consumer chocolate brands seek transparent fat sourcing that supports premium positioning.
Industry Challenges
- Traceability system implementation:The EU Deforestation Regulation demands granular supplier audits and chain-of-custody documentation that strains existing procurement infrastructure.
- Interesterification capacity constraints:Specialized processing equipment for enzymatic fat modification requires significant capital deployment and technical expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Confectionery Fats Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cocoa Butter, Shortening, Margarine, Compound Fats Application: Candies, Chocolate, Bakery, Ice Cream Form: Solid, Liquid, Semi-solid, Powdered End User: Food Manufacturers, Bakeries, Restaurants, Retailers |
| Companies Covered | Bunge Loders Croklaan, Musim Mas Holdings, Cargill Incorporated, EFKO Group, Golden Agri-Resources, AAK AB, Fuji Oil Holdings, Sime Darby Plantation, Wilmar International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Confectionery Fats Market Emerging Trajectories
Enzymatic interesterification is displacing chemical modification as the dominant fat structuring technology, while regulatory pressure on supply chain transparency accelerates digital traceability adoption across confectionery fat networks.
Enzymatic interesterification is rewriting how manufacturers achieve fat polymorphism without trans-fat generation. Premium chocolate makers in Belgium and Switzerland adopt this technology to meet clean-label demands while preserving tempering performance. The shift is compressing demand for chemically modified fats and elevating enzyme supplier influence in formulation partnerships.
REACH and the EU F-Gas Regulation tighten chemical input oversight and processing emissions standards for European confectionery fat facilities. Manufacturers face reformulation costs and equipment upgrades to maintain market access. The regulatory burden falls heaviest on mid-scale compound fat producers lacking integrated refining capabilities.
Buyer concentration among artisanal chocolate makers is shortening supplier qualification cycles and elevating sustainability documentation requirements. Specialty fat blenders displace traditional commodity distributors in premium segments. This pattern is most pronounced in German and French confectionery clusters where bean-to-bar producers command sourcing influence.
Confectionery Fats Market Segmentation
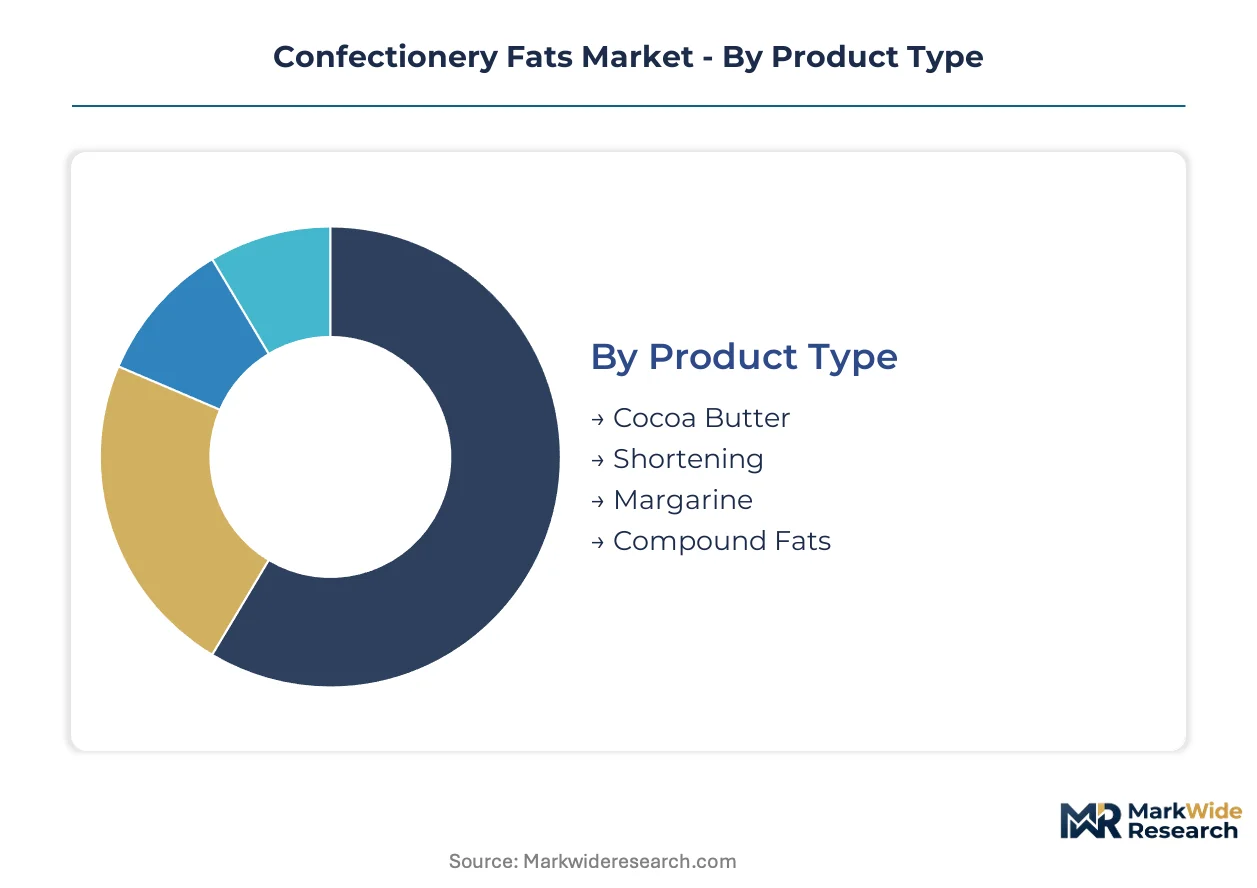
Confectionery fat buyers configure procurement around functional requirements, regulatory exposure, and processing infrastructure. Segmentation reveals which fat categories command premium positioning and where formulation flexibility creates cost advantages.
Product Type:
EFSA clearance requirements vary sharply across product categories, with enzymatically modified fats facing novel food assessments while traditional shortenings navigate standard food additive pathways.
- Cocoa Butter:Natural fat extracted from cacao beans contains specific triglyceride structures that deliver signature snap and melt. Bean-to-bar chocolate makers in Belgium and Switzerland absorb this material despite price volatility from West African supply fluctuations.
- Shortening:Hydrogenated or interesterified vegetable oil blends engineered for creaming stability and shelf life. North American bakeries and industrial cookie manufacturers deploy shortening for cost-controlled texture in laminated doughs and fillings.
- Margarine:Water-in-fat emulsion formulated for spreadability or baking performance depending on fat phase composition. European food manufacturers specify low-trans variants to meet F-Gas Regulation processing standards and clean-label positioning.
- Compound Fats:Tropical fat-based coatings that substitute for cocoa butter in enrobing applications. Asian confectionery producers in Indonesia and Malaysia drive volume expansion as cost-stable alternatives for mass-market chocolate products.
Compound fats sit at the top of the volume ranking, with cocoa butter climbing the fastest on artisanal premiumization.
Application:
End-use concentration determines margin structure, with chocolate applications absorbing specialty fat investment while candy production prioritizes cost efficiency.
- Candies:Hard-boiled sweets, toffees, and caramels require fats that control sugar crystallization and provide chew resistance. Manufacturers in Germany and France specify fractionated palm stearin for its clean flavor release and processing tolerance.
- Chocolate:Tempered coatings and molded bars demand precise polymorphic stability achieved through cocoa butter or high-grade equivalents. Premium positioning in Swiss and Belgian markets rewards shea-based improvers that satisfy EU Deforestation Regulation traceability mandates.
- Bakery:Laminated pastries, cookies, and cakes utilize shortening and margarine for aeration and structure. Industrial bakeries in the United States configure modular fat blends to balance functionality against commodity price exposure.
- Ice Cream:Fat globule size and crystallization behavior determine mouthfeel and heat shock resistance. Italian gelato producers and North American ice cream manufacturers specify specialized fat fractions for creamy texture retention.
Chocolate commands the highest value per kilogram, though bakery applications dominate absolute tonnage.
Form:
Physical state selection reflects inventory economics against processing line configuration, with semi-solid formats optimizing most tempering and enrobing operations.
- Solid:Fully hydrogenated blocks or flakes requiring melting before incorporation. Large-scale compound chocolate manufacturers in Malaysia prefer solid delivery for bulk storage efficiency and controlled batch dosing.
- Liquid:Pumpable oils used in spray applications or continuous mixing systems. Industrial bakeries and coating operations in the United States deploy liquid forms for automated dosing and reduced handling labor.
- Semi-solid:Plastic fats ready for direct tempering or creaming without preprocessing. This form dominates European confectionery procurement, balancing storage stability with immediate functionality in enrobing lines.
- Powdered:Encapsulated or spray-dried fats for dry mix incorporation and extended shelf life. Powdered formats serve specialty confectionery and nutritional applications where moisture exclusion matters.
Semi-solid forms lead industrial procurement volumes, with liquid formats gaining share fastest on automation adoption.
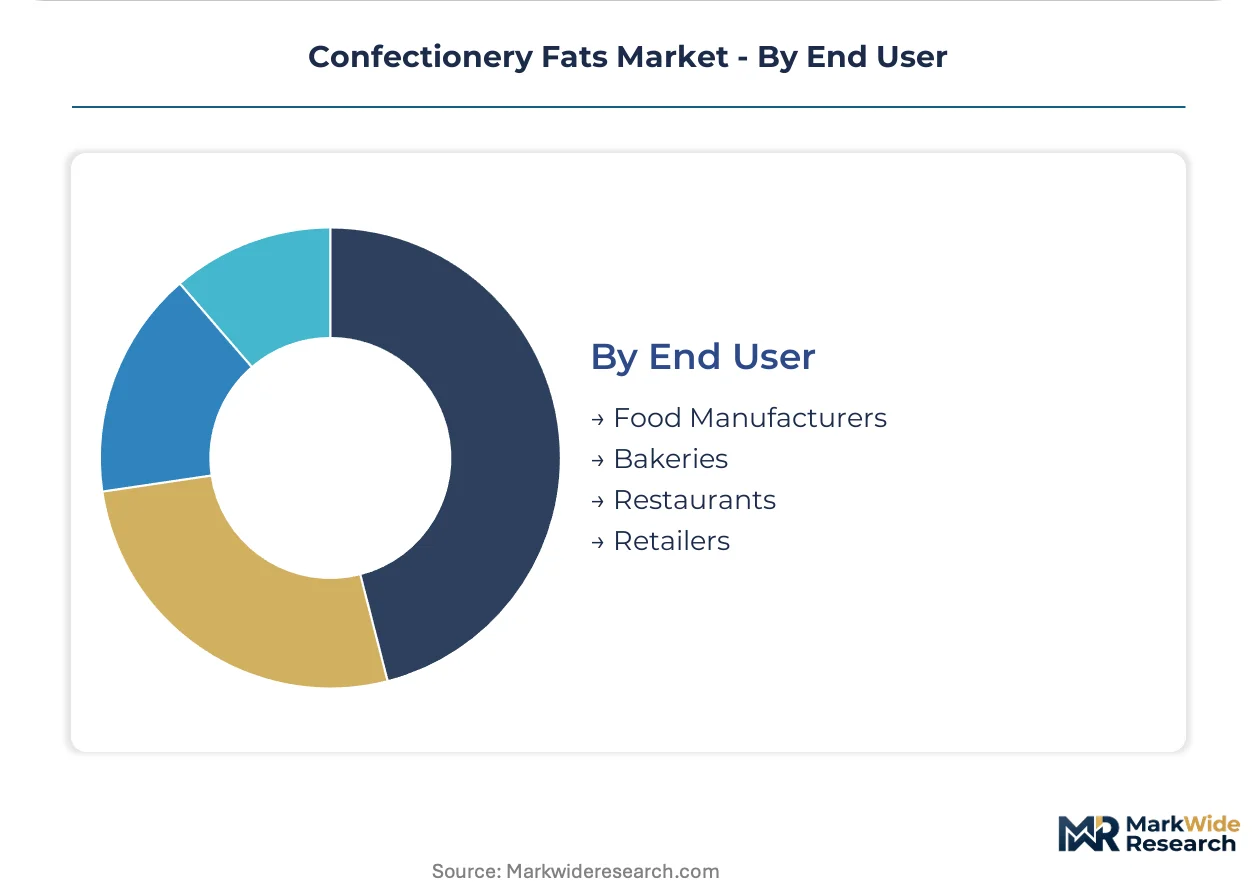
End User:
Customer scale and technical capability determine whether buyers source finished compounds or discrete fat fractions for in-house blending.
- Food Manufacturers:Industrial confectionery and bakery operations with integrated R&D capabilities. These buyers in Germany and Switzerland increasingly unbundle procurement to configure custom fat portfolios from separate cocoa butter equivalent, shortening, and margarine inputs.
- Bakeries:Mid-scale operations requiring consistent performance without extensive formulation expertise. French and Italian artisanal bakeries specify compound shortenings that simplify laminated dough production.
- Restaurants:Foodservice channels needing reliable fat performance across menu applications. This segment prioritizes cost stability and supplier reliability over specialty functionality.
- Retailers:Private-label confectionery and bakery product developers. Clean-label positioning and deforestation-free sourcing credentials drive specification decisions for European retail chains.
Food manufacturers absorb the highest absolute volume, with retailers expanding specifications fastest on sustainability transparency demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European chocolate makers pioneered modern confectionery fat formulation in Belgium and Switzerland during the early twentieth century, establishing the technical standards that now govern global specialty fat demand. This heritage shapes today's regional procurement patterns.
Germany
Industrial bakeries and confectionery manufacturers in Cologne and Hamburg drive shortening and margarine absorption for laminated dough production. EFSA clearance requirements for novel enzymatic modifications shape R&D investment patterns. The Lower Saxony cluster hosts fractionation facilities supplying cocoa butter equivalents to bean-to-bar chocolate makers.
Indonesia
Palm oil fractionation capacity concentrates in Sumatra and Java, serving Asian compound chocolate manufacturers with cost-stable coating solutions. The country's national food safety regulator enforces halal certification standards that govern export eligibility. Surabaya-based refiners supply semi-solid fat blends to regional enrobing operations.
United States
Integrated oilseed processors in the Midwest anchor North American demand for confectionery fat formulations. FDA labeling requirements for trans-fat content drive interesterification technology adoption. Chicago-area food manufacturers configure modular fat portfolios blending discrete cocoa butter equivalents with commodity shortenings.
Malaysia
Upstream processing capacity for confectionery fat intermediates clusters in Port Klang and Pasir Gudang, creating geographic supply concentration. The country's halal certification authority governs export documentation for palm-derived fractions. Johor-based facilities supply compound fat bases to Southeast Asian coating manufacturers.
Switzerland
Premium chocolate makers in Zurich and Geneva absorb shea-based cocoa butter improvers at elevated rates for precise tempering performance. Swissmedic oversees food contact material standards for processing equipment. The Lake Geneva corridor hosts specialty fat blenders serving artisanal bean-to-bar producers.
Confectionery Fats Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification and formulation sophistication, with deforestation-free supply chains commanding price premiums. The vendor base spans integrated agribusiness conglomerates, tropical fat specialists, and regional refiners with fractionation expertise. Three archetypes dominate: upstream-integrated palm processors, shea-specialized improver suppliers, and modular fractionation service providers. Competitive moves center on sustainability certification acquisition and enzymatic processing capacity deployment.
Within the integrated processor tier, Bunge Loders Croklaan and Cargill Incorporated exemplify multinational agribusiness structures with European and North American refining footprints. AAK AB occupies a position among specialty fat specialists focused on shea-derived formulations. These three entities represent contrasting strategic postures: geographic diversification versus raw material specialization versus sustainability credentialing.
| Leading Market Players |
|---|
| Bunge Loders Croklaan |
| Musim Mas Holdings |
| Cargill Incorporated |
| EFKO Group |
| Golden Agri-Resources |
| AAK AB |
| Fuji Oil Holdings |
| Sime Darby Plantation |
| Wilmar International |
| Others |
Supply Flow & Price Mechanics
Fractionation technology specialists in Belgium and Switzerland command wage premiums that compress margin spreads between artisanal cocoa butter equivalents and mass-market compound fats. Labor-cost differentials between European enzymatic processing hubs and Southeast Asian chemical modification facilities drive three-tier pricing stratification across certification grades.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs confectionery fat procurement, with EU Deforestation Regulation compliance and enzymatic processing capability serving as the primary price differentiation drivers. Pricing pressure stems from cocoa butter price volatility transmitting from West African bean supply fluctuations, compressing margins for natural fat-dependent tiers. Artisanal chocolate makers in Switzerland exhibit lowest price sensitivity due to premium positioning requirements, while Asian compound chocolate manufacturers demonstrate highest sensitivity to cost-stable coating alternatives.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian and Malaysian palm oil fractionation capacity, which feeds from crude palm oil, shea nuts from West Africa, and coconut oil from the Philippines. The supply chain draws from tropical fat origination zones with limited geographic diversification, creating tariff exposure from EU regulatory restrictions on deforestation-linked imports. Distribution runs through integrated refiners with in-house fractionation capabilities serving regional enrobing and tempering operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Deforestation Regulation operates as a regulatory compounder, with compliance deadlines accelerating certified supply chain investments and redirecting procurement toward traceable shea and palm sources.
For Market Incumbents:Acquire enzymatic interesterification capacity to defend against chemical modification substitution threats from Southeast Asian compound fat producers. Secure backward integration into West African shea cooperatives to lock deforestation-free certification supply and protect margin position against bean-to-bar chocolate maker procurement concentration.
For New Entrants and Emerging Players:Enter via modular fat fraction supply to German and Swiss food manufacturers unbundling traditional compound solutions. Target clean-label confectionery channels in European specialty retail where sustainability documentation requirements exceed incumbent certification capabilities. Deploy direct technical sales teams to bean-to-bar producers seeking custom melting profile formulations.
For Investors and Strategic Acquirers:Integrated agribusiness conglomerates with tropical fat origination assets are the most active acquirer in this space, consolidating fractionation capacity to capture premium-mid-economy pricing spreads. Long-term viability hinges on enzymatic processing technology ownership and EU regulatory compliance infrastructure. Watch shea supply chain certification penetration rates as the inflection indicator for sustainable premium tier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Processing Capacity Expansion | Belgian and Swiss facilities deploy enzymatic interesterification to meet EFSA novel food clearance requirements. |
| Shea Supply Chain Certification | West African cooperative partnerships satisfy EU Deforestation Regulation traceability mandates for premium chocolate applications. |
| Modular Fat Fraction Development | German food manufacturers configure custom portfolios blending discrete cocoa butter equivalents with commodity shortenings. |
| Halal Certification Infrastructure | Malaysian and Indonesian refiners secure JAKIM and MUI approvals to maintain export eligibility across Muslim-majority markets. |
| Clean-Label Channel Partnerships | Specialty retailers in France and Switzerland demand granular supplier audits supporting bean-to-bar brand positioning. |
Methodological Framework
Multiple input streams — primary interviews with fractionation plant managers, confectionery procurement leads, and regulatory affairs directors; secondary validation through EFSA novel food assessments, EU Deforestation Regulation implementation guidance, and customs trade data — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned enzymatic technology suppliers, shea cooperative representatives, and chocolate maker R&D formulation teams. Secondary sources included REACH chemical input registries, Malaysian Palm Oil Board production statistics, and SEC filings from integrated agribusiness conglomerates.
Historical volume trajectories were cross-referenced against panel input from procurement executives to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled encompassed product type, application, physical form, and end-user technical capability. CAGRs were derived from elasticity-adjusted demand curves incorporating cocoa butter price volatility indices and regulatory compliance cost pass-through assumptions. Industry-specific forecast inputs included enzymatic processing capacity deployment schedules and EU Deforestation Regulation supplier audit completion rates.
Inputs from primary stakeholder interviews and published regulatory guidance were available through the study window; gaps in real-time shea supply chain traceability data introduce uncertainty bands around sustainable premium tier penetration assumptions. Forecasts reflect documented elasticity parameters and substitution threshold estimates. Cocoa bean supply disruptions in West Africa or accelerated EU regulatory enforcement could revise trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Cocoa and Chocolate Market
Confectionery
Premium Chocolate Market
Confectionery
Boiled-Cooked Icing Market
Confectionery
Asia Pacific Sugar Confectionery Market
Confectionery
Chocolate Inclusions and Decorations Market
Confectionery
Citrus Gummies Market
Confectionery
Sugar-Free Chocolate Market
Confectionery
Vegan Candies Market
Confectionery
Xylitol Lollipops Market
Confectionery
United Arab Emirates Chocolate Market
Confectionery
North America Premium Chocolate Market
Confectionery
Asia-Pacific Sugar Free Chewing Gum Market
Confectionery
South America Compound Chocolate Market
Confectionery
Europe Caramel Chocolate Market
Confectionery
Chocolate Flavors Market
Confectionery
Global Chocolate Sprinkles Market