
 United Arab Emirates Chocolate Market | 2026-2036
United Arab Emirates Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Chocolate Market Analytics
Expatriate culinary talent pools is redrawing production capabilities across the Emirates. Mondelez International leverages its global supply infrastructure to secure shelf space in major retail chains. Patchi anchors the premium gifting segment through distinctive Lebanese-origin formulations and regional brand equity. Al Nassma specializes in camel-milk chocolate, carving a defensible niche in halal-adjacent luxury confections.
Chocolate comprises cocoa solids, cocoa butter, sugar, and emulsifiers formed through conching, tempering, and molding processes to achieve defined viscosity, snap, and mouthfeel parameters. The product serves confectionery, premium gifting, and foodservice decoration applications across commercial and consumer channels. Milk chocolate dominates volume throughput in supermarket and convenience store tiers, while dark chocolate commands margin premiums in specialty retail and health-positioned assortments. Gift packs concentrate value capture during Eid and Ramadan seasonal peaks, with packaging innovation driving per-unit economics.
MOHAP enforces food safety standards and halal certification protocols that govern ingredient sourcing, labeling, and import clearance for all chocolate products entering UAE commerce. The Emirates Authority for Standardization and Metrology (ESMA) mandates product composition disclosures and nutritional labeling aligned with Gulf Standardization Organization frameworks. Stakeholders must monitor evolving sugar taxation discussions and single-use packaging regulations that could reshape formulation and material choices.
Market Dynamics
MOHAP halal certification protocols and ESMA nutritional labeling mandates are forcing reformulation across all import and domestic production channels, compressing time-to-market for new product introductions.
Growth Catalysts
- ESMA Composition Standards:Mandatory Gulf Standardization Organization labeling alignment creates transparent ingredient disclosure that builds consumer trust and reduces counterfeit infiltration.
- Camel Milk Supply Chains:Localized dairy sourcing from Al Ain and Dubai camel farms reduces import dependency and unlocks premium positioning for heritage-positioned confections.
- Eid and Ramadan Gifting Cycles:Seasonal retail peaks in Dubai Mall and Yas Mall corridors concentrate revenue capture through limited-edition packaging and corporate bulk procurement.
Market Restraints
- Cocoa Butter Price Volatility:West African supply disruptions and currency fluctuations in Côte d'Ivoire and Ghana import channels compress margin predictability for local processors.
- Single-Origin Supply Concentration:European and Malaysian cocoa processors dominate intermediate ingredient flows, creating bottleneck risk for Emirates-based manufacturers without backward integration.
- Sugar Taxation Discussions:Ministry of Finance deliberations on sweetened-product levies introduce formulation uncertainty that delays R&D investment cycles.
Strategic Opportunities
- Sharjah and Northern Emirates Penetration:Underdeveloped retail infrastructure in Ajman, Ras Al Khaimah, and Fujairah creates first-mover advantage for mall-based flagship stores.
- Hotel and Airline Catering Channels:Emirates Airlines and Jumeirah Group procurement contracts offer volume scale for halal-certified premium assortments with customized packaging.
- Biodegradable Packaging Mandates:Dubai Municipality single-use plastic restrictions accelerate demand for compostable wrappers and molded pulp gift boxes.
Industry Challenges
- Confectionery Technologist Scarcity:Limited UAE-based training programs in tempering, conching, and viscosity control force reliance on expatriate talent with European or Lebanese credentials.
- Halal Certification Timelines:MOHAP audit backlogs and ingredient traceability documentation extend product launch cycles by four to eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Chocolate Market |
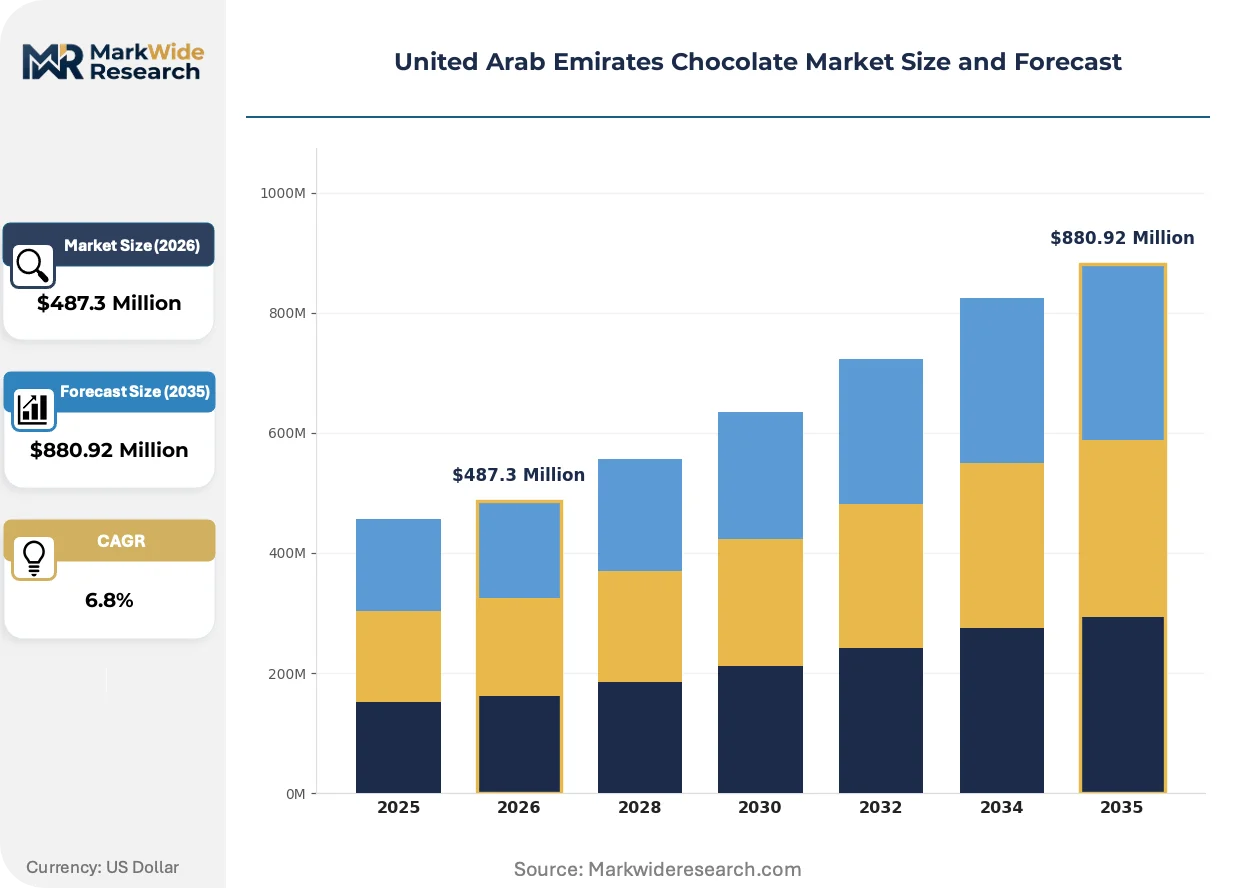
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate Packaging Type: Bars, Boxes, Gift Packs, Sachets Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Stores Customer Type: Adults, Children, Gifting, Impulse Buyers |
| Companies Covered | Mondelez International, Godiva, Nestlé, Al Nassma, Patchi, Mars, Lindt & Sprüngli, Ghirardelli, Ferrero, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Chocolate Market Evolving Landscape
Ingredient provenance transparency and portion-format downsizing are compressing traditional mass-market positioning while elevating craft and single-origin narratives across Dubai's retail corridors.
Bean-to-bar processing equipment is miniaturizing. Artisanal producers in Al Quoz industrial zone adopt compact roasters and winnowers that reduce minimum viable batch sizes from metric tons to fifty-kilogram runs. Boutique hotels and specialty grocers in Jumeirah and Downtown Dubai now source from these micro-producers, fragmenting procurement away from multinational distributors.
MOHAP tightened contaminant thresholds for heavy metals and pesticide residues in cocoa imports during 2024. This regulatory compression forces suppliers to redirect sourcing toward certified organic cooperatives in Latin America and Southeast Asia. Premium dark chocolate SKUs bear the highest compliance burden, with reformulation costs passed through to corporate gifting segments.
Corporate procurement teams now unbundle seasonal gifting from year-long confectionery contracts. Abu Dhabi sovereign wealth fund portfolio companies and Dubai-based family offices negotiate spot purchases for Ramadan assortments rather than committing to annual volumes. This demand fragmentation pressures manufacturers to maintain excess finishing capacity for compressed fulfillment windows.
United Arab Emirates Chocolate Market Segmentation
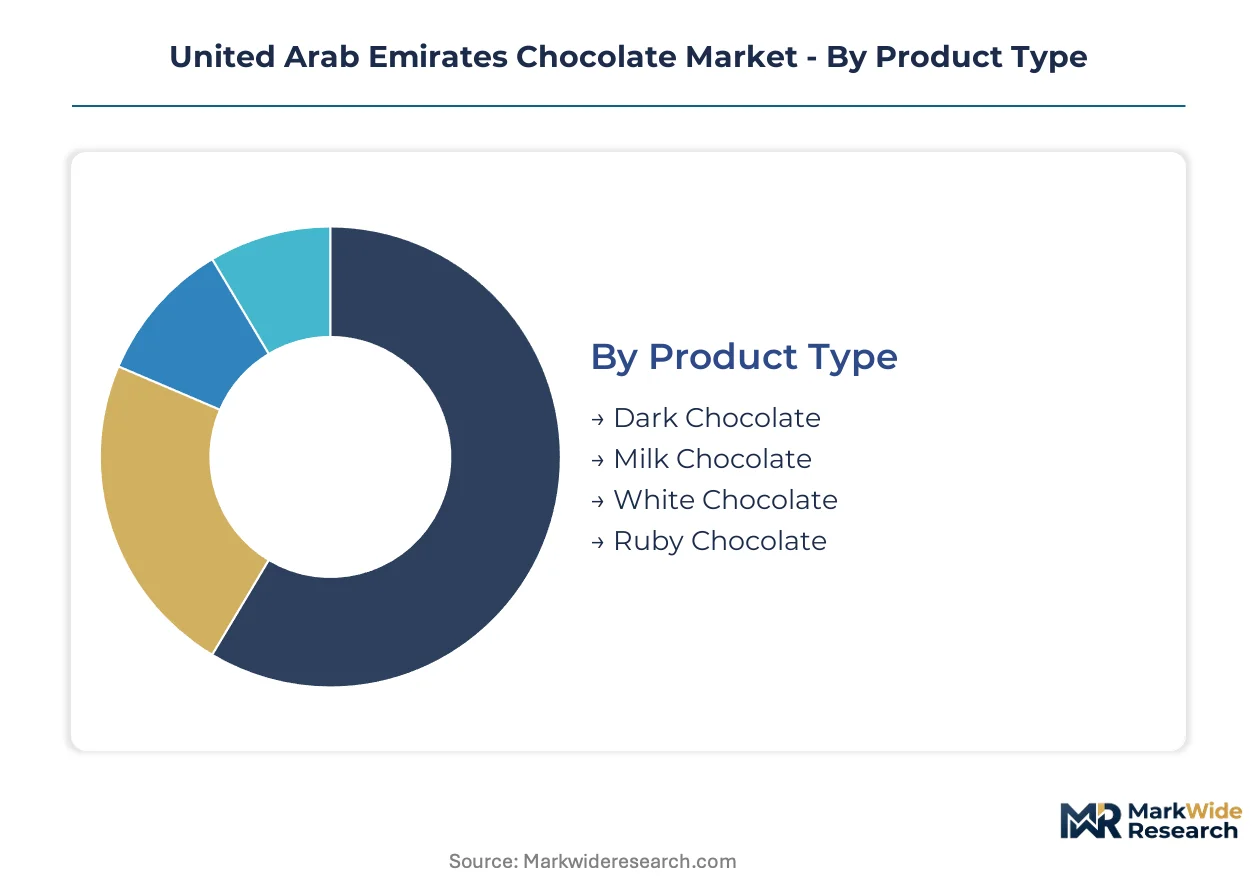
Segmentation in the UAE chocolate market reveals distinct procurement patterns between domestic consumption corridors and export-oriented premium gifting channels. Manufacturers calibrate formulation, packaging, and certification strategies differently across each dimension to capture value in Dubai's luxury retail clusters versus Sharjah's mass-market penetration.
Product Type:
Domestic production concentrates on milk chocolate variants leveraging local camel milk supply chains, while dark and ruby chocolate segments depend almost entirely on imported cocoa mass and European processing intermediates.
- Dark Chocolate:High cocoa solid content formulations command margin premiums in Jumeirah and Downtown Dubai specialty retail. Health-positioned assortments with reduced sugar profiles concentrate demand among Abu Dhabi corporate gifting buyers seeking ESMA-compliant nutritional transparency.
- Milk Chocolate:Standard emulsifier-sugar-cocoa butter matrices dominate volume throughput in Carrefour and Lulu hypermarket tiers. Local processors blend Ghanaian cocoa powder with Al Ain dairy solids to satisfy MOHAP halal certification requirements for domestic shelf placement.
- White Chocolate:Cocoa butter-dominant formulations without cocoa solids attract premium positioning in hotel minibar and airline catering channels.
- Ruby Chocolate:Ruby cocoa bean-derived pink formulations from Barry Callebaut and limited regional licensees occupy niche gifting assortments in Dubai Mall flagship locations.
Milk chocolate holds the largest share; momentum sits with dark chocolate as ESMA labeling mandates elevate cocoa percentage transparency.
Packaging Type:
Packaging economics stratify sharply between impulse formats optimized for convenience store velocity and gift formats engineered for Ramadan seasonal compression.
- Bars:Standard molded formats with foil-and-paper wrapping dominate unit economics in petrol station and supermarket checkout tiers. Dubai Municipality biodegradable packaging mandates are accelerating compostable wrapper trials among local contract manufacturers.
- Boxes:Rigid carton constructions with molded pulp inserts concentrate value capture in corporate procurement cycles. Abu Dhabi sovereign wealth portfolio companies negotiate spot purchases for Eid assortments with customized foil stamping.
- Gift Packs:Seasonal limited-edition configurations with regional geometric patterns command per-unit premiums three to four times standard bar equivalents.
- Sachets:Single-serve flow-wrap formats penetrate airline catering and hotel welcome amenities through Emirates Airlines and Jumeirah Group procurement contracts.
Boxes hold the largest share; sachets are climbing the fastest as hospitality channels recover post-pandemic procurement volumes.
Distribution Channel:
Channel control determines margin retention, with multinational conglomerates dominating supermarket shelf space while artisanal producers fragment toward specialty retail and direct-to-hotel supply.
- Supermarkets:Carrefour, Lulu, and Union Coop chains enforce slotting fee structures that favor Mondelez and Mars volume commitments. MOHAP import clearance documentation requirements create compliance barriers for smaller international entrants.
- Online Retailers:Noon and Amazon.ae fulfillment centers concentrate last-mile delivery for Ramadan surge periods. Temperature-controlled logistics partnerships with Aramex and Emirates Post enable premium chocolate shipment integrity.
- Convenience Stores:ENOC and ADNOC petrol station networks optimize impulse placement for single-bar formats. Shelf rotation velocity exceeds supermarket tiers by forty to sixty percent for standard milk chocolate SKUs.
- Specialty Stores:Boutique chocolatiers in Al Quoz industrial zone and Mall of the Emirates curate bean-to-bar assortments. Patchi and Mirzam flagship locations capture tourist and high-net-worth resident procurement with Lebanese-origin and single-origin narratives.
Supermarkets hold the largest share; specialty stores are gaining share fastest as Dubai's culinary tourism positioning elevates craft chocolate visibility.
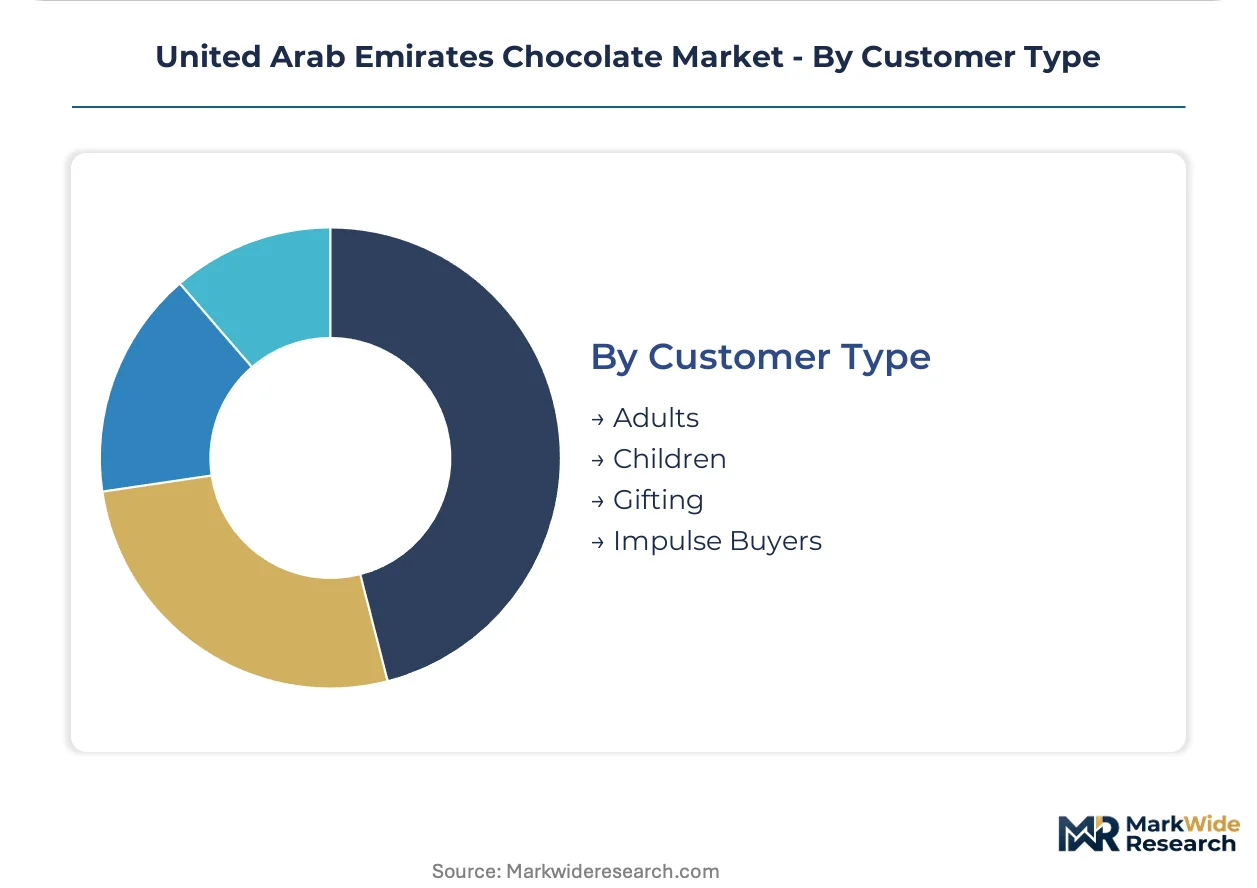
Customer Type:
Procurement behavior diverges between programmatic household replenishment and event-driven gifting compression that concentrates revenue in narrow seasonal windows.
- Adults:Health-conscious formulations with elevated cocoa percentages and reduced sugar profiles attract thirty-five to fifty-five demographic segments in Marina and JLT residential clusters. Dark chocolate consumption correlates with fitness and wellness positioning.
- Children:Sugar-dominant milk chocolate formats with licensed character packaging concentrate demand in back-to-school and Eid al-Fitr seasonal peaks. Parental procurement prioritizes ESMA nutritional labeling transparency.
- Gifting:Corporate and interpersonal gift procurement drives seventy percent of annual premium chocolate revenue in compressed Ramadan and Eid windows. Customized packaging and halal certification documentation satisfy MOHAP requirements for government and banking sector recipients.
- Impulse Buyers:Checkout-adjacent placement in convenience and supermarket channels captures unplanned purchase behavior. Single-bar price points below fifteen dirhams optimize conversion velocity.
Gifting holds the largest share; adults are expanding most quickly as health-positioned dark chocolate displaces conventional confectionery in affluent household procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Emirates diverge sharply between Dubai's luxury gifting corridors and Sharjah's mass-market penetration, with Abu Dhabi anchoring corporate procurement cycles through sovereign wealth fund portfolio companies.
Dubai
Dubai Mall and Mall of the Emirates concentrate premium chocolate revenue through tourist-facing flagship locations and seasonal Ramadan gifting peaks. Dubai Municipality enforces single-use plastic restrictions that accelerate biodegradable packaging adoption among contract manufacturers. Al Quoz industrial zone hosts compact bean-to-bar processors supplying Jumeirah boutique hotels with fifty-kilogram micro-batches.
Abu Dhabi
Yas Mall and Marina Mall corridors capture corporate bulk procurement from banking and government sector buyers requiring MOHAP halal certification documentation. The Abu Dhabi Department of Economic Development monitors retail licensing for specialty confectionery entrants. Khalifa Industrial Zone anchors import logistics for European cocoa butter flows serving local finishing operations.
Sharjah
Mass-market milk chocolate volumes concentrate in Sharjah's Union Coop and Lulu hypermarket tiers with price-sensitive household replenishment patterns. Sharjah Chamber of Commerce and Industry facilitates SME confectionery licensing for Northern Emirates distribution reach. Industrial zones near Sharjah International Airport host regional packaging converters serving mid-tier chocolate brands.
Northern Emirates
Ajman, Ras Al Khaimah, and Fujairah present underdeveloped retail infrastructure with first-mover potential for mall-based flagship expansion beyond saturated Dubai-Abu Dhabi corridors. Federal MOHAP standards apply uniformly across all seven emirates, eliminating regulatory fragmentation. Ras Al Khaimah's expanding tourism infrastructure creates hospitality channel opportunities for halal-certified premium assortments.
United Arab Emirates Chocolate Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational conglomerates commanding supermarket shelf space through volume commitments and slotting fee structures while artisanal producers fragment toward specialty retail and direct hospitality supply. The market structures around three archetypes: global FMCG conglomerates with Gulf-wide distribution infrastructure, regional heritage brands leveraging Lebanese-origin equity, and camel-milk specialists occupying halal-adjacent luxury niches. Dominant competitive moves include portfolio diversification into seasonal gifting formats and strategic partnerships with Emirates Airlines and Jumeirah Group for hospitality channel penetration.
Within the heritage specialist tier, Patchi anchors regional brand equity through distinctive Lebanese-origin formulations and premium gifting positioning. Mondelez International occupies the scale-driven multinational tier with global supply infrastructure securing shelf space across Carrefour and Lulu chains. Al Nassma exemplifies the niche specialist archetype through camel-milk chocolate production sourcing dairy solids from Al Ain and Dubai camel farms.
| Leading Market Players |
|---|
| Mondelez International |
| Godiva |
| Nestlé |
| Al Nassma |
| Patchi |
| Mars |
| Lindt & Sprüngli |
| Ghirardelli |
| Ferrero |
| Others |
Value Network & Pricing Analysis
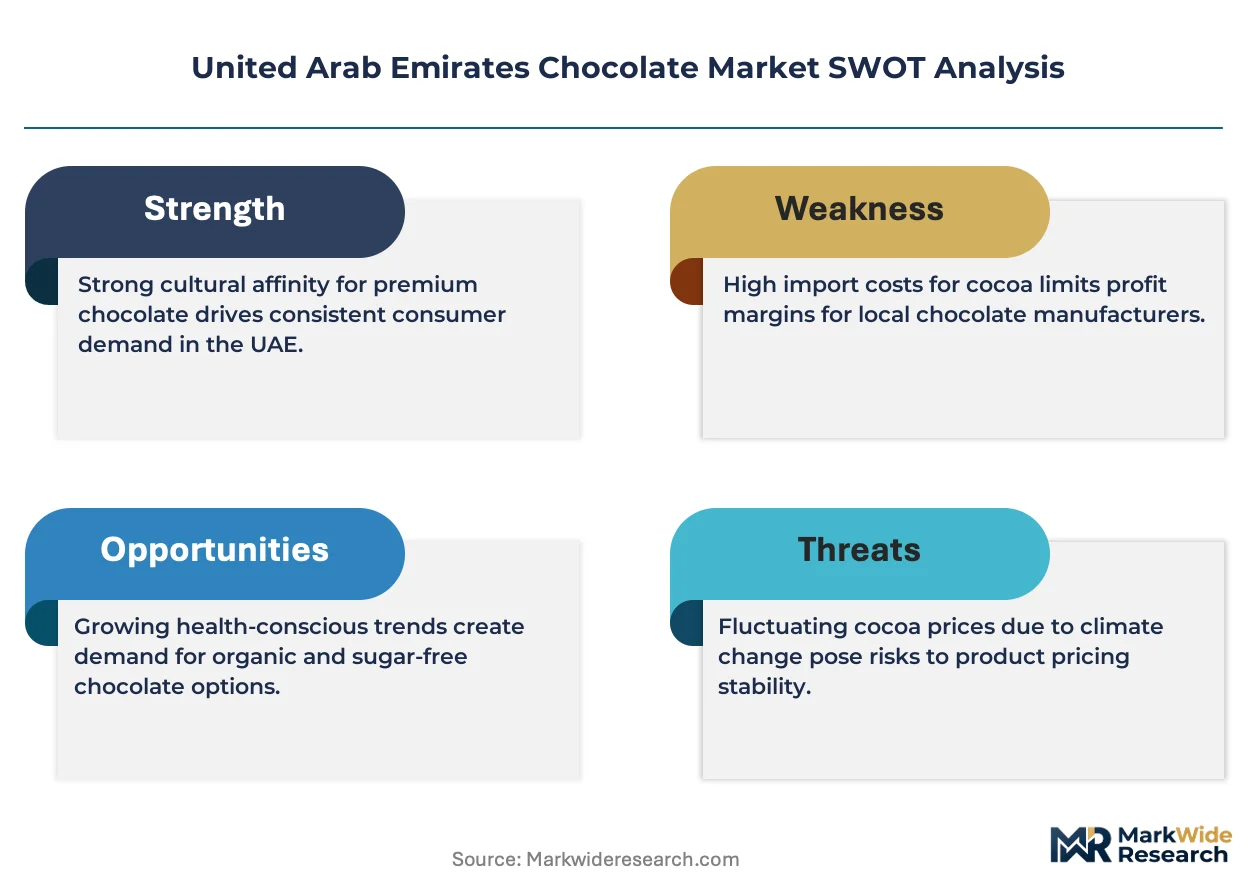
MOHAP halal certification protocols gate both supplier qualification and price differentiation across UAE chocolate tiers, forcing importers to absorb audit costs that compound with cocoa butter volatility while domestic camel-milk processors capture heritage premiums unavailable to commodity entrants.
Pricing Analysis
Long-term offtake contracts between European cocoa processors and Dubai-based finishers dominate procurement above spot purchasing, though corporate gifting buyers increasingly negotiate spot Ramadan volumes. Price differentiation rests on halal certification tier and cocoa origin transparency, with single-origin dark chocolate commanding premiums over mass-market milk variants. Cost compression in supermarket tiers is intensifying because Ghanaian cocoa powder import channels face currency headwinds. Hypermarket chains exhibit highest price sensitivity; boutique hotel procurement shows lowest.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Dubai Mall flagship retailers, while domestic processors maintain strategic stockpiles of Al Ain camel milk powder ahead of Eid surge periods. Supply draws from Côte d'Ivoire, Ghana, and European intermediate processors for cocoa mass, with Malaysian and Indonesian channels for cocoa butter. Single-source vulnerability concentrates in West African bean supply disrupted by climate volatility. Distribution runs through Khalifa Industrial Zone import logistics and Jebel Ali cold-chain corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UAE chocolate incumbents face substitution pressure from date-based confections and premium nut assortments capturing Ramadan gifting spend, requiring defensive repositioning around provenance narratives and certification moats.
For Market Incumbents: Secure MOHAP audit pre-clearance for ingredient suppliers to compress launch timelines threatened by four-to-eight-month certification backlogs. Anchor backward integration into Al Ain camel dairy networks to defend heritage-premium positioning against Lebanese-origin competitors.
For New Entrants and Emerging Players: ESMA nutritional labeling fast-tracks create entry pathways for health-positioned dark chocolate with transparent cocoa percentage disclosure. Penetrate Ras Al Khaimah and Fujairah mall corridors before infrastructure saturation. Pursue direct-to-hotel supply contracts bypassing supermarket slotting fee barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from European cocoa processors seeking Gulf distribution footholds. Five-to-ten-year viability favors specialists with captive halal certification infrastructure over commodity traders. Watch Dubai Municipality packaging mandate enforcement velocity as inflection signal for compostable wrapper adoption curves.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Pre-Clearance | MOHAP audit compression reduces new product introduction cycles by four to eight months. |
| Camel Milk Supply Integration | Al Ain dairy sourcing unlocks heritage-premium positioning unavailable to commodity importers. |
| Northern Emirates Mall Expansion | Ajman and Fujairah first-mover advantage precedes Dubai-Abu Dhabi corridor saturation. |
| Biodegradable Packaging Transition | Dubai Municipality compliance converts single-use plastic restrictions into brand differentiation. |
| Hotel and Airline Direct Supply | Emirates Airlines and Jumeirah Group contracts bypass supermarket slotting fee structures. |
Research Methodology
The analysis maps milk chocolate, dark chocolate, white chocolate, and ruby chocolate segments, each validated through confectionery technologists, MOHAP regulatory affairs officers, Carrefour category buyers, and hotel procurement managers. Primary fieldwork combined with secondary validation from ESMA labeling directives, Gulf Standardization Organization frameworks, customs import records, and MOHAP contaminant threshold publications. Bottom-up volume modeling triangulated against top-down retail audit data from Nielsen and Circana.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product type, packaging format, distribution channel, and customer archetype. CAGRs derived from regression analysis of historical import volumes and retail velocity indices. Forecast inputs incorporated cocoa butter price volatility assumptions and seasonal gifting compression patterns around Ramadan and Eid cycles.
Decision-makers should treat outputs as directional under stable MOHAP regulatory enforcement and intact West African cocoa supply; material deviation would warrant model refresh. Forecasts reflect assumptions of continued halal certification requirement stringency and sustained luxury retail corridor expansion. Revision becomes warranted when cocoa bean supply disruption crosses thresholds affecting European intermediate processor availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Europe Dark Chocolate Market
Confectionery
Cocoa and Chocolate Market
Confectionery
North America Dark Chocolate Market
Confectionery
United Arab Emirates Sugar Confectionery Market
Confectionery
North America Confectionery Market
Confectionery
Global Mochi Market
Confectionery
Germany Chocolate Market
Confectionery
Salted Caramel Products Market
Confectionery
Global Confectionery Market
Confectionery
Global Candy Market
Confectionery
Dark Chocolate Market
Confectionery
Europe Compound Chocolate Market
Confectionery
Mints Market
Confectionery
South America Confectionery Market
Confectionery
Confectionery Fillings Market
Confectionery
US Dark Chocolate Market