
 White Chocolate Market | 2026-2036
White Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
White Chocolate Market Intelligence
The adoption of natural emulsifiers and clean-label ingredients is reshaping product formulation across the white chocolate industry. This shift allows for premium positioning based on ingredient transparency. Barry Callebaut AG leverages its extensive cocoa sourcing and processing capabilities to supply specialty cocoa butters for these applications. Meanwhile, Cargill, Incorporated competes on the basis of its wide portfolio of functional ingredients, including lecithin and other plant-based emulsifiers.
White chocolate is a chocolate derivative defined by its composition of cocoa butter, sugar, and milk solids. To be legally classified as white chocolate in many jurisdictions, it must contain a minimum percentage of cocoa butter, often around 20 percent, and be devoid of non-fat cocoa solids. Within applications, confectionery and baking remain the dominant volume drivers, while use in premium beverages is a notable growth area. Product formats like chips and coatings gain share over traditional blocks, driven by demand from food manufacturers.
Product composition and labeling are strictly governed by food safety authorities. The U.S. FDA mandates specific cocoa butter and milk solid percentages, while EU directives establish similar standards of identity for products sold across the bloc. Navigating these varied international standards for cocoa butter content and approved additives remains a critical competency for producers targeting export markets.
Market Dynamics
The central structural force shaping the white chocolate market is the consumer-driven push for clean-label ingredients. This pressure, originating from the premium confectionery and artisanal bakery sectors, compels manufacturers to reformulate products for greater ingredient transparency and perceived health benefits.
Growth Catalysts
- Cocoa Butter Deodorization:Advanced processing techniques reduce unwanted flavor notes from cocoa butter, expanding white chocolate's use in applications with delicate flavor profiles like premium beverages and complex desserts.
- Japanese Dessert Innovation:A strong consumer preference in Japan for novel textures and high-quality confectionery drives development of sophisticated white chocolate products, setting trends that influence other markets.
- Artisanal Bakery Expansion:The proliferation of craft bakeries creates steady demand for versatile white chocolate formats, including chips and coatings, for use in high-end pastries and decorated goods.
Market Restraints
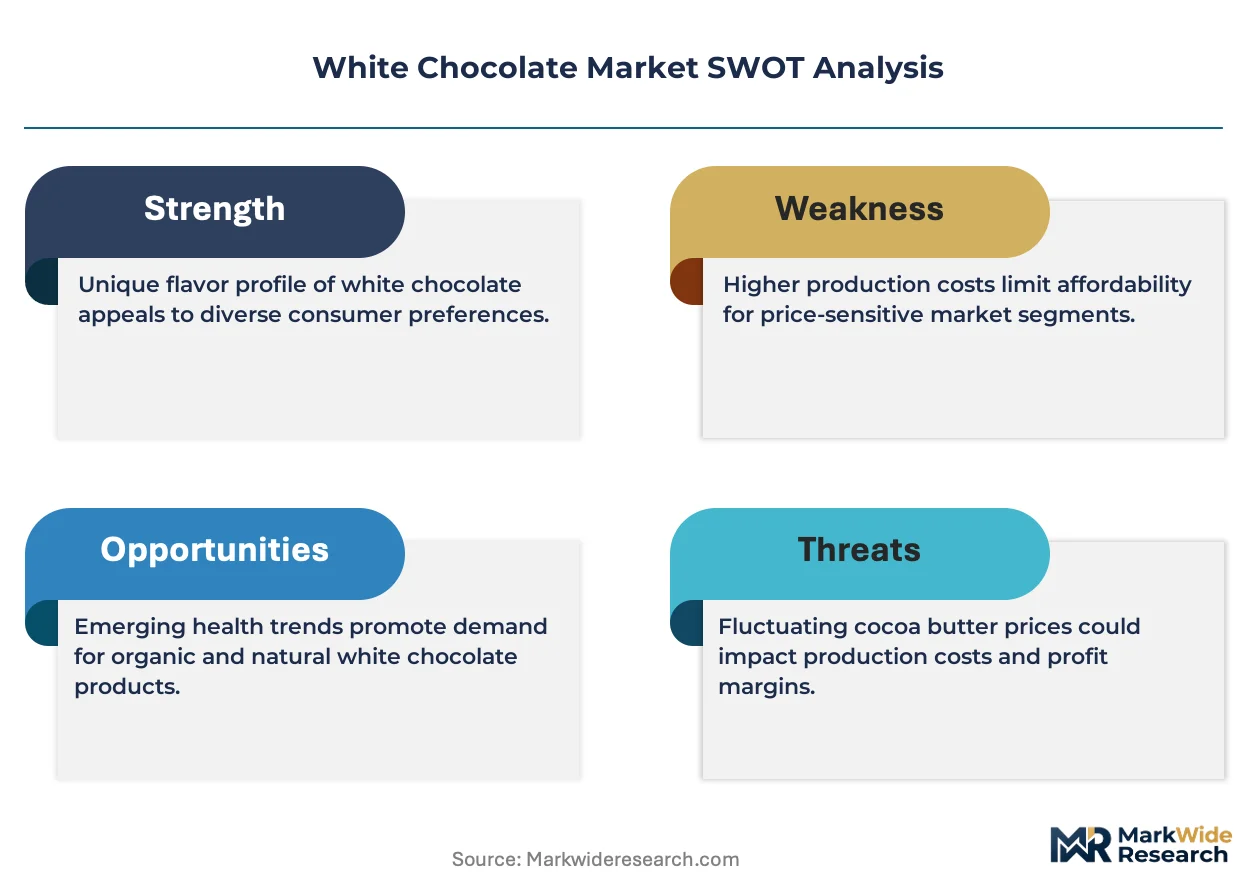
- Cocoa Butter Price Volatility:As the primary and defining input, cocoa butter prices are subject to significant fluctuation based on West African crop yields and commodity market speculation, creating margin pressure for producers.
- Compound Coating Competition:Lower-cost compound coatings, which replace cocoa butter with other vegetable fats, remain a persistent substitution threat, especially in price-sensitive industrial and food service applications.
- Varying Standards of Identity:Divergent regulations between the U.S. FDA and EU directives regarding minimum cocoa butter content create formulation and labeling complexities for brands targeting transatlantic export markets.
Strategic Opportunities
- Premium Beverage Formulations:An opportunity exists to develop shelf-stable white chocolate syrups, sauces, and powders specifically formulated for specialty coffee and tea beverages in the cafe and restaurant channel.
- Plant-Based Alternatives:Formulating vegan white chocolate using alternatives to dairy milk solids, such as rice powder or oat milk, provides access to the expanding demographic of plant-based consumers.
- Middle East Confectionery Market:Rising disposable incomes and a strong gifting culture in countries like the UAE and Saudi Arabia create an opportunity for premium, elegantly packaged white chocolate offerings.
Industry Challenges
- Supply Chain Traceability:Documenting and verifying the origin of cocoa butter to comply with ethical sourcing certifications like Fair Trade or Rainforest Alliance adds significant administrative cost and complexity for manufacturers.
- Managing Bloom and Stability:Preventing fat bloom requires precise temperature control throughout the supply chain, from production to retail, posing a constant quality assurance challenge to maintain product appearance and texture.
Report Scope
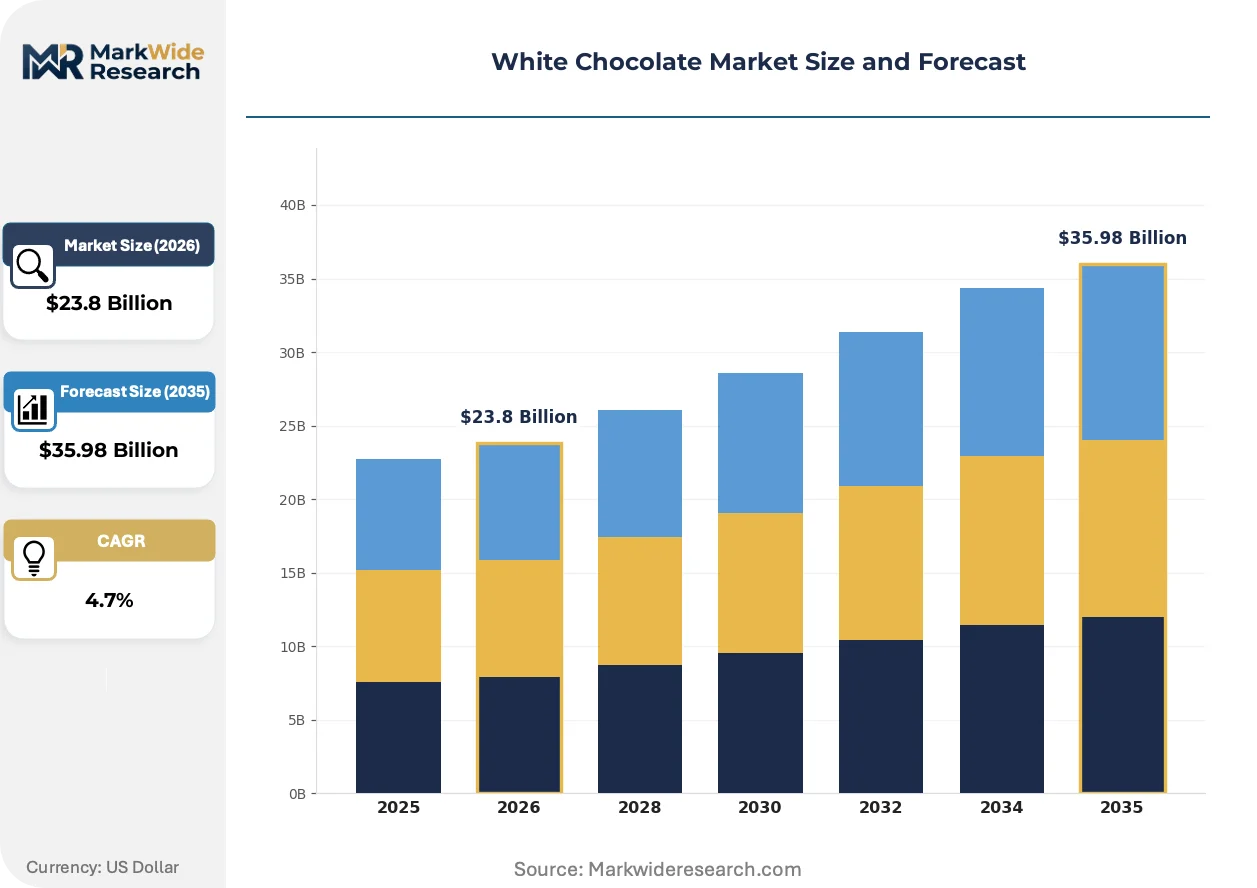
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Chocolate Market |
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $35.98 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bars, Coatings, Chips, Blocks, Spreads Application: Baking, Confectionery, Beverages, Desserts, Dairy Enhancements End User: Food Service, Retail Outlets, Artisan Chocolatiers, Food Manufacturers Packaging Type: Boxes, Wraps, Tubs, Pouches, Bulk Containers |
| Companies Covered | Mars Incorporated, Nestle S.A., Barry Callebaut AG, CEMOI Group, Mondelez International, Inc., Cargill, Incorporated, The Hershey Company, Chocoladefabriken Lindt and Sprungli AG, Fuji Oil Company Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Chocolate Market Strategic Shifts & Innovations
Ingredient science advancements are converging with consumer demands for healthier and more transparent food products. This dynamic influences the entire value chain, from raw material selection and processing to final product formulation and labeling in the white chocolate sector.
Natural emulsifiers like sunflower lecithin are gaining adoption for their clean-label profile and functional properties in managing viscosity. Food manufacturers in the premium confectionery and natural foods channels are leading this switch. The market for emulsifiers is migrating from traditional soy-based lecithin, which faces consumer resistance due to allergen and GMO concerns, toward these plant-based alternatives.
New EU front-of-pack nutrition labeling systems, such as Nutri-Score, are directly influencing consumer purchasing decisions. This regulatory pressure forces manufacturers to reformulate products, primarily by reducing sugar content to achieve a more favorable score. White chocolate, with its high sugar and fat composition, is particularly affected, prompting innovation in reduced-sugar variants to compete in health-conscious European retail channels.
A distinct shift in purchasing behavior is occurring from large blocks of white chocolate towards smaller, more convenient formats like chips, wafers, and coatings. This pattern reflects the growing influence of home bakers and industrial food manufacturers, who prioritize ease of use and precise portioning over traditional consumer bar formats. This change is most pronounced in North American and European markets where food processing and home baking are significant end-use segments.
White Chocolate Market Segmentation
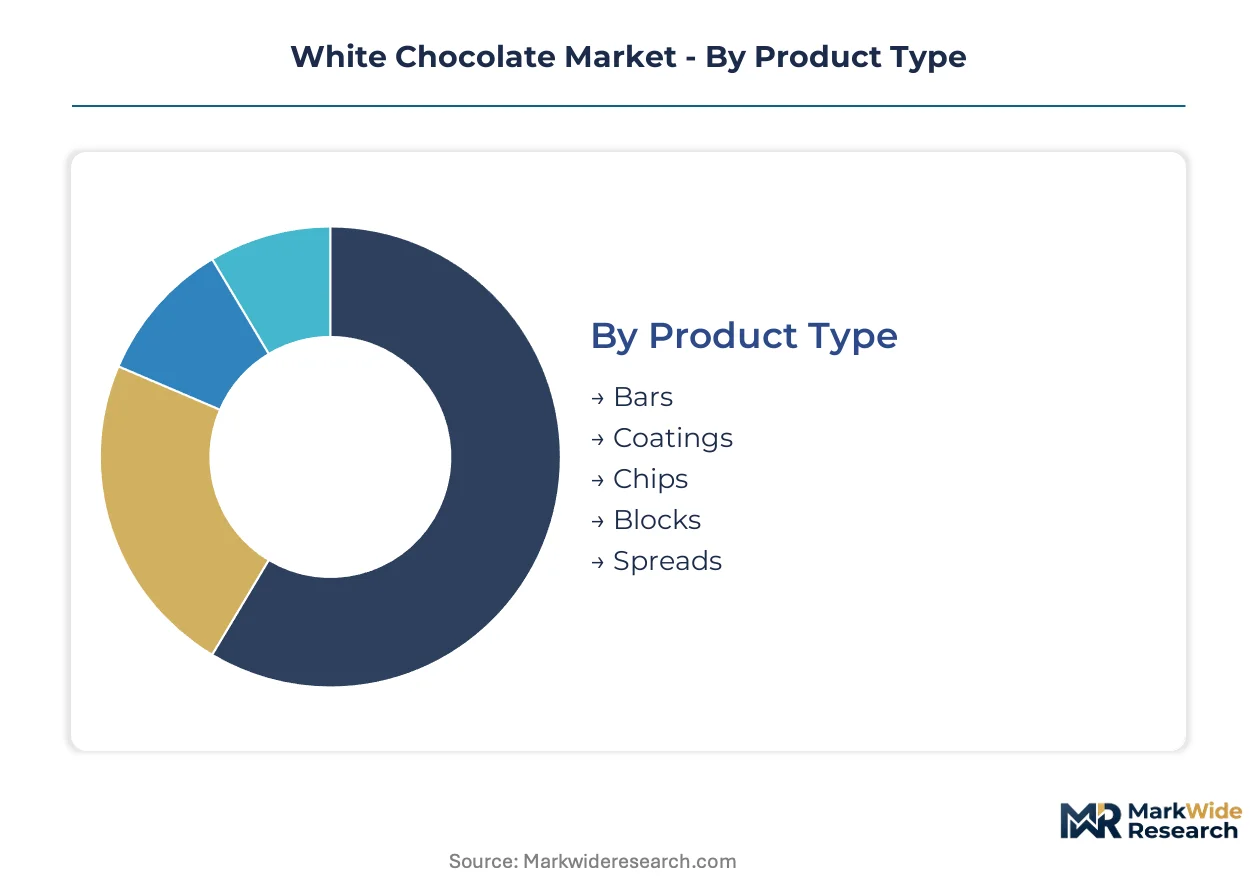
White chocolate market segmentation provides a granular view of product variations, application diversity, and end-user preferences influencing purchasing decisions. This detailed breakdown helps manufacturers align product development and distribution strategies with specific market demands. Understanding these segments is crucial for identifying areas of high growth and competitive advantage.
Product Type:
The white chocolate market's product type segmentation reveals varying levels of required post-purchase support, influencing manufacturer investment in technical services and customer education.
- Coatings:These products feature specific viscosity and melting point characteristics, designed for industrial application in confectionery and baked goods. Demand concentrates among food manufacturers requiring efficient, high-volume processing solutions.
- Chips:Characterized by their small, uniform size and often engineered for bake-stable properties, these formats are ideal for inclusions and toppings. Demand from artisanal bakeries and home baking segments drives this category.
- Bars:Traditional consumer-ready white chocolate items, typically for direct consumption or gifting.
- Blocks:Large format white chocolate ingredients primarily sold to industrial users for further processing.
- Spreads:Creamy, ready-to-eat white chocolate formulations designed for breakfast or dessert applications.
Bars hold the largest share; momentum sits with Chips.
Application:
The application segments illustrate the distinct functional requirements and volume contributions of white chocolate across diverse food industries.
- Confectionery:White chocolate here demands specific moldability, snap, and flavor pairing, crucial for premium chocolate bars, truffles, and pralines. Demand remains strong in high-end chocolate shops and seasonal treat production.
- Baking:This segment requires white chocolate with good heat stability and texture integration for use in cookies, cakes, and pastries. Artisanal bakeries and industrial pastry manufacturers are significant consumers.
- Beverages:White chocolate is integrated into specialty coffee, hot chocolate, and milkshake formulations, often as syrups or powders.
- Desserts:Used as an ingredient or garnish in plated desserts, mousses, and other sweet culinary creations.
- Dairy Enhancements:Incorporated into yogurts, ice creams, and other dairy products as inclusions or flavorings.
Confectionery applications command significant volume, while Beverages demonstrate the steepest expansion trajectory.
End User:
End-user segmentation highlights the distinct purchasing behaviors and volume requirements across various commercial and consumer channels.
- Food Manufacturers:These entities require bulk quantities of white chocolate, often with custom formulations and specific functional properties for large-scale production. Industrial bakery and snack companies represent a substantial portion of this demand.
- Retail Outlets:This segment encompasses supermarkets, convenience stores, and specialty food shops selling consumer-packaged white chocolate products. Brand visibility and shelf appeal are critical factors in this channel.
- Food Service:Restaurants, cafes, and hotels utilize white chocolate as an ingredient in their menus and dessert offerings.
- Artisan Chocolatiers:Small-batch producers focused on high-quality, handcrafted white chocolate products for niche markets.
Food Manufacturers represent the largest procurement volume, with Artisan Chocolatiers showing increasing demand for specialty ingredients.
Packaging Type:
Packaging type differentiation reflects the varied logistical demands and cost structures associated with delivering white chocolate products to diverse end-users.
- Bulk Containers:Designed for industrial efficiency, these large formats (e.g., 25kg bags, totes) minimize packaging waste and reduce unit costs for high-volume users. Food manufacturers and large-scale bakeries are primary purchasers.
- Pouches:Offering convenience and re-sealability, pouches are popular for white chocolate chips or smaller bar formats, catering to home bakers and retail consumers. This format is gaining share in European markets.
- Boxes:Used for gifting, premium white chocolate assortments, or multi-pack consumer sales.
- Wraps:Individual packaging for white chocolate bars, common in retail and impulse purchase settings.
- Tubs:Medium-sized containers suitable for food service applications or larger consumer packs.
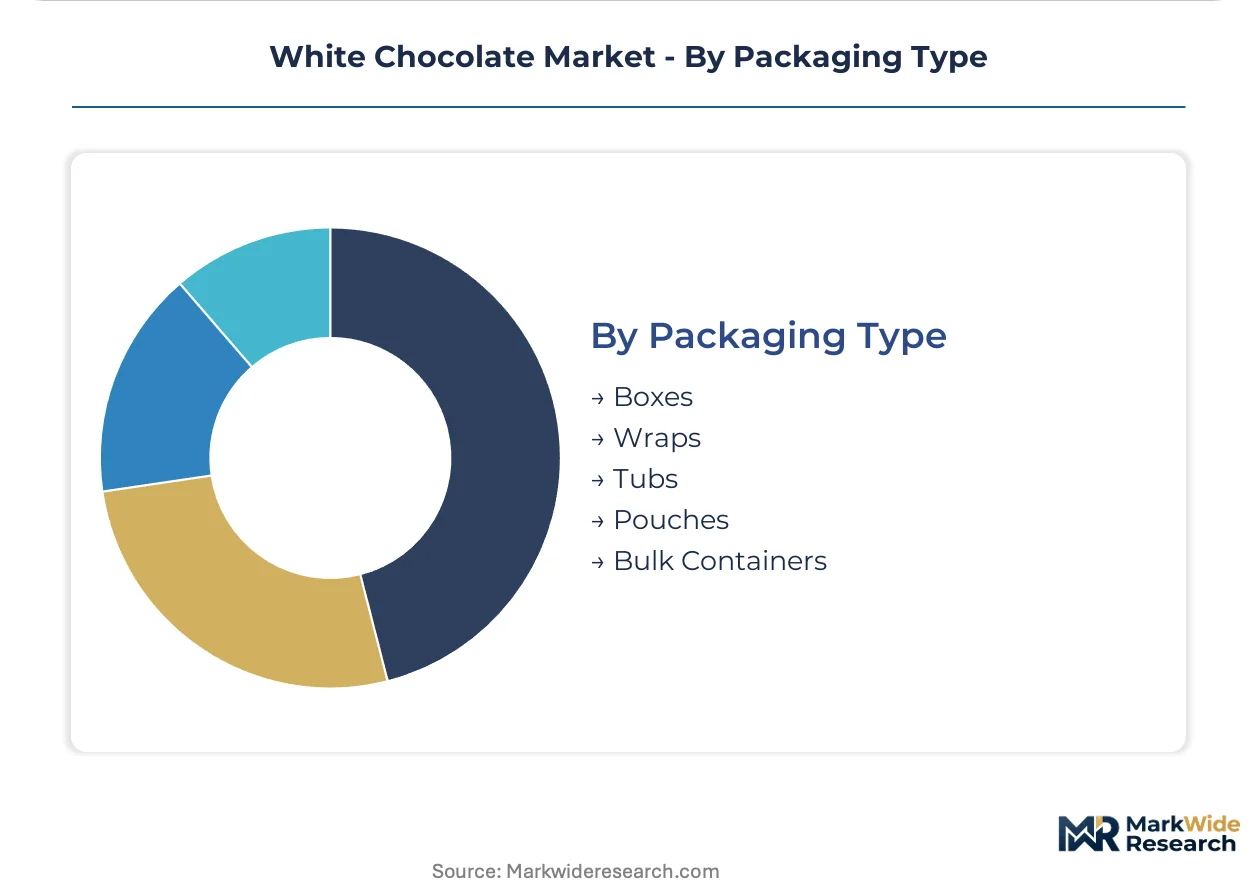
Bulk Containers optimize industrial supply chains, while Pouches are gaining share due to consumer convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration heavily influences regional white chocolate market dynamics, with distinct consumer preferences and regulatory frameworks shaping product demand across different geographies. This segmentation reflects varying levels of disposable income, cultural traditions, and food safety standards impacting ingredient formulation and market access. Manufacturers must tailor product offerings to meet these localized demands.
Japan
Japanese consumers exhibit a strong preference for novel textures and high-quality confectionery, driving demand for sophisticated white chocolate applications. The METI (Ministry of Economy, Trade and Industry) supports food innovation through various industrial policies. Tokyo's upscale Ginza district consistently showcases premium white chocolate desserts, setting trends for wider market adoption.
United States
Demand in the United States stems from robust home baking trends and large-scale industrial food manufacturing. The U.S. FDA mandates specific cocoa butter and milk solid percentages for white chocolate products, ensuring ingredient integrity. California's extensive food processing hubs utilize bulk white chocolate for diverse products, from baked goods to specialty beverages.
Germany
German artisanal bakery expansion creates steady demand for versatile white chocolate formats, including chips and coatings. EU directives establish strict standards of identity for cocoa butter content and approved additives across the bloc. Cologne's prominent confectionery industry integrates white chocolate into seasonal and specialty chocolate products.
United Arab Emirates
Rising disposable incomes and a strong gifting culture in the United Arab Emirates create an opportunity for premium, elegantly packaged white chocolate offerings. MOHAP (Ministry of Health and Prevention) oversees rigorous food safety standards for both domestic and imported food products. Dubai's luxury retail sector serves as a key showcase for high-end white chocolate confectionery.
China
China's expanding middle class and growing e-commerce penetration contribute to a rising demand for imported and premium white chocolate sweets. GB standards regulate food additives and ingredient purity for all chocolate products sold within the country. Shanghai's burgeoning food scene sees a notable increase in white chocolate dessert cafes and artisanal chocolatiers.
White Chocolate Market Key Industry Players
Channel-controlling players compete with product-specialist players across the white chocolate market, creating a tiered competitive structure. The market exhibits a consolidation among large food ingredient suppliers and a fragmentation among consumer-facing brands. Strategic archetypes include global confectionery giants, specialty ingredient providers, and regional artisan producers. Dominant competitive moves include strategic partnerships for ingredient sourcing and portfolio diversification into plant-based alternatives.
Specialty ingredient providers like Barry Callebaut AG occupy a strong position, leveraging extensive cocoa sourcing capabilities to supply high-quality cocoa butter. Cargill, Incorporated, a global agricultural and food ingredient powerhouse, represents another key player, offering a wide portfolio of functional ingredients including plant-based emulsifiers. These companies anchor the supply side, providing essential raw materials for downstream manufacturers.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestle S.A. |
| Barry Callebaut AG |
| CEMOI Group |
| Mondelez International, Inc. |
| Cargill, Incorporated |
| The Hershey Company |
| Chocoladefabriken Lindt and Sprungli AG |
| Fuji Oil Company Ltd. |
| Others |
Cost & Logistics Intelligence
Cocoa butter price volatility significantly determines both pricing tier spreads and the structural shape of the white chocolate supply chain. This primary input's fluctuating cost directly impacts producer margins and influences sourcing decisions across the value chain.
Pricing Analysis
Cost-plus contract patterns, often indexed to global cocoa butter prices, define much of the white chocolate market's pricing structure. Price differentiation stems from the quality grade of cocoa butter and specific ethical sourcing certifications like Fair Trade. Pricing softness permeates industrial applications due to intense competition from lower-cost compound coatings. Food manufacturers exhibit the highest price sensitivity, while artisan chocolatiers prioritize ingredient quality over cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common practices to manage working capital across the white chocolate supply chain. Supply concentrates heavily in West Africa for cocoa beans, while processing expertise often resides in Europe. The supply chain relies on consistent access to cocoa butter, sugar, and milk solids, facing structural risk from cocoa butter price volatility. Distribution runs primarily through direct sales channels to large food manufacturers and specialized ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The white chocolate market presents a defensive-moat story, primarily due to regulatory entrenchment in product definitions. Strict standards of identity, such as those from the U.S. FDA and EU directives, create significant barriers to entry and protect established players.
For Market Incumbents: Pre-empt the threat from lower-cost compound coatings by investing in advanced cocoa butter processing technologies. Deepen vertical integration into specialty cocoa butter sourcing to control quality and secure supply for premium offerings. Invest in R&D for natural emulsifiers and reduced-sugar formulations, addressing clean-label consumer demands and EU Nutri-Score pressures. Reinforce brand equity through ethical sourcing certifications like Fair Trade, differentiating from generic alternatives.
For New Entrants and Emerging Players: Middle East confectionery markets represent a significant underpenetrated opportunity for premium white chocolate offerings. Develop vegan white chocolate using oat or rice milk solids to access the expanding plant-based consumer demographic. Target the premium beverage sector with shelf-stable white chocolate syrups and powders for cafes and restaurants. Leverage e-commerce and direct-to-consumer channels to bypass established retail distribution and reach niche markets.
For Investors and Strategic Acquirers: New EU front-of-pack nutrition labeling systems reshape the acquisition landscape for white chocolate manufacturers over a 5-10 year horizon. The long-term viability favors companies able to innovate in reduced-sugar and plant-based white chocolate categories. Target mid-sized manufacturers with proprietary clean-label formulations or strong regional distribution in high-growth areas like Japan. The signal to watch is the market share growth of plant-based white chocolate alternatives and their acceptance in mainstream retail.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Reduced-Sugar White Chocolate | Addresses EU Nutri-Score pressures and health-conscious consumer demand in European markets. |
| Expand into Middle East Confectionery | Captures rising disposable incomes and strong gifting culture in countries like the UAE. |
| Invest in Advanced Cocoa Butter Deodorization | Enhances product quality and expands application into delicate flavor profiles like premium beverages. |
| Establish Direct-to-Consumer E-commerce Channels | Bypasses traditional retail, reaching artisanal bakeries and niche consumer segments directly. |
| Formulate Plant-Based White Chocolate Variants | Accesses the growing demographic of vegan consumers and aligns with clean-label trends. |
Research Approach
The analysis maps white chocolate sub-sectors including confectionery, baking, and beverages, each validated through extensive primary interviews. Primary research involved discussions with food manufacturers, artisanal chocolatiers, and ingredient suppliers to gather granular market insights. Secondary validation drew from industry association reports, trade publications, and relevant regulatory filings from the U.S. FDA and EU. A robust bottom-up and top-down triangulation approach reconciled market sizing and growth projections.
The forecast framework held macroeconomic stability and current regulatory structures fixed, while varying consumer preference shifts and raw material availability. The model segmented the market by product type, application, end-user, and packaging type across the analysis window. Compound annual growth rates were derived from historical market expansion and projected consumer spending patterns. Key forecast inputs included cocoa butter price trends and the adoption rates of clean-label ingredients in new product formulations.
Practitioners should monitor significant shifts in commodity prices or new international trade policies for early signals of market recalibration. Forecasts reflect assumptions regarding consumer preferences and ingredient innovation, which are subject to change. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Low Calorie Keto Desserts Market
Confectionery
Ice Cream Coating Market
Confectionery
Global Chocolate Market
Confectionery
Cookie Dough Market
Confectionery
Pralines Market
Confectionery
Sugarless Chocolate Market
Confectionery
Vegan Chocolate Confectionery Market
Confectionery
CBD-Infused Confectionery Market
Confectionery
China Chocolate Market
Confectionery
South America Chocolate Market
Confectionery
Sugar Free Mints Market
Confectionery
India Chocolate Market
Confectionery
Chocolate Flavors Market
Confectionery
North America Sugar Confectionery Market
Confectionery
South America Confectionery Market
Confectionery
United Arab Emirates Sugar Confectionery Market