
 Bangladesh Candy Market | 2026-2036
Bangladesh Candy Market Size, Share, and Industry Trends Forecast 2026-2036
Bangladesh Candy Market Insights
Urban convenience retail is hardening as the dominant demand channel for packaged confectionery in Bangladesh. PRAN-RFL Group leverages its deep rural distribution network to sustain volume leadership across mass-market segments. Olympic Industries Limited anchors its position through baked-and-confectionery hybrid manufacturing scale. Perfetti Van Melle differentiates via sugar-free and functional candy portfolios targeting health-conscious urban consumers.
Candy comprises sugar-based or sugar-substitute confectionery formulated with syrups, flavoring agents, and stabilizers, then cooked, pulled, or deposited into solid or semi-solid forms for direct consumption. Hard candies and lollipops currently lead value contribution due to longer shelf stability and lower logistics cost in Bangladesh's ambient supply chain. Gummies represent the fastest-growing product type as gelatin and pectin formulations gain traction among teenagers seeking texture novelty. Fruity flavor profiles occupy the largest share of volume, though chocolate-infused variants command higher per-unit margins in urban pouches and jar formats.
Bangladesh's national food safety regulator enforces standards on artificial coloring limits and sweetener labeling that shape product reformulation cycles for both domestic and import-reliant brands. The Bangladesh Standards and Testing Institution (BSTI) certifies packaging material safety, directly influencing supplier selection for bags and pouches used in humid monsoon conditions. Stakeholders must monitor enforcement intensity around sugar-content disclosure rules and the pace of modern trade expansion into secondary cities to calibrate portfolio and channel investments.
Market Dynamics
Urban retail modernization is hardening demand among working adults seeking convenience formats, while BSTI packaging standards and BIS-equivalent food safety protocols reshape supplier selection and shelf-life claims across Dhaka and Chattogram distribution corridors.
Growth Catalysts
- Modern Trade Expansion:Supermarket and hypermarket formats in Dhaka and Chattogram are pulling packaged confectionery into air-conditioned retail environments that extend shelf visibility and impulse purchase frequency among salaried professionals.
- BSTI Packaging Certification:Mandatory safety testing for materials used in humid monsoon conditions is filtering out informal suppliers and consolidating procurement toward certified converters with moisture-barrier capabilities.
- Gelatin and Pectin Formulation Advances:Texture innovation in gummy candies is capturing teenage consumers seeking novelty formats beyond traditional hard candy and lollipop segments.
Market Restraints
- Sugar Input Volatility:Domestic sugar procurement faces price instability and import dependency cycles that compress margin buffers for mass-market producers reliant on conventional formulations.
- Ambient Supply Chain Limitations:Refrigerated last-mile infrastructure gaps in secondary cities restrict distribution of chocolate-infused and temperature-sensitive premium variants to Dhaka and Chattogram corridors.
- Artificial Coloring Limits:BSTI enforcement of maximum permissible limits on synthetic dyes forces reformulation cycles and raw material switching costs for legacy product lines.
Strategic Opportunities
- Sylhet and Khulna Corridors:Underpenetrated urban centers outside Dhaka-Chattogram axis present whitespace for modern trade format entry and premium portfolio expansion.
- Sugar-Free and Functional Positioning:Health-conscious urban demographics create demand for xylitol and stevia-based formulations that command higher per-unit margins in pharmacy and wellness retail channels.
- E-Commerce Direct-to-Consumer:Digital platforms are bypassing traditional wholesale layers to reach working professionals in gated communities with subscription-based convenience packs.
Industry Challenges
- Food Technologist Talent Scarcity:Formulation expertise for clean-label and reduced-sugar product development remains concentrated among a limited pool of trained professionals in Dhaka.
- Legacy Equipment Retrofit Costs:Depositing and pulling machinery upgrades required for gummy and pectin production demand capital outlays that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bangladesh Candy Market |
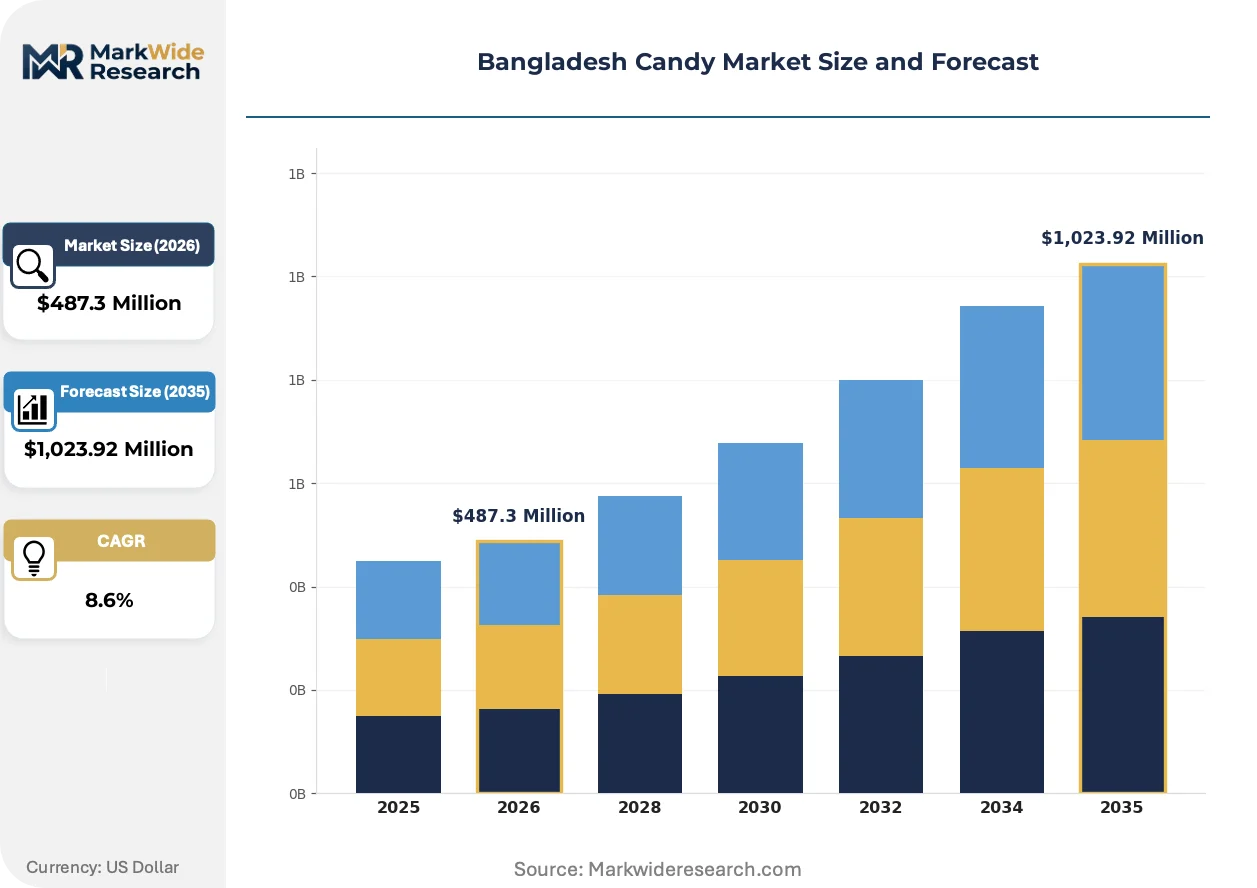
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Candies, Gummies, Hard Candies, Lollipops Consumer Age Group: Children, Teenagers, Adults, Seniors Flavor Profile: Fruity, Chocolate, Mint, Sour Packaging Type: Bags, Boxes, Jars, Pouches |
| Companies Covered | PRAN-RFL Group, Olympic Industries Limited, ACI Foods Limited, Perfetti Van Melle, Nestlé Bangladesh Limited, Cadbury Bangladesh, Mondelez International Inc., Mars Incorporated, Parle Products Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bangladesh Candy Market Trends and Innovations
Automation in processing equipment, tightening ingredient disclosure mandates, and channel fragmentation between modern retail and digital platforms are collectively reconfiguring how confectionery reaches Bangladeshi consumers.
Automated depositing and cooling tunnel systems are automating the transition from batch-based hard candy production to continuous-flow gummy manufacturing. Urban processors in Gazipur and Narayanganj industrial zones are adopting servo-controlled dosing equipment to reduce batch-to-batch variation in gelatin hydration. This automation is compressing unit labor requirements while enabling faster flavor changeovers that respond to seasonal demand spikes.
BSTI sugar-content disclosure rules are mandating front-of-pack labeling that exposes hidden sweetener loads in traditional formulations. Manufacturers must now reformulate or risk shelf-space relegation in modern trade channels where health-conscious buyers comparison-shop. Premium pouch formats in Dhaka supermarkets are responding with stevia-sweetened variants that carry explicit low-glycemic index claims.
Working professionals in Chattogram's port-zone employment clusters are fragmenting their confectionery purchases across convenience store impulse buys, office pantry subscription boxes, and pharmacy wellness aisles. This channel multiplication is forcing brands to maintain parallel packaging formats—single-serve sachets, jarred sharing sizes, and blister-pack pharmacy displays—each with distinct margin profiles and distribution economics.
Bangladesh Candy Market Segmentation
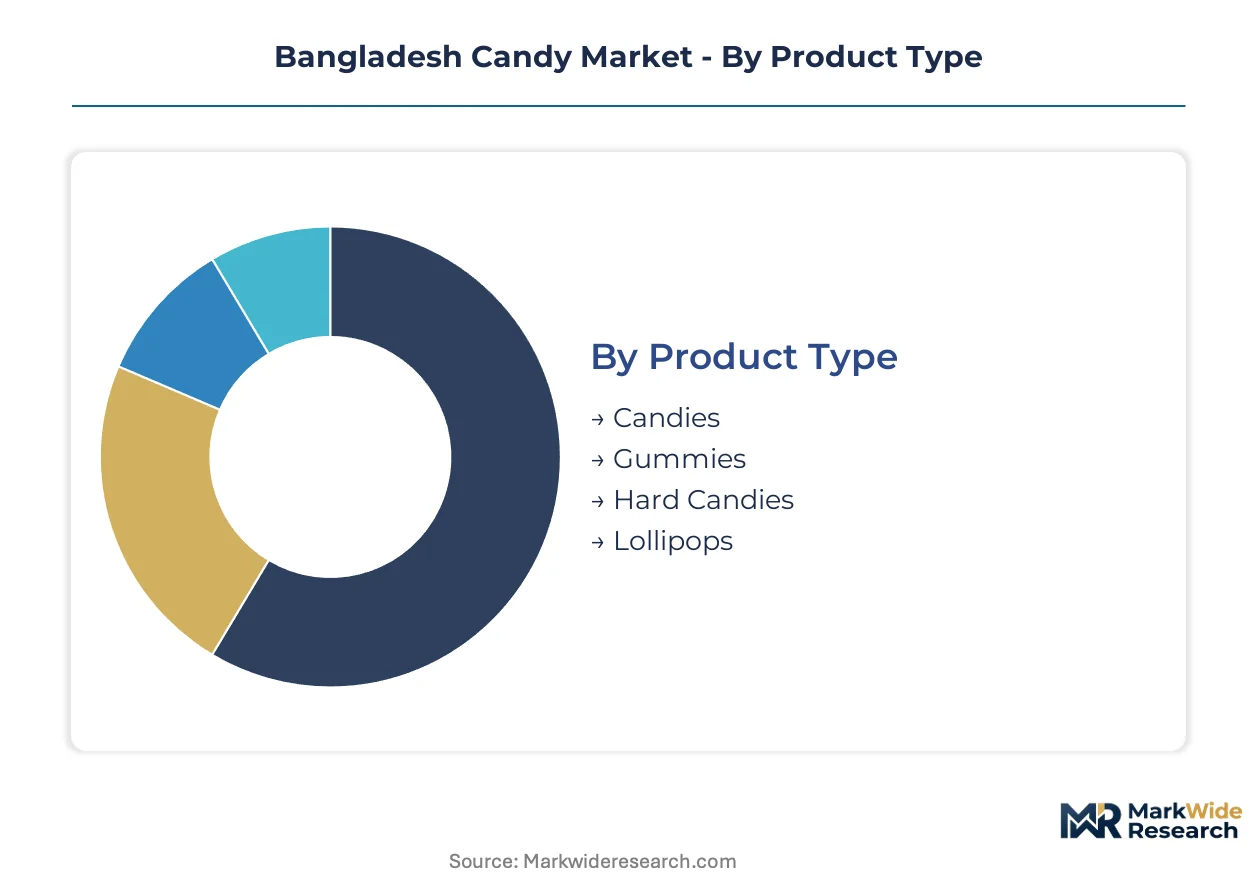
Candy manufacturers in Bangladesh calibrate production lines, ingredient sourcing, and channel strategies around four distinct segmentation axes. Each category carries different capital requirements, margin profiles, and regulatory exposure that shape portfolio allocation decisions.
Product Type:
Capital intensity varies sharply across production technologies, with continuous-flow gummy manufacturing demanding the highest upfront equipment outlays.
- Candies:Broad category encompassing sugar-based boiled sweets with flavoring and coloring agents. Dhaka's mass-market producers dominate volume through batch processing, though margin compression from sugar price volatility limits reinvestment capacity.
- Gummies:Gelatin or pectin-based chewy formulations requiring precision temperature control and starch molding systems. Teenagers in Chattogram's urban corridors drive demand for texture novelty, forcing manufacturers to absorb higher gelatin import costs and BSTI certification overhead.
- Hard Candies:High-boiled sugar glasses with extended ambient shelf stability. Rural distribution through PRAN-RFL's network favors this format for its logistics resilience during monsoon season.
- Lollipops:Sugar solution deposited onto sticks with slower cooling requirements than hard candy. Stick insertion automation remains limited among mid-tier Gazipur processors.
Most installed capacity flows through hard candies. Expansion is steepest in gummies.
Consumer Age Group:
Demand concentration patterns diverge by purchasing authority and consumption occasion, with working adults emerging as the most profitable addressable base.
- Children:Primary consumers of impulse-format lollipops and hard candies, though actual purchase decisions rest with parents. School-adjacent retail in Dhaka's Dhanmondi and Gulshan zones concentrates this segment.
- Teenagers:Texture-seeking cohort driving gummy adoption and flavor experimentation. Social media exposure accelerates preference shifts toward imported-format products.
- Adults:Working professionals purchasing convenience packs for office consumption and gifting occasions. Pharmacy channel penetration for sugar-free variants is climbing fastest among this group.
- Seniors:Limited direct consumption; occasional recipients of gift-box formats during Eid and cultural celebrations.
Volume leadership sits with children. Value-per-kilogram expansion is sharpest among adults.
Flavor Profile:
Raw material sourcing strategies and reformulation cycles align with flavor technology requirements and import dependency.
- Fruity:Synthetic and natural fruit essences combined with acidulants for tartness. Mango, orange, and strawberry variants dominate production schedules at Olympic Industries' Narayanganj facility.
- Chocolate:Cocoa mass and cocoa butter formulations requiring temperature-controlled supply chains. Premium positioning in Dhaka supermarkets commands higher margins but restricts distribution to modern trade corridors.
- Mint:Menthol and peppermint oil blends with cooling sensory properties. Pharmacy channel placement for breath-freshening positioning is gaining traction.
- Sour:Citric and malic acid coatings delivering intense acidity. Teenage consumers in Chattogram drive trial, though enamel erosion concerns limit mainstream expansion.
Production volume concentrates in fruity. Margin expansion is most pronounced in chocolate.
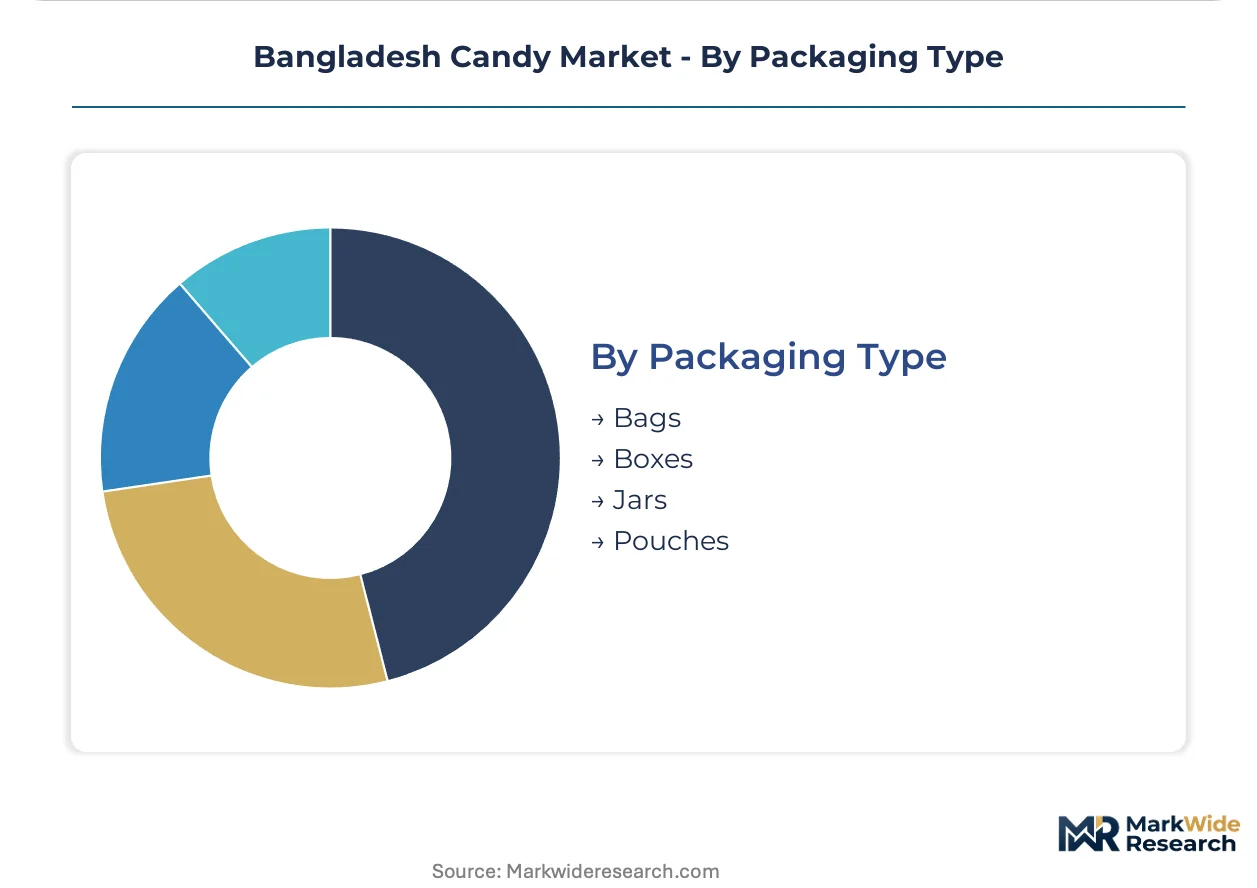
Packaging Type:
BSTI certification requirements and moisture-barrier specifications filter supplier capabilities and determine channel compatibility.
- Bags:Multi-layer polymer films with heat-sealed closures for single-serve and family packs. Certified converters in Gazipur industrial zone supply modern trade channels with humidity-resistant specifications.
- Boxes:Folding carton formats for gift occasions and premium positioning. Eid seasonal demand spikes require flexible secondary packaging capacity.
- Jars:Rigid PET or glass containers with screw-cap closures for sharing sizes. Urban pantry stocking and office consumption favor this format in Dhaka's gated communities.
- Pouches:Stand-up or flat pouches with resealable zippers for convenience positioning. Digital direct-to-consumer platforms are standardizing on this format for subscription deliveries.
Bag formats carry the highest shipment volume. Pouch adoption is accelerating fastest through e-commerce channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
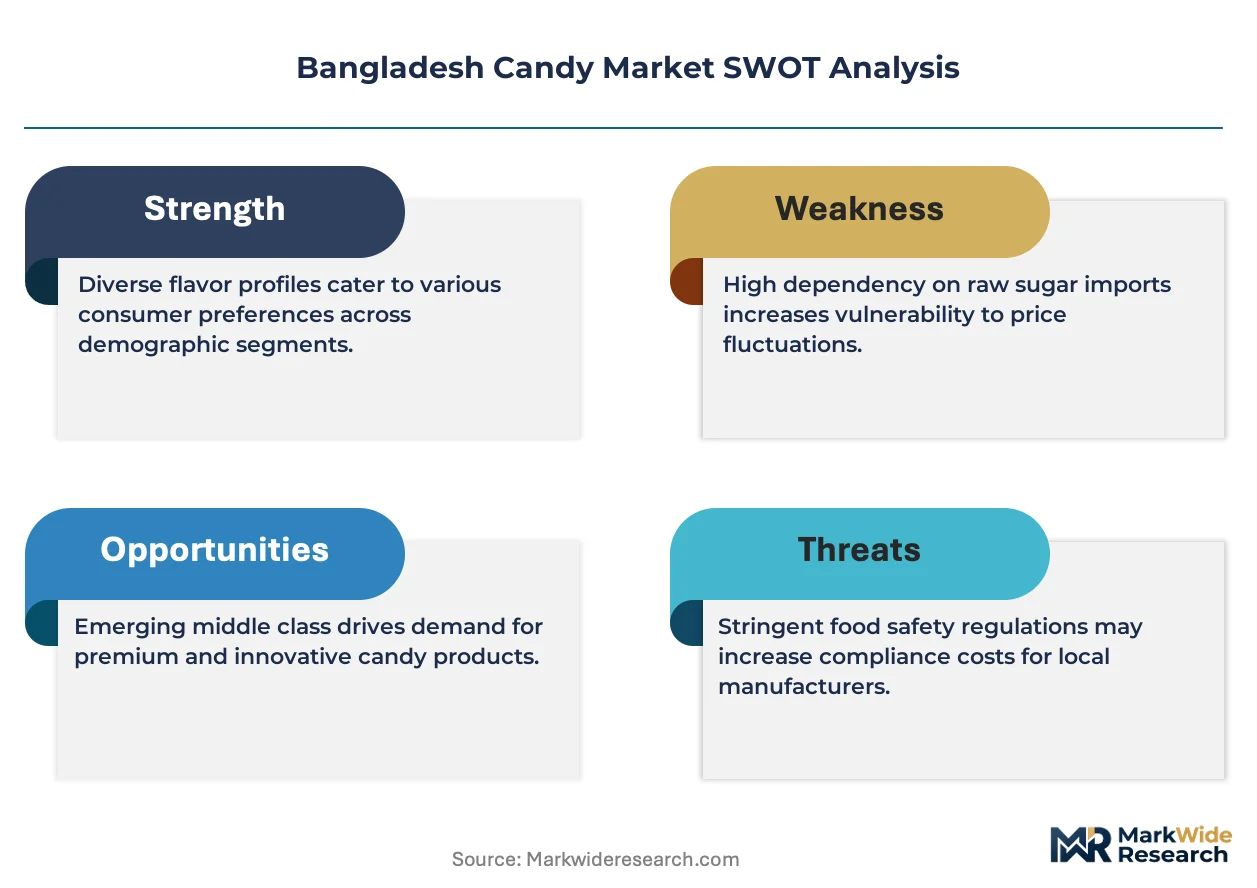
Production cost differentials between Bangladesh and neighboring economies are drawing contract manufacturing inquiries from brands seeking lower compliance overhead than India's FSSAI regime or Thailand's FDA requirements.
Dhaka Division
Working professionals in Gulshan and Dhanmondi commercial zones drive premium pouch and jar format demand through modern trade channels. BSTI packaging certification requirements filter supplier selection toward Gazipur-based converters with moisture-barrier capabilities. The Tejgaon industrial corridor hosts the highest concentration of automated depositing equipment for gummy production.
Chattogram Division
Port-zone employment clusters generate convenience-format consumption across office pantry and pharmacy wellness channels. The country's national food safety regulator enforces artificial coloring limits that force reformulation cycles for legacy hard candy lines. Agrabad and Foy's Lake retail zones concentrate premium chocolate-infused variant distribution.
Sylhet Division
Underpenetrated urban centers present whitespace for modern trade format entry beyond the dominant Dhaka-Chattogram axis. Local packaging standards for humid monsoon conditions shape procurement decisions for multi-layer polymer films. Sylhet city's emerging retail corridors attract initial supermarket investment targeting salaried service-sector workers.
Khulna Division
Ambient supply chain limitations restrict temperature-sensitive premium variants to basic hard candy and lollipop formats. Sugar input volatility from domestic procurement instability compresses margin buffers for mass-market producers. Khulna city's industrial estates house mid-tier manufacturers lacking capital for gummy production equipment upgrades.
Rajshahi Division
Rural distribution networks favor extended shelf-life formats resistant to monsoon logistics challenges. The Bangladesh Standards and Testing Institution certifies packaging material safety for bag formats used in traditional wholesale channels. Rajshahi city's retail base remains concentrated in informal kirana stores with limited modern trade penetration.
Bangladesh Candy Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with domestic conglomerates commanding rural volume through deep distribution networks while multinational affiliates capture urban premium tiers. The vendor base organizes around three strategic archetypes: diversified food conglomerates with backward integration into sugar processing, pure-play confectionery specialists with formulation expertise, and multinational licensors with global brand equity. Competitive moves center on portfolio diversification into sugar-free and functional variants, plus geographic expansion into underpenetrated secondary cities.
Among domestic diversified conglomerates, PRAN-RFL Group and Olympic Industries Limited exemplify the scale-driven archetype with integrated manufacturing footprints. Perfetti Van Melle represents the multinational specialist tier with health-positioned portfolios targeting pharmacy and wellness channels. These three anchors illustrate how competitive positioning stratifies across mass-market volume leadership, hybrid baked-confectionery manufacturing scale, and premium functional differentiation.
| Leading Market Players |
|---|
| PRAN-RFL Group |
| Olympic Industries Limited |
| ACI Foods Limited |
| Perfetti Van Melle |
| Nestlé Bangladesh Limited |
| Cadbury Bangladesh |
| Mondelez International Inc. |
| Mars Incorporated |
| Parle Products Pvt. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Working professionals in Dhaka's gated communities and Chattogram port-zone clusters concentrate purchasing power for premium pouch and jar formats, anchoring a three-tier pricing structure across premium, standard, and economy levels that rewards moisture-barrier packaging certification and sugar-free formulation claims.
Pricing Analysis
Distributor margins in traditional wholesale channels compress as modern trade retailers extract slotting fees for air-conditioned shelf placement. Price differentiation rests on BSTI certification status and gelatin sourcing tier, with Thai-imported hydrocolloid formulations commanding premiums over domestic batch-processed alternatives. Pricing pressure stems from sugar import duty volatility, eroding margin buffers for mass-market producers reliant on conventional boiled-sweet formulations. Rural kirana buyers exhibit highest price sensitivity, while pharmacy-channel wellness seekers accept per-unit premiums for stevia-based functional claims.
Supply Chain Analysis
BSTI domestic-content mandates for packaging material safety are reshaping sourcing toward Gazipur-based certified converters with multi-layer polymer film capabilities. Raw material dependencies draw from Thailand for gelatin, India for flavor essences and acidulants, and domestic sugar mills for sucrose feedstock. Supply chain risk centers on monsoon-season logistics chokepoints that delay humidity-sensitive ingredient deliveries to Narayanganj processing zones. Distribution runs through PRAN-RFL's rural wholesale network alongside Olympic Industries' hybrid baked-confectionery direct-to-retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bangladesh's candy sector offers geographic-arbitrage positioning against India's FSSAI compliance costs and Thailand's FDA overhead, with lower regulatory burden per unit attracting contract manufacturing inquiries from regional brands seeking margin relief.
For Market Incumbents: Anchor volume leadership through backward integration into sugar processing and captive gelatin hydration capacity at Gazipur industrial zones. Defend against multinational functional-candy entrants by accelerating BSTI certification for moisture-barrier pouch formats and locking exclusive modern trade shelf-space contracts in Dhaka's emerging supermarket corridors. For New Entrants and Emerging Players: BSTI sugar-content disclosure rules in Bangladesh open a window for stevia and xylitol-based formulations targeting pharmacy wellness channels. Whitespace sits in Sylhet and Khulna modern trade corridors where premium gummy formats remain underdistributed. A direct-to-consumer subscription model through digital platforms bypasses entrenched wholesale layers and captures working-professional pantry-stocking occasions. For Investors and Strategic Acquirers: Diversified food conglomerates with rural distribution depth are the most active acquirer in this space, seeking confectionery specialists to fill portfolio gaps. Long-term viability hinges on clean-label formulation capabilities and secondary-city modern trade penetration. The signal to watch is enforcement intensity around artificial coloring limits, which would accelerate consolidation toward compliant mid-tier manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sugar Processing | Captive sucrose supply insulates margin buffers against import duty volatility at Narayanganj facilities. |
| Gelatin Hydration Equipment Upgrade | Servo-controlled dosing systems enable pectin formulation shifts that capture teenage texture-seeking demand. |
| Pharmacy Channel Penetration | Wellness-aisle placement for sugar-free variants commands per-unit premiums from Dhaka health-conscious professionals. |
| Secondary City Modern Trade Expansion | Sylhet and Khulna supermarket entry captures salaried-worker convenience-format demand outside Dhaka-Chattogram axis. |
| BSTI Certification Investment | Moisture-barrier packaging approval filters informal competitors and consolidates procurement toward Gazipur converters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers at PRAN-RFL and Olympic Industries, category buyers at Dhaka supermarket chains, BSTI compliance officers, and gelatin procurement leads with secondary validation against Bangladesh customs records, BSTI certification databases, and Nielsen retail audit data. Bottom-up production capacity estimates triangulated against top-down consumption surveys.
Comparable historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions spanning product type, consumer age group, flavor profile, and packaging format. CAGRs derived from trend extrapolation of urban retail modernization rates and gelatin import volume trajectories, incorporating BSTI enforcement intensity scenarios and monsoon-season logistics disruption patterns as sensitivity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sugar import duty spikes or accelerated artificial coloring limit enforcement. The analytical envelope assumes continued modern trade format expansion into secondary cities and stable BSTI certification timelines for packaging converters. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Low-Calorie Candy Market
Confectionery
South America Compound Chocolate Market
Confectionery
US Dark Chocolate Market
Confectionery
Brain Mint Market
Confectionery
South America Chocolate Market
Confectionery
Global Chocolate Sprinkles Market
Confectionery
Cookie Dough Market
Confectionery
Durian Chocolate Market
Confectionery
North America Chocolate Confectionery Market
Confectionery
Fruit Jellies Market
Confectionery
Macarons Market
Confectionery
Confectionery Fats Market
Confectionery
Asia-Pacific Sugar Free Mints Market
Confectionery
Chocolate Spread Market
Confectionery
United States Caramel Chocolate Market
Confectionery
Chocolate Confectionery Market