
 Confectionery Fillings Market | 2026-2036
Confectionery Fillings Market Size, Share, and Industry Trends Forecast 2026-2036
Confectionery Fillings Market Analysis
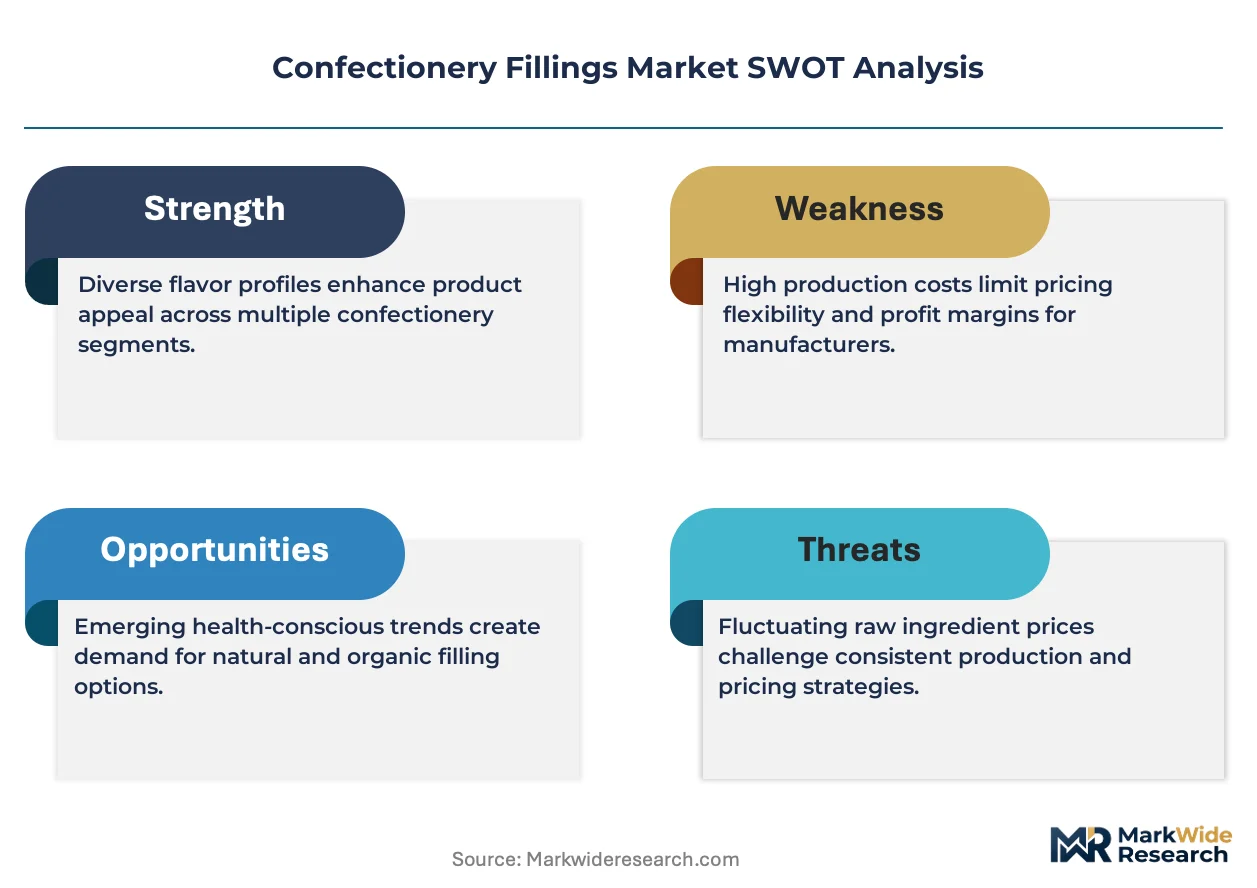
Artisanal bakery applications is broadening as a demand anchor for confectionery fillings, with craft chocolatiers and boutique patisseries seeking premium fruit and nut pastes. Barry Callebaut leverages its integrated cocoa processing network to secure supply continuity for high-fat chocolate fillings. Ferrero Group sustains competitive distance through captive hazelnut sourcing and proprietary roasting protocols. Zentis specializes in fruit preparation systems, occupying a defensible niche across European industrial bakery channels.
Confectionery fillings are semi-solid or viscous preparations formulated from chocolate, fruit purees, dairy creams, or nut pastes, typically containing 15-35% fat content and stabilized through emulsification or temperature-controlled crystallization, designed to deliver flavor, texture contrast, and structural integrity within enclosed confectionery shells or layered desserts. Chocolate fillings dominate value capture due to cocoa butter price volatility and premium positioning, while fruit preparations gain traction from clean-label bakery demand. Cream formulations remain mature in Western Europe, whereas paste-form nut fillings register the fastest growth in North American craft confectionery segments.
FDA standards for ingredient disclosure and allergen labeling shape product formulation thresholds in the United States, while EFSA evaluations of novel food additives constrain innovation pathways for European manufacturers. REACH compliance on food-contact substances and EU Green Deal sourcing requirements are elevating traceability costs across hazelnut and cocoa supply chains. Stakeholders must weigh backward integration into raw nut and fruit processing against flexible procurement models as regulatory stringency and consumer transparency expectations intensify.
Market Dynamics
Clean-label reformulations under EFSA guidance and reduced-sugar mandates are redirecting R&D spend toward fruit-based and nut-based alternatives, compressing traditional cream formulation margins while elevating traceability costs across hazelnut and cocoa supply chains.
Growth Catalysts
- EFSA Novel Food Evaluations:Accelerated approval pathways for innovative plant-based emulsifiers enable faster commercialization of clean-label fillings in European industrial bakery channels.
- Artisanal Bakery Demand:Craft chocolatiers and boutique patisseries in Germany anchor premium volume for high-fat chocolate and nut paste formulations.
- Temperature-Controlled Crystallization:Advanced stabilization protocols extend shelf stability of reduced-sugar fruit preparations without synthetic additives.
Market Restraints
- Cocoa Butter Price Volatility:Chocolate filling margins compress unpredictably due to commodity swings in West African supply origins.
- REACH Compliance Burden:Food-contact substance traceability requirements elevate testing and documentation costs for European manufacturers.
- Technical Viscosity Limits:Fat-content thresholds of 15-35% constrain water-activity reduction in clean-label reformulations.
Strategic Opportunities
- North American Craft Confectionery:Paste-form nut fillings register fastest adoption in small-batch chocolate operations seeking differentiation.
- EU Green Deal Sourcing Incentives:Deforestation-free supply chain certifications unlock preferential access to institutional procurement channels.
- Direct-to-Consumer Channels:Specialty food e-commerce platforms enable artisanal producers to bypass traditional distributor markups.
Industry Challenges
- Emulsification Chemistry Expertise:Shortage of food scientists skilled in clean-label stabilization without synthetic additives delays reformulation timelines.
- Legacy Equipment Retrofit Costs:Temperature-controlled crystallization systems require substantial capital outlay for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Confectionery Fillings Market |
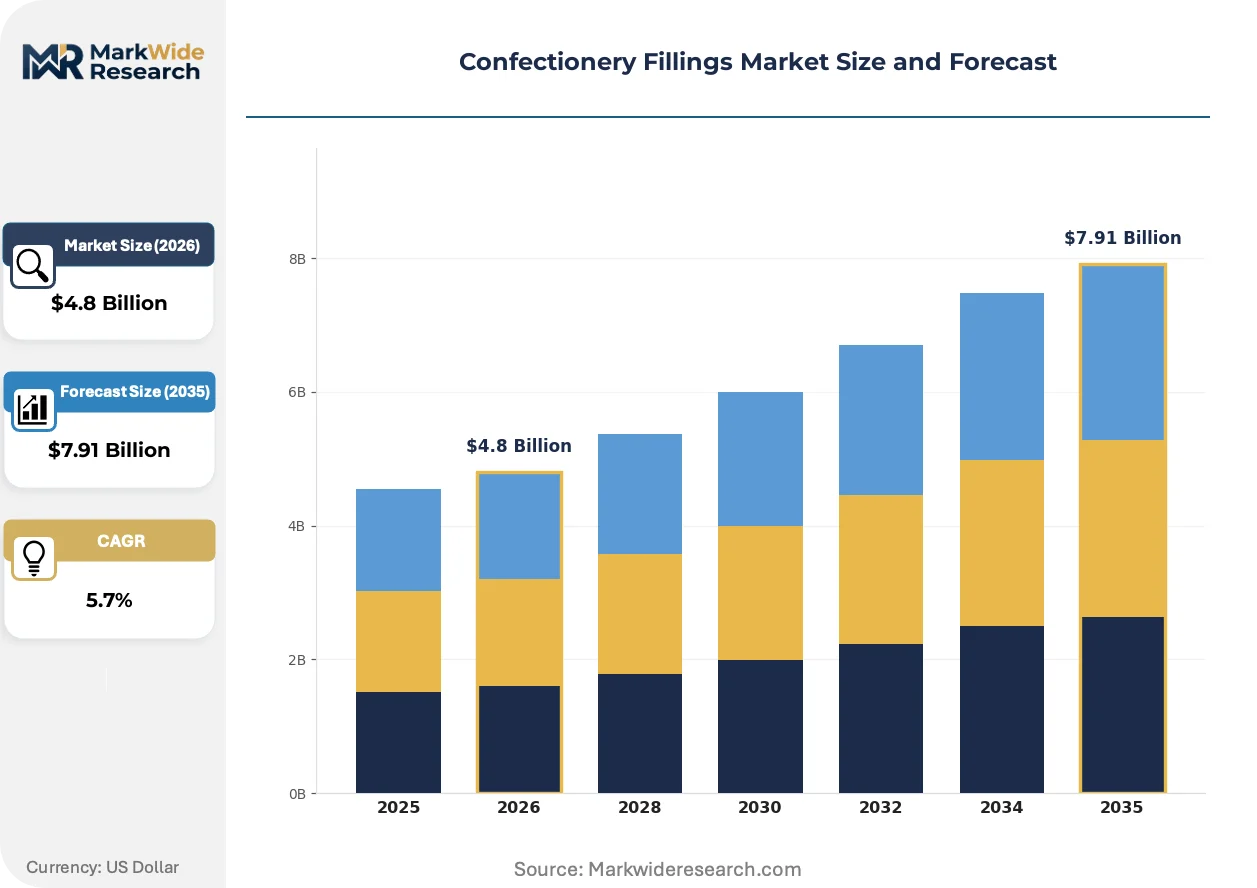
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Fruit, Cream, Nut End User: Bakers, Candy Manufacturers, Ice Cream Makers, Confectionery Shops Form: Liquid, Paste, Powder, Granulated Flavor: Vanilla, Strawberry, Coffee, Hazelnut |
| Companies Covered | Nestlé, Zentis, Mondelez International, Meiji Co. Ltd., The Hershey Company, Mars Incorporated, Barry Callebaut, Chocoladefabriken Lindt & Sprüngli, Ferrero Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Confectionery Fillings Market Emerging Trajectories
Precision processing technologies and regulatory transparency mandates are compressing product development cycles while fragmenting procurement authority across specialty ingredient channels.
High-pressure processing for fruit purees is automating pathogen reduction without thermal degradation, preserving volatile aromatic compounds. Industrial confectionery manufacturers in Belgium and Switzerland deploy these systems at pilot scale. The technology is automating quality assurance steps previously requiring manual batch testing.
EU Green Deal deforestation-free supply chain regulations now mandate geolocation verification for hazelnut and cocoa sourcing. Manufacturers must document farm-level coordinates through digital traceability platforms. Chocolate filling producers with Turkish and Italian hazelnut dependencies face the steepest compliance ramp.
Buyer concentration among private-label manufacturers is compressing ingredient specification negotiations. Tier-one retailers in Germany and France now dictate fat-content ranges and additive prohibitions directly. This shift is most visible in cream formulation segments where former brand autonomy has eroded.
Confectionery Fillings Market Segmentation
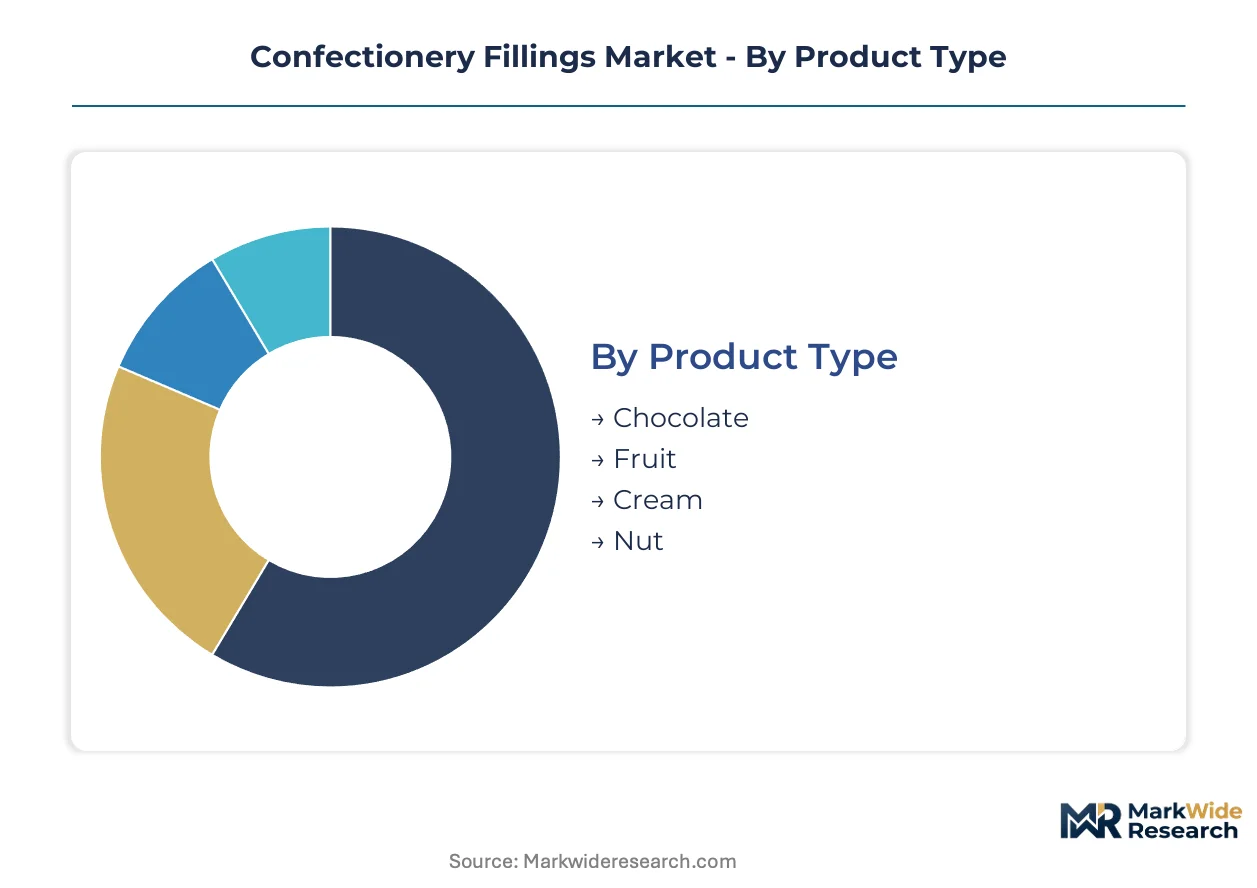
Confectionery fillings serve distinct functional roles across temperature-sensitive, viscosity-critical, and shelf-stability applications. Segmentation reveals how formulation chemistry and distribution temperature requirements partition procurement decisions between industrial-scale manufacturers and craft producers.
Product Type:
Chocolate formulations command premium positioning through cocoa butter crystallization control, while fruit and nut alternatives expand through clean-label substitution mandates.
- Chocolate:High-fat formulations stabilized through tempering protocols dominate praline and bonbon applications. German industrial bakeries anchor volume demand, though cocoa price volatility compresses margin predictability for mid-scale processors.
- Fruit:Puree-based preparations with reduced water activity target clean-label bakery reformulations under EFSA guidance. Paste-form fruit fillings are expanding most quickly in European artisanal channels seeking synthetic additive elimination.
- Cream:Dairy-based emulsions remain mature in Western European layered dessert applications, constrained by refrigerated distribution requirements.
- Nut:Hazelnut and almond pastes leverage high oil content for shelf-stable viscosity, gaining traction in North American craft confectionery segments.
Mature deployment sits with chocolate formulations. Newer deployment is concentrated in fruit-based alternatives.
End User:
Procurement authority fragments across specification complexity, with private-label retailers dictating ingredient thresholds to former brand-autonomous manufacturers.
- Bakers:Industrial bakery channels in Belgium and Switzerland specify fat-content ranges and emulsifier prohibitions directly. Temperature-controlled crystallization systems enable extended shelf stability for high-volume croissant and Danish applications.
- Candy Manufacturers:Mass-market chocolate operations prioritize supply continuity through backward integration into cocoa processing networks. REACH compliance documentation for food-contact substances elevates procurement costs for European facilities.
- Ice Cream Makers:Low-temperature viscosity maintenance drives emulsifier selection, with fruit swirl applications requiring freeze-thaw stability protocols.
- Confectionery Shops:Artisanal producers in German craft clusters source premium nut pastes through specialty ingredient distributors, bypassing traditional volume-tier pricing structures.
Volume concentration rests with candy manufacturers. Specification complexity is rising fastest among bakers.
Form:
Physical state determines equipment compatibility and automation potential across deposition, enrobing, and injection production lines.
- Liquid:Pumpable viscosity enables continuous-flow enrobing systems in high-throughput operations. EFSA novel food evaluations for plant-based emulsifiers are accelerating clean-label liquid formulation approvals.
- Paste:Semi-solid consistency supports structural integrity in layered desserts and filled pralines. Nut-based pastes register the steepest adoption curve in small-batch North American chocolate operations.
- Powder:Dehydrated formats reduce transport costs and extend ambient shelf life, requiring reconstitution protocols at point of use.
- Granulated:Crystalline sugar-based inclusions provide textural contrast in compound chocolate applications, constrained by moisture sensitivity during storage.
Established infrastructure serves liquid formats. Capital investment is flowing toward paste-form processing capabilities.
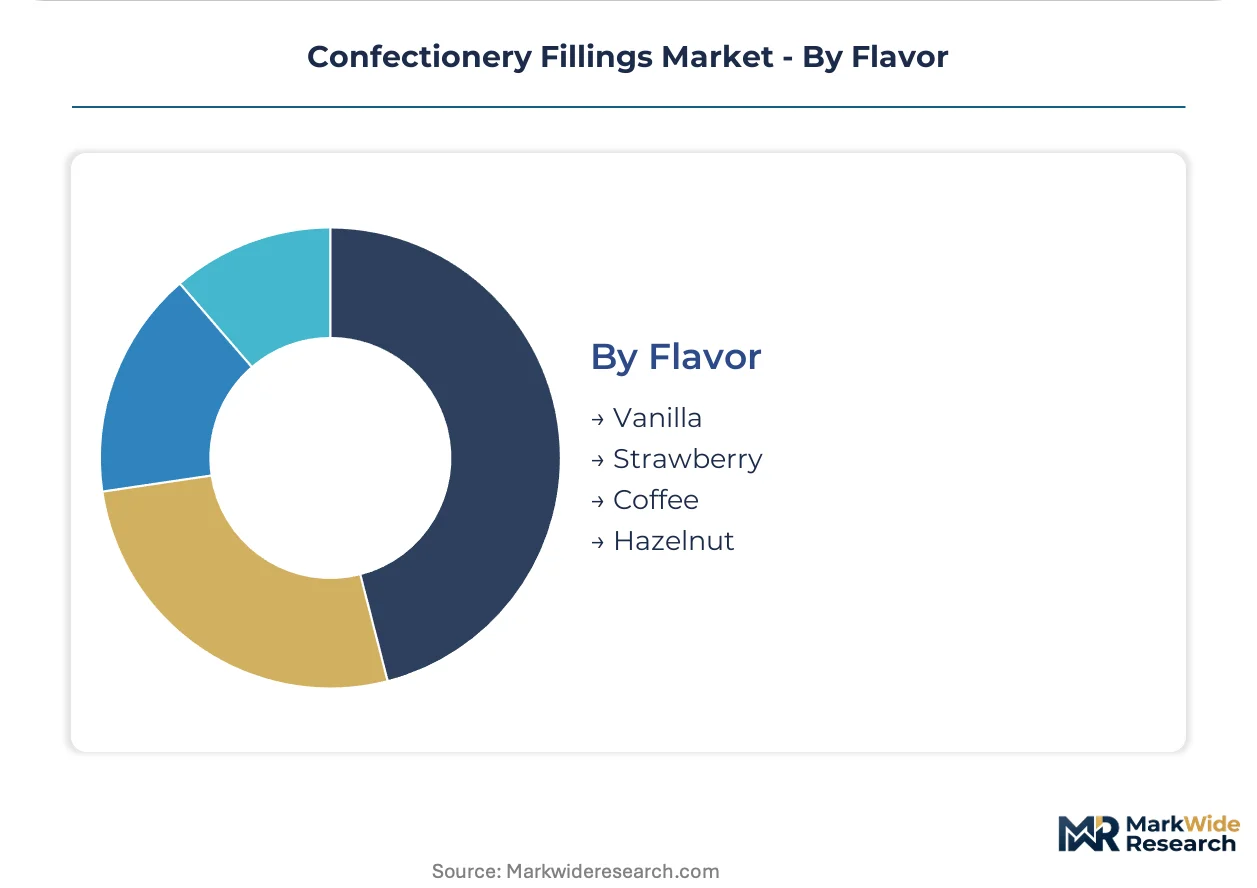
Flavor:
Flavor selection reflects sourcing geography and agricultural commodity exposure, with nut-derived profiles tied to specific cultivation regions.
- Vanilla:Extract and natural flavor formulations face supply concentration in Madagascar and Indonesia, with price volatility managed through synthetic alternatives in economy-tier applications.
- Strawberry:High-pressure processed fruit purees preserve volatile aromatic compounds for premium positioning. EU Green Deal deforestation-free sourcing mandates now require geolocation verification for fruit supply chains.
- Coffee:Roasted bean extracts deliver bitter balance in chocolate pairings, with specialty coffee provenance claims supporting premium pricing tiers.
- Hazelnut:Turkish and Italian origin dependence creates compliance exposure under EU deforestation regulations. Captive roasting protocols differentiate proprietary flavor signatures for market leaders.
Vanilla and strawberry anchor mature flavor deployment. Hazelnut applications are climbing the fastest on clean-label nut paste substitution trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German free-trade zones and industrial parks along the Rhine corridor concentrate European confectionery filling capacity, with tax-advantaged manufacturing sites drawing cross-border investment from Swiss and Belgian processors.
Germany
Craft confectionery shops in Cologne and industrial bakeries in Munich drive premium chocolate and nut paste consumption. EFSA novel food evaluations accelerate clean-label emulsifier approvals for reformulated fruit preparations. The Stuttgart industrial cluster hosts temperature-controlled crystallization facilities serving pan-European praline manufacturers.
Switzerland
Artisanal chocolate houses in Zurich and Geneva anchor demand for high-fat cocoa butter formulations with precise tempering specifications. Swissmedic food-contact substance regulations exceed baseline EU REACH requirements, elevating documentation burdens for imported nut preparations. The Vevey-Lausanne corridor concentrates research facilities developing reduced-sugar stabilization protocols.
United States
Small-batch confectionery operations in Brooklyn and San Francisco propel paste-form nut filling adoption for differentiation. FDA allergen labeling mandates reshape formulation thresholds for hazelnut and almond derivatives. The Chicago metropolitan area hosts industrial-scale enrobing equipment manufacturers supplying mid-continent candy processors.
Belgium
Industrial praline manufacturers in Brussels and Antwerp specify fat-content ranges and additive prohibitions for private-label retail programs. EU Green Deal deforestation-free sourcing regulations mandate geolocation verification for cocoa and hazelnut supply chains. The Flanders region pilots high-pressure processing systems for fruit puree pathogen reduction without thermal degradation.
Italy
Piedmontese hazelnut cultivation in the Alessandria province supplies raw material for regional paste formulations and export-oriented processors. ECHA REACH compliance on food-contact substances elevates testing costs for Turin-based confectionery equipment manufacturers. The Bologna packaging machinery cluster develops automated deposition systems for viscous nut preparations.
Confectionery Fillings Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated cocoa processors commanding premium chocolate filling categories while fruit preparation houses serve industrial bakery channels through specification-driven contracts. The vendor base concentrates around three strategic archetypes: captive nut processors with proprietary roasting protocols, integrated cocoa processors controlling supply continuity, and fruit system specialists occupying defensible clean-label niches. Dominant competitive moves include backward integration into Turkish and Italian hazelnut sourcing regions and technology licensing for temperature-controlled crystallization systems.
Among European integrated processors, Barry Callebaut and Zentis exemplify contrasting archetypes—the former representing upstream cocoa control, the latter occupying fruit preparation specialization. Ferrero Group anchors the captive sourcing tier through in-house hazelnut supply chains. These three structures illustrate how procurement authority fragments between commodity-integrated and specification-driven business models.
| Leading Market Players |
|---|
| Nestlé |
| Zentis |
| Mondelez International |
| Meiji Co. Ltd. |
| The Hershey Company |
| Mars Incorporated |
| Barry Callebaut |
| Chocoladefabriken Lindt & Sprüngli |
| Ferrero Group |
| Others |
Supply Flow & Price Mechanics
Private-label manufacturers in Germany and France now dictate fat-content ranges and additive prohibitions directly to ingredient suppliers, compressing margin autonomy and forcing a contract-based long-term offtake pricing model across European industrial bakery channels.
Pricing Analysis
Short lead-time premiums of 15-20% apply to temperature-controlled crystallization equipment and specialty nut pastes ordered on compressed schedules. Three-tier pricing structure across premium, standard, and economy levels separates artisanal-grade fruit preparations with EFSA novel food approvals from commodity cream formulations and synthetic-stabilized economy tiers. Price differentiation hinges on clean-label certification grade and captive hazelnut sourcing from Turkish and Italian origins. Cost compression in mid-tier chocolate fillings is intensifying because cocoa butter price volatility from West African supply origins compresses processor margins unpredictably. Industrial bakery channels exhibit highest price sensitivity due to volume concentration and specification complexity, while craft confectionery shops remain least sensitive given premium positioning and small-batch economics.
Supply Chain Analysis
Regional distribution centers in Cologne, Stuttgart, and the Rhine corridor operate hub-and-spoke patterns serving pan-European praline manufacturers and industrial bakeries. Supply concentrates in Germany, Belgium, and Switzerland for finished filling production, with raw material dependencies on Turkish and Italian hazelnuts, West African cocoa, and high-pressure processed fruit purees from Flanders pilot facilities. Single-source vulnerability in Turkish hazelnut sourcing creates compliance exposure under EU Green Deal deforestation-free regulations requiring geolocation verification. Distribution runs through temperature-controlled logistics networks with specialized enrobing equipment manufacturers in Chicago supplying mid-continent North American processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cocoa butter crystallization expertise and captive nut roasting capacity constrain supply expansion, propping pricing power for integrated processors with backward control over Turkish and Italian hazelnut origins.
For Market Incumbents: Deepen proprietary roasting protocol investments to differentiate flavor signatures against commodity paste competitors. Secure EFSA novel food evaluation pipelines for plant-based emulsifiers before specification mandates harden. Add temperature-controlled crystallization capacity in the Stuttgart industrial cluster to capture pan-European praline manufacturer demand. Defend margin position by locking long-term offtake contracts with German private-label retailers before buyer concentration intensifies further. For New Entrants and Emerging Players: Specialty ingredient distributors serving Brooklyn and San Francisco craft confectionery operations offer the most penetrable channel for paste-form nut filling introduction. North American small-batch chocolate operations seek differentiation through clean-label hazelnut and almond derivatives with freeze-thaw stability protocols. Target EU Green Deal deforestation-free certification gaps in Turkish hazelnut supply chains as a sourcing wedge. Direct-to-consumer e-commerce platforms enable bypass of traditional distributor markups for artisanal positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor fruit preparation specialists with EFSA-approved clean-label portfolios in German industrial bakery channels. Long-term viability over the projection horizon rests on defensible positioning in specification-driven contracts rather than commodity volume exposure. Acquisition targets should demonstrate captive sourcing relationships or proprietary stabilization technology. Watch EU Green Deal geolocation verification compliance rates as the inflection signal for supply chain restructuring urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hazelnut Sourcing | Captive Turkish and Italian supply secures deforestation-free compliance under EU Green Deal mandates. |
| Temperature-Controlled Crystallization Capacity Addition | Stuttgart cluster facilities capture pan-European praline manufacturer specification demand. |
| EFSA Novel Food Emulsifier Approval Pipeline | Accelerated clean-label formulation pathways outpace synthetic-additive-dependent competitors. |
| Direct-to-Consumer Channel Launch | Specialty e-commerce platforms enable artisanal producers to bypass traditional distributor markups. |
| High-Pressure Processing Technology Licensing | Flanders pilot systems automate pathogen reduction without thermal degradation for fruit purees. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this confectionery fillings assessment. Primary interviews with industrial bakery procurement directors, craft confectionery shop owners, chocolate filling R&D scientists, and specialty ingredient distributors combined with EFSA novel food evaluation databases, EU Green Deal compliance documentation, and REACH food-contact substance filings. Bottom-up volume modeling across product types and end-user segments triangulated against top-down value estimates from cocoa butter price indices and hazelnut commodity benchmarks.
Granularity-level modeling deployed country-specific production capacity for Germany, Switzerland, Belgium, and Italy alongside end-user segmentation across industrial bakeries, candy manufacturers, ice cream makers, and confectionery shops. CAGRs derived from weighted average growth assumptions across the projection horizon incorporating clean-label substitution elasticity, private-label buyer concentration trends, and temperature-controlled crystallization adoption curves. Cocoa butter price volatility scenarios and EFSA regulatory approval timelines served as key forecast sensitivity inputs.
Caveats apply where EFSA novel food evaluation delays, EU Green Deal enforcement intensity, or West African cocoa supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions on clean-label penetration rates and private-label specification evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
North America Dark Chocolate Market
Confectionery
Crunchy Chocolate Market
Confectionery
Low Calorie Keto Desserts Market
Confectionery
Europe Chocolate Market
Confectionery
Sugar-Free Gumballs Market
Confectionery
Chocolate Confectionery Market
Confectionery
Europe Caramel Chocolate Market
Confectionery
Chocolate Flavors Market
Confectionery
Mooncake Market
Confectionery
China Cakes, Pastries, & Sweet Pies Market
Confectionery
Middle East Chocolate Market
Confectionery
Chocolate Inclusions and Decorations Market
Confectionery
Canada Chocolate Market
Confectionery
South Africa Confectionery Market
Confectionery
Confectionery Fats Market
Confectionery
Green Tea Chocolate Market