
 Sugar Free Lollipops Market | 2026-2036
Sugar Free Lollipops Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Free Lollipops Market Analytics
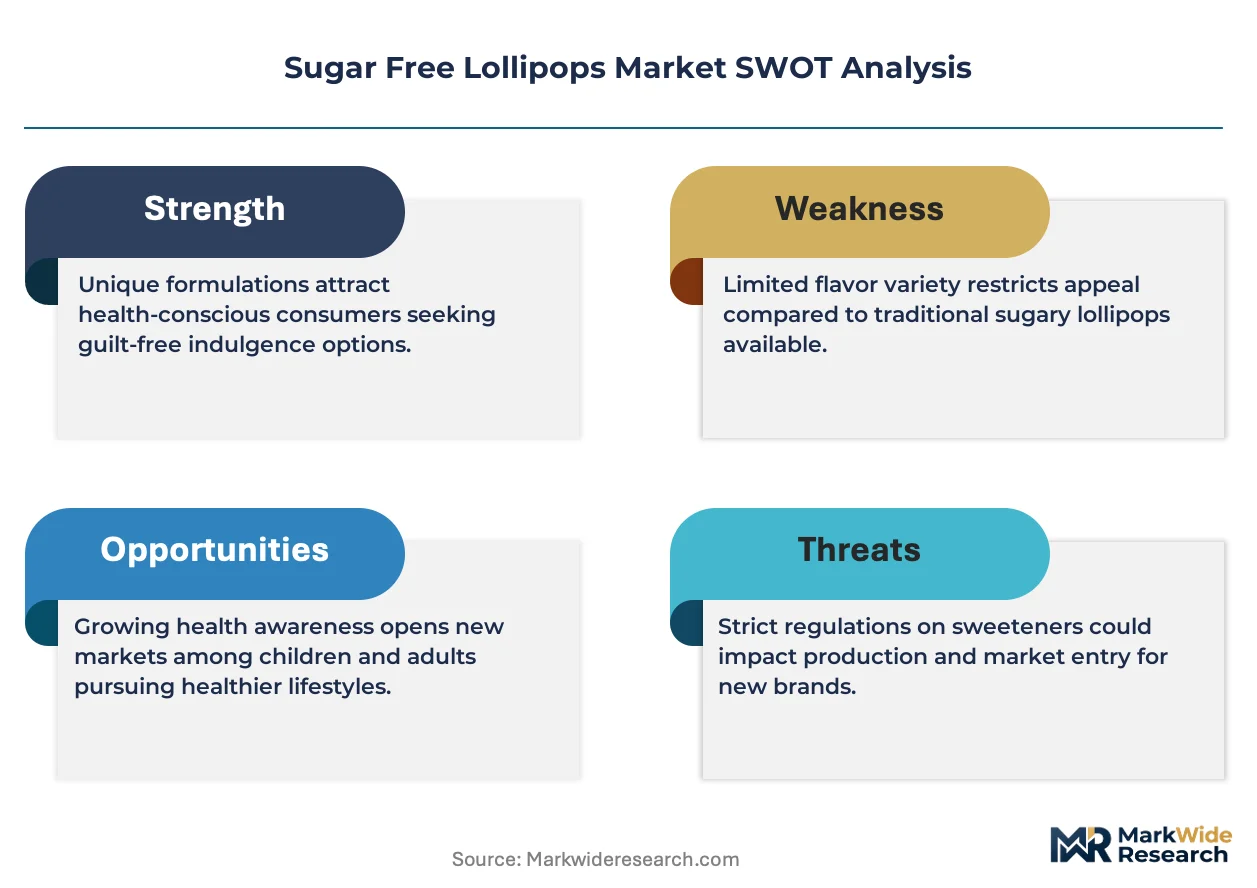
The gap between premium functional lollipops and commodity sugar-free candy is broadening. Premium tiers now carry dental health certifications and clean-label sweetener profiles, while commodity segments compete on price through artificial sweetener formulations. Perfetti Van Melle Company leverages its global manufacturing footprint to sustain cost advantages across multiple price tiers. Zolli Lollipops anchors its brand in the pediatric dental channel, where it competes with conventional candy through cavity-prevention positioning. The Hershey Company differentiates via retail shelf-space control and mainstream grocery distribution.
Sugar-free lollipops are hard or chewy confectionery products manufactured without sucrose, typically incorporating sugar alcohols such as xylitol or erythritol, artificial sweeteners like sucralose, or natural alternatives including stevia, with formulations designed to deliver flavor and mouthfeel comparable to conventional candy while minimizing glycemic impact and dental caries risk. The ingredient type dimension shows sugar alcohols commanding the strongest margin pools due to dual dental-health and clean-label positioning, while natural sweeteners represent the fastest-growing category as consumers reject artificial alternatives. Hard candy dominates product type volume through longer shelf stability and lower production complexity, though chewy candy formats attract repeat purchase through texture preference among adult consumers.
The FDA regulates sugar-free claims and sweetener safety thresholds under food additive provisions, while EFSA establishes maximum intake guidelines for polyols that directly constrain European formulation strategies. Health Canada and the FSSAI enforce parallel labeling standards that shape which sweetener systems gain market access in North America and India respectively. Stakeholders must monitor evolving clean-label definitions and regional maximum-per-serving limits for sugar alcohols, as these standards increasingly determine which formulations qualify for premium positioning versus commodity classification.
Market Dynamics
Regulatory pressure from FDA and EFSA on sugar reduction in children's foods is compressing formulation cycles and forcing manufacturers to abandon artificial sweetener systems faster than supply chains can adapt, creating a structural bottleneck in clean-label ingredient sourcing.
Growth Catalysts
- Pediatric dental protocol adoption:Dental clinics in the United States now stock sugar-free confectionery as standard preventive care, embedding lollipops into professional recommendation channels that conventional candy cannot access.
- EFSA polyol guidelines:Maximum intake thresholds for sugar alcohols in Europe validate dental-health positioning, giving xylitol and erythritol formulations regulatory credibility that accelerates pharmacy channel penetration.
- Private-label pharmacy expansion:Wellness-oriented retail chains in the United States are building dedicated sugar-free confectionery sets, creating shelf-space momentum that pulls manufacturer investment toward compliant formulations.
Market Restraints
- Xylitol supply concentration:Birch wood and corn cob feedstock dependence on Chinese and Finnish processing capacity exposes margin stability to agricultural commodity volatility and freight cost spikes.
- Clean-label cost premium:Natural sweetener systems carry 40-60% higher ingredient costs versus sucralose or aspartame, compressing profitability in price-sensitive mass retail segments.
- Technical mouthfeel limitations:Erythritol's cooling effect and stevia's bitter aftertaste require expensive masking technologies that smaller manufacturers cannot afford, constraining competitive entry.
Strategic Opportunities
- Indian regulatory opening:FSSAI labeling standardization for sugar-free claims remains underdeveloped, creating first-mover advantage for brands establishing compliant formulations before enforcement tightens.
- Functional ingredient convergence:Probiotic and vitamin fortification combined with xylitol bases is automating new product development pipelines that command pharmacy-tier pricing.
- Direct-to-dental distribution:Bypassing traditional retail through practice-exclusive SKUs locks in professional endorsement and insulates pricing from grocery channel margin pressure.
Industry Challenges
- Formulation talent scarcity:Food scientists with dual expertise in polyol stabilization and clean-label sensory engineering command premium compensation that strains mid-tier manufacturer R&D budgets.
- Certification timeline compression:Dental health certification from recognized oral health bodies requires 18-24 month clinical validation cycles that delay premium positioning and tie up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Free Lollipops Market |
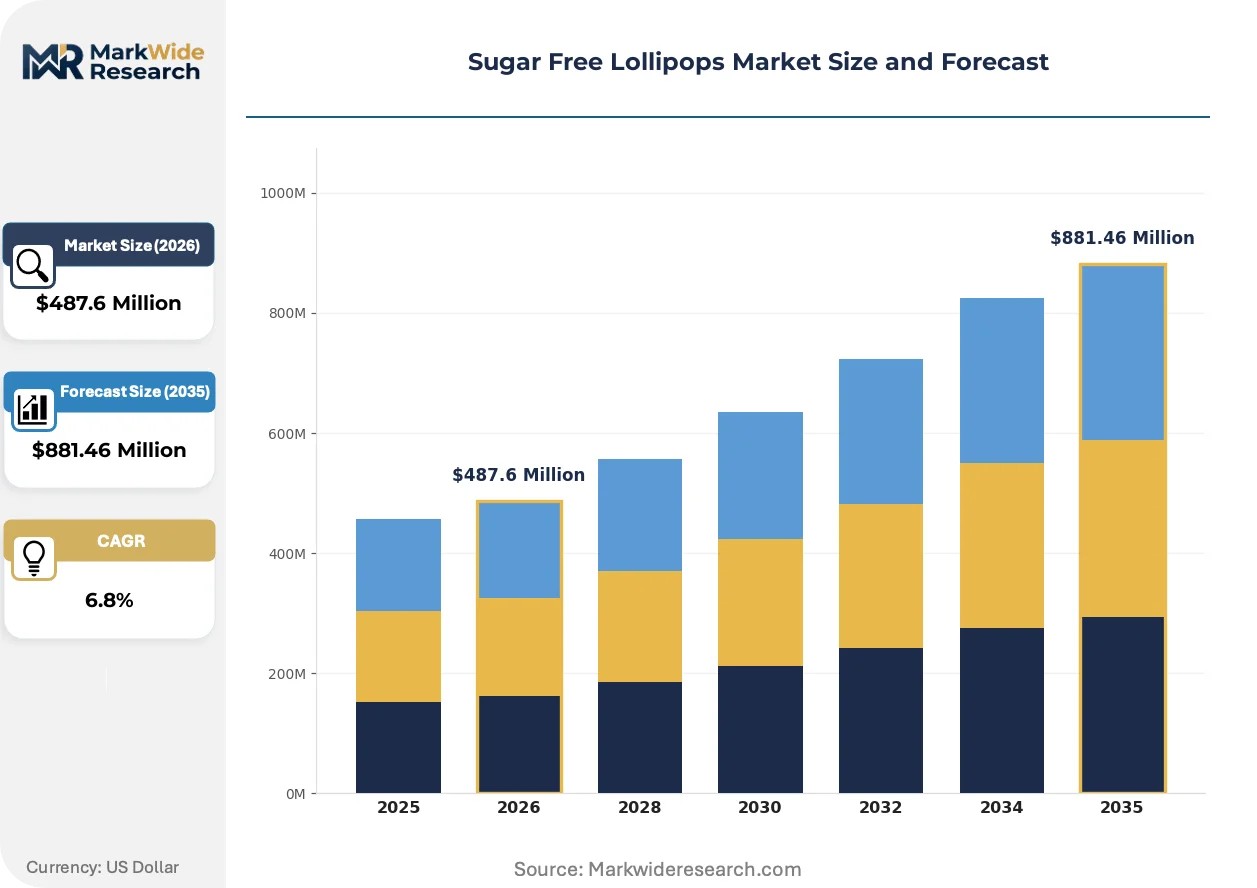
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Candy, Hard Candy, Chewy Candy, Novelty Candy Ingredient Type: Artificial Sweeteners, Natural Sweeteners, Sugar Alcohols, Flavoring Agents Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Stores Consumer Type: Children, Adults, Health-Conscious Consumers, Diabetics |
| Companies Covered | Perfetti Van Melle Company, Zolli Lollipops, Chupa Chups, Nestlé S.A., The Hershey Company, Mars, Koochikoo, Hsu Fu Chi, Jelly Belly Candy Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Free Lollipops Market Evolving Landscape
Clean-label automation and regulatory harmonization are compressing the gap between formulation innovation and commercial deployment, while channel specialization fragments how value capture distributes across the value chain.
Continuous manufacturing systems using real-time near-infrared spectroscopy are automating polyol blending precision that previously required batch-wise laboratory verification. Mid-sized confectionery producers in Germany and the Netherlands are adopting these systems to reduce yield loss from crystallization defects. This automation is compressing the cost gap between artisan-scale and industrial-scale sugar-free production.
REACH registration requirements for novel sweetener molecules are tightening purity thresholds that European suppliers must meet before market entry. The industrial consequence is a consolidation of approved supplier lists among major manufacturers, who now demand full supply chain disclosure. Chewy candy formats containing erythritol are most affected, as residual solvent specifications now require additional purification investments.
Subscription-based replenishment models through pediatric dental practices are displacing conventional retail purchase cycles for preventive confectionery. Parents in suburban United States markets are accepting auto-ship arrangements tied to six-month checkup schedules. This channel innovation is most visible in Texas and Florida, where dental practice consolidation creates centralized procurement leverage that individual retailers cannot match.
Sugar Free Lollipops Market Segmentation
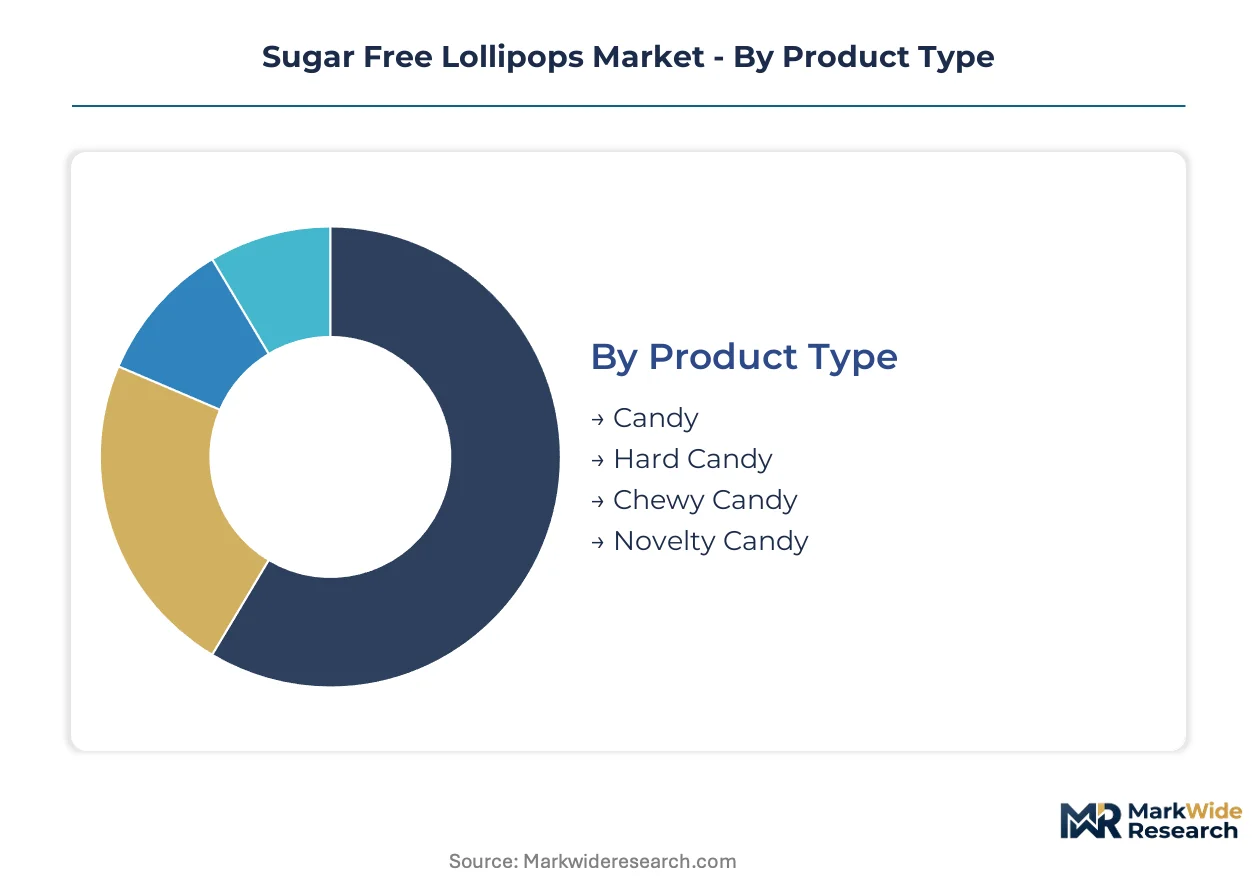
Sugar-free lollipop manufacturers navigate divergent certification requirements across pediatric dental, pharmacy, and mass retail channels. Each segment demands distinct formulation investments that reshape margin structures and competitive entry barriers.
Product Type:
Dental health certifications from recognized oral health bodies constrain which product formats qualify for professional channel placement, with hard candy and chewy formats facing divergent stability validation protocols.
- Hard Candy:Crystalline polyol matrices deliver extended shelf stability exceeding 24 months under ambient conditions. Pharmacy chains in the United States prioritize this format for dental practice dispensing due to minimal moisture sensitivity and straightforward xylitol content verification. EFSA maximum intake guidelines for sugar alcohols are easier to communicate on single-serve hard candy packaging.
- Chewy Candy:Hydrophilic gum bases require humectant systems that complicate clean-label positioning. Adult consumers in Germany and the Netherlands drive repeat purchase through texture preference, though erythritol cooling effects demand expensive masking investments that constrain smaller manufacturers.
- Candy:General confectionery formats without specialized dental positioning compete on price through sucralose formulations in mass retail.
- Novelty Candy:Shaped and themed products target gift occasions with premium positioning that absorbs higher natural sweetener costs.
Leading the category by volume: Hard Candy. Growing fastest: Chewy Candy.
Ingredient Type:
Cost tier stratification separates premium pharmacy positioning from commodity mass retail, with ingredient selection directly determining channel access and pricing power.
- Sugar Alcohols:Xylitol and erythritol formulations command pharmacy-tier margins through dual dental-health and clean-label positioning. Birch wood and corn cob feedstock dependence on Chinese and Finnish processing capacity exposes supply stability to agricultural commodity volatility. FDA food additive provisions and EFSA polyol guidelines validate safety claims that accelerate professional endorsement.
- Natural Sweeteners:Stevia and monk fruit extracts carry 40-60% higher ingredient costs versus artificial alternatives. Wellness-oriented retailers in the United States build dedicated sets around these formulations, though bitter aftertaste issues require expensive sensory engineering that strains mid-tier R&D budgets.
- Artificial Sweeteners:Sucralose and aspartame systems dominate price-sensitive mass retail segments where clean-label positioning is not required.
- Flavoring Agents:Natural flavor systems complete clean-label profiles but face REACH registration purity thresholds in Europe that consolidate approved supplier lists.
Highest margin capture: Sugar Alcohols. Steepest expansion trajectory: Natural Sweeteners.
Distribution Channel:
Volume concentration in pharmacy and grocery channels is reshaping how manufacturers allocate formulation investments and certification resources.
- Supermarkets:Mainstream grocery distribution demands shelf-space control capabilities that favor established manufacturers with trade marketing budgets. Private-label pharmacy chains in the United States increasingly cross-list sugar-free confectionery in grocery adjacent sets.
- Specialty Stores:Wellness-focused retailers curate premium assortments that absorb clean-label cost premiums through educated consumer self-selection.
- Online Retail:Direct-to-consumer models enable subscription-based replenishment tied to pediatric dental checkup schedules in suburban United States markets.
- Convenience Stores:Impulse-oriented formats favor single-serve hard candy with minimal certification burden and straightforward price positioning.
Dominant volume channel: Supermarkets. Fastest channel expansion: Online Retail.
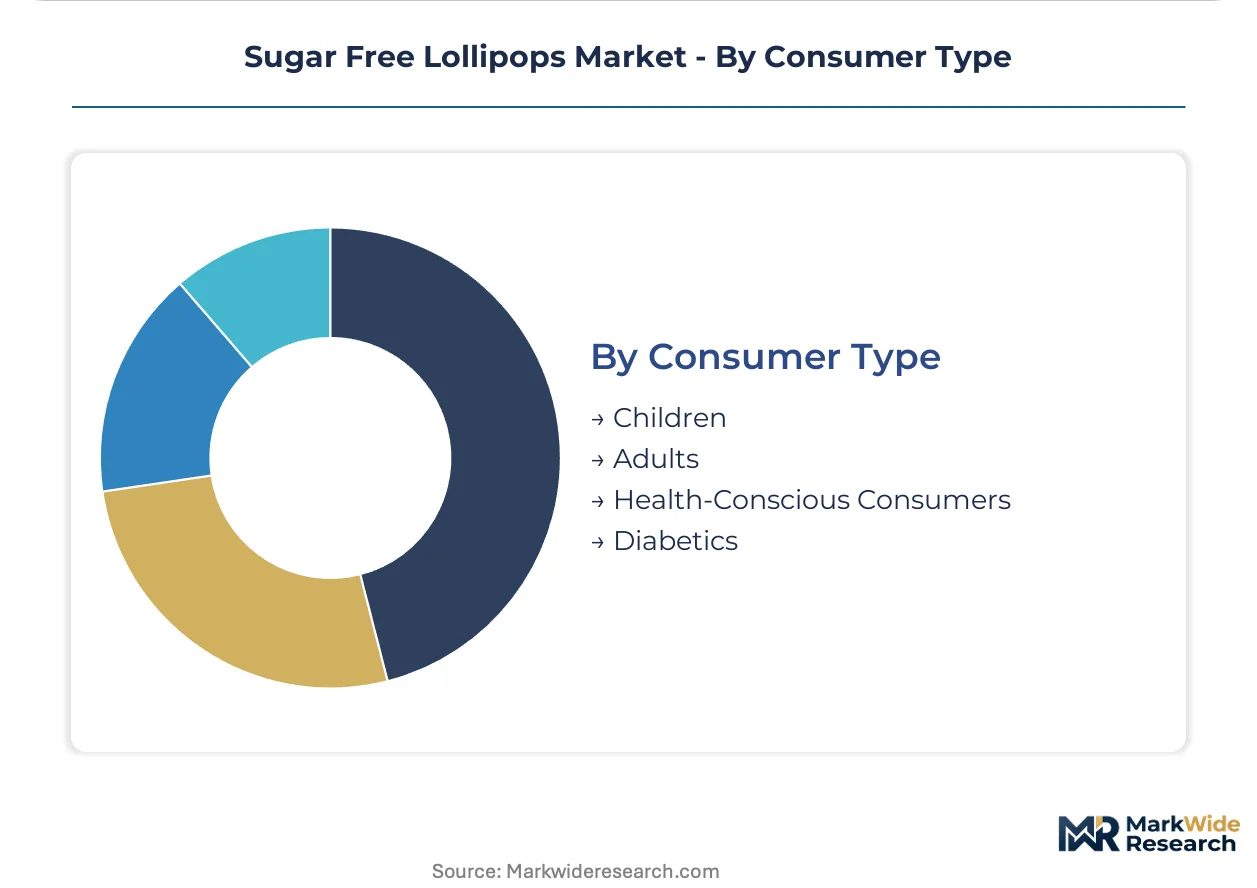
Consumer Type:
Application-specific demand from dental protocol adoption and diabetes management creates divergent product requirements that fragment formulation standardization.
- Children:Pediatric dental clinic stocking as standard preventive protocol embeds lollipops into professional recommendation channels. Parents accept auto-ship arrangements through practice-exclusive SKUs that insulate pricing from grocery margin pressure.
- Health-Conscious Consumers:Clean-label rejection of artificial alternatives drives natural sweetener demand despite 40-60% cost premiums.
- Adults:Texture preference for chewy formats supports repeat purchase behavior, particularly in German and Dutch markets.
- Diabetics:Glycemic impact minimization requires precise polyol labeling that FDA regulations enforce through food additive provisions.
Largest addressable base: Children. Fastest-growing targeting: Health-Conscious Consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American sugar-free confectionery distribution, with pharmacy chain consolidation driving procurement centralization from this logistics hub.
United States
Pediatric dental clinics in Texas and Florida embed sugar-free lollipops into preventive care protocols through auto-ship arrangements tied to six-month checkup schedules. FDA food additive provisions enforce precise polyol labeling that validates dental-health positioning for pharmacy-tier products. Private-label pharmacy chains in suburban markets build dedicated sugar-free sets that pull manufacturer investment toward compliant formulations.
Germany
Adult consumers in German metropolitan areas drive repeat purchase of chewy candy formats despite erythritol cooling effects requiring expensive masking investments. EFSA maximum intake guidelines for sugar alcohols give xylitol formulations regulatory credibility that accelerates pharmacy channel penetration. Mid-sized confectionery producers in the Netherlands and western Germany adopt continuous manufacturing systems using real-time near-infrared spectroscopy to reduce yield loss from crystallization defects.
India
FSSAI labeling standardization for sugar-free claims remains underdeveloped, creating first-mover advantage for brands establishing compliant formulations before enforcement tightens. Health-conscious parents in urban centers accept 40-60% cost premiums for natural sweetener systems despite mid-tier R&D budget constraints. Maharashtra-based distributors are expanding into pharmacy-adjacent retail formats that mirror United States wellness-oriented channel development.
China
Birch wood and corn cob feedstock dependence on Chinese processing capacity exposes global margin stability to agricultural commodity volatility and freight cost spikes. SAMR food safety standards shape which sweetener systems gain market access for domestic consumption versus export production. Processing clusters in Shandong Province concentrate xylitol refining capacity that supplies formulation inputs to European and North American manufacturers.
Sugar Free Lollipops Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and sweetener-system dimensions, with dental-health credentials separating pharmacy-tier positioning from mass retail price competition. The vendor base spans multinational confectionery conglomerates with shelf-space control capabilities, specialized pediatric dental channel operators, and regional private-label suppliers. Three archetypes dominate: certification-anchored premium specialists, scale-driven cost optimizers, and channel-exclusive niche operators. Competitive moves concentrate on professional endorsement lock-in through practice-exclusive SKUs and backward integration into polyol supply to defend input cost stability.
Within the certification-anchored tier, Zolli Lollipops and Perfetti Van Melle Company exemplify divergent scale approaches to dental-channel positioning. The Hershey Company occupies a position reflecting mainstream grocery distribution capabilities that trade professional endorsement access for volume reach. These three entities represent the spectrum from niche professional-channel specialization through hybrid mass-premium positioning to conventional retail dominance.
| Leading Market Players |
|---|
| Perfetti Van Melle Company |
| Zolli Lollipops |
| Chupa Chups |
| Nestlé S.A. |
| The Hershey Company |
| Mars |
| Koochikoo |
| Hsu Fu Chi |
| Jelly Belly Candy Company |
| Others |
Value Network & Pricing Analysis
Backward integration into birch wood and corn cob processing anchors both supply security and margin defense for xylitol-dependent manufacturers. Finnish and Chinese refining capacity concentration creates pricing power asymmetries that favor scale players with captive offtake agreements over spot-market buyers.
Pricing Analysis
Dental-health outcome pricing anchors pharmacy-tier premiums, with cavity-prevention certifications commanding 40-60% markups over mass retail alternatives. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-validated xylitol formulations from sucralose commodity candy. Cost compression in artificial sweetener tiers is intensifying because private-label pharmacy chains squeeze manufacturer margins through volume consolidation. Parents purchasing through pediatric dental practices show least price sensitivity, while convenience store impulse buyers drive hardest bargain negotiations.
Supply Chain Analysis
Direct-to-dental distribution channels handle preventive care demand through practice-exclusive SKUs that bypass traditional retail markup layers. Raw material sourcing draws from Chinese Shandong Province processing clusters and Finnish birch refining operations for xylitol feedstock. Erythritol production rests on corn cob agricultural cycles exposed to commodity volatility and freight cost spikes. Single-source vulnerability in polyol purification capacity threatens margin stability when REACH registration requirements tighten purity thresholds. Distribution runs through pharmacy chain consolidation hubs in Chicago and regional wellness retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Xylitol feedstock concentration in Chinese and Finnish processing capacity props pricing power for integrated manufacturers while stranding mid-tier competitors on volatile spot markets.
For Market Incumbents: Hedge margin exposure through long-term offtake contracts with Shandong Province refiners before agricultural commodity cycles spike input costs. Secure dental health certification from recognized oral health bodies to lock professional endorsement channels against emerging clean-label competitors. Reinforce pharmacy shelf-space control through exclusive SKU arrangements that insulate pricing from grocery channel consolidation pressure. For New Entrants and Emerging Players: Pediatric dental practices in Texas and Florida represent the most penetrable channel white-space, where auto-ship subscription models tied to six-month checkup schedules displace conventional retail purchase cycles. Target FSSAI labeling standardization gaps in India before enforcement tightens and first-mover advantage evaporates. Lead with natural sweetener formulations positioned for wellness-oriented retail sets that absorb clean-label cost premiums through educated consumer self-selection. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by multinational confectionery conglomerates seeking dental-channel certification assets and polyol supply chain control. Mid-term viability hinges on formulation talent scarcity creating defensive moats around R&D-capable targets. Watch for EFSA maximum intake guideline revisions as inflection indicator that could reclassify premium positioning eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Dental Health Certification Investment | 18-24 month clinical validation cycles from oral health bodies unlock pharmacy-tier pricing and professional endorsement channels. |
| Backward Integration into Polyol Supply | Captive xylitol refining capacity in Shandong Province or Finnish birch operations defends input cost stability against agricultural volatility. |
| Direct-to-Dental Distribution Launch | Practice-exclusive SKUs bypass grocery channel margin pressure and embed products into preventive care protocols. |
| Natural Sweetener Formulation Pivot | Stevia and monk fruit systems access wellness-oriented retail sets despite 40-60% ingredient cost premiums over artificial alternatives. |
| Continuous Manufacturing Adoption | Real-time near-infrared spectroscopy systems in German and Dutch facilities reduce crystallization defect yield loss and compress artisan-industrial cost gaps. |
Research Methodology
Multi-period observation of pediatric dental clinic stocking rates, pharmacy chain SKU expansion, and sweetener system formulation shifts anchored the trend analysis, supplemented by interviews with confectionery R&D directors, pharmacy category buyers, dental practice procurement managers, and polyol supply chain specialists. Secondary validation drew from FDA food additive filings, EFSA polyol guideline documentation, FSSAI labeling standards, and customs records tracking birch wood and corn cob derivative trade flows. Bottom-up volume modeling across product type, ingredient system, and distribution channel dimensions triangulated against top-down market sizing.
Input-output matrices mapped formulation cost structures through production value chains, with segmentation dimensions covering hard versus chewy candy formats, sugar alcohol versus natural versus artificial sweetener tiers, and dental-pharmacy-grocery channel stratification. CAGRs across the analysis window derived from elasticity-adjusted demand projections incorporating regulatory enforcement timelines and professional endorsement adoption curves. Forecast inputs included REACH registration purity threshold evolution and continuous manufacturing technology diffusion rates among mid-sized European producers.
Caveats apply where EFSA polyol guideline revisions, FSSAI enforcement tightening, or xylitol feedstock agricultural disruption could materially shift the outlook. Forecasts reflect documented assumptions on clean-label consumer preference stickiness and dental practice consolidation trajectories. Periodic stress-testing of base assumptions against regulatory notification timelines and commodity cycle turning points is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Chocolate Inclusions and Decorations Market
Confectionery
United States Caramel Chocolate Market
Confectionery
Caramel Market
Confectionery
China Chocolate Market
Confectionery
India Chocolate Market
Confectionery
Global Confectionery Market
Confectionery
Low-Calorie Dark Chocolate Market
Confectionery
Jellies and Gummies Market
Confectionery
Sugar-Free Chocolate Market
Confectionery
Vegan Candies Market
Confectionery
Sugar-Free Gumballs Market
Confectionery
Low-Calorie Chocolate Market
Confectionery
Xylitol Lollipops Market
Confectionery
United States and Europe Macarons Market
Confectionery
Fruit Jellies Market
Confectionery
US Dark Chocolate Market