
 Edible Halal Gelatin Market | 2026-2036
Edible Halal Gelatin Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Halal Gelatin Market Insights
Enzymatic extraction and membrane filtration is fragmenting traditional acid-alkali processing lines across halal gelatin facilities. Rousselot leverages its European rendering network to secure bovine hides certified by multiple halal authorities. Gelita AG sustains R&D intensity in cold-water soluble variants for confectionery applications. Nitta Gelatin Inc. anchors its competitive position through backward integration into Japanese abattoir partnerships.
Edible halal gelatin denotes collagen hydrolysate derived from halal-slaughtered bovine, ovine, or piscine sources, processed to achieve bloom strengths between 50 and 300 g for food and pharmaceutical binding. The material functions primarily as a gelling, stabilizing, and encapsulating agent in dosage forms and processed foods. Powdered gelatin dominates volume throughput due to its handling efficiency in industrial batching, while capsule gelatin commands premium positioning through pharmacopeial-grade certification requirements. Confectionery applications remain mature with stable offtake, whereas nutraceuticals represents the fastest-expanding application as soft-gel and hard-shell halal supplement formats multiply.
Halal certification bodies including JAKIM in Malaysia, MUI in Indonesia, and the Halal Food Council of Europe operate alongside national regulators such as FDA and EMA to enforce species traceability and slaughter compliance. These layered standards create significant compliance costs that filter smaller traders from approved-supplier lists. Stakeholders must monitor evolving blockchain-based halal provenance platforms that threaten to displace paper-based chain-of-custody documentation.
Market Dynamics
Enzymatic extraction technology is fragmenting traditional acid-alkali processing lines across halal gelatin manufacturing, forcing capital retooling decisions while EMA and FDA traceability mandates reshape supplier qualification protocols worldwide.
Growth Catalysts
- EMA traceability mandates:Tightened documentation requirements for pharmaceutical-grade gelatin are filtering non-compliant traders from approved-supplier lists, consolidating demand around certified processors.
- Nutraceutical soft-gel expansion:Southeast Asian supplement manufacturers are scaling halal-certified capsule programs to serve Muslim-majority populations and export markets.
- Indonesia-Malaysia import concentration:These two markets now absorb the majority of new halal gelatin import volumes, pulling supply chain investments toward Southeast Asian distribution nodes.
Market Restraints
- Bovine hide input volatility:Rendering supply fluctuations and feedstock competition from pet food and leather industries create margin pressure for gelatin processors dependent on cattle byproducts.
- Multi-layered certification costs:JAKIM, MUI, and Halal Food Council of Europe standards impose overlapping audit and documentation burdens that smaller traders cannot absorb.
- Pectin and carrageenan substitution:Plant-based hydrocolloids are capturing confectionery applications where gelatin functionality is not strictly required, compressing addressable market scope.
Strategic Opportunities
- Blockchain provenance platforms:Distributed ledger systems for halal chain-of-custody documentation threaten to displace paper-based certification, creating first-mover advantages for early adopters.
- Cold-water soluble variants:Functional gelatin grades for ambient-temperature confectionery processing address unmet needs in tropical climate manufacturing.
- Japanese abattoir partnerships:Backward integration into controlled livestock sourcing enables premium positioning for pharmaceutical-grade material with full species traceability.
Industry Challenges
- Halal slaughter compliance expertise:Shortages of certified Islamic slaughter supervisors and veterinary auditors extend certification timelines and limit production scale-up.
- Membrane filtration capex requirements:Enzymatic extraction lines demand substantial upfront investment in ultrafiltration and nanofiltration equipment, straining mid-tier processor balance sheets.
- Cross-certification reciprocity gaps:Non-recognition between JAKIM, MUI, and European halal bodies forces redundant audits for exporters serving multiple markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Halal Gelatin Market |
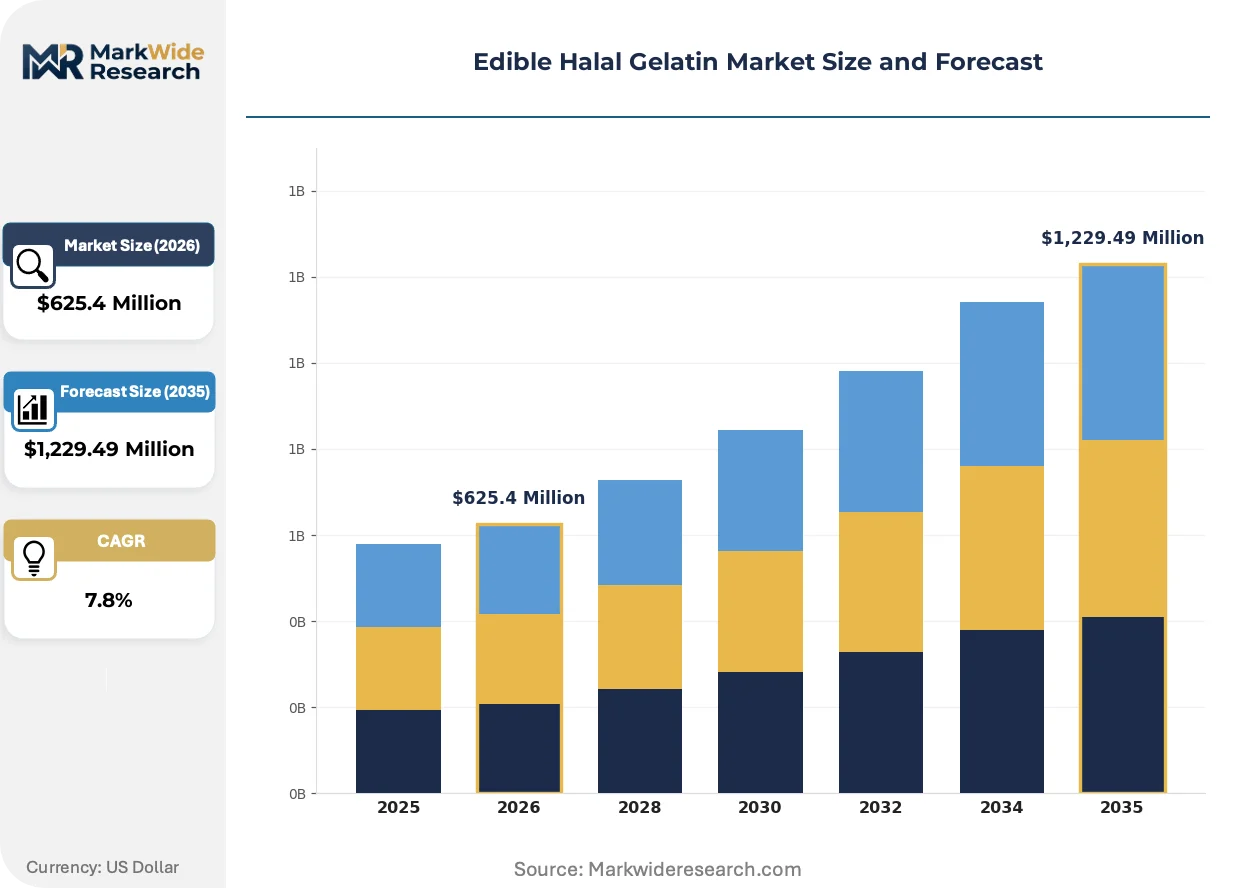
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $1,229.49 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Gelatin, Sheet Gelatin, Granulated Gelatin, Capsule Gelatin Application: Confectionery, Dairy Products, Nutraceuticals, Pharmaceuticals End User: Food Manufacturers, Cosmetic Companies, Dietary Supplement Providers, Pharmaceutical Firms Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Gelita AG, Rousselot, Nitta Gelatin Inc., Tessenderlo Group, Weishardt Group, PB Gelatins, Foodmate Co., Ltd, Xiamen Gelken Gelatin, Henan Boom Gelatin Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Halal Gelatin Market Trends and Innovations
Halal gelatin manufacturing is experiencing convergent pressures from digital traceability systems, tightening pharmaceutical regulations, and evolving buyer procurement models that favor certified supply partnerships over spot-market purchasing.
Blockchain-based halal provenance platforms are digitizing chain-of-custody documentation across multi-node supply networks. Pharmaceutical manufacturers and large-scale confectionery groups are piloting these systems to preempt EMA and FDA audit demands. The technology is digitizing compliance verification, compressing documentation timelines from weeks to hours while creating data monopolies for platform operators.
REACH and EU Green Deal sustainability disclosure requirements are extending to imported gelatin and collagen derivatives. European pharmaceutical and food manufacturers must now document environmental footprints across their halal supply chains, forcing Southeast Asian processors to adopt carbon accounting and wastewater treatment upgrades. Nutraceutical capsule applications face the steepest compliance gradients due to pharmacopeial-grade purity requirements.
Certification-driven procurement consolidation is replacing spot-market purchasing among large pharmaceutical and nutraceutical buyers. Long-term offtake agreements with single-source halal-certified suppliers are displacing fragmented multi-source buying patterns. This shift is most pronounced in Indonesia and Malaysia, where JAKIM and MUI certification is becoming a non-negotiable qualification criterion for contract awards.
Edible Halal Gelatin Market Segmentation
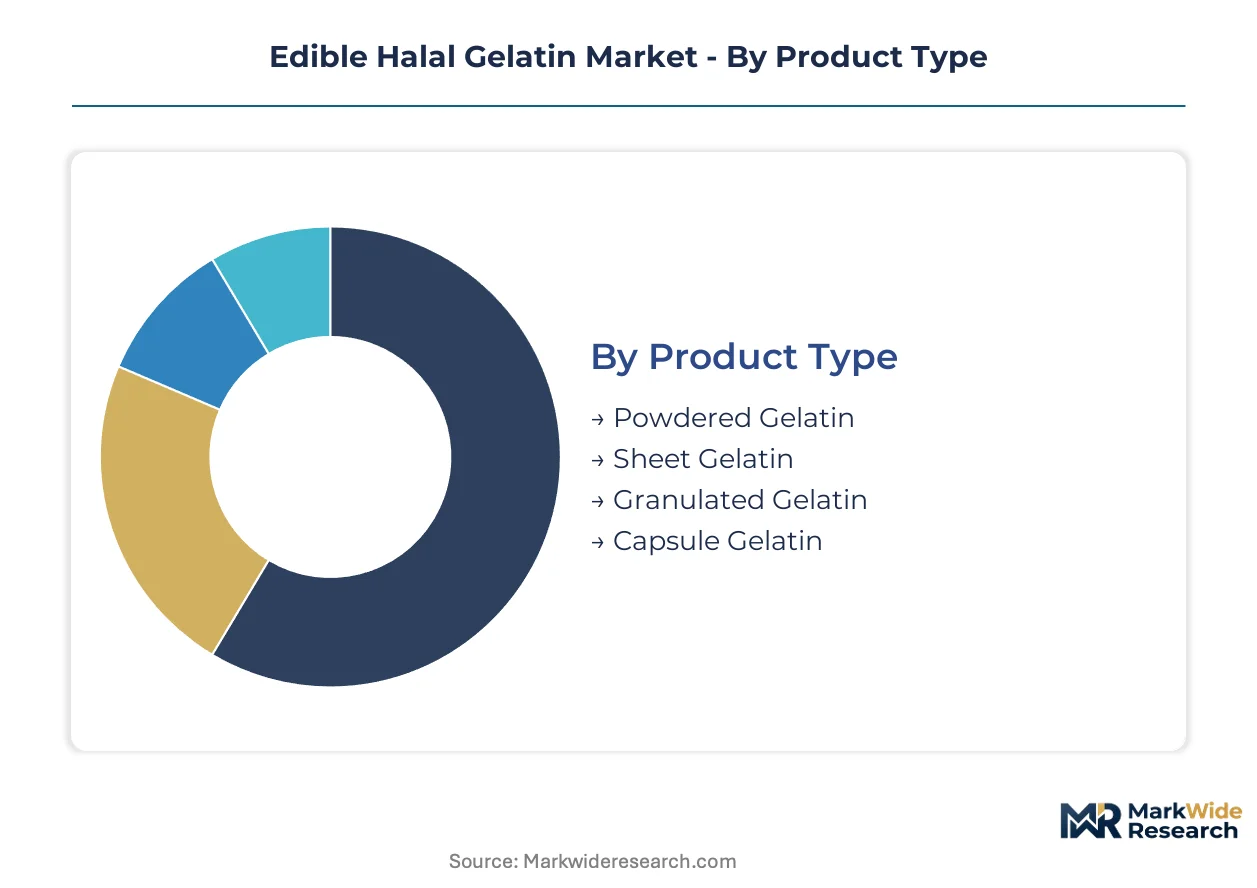
Segmentation in edible halal gelatin reveals how certification requirements, processing specifications, and buyer procurement models fragment demand across distinct value tiers. Each category carries different compliance burdens and margin profiles that reshape supplier positioning.
Product Type:
After-sales service intensity varies sharply across product formats, with pharmaceutical-grade capsule gelatin demanding dedicated technical support for dissolution validation and bloom strength calibration.
- Powdered Gelatin:Fine-mesh collagen hydrolysate with bloom strengths ranging 50-300 g dominates industrial batching due to handling efficiency and rapid hydration. Food manufacturers in Indonesia and Malaysia absorb the majority of volume for confectionery and dairy stabilizer applications. Powdered formats require minimal technical support beyond certificate of analysis documentation.
- Capsule Gelatin:Pharmacopeial-grade material meeting USP-NF and EP monographs commands premium positioning through enhanced viscosity control and endotoxin limits. Pharmaceutical firms in Southeast Asia and Europe drive demand for two-piece hard-shell and soft-gel encapsulation, with JAKIM and MUI certification becoming mandatory for contract awards.
- Sheet Gelatin:Pre-portioned leaf format preferred by artisan confectioners and premium dessert manufacturers for precise gelling control without weighing equipment.
- Granulated Gelatin:Intermediate particle size offering faster dissolution than sheets with less dusting than powders, serving mid-scale food processors.
By volume, Powdered Gelatin leads. By growth pace, Capsule Gelatin is ahead.
Application:
Cost tier stratification separates mature confectionery demand from emerging nutraceutical opportunities where halal certification carries price premiums.
- Nutraceuticals:Soft-gel and hard-shell supplement formats represent the steepest expansion trajectory as Southeast Asian manufacturers scale halal-certified capsule programs for domestic and export markets. Dietary supplement providers in Malaysia and Indonesia require full species traceability and blockchain-ready documentation to satisfy EMA and FDA audit protocols.
- Pharmaceuticals:Encapsulation-grade gelatin for prescription and over-the-counter dosage forms demands the highest purity tiers with endotoxin and microbial limits enforced by national pharmaceutical regulators. European and Southeast Asian drug manufacturers are consolidating procurement around single-source certified suppliers with multi-authority halal recognition.
- Confectionery:Mature demand for gummies, marshmallows, and aerated desserts faces substitution pressure from pectin and carrageenan in cost-sensitive applications.
- Dairy Products:Stabilizer applications in yogurt, cream, and processed cheese maintain steady offtake with lower certification stringency than pharmaceutical grades.
Confectionery retains volume dominance. Nutraceuticals climbs fastest.
End User:
Customer type determines procurement sophistication, with pharmaceutical and supplement firms imposing qualification protocols that exclude spot-market traders.
- Pharmaceutical Firms:Multinational and regional drug manufacturers enforce long-term offtake agreements with single-source halal-certified processors. These buyers require EMA traceability documentation, JAKIM or MUI certification, and validated blockchain provenance systems for audit readiness.
- Dietary Supplement Providers:Southeast Asian soft-gel and hard-shell manufacturers represent the fastest-expanding customer segment, scaling halal capsule production for Muslim-majority populations and export markets.
- Food Manufacturers:Confectionery and dairy processors prioritize cost efficiency and handling characteristics over multi-authority certification, though JAKIM compliance is becoming standard for Indonesian market access.
- Cosmetic Companies:Niche demand for halal-certified gelatin in skincare and personal care applications remains limited by plant-based ingredient preferences.
Food Manufacturers move the most volume. Dietary Supplement Providers expand most quickly.
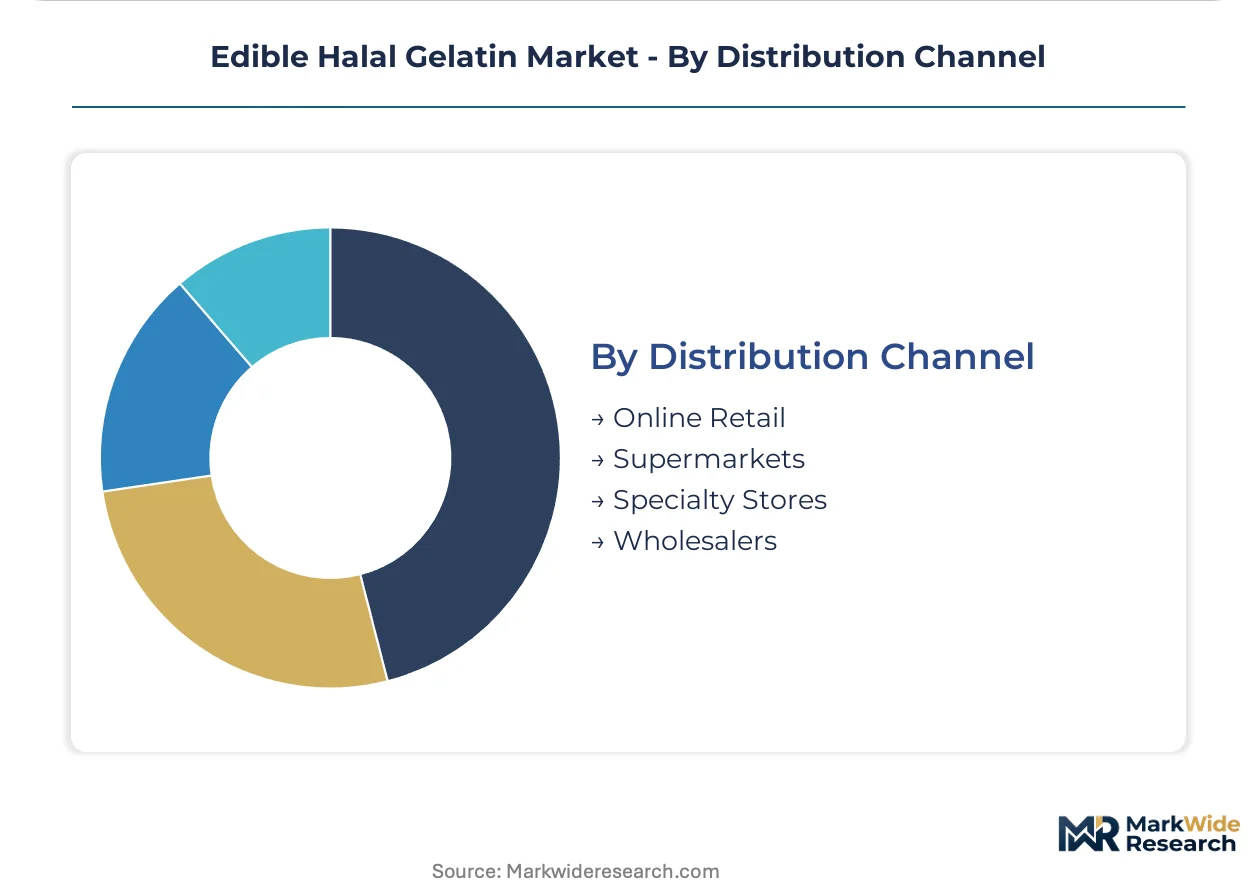
Distribution Channel:
Supply concentration favors direct wholesale relationships for industrial volumes, while specialty formats fragment through targeted retail channels.
- Wholesalers:Bulk industrial distribution dominates volume throughput, connecting certified processors directly to pharmaceutical and food manufacturing facilities. These channels carry mandatory halal documentation and certificate of analysis for every lot.
- Specialty Stores:Professional-grade gelatin for artisan confectioners and small-batch food processors requires technical consultation on bloom strength selection and hydration protocols.
- Online Retail:E-commerce penetration remains limited by certification verification challenges and temperature-controlled shipping requirements for sheet and granulated formats.
- Supermarkets:Consumer-packaged gelatin for home baking represents minimal share in halal-certified segments due to price competition with conventional products.
Wholesalers lead by volume. Specialty Stores gain share fastest among non-industrial channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia and Malaysia now absorb the majority of new halal gelatin import volumes, pulling supply chain investments toward Southeast Asian distribution nodes while European processors reroute exports to serve tightened EMA traceability mandates.
Indonesia
MUI certification requirements and expanding nutraceutical soft-gel manufacturing are driving import demand. The national pharmaceutical regulator enforces species traceability rules aligned with EMA documentation standards. Jakarta and Surabaya host concentrated capsule production facilities serving domestic supplement brands and export markets.
Malaysia
JAKIM halal standards and pharmaceutical-grade capsule programs are consolidating procurement around certified processors. REACH and EU Green Deal sustainability disclosure requirements extend to imported gelatin derivatives. Penang and Selangor industrial zones concentrate backward-integrated gelatin processing with abattoir partnerships.
Germany
EMA traceability mandates and pharmacopeial-grade purity requirements are filtering non-compliant traders from approved-supplier lists. The EU Green Deal carbon accounting rules force Southeast Asian processors to document environmental footprints. Bavaria and North Rhine-Westphalia anchor rendering networks supplying bovine hide feedstock to gelatin facilities.
United States
FDA tightening of gelatin traceability rules is reshaping supplier qualification protocols for pharmaceutical encapsulation. Dietary supplement manufacturers require blockchain-ready documentation for audit preparedness. New Jersey and California pharmaceutical corridors drive demand for halal-certified capsule gelatin with full species verification.
Japan
PMDA pharmaceutical regulations and cold-water soluble gelatin R&D are sustaining premium positioning for technical-grade materials. METI industrial standards support enzymatic extraction technology adoption. Osaka and Tokyo metropolitan areas concentrate abattoir partnerships enabling controlled livestock sourcing with full halal compliance.
Edible Halal Gelatin Market Competitive Landscape
On the supply side, the industry is consolidating around multi-authority certified processors with the capital to absorb overlapping audit burdens from JAKIM, MUI, and European halal bodies. Three strategic archetypes dominate: European rendering-integrated multinationals, Asian backward-integrated specialists, and Chinese scale-driven exporters. Competitive moves center on enzymatic extraction capacity expansion and blockchain provenance platform partnerships.
Within the European integrated tier, Gelita AG and Rousselot exemplify archetypes combining rendering network control with multi-certification compliance. Among Asian specialists, Nitta Gelatin Inc. occupies a position representing backward integration into controlled livestock sourcing. These three entities anchor the competitive structure, with Chinese manufacturers including Xiamen Gelken Gelatin and Henan Boom Gelatin Co., Ltd. representing scale-driven export positioning.
| Leading Market Players |
|---|
| Gelita AG |
| Rousselot |
| Nitta Gelatin Inc. |
| Tessenderlo Group |
| Weishardt Group |
| PB Gelatins |
| Foodmate Co., Ltd |
| Xiamen Gelken Gelatin |
| Henan Boom Gelatin Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Bovine hide input volatility determines both the spread between pharmaceutical-grade premiums and food-grade baselines and the geographic clustering of rendering-integrated processors. Feedstock competition from pet food and leather industries compresses margins for non-integrated traders while consolidating pricing power among backward-integrated multinationals with captive abattoir supply.
Pricing Analysis
Acid-alkali processing lines face pricing pressure from enzymatic extraction capacity expansions that command 15-25% premiums for cold-water soluble grades. Three-tier pricing structure across pharmacopeial capsule gelatin, industrial food-grade powder, and artisan sheet formats reflects JAKIM-MUI certification depth and bloom strength calibration. Cost compression in standard food-grade tiers intensifies because pectin and carrageenan substitution erodes volume leverage. Pharmaceutical firms show least price sensitivity due to EMA traceability mandates that disqualify uncertified suppliers.
Supply Chain Analysis
Extended payment terms from Indonesian and Malaysian nutraceutical manufacturers strain working capital for mid-tier processors without supply-chain finance facilities. Geographic supply concentration centers on Germany, Japan, and China for pharmaceutical-grade output, with Indonesia and Malaysia dominating import demand growth. Raw material dependencies draw from bovine hides, ovine skins, and piscine collagen feedstocks. Single-source vulnerability runs through JAKIM-certified rendering networks in Penang and Selangor. Distribution runs through direct wholesale relationships with pharmaceutical and food manufacturing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edible halal gelatin sits in early-cycle expansion as Southeast Asian nutraceutical soft-gel manufacturing scales halal-certified capsule programs for export penetration. This adoption tailwind justifies capacity investments ahead of demand maturation.
For Market Incumbents: Insulate core pharmaceutical-grade positioning through captive abattoir partnerships in Japan and Malaysia that preempt EMA species traceability audits. Deepen backward integration into rendering networks to offset bovine hide volatility. Acquire blockchain provenance platform capabilities before paper-based certification becomes obsolete. For New Entrants and Emerging Players: Underpenetration in cold-water soluble gelatin for tropical climate confectionery offers white-space entry with lower certification barriers than pharmaceutical tiers. Target Indonesian dairy stabilizer applications where JAKIM compliance is becoming standard but multi-authority recognition remains sparse. Pursue enzymatic extraction joint ventures with established membrane filtration equipment suppliers to bypass capital-intensive greenfield builds. For Investors and Strategic Acquirers: FDA tightening of gelatin traceability rules reshapes the acquisition landscape toward processors with pre-validated blockchain documentation and multi-authority halal recognition. Long-term viability favors targets with demonstrated EMA audit readiness and Southeast Asian distribution nodes. The signal to watch is cross-certification reciprocity agreements between JAKIM, MUI, and European halal bodies that would eliminate redundant audit costs for portfolio companies.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Capacity Expansion | Cold-water soluble output from membrane filtration lines commands pharmaceutical-grade premiums in tropical markets. |
| Backward Integration into Abattoir Partnerships | Controlled livestock sourcing enables full species traceability required by EMA and FDA audit protocols. |
| Blockchain Provenance Platform Adoption | Distributed ledger documentation compresses JAKIM certification timelines from weeks to hours for audit readiness. |
| Multi-Authority Halal Certification Investment | Simultaneous JAKIM-MUI-European recognition eliminates redundant audits for exporters serving Indonesia and Malaysia. |
| Long-Term Offtake Agreement Structuring | Single-source procurement contracts with pharmaceutical firms displace fragmented spot-market purchasing patterns. |
Research Methodology
Cross-validation between primary interviews with gelatin plant managers, pharmaceutical procurement leads, and halal certification auditors and secondary validation through customs trade data, EMA submission filings, and JAKIM certification registries anchors the qualitative findings. Bottom-up and top-down triangulation reconciles processor capacity disclosures with import volume flows through Indonesian and Malaysian port authorities.
Calibration against historical bloom strength pricing spreads and certification cost trajectories informs the projection framework across the analysis window. Segmentation dimensions modeled include product type, application tier, certification authority, and regional regulatory cluster. CAGRs derive from feedstock cost elasticity estimates and nutraceutical soft-gel demand curves. Industry-specific inputs incorporate enzymatic extraction adoption rates and blockchain provenance platform penetration.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese scale-driven exporters or European rendering-integrated multinationals would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Pea Starch Market
Ingredients
2'-Fucosyllactose (2'-FL) Market
Ingredients
Omega Ingredients Market
Ingredients
Maracuja Oil Market
Ingredients
Food Ingredients Market
Ingredients
Low Fat Cooking Oil Market
Ingredients
Icing Shortening Market
Ingredients
Global Apricot Oil Market
Ingredients
Bean Flour Market
Ingredients
South America Algae Omega-3 Ingredients Market
Ingredients
Global Edible Oil Market
Ingredients
Food Minerals Market
Ingredients
Plant Protein Ingredients Market
Ingredients
Agarwood Oil Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market