
 Anti-Sagging Agents Market | 2026-2036
Anti-Sagging Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Sagging Agents Market Analytics
Specialty chemical distribution channels across Asia-Pacific are reshaping how formulators access anti-sagging agents, with regional distributors consolidating technical service capabilities alongside inventory. BASF SE leverages its integrated polymer backbone to supply acrylic rheology modifiers directly to multinational coatings producers. Evonik Industries AG anchors its position through polyurethane-based additive portfolios that dominate high-performance automotive clearcoat segments. Dow Inc. competes on liquid emulsion technologies that reduce manufacturing complexity for mid-sized paint producers.
Anti-sagging agents are rheology control additives, typically comprising modified acrylic polymers, fumed silica, or organoclays, that build yield stress within liquid coatings to prevent pigment settling and sagging on vertical surfaces during cure. Their primary industrial purpose is maintaining film thickness uniformity in high-build coatings applied to complex geometries. Polyurethane additives command premium positioning in automotive and aerospace applications where thermal stability under bake cycles determines specification compliance. Silicones occupy a narrower but defensible niche in high-temperature industrial maintenance coatings. The emulsions form category is gaining formulation share as waterborne regulatory mandates tighten across OECD jurisdictions.
EPA VOC regulations in the United States, EU REACH restrictions on hazardous substance content, and China's GB standards for architectural coatings collectively constrain solvent-borne formulation options and redirect procurement toward compliant rheology systems. Japan's METI chemical substance reporting requirements add compliance layers for suppliers serving electronics coating applications. Stakeholders must monitor divergence between regional hazard classification protocols, as misalignment between EPA Safer Choice criteria and EU Green Deal chemical sustainability thresholds threatens to fragment product registration strategies and complicate global formulation standardization.
Market Dynamics
Waterborne regulatory mandates across OECD jurisdictions are compressing solvent-borne formulation share and forcing rheology modifier suppliers to rebuild additive architectures around emulsion compatibility and low-VOC performance thresholds.
Growth Catalysts
- EU REACH VOC limits:Stricter volatile organic compound ceilings under EU REACH are compelling automotive OEMs in Germany to expand procurement of rheology-modified coatings, directly expanding specification-grade additive volumes.
- Construction intensity in China and India:Waterborne acrylic formulations for architectural paints are experiencing concentrated demand across China, India, and Southeast Asia as residential and commercial construction activity accelerates.
- Japan METI chemical reporting:METI substance reporting requirements for electronics coatings are layering compliance complexity that favors established additive suppliers with documented technical dossiers.
Market Restraints
- Fumed silica supply concentration:Production of pyrogenic silica concentrates among a limited set of European and Asian suppliers, exposing formulators to input volatility during energy price spikes.
- Organoclay technical ceiling:Traditional organoclay rheology modifiers face performance boundaries in high-temperature bake cycles, restricting their deployment in automotive clearcoat segments.
- EPA Safer Choice divergence:Misalignment between EPA Safer Choice hazard criteria and EU Green Deal chemical sustainability thresholds fragments product registration strategies and complicates global standardization.
Strategic Opportunities
- India's PLI-linked chemical sector:India's Production Linked Incentive scheme for specialty chemicals creates domestic manufacturing incentives that regional formulators can leverage for cost-competitive sourcing.
- Polyurethane-acrylic hybrid convergence:Technology blending polyurethane thermal stability with acrylic water compatibility opens formulation white space in high-performance industrial maintenance coatings.
- Direct technical service distribution:Asia-Pacific distributors consolidating inventory with on-site formulation support are capturing mid-sized paint producers previously served through layered channels.
Industry Challenges
- Rheology modeling expertise scarcity:Formulation laboratories lack sufficient personnel trained in yield stress prediction for complex coating geometries, slowing new product qualification timelines.
- Legacy solvent-borne line retrofit costs:Paint manufacturers face capital intensity in converting production equipment for waterborne rheology systems, particularly in smaller regional facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Sagging Agents Market |
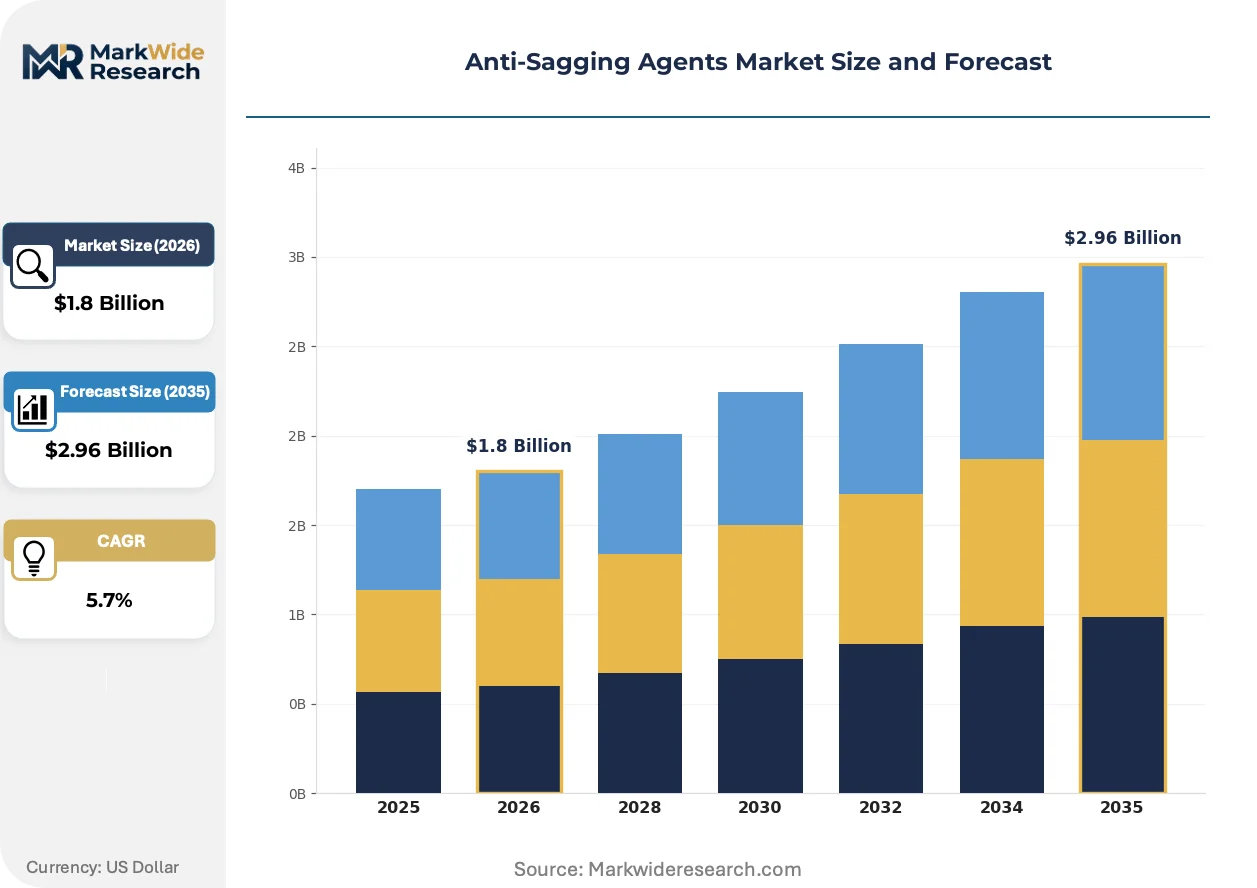
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylics, Polyurethane, Epoxies, Silicones Application: Paints, Coatings, Adhesives, Sealants End User: Construction, Automotive, Electronics, Consumer Goods Form: Liquid, Powder, Granules, Emulsions |
| Companies Covered | BASF SE, Evonik Industries AG, Dow Inc., Clariant AG, Croda International Plc, The Lubrizol Corporation, Solvay S.A., Ashland Inc., BYK Additives & Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Sagging Agents Market Evolving Landscape
Acrylic emulsion rheology modifiers are displacing legacy solvent-borne technologies across formulation portfolios, while regulatory divergence between jurisdictions fragments compliance architecture and procurement patterns concentrate among technically integrated distributors.
Associative thickener technology employing hydrophobically modified ethoxylated urethane chemistry is rendering obsolete conventional cellulosic thickeners in premium architectural coatings. Multinational coatings producers in Western Europe and North America are accelerating adoption to achieve superior sag resistance at lower shear rates. This displacement is compressing commodity thickener margins while expanding specification-grade additive pricing power.
China's GB standards for architectural coatings are tightening VOC emission thresholds and mandating waterborne content minimums that reshape domestic formulation practices. Local producers are reformulating entire product lines to maintain market access, with compliance timelines accelerating through 2025-2026 certification renewal cycles. The enforcement mechanism is most acute in tier-one cities where environmental inspection intensity exceeds national baselines.
Technical service unbundling from raw material supply is altering how mid-sized paint producers access formulation expertise. Regional distributors in Asia-Pacific are building in-house rheology laboratories to capture value previously retained by multinational additive suppliers. This channel evolution is most visible in India and Southeast Asia where fragmented end-user bases resist direct supplier engagement models.
Anti-Sagging Agents Market Segmentation

Anti-sagging agent procurement patterns diverge sharply across product chemistries and application requirements, with formulation compatibility and regulatory compliance driving segment selection. Understanding these dimensional splits enables suppliers to align technical service capabilities with concentrated demand pockets.
Product Type:
Mature acrylic technologies dominate volume throughput while polyurethane systems command premium positioning in specification-grade applications.
- Acrylics:Modified polyacrylate backbones deliver cost-effective yield stress control in waterborne architectural formulations. Construction activity across China and India concentrates demand for these emulsion-compatible additives as GB standards and BIS compliance tighten VOC thresholds.
- Polyurethane:Hydrophobically modified ethoxylated urethane chemistry provides superior sag resistance under low-shear conditions in automotive clearcoats. German and Japanese OEM procurement of these thermal-stable additives accelerates under EU REACH and METI substance reporting requirements.
- Epoxies:Reactive diluent-modified systems serve high-build industrial maintenance coatings requiring chemical resistance.
- Silicones:Siloxane-based modifiers occupy high-temperature niche applications in aerospace and industrial bake cycles.
Acrylics handle the majority of throughput; polyurethane is the fastest mover on share.
Application:
Cost tier differentiation separates commodity architectural applications from specification-driven industrial segments.
- Paints:Waterborne acrylic formulations for residential and commercial buildings represent the largest volume outlet. China's tier-one city enforcement of GB standards and India's construction intensity concentrate procurement of compliant rheology systems.
- Coatings:Automotive OEM clearcoats and aerospace primers demand polyurethane-based sag control with documented thermal stability dossiers. METI reporting requirements in Japan and EU REACH compliance in Germany favor established additive suppliers with technical service integration.
- Adhesives:Structural bonding applications in electronics assembly require low-VOC rheology modifiers compatible with automated dispensing equipment.
- Sealants:Construction joint applications favor cost-optimized acrylic thickeners in emerging market infrastructure projects.
Paints absorb the greatest additive volume; coatings expand most quickly as automotive specification compliance tightens.
End User:
Customer type fragmentation separates project-based construction procurement from integrated automotive supply chains.
- Construction:Residential and commercial building activity across China, India, and Southeast Asia drives waterborne acrylic formulation demand. Environmental inspection intensity in China's tier-one cities accelerates compliance timelines through certification renewal cycles.
- Automotive:German and Japanese OEMs specify polyurethane rheology modifiers for thermal stability under bake cycles. EU REACH VOC limits and METI guidelines compel procurement of documented, compliant additive systems.
- Electronics:Japan's METI chemical substance reporting requirements layer compliance complexity for coatings used in device manufacturing.
- Consumer Goods:Appliance and furniture coatings favor cost-optimized acrylic thickeners with rapid dry-to-touch properties.
Construction generates the largest absolute demand; automotive climbs the fastest on specification-grade additive penetration.
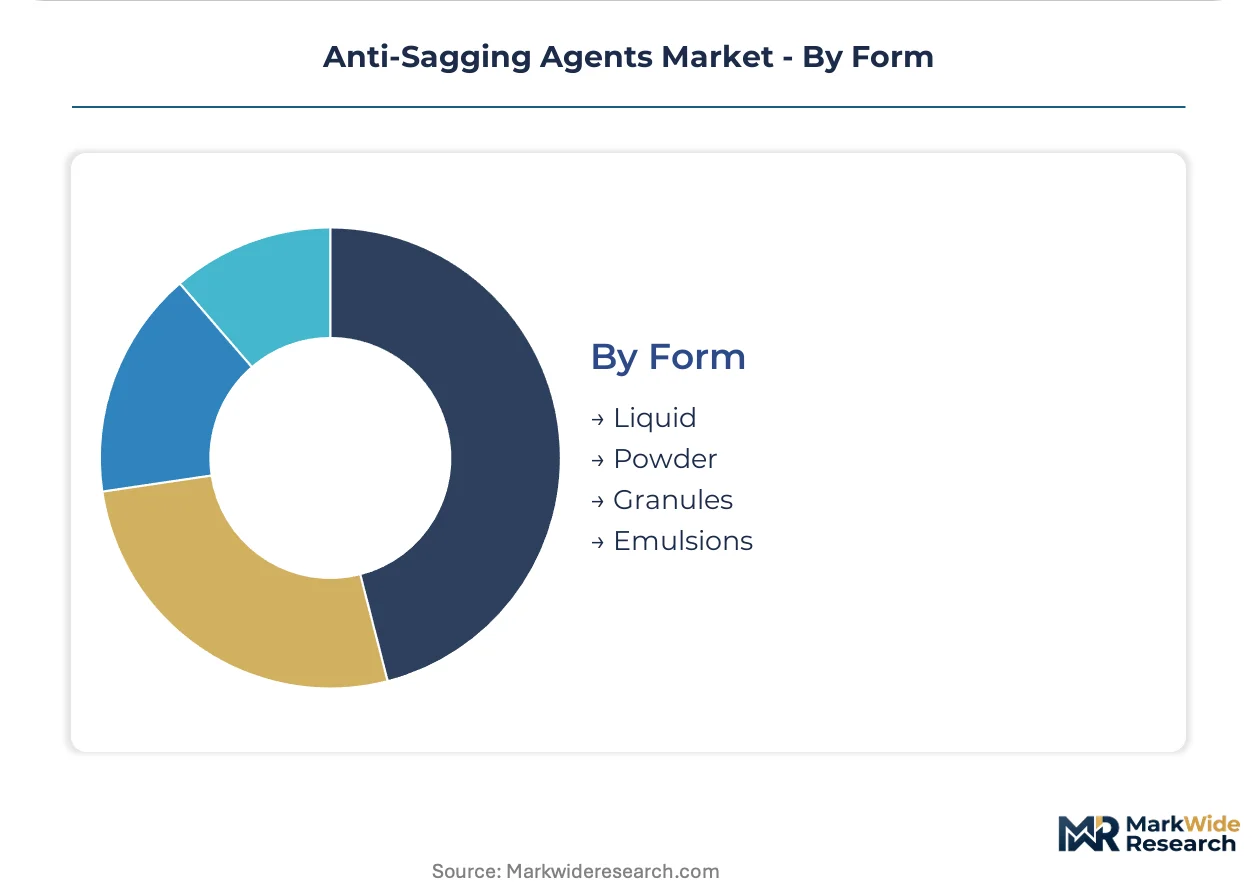
Form:
Supply concentration in powder and liquid formats contrasts with emerging emulsion technology adoption curves.
- Liquid:Solvent-borne concentrates face regulatory compression as EPA VOC regulations and EU REACH restrictions constrain formulation options. Legacy production lines in smaller regional facilities resist capital-intensive conversion.
- Emulsions:Waterborne-compatible rheology modifiers gain formulation share as OECD jurisdictions tighten regulatory mandates. Direct technical service distribution in Asia-Pacific captures mid-sized paint producers seeking formulation support alongside inventory.
- Powder:Fumed silica concentrates among limited European and Asian suppliers, exposing formulators to energy price volatility.
- Granules:Organoclay-based systems face performance boundaries in high-temperature bake cycles, restricting automotive deployment.
Liquid forms retain existing installed base; emulsions gain share fastest on waterborne regulatory alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical throughput infrastructure underwrites Europe's additive distribution capacity, while the Yangtze River Delta's coatings manufacturing belt anchors Asia-Pacific formulation demand. These logistics nodes shape where anti-sagging agent procurement concentrates.
China
Construction intensity in tier-one cities drives waterborne acrylic formulation demand. GB standards for architectural coatings mandate VOC emission thresholds that accelerate reformulation timelines. Shanghai and the surrounding Yangtze River Delta manufacturing corridor host the densest concentration of domestic paint producers converting product lines.
Germany
Automotive OEM clearcoat specifications concentrate demand for polyurethane-based thermal-stable additives. EU REACH VOC limits compel procurement of documented rheology systems. The Ruhr industrial basin and Bavarian automotive clusters represent the primary specification-grade additive consumption centers.
United States
EPA VOC regulations compress solvent-borne formulation options across architectural and industrial coatings segments. The Gulf Coast petrochemical corridor supplies raw material backbones for emulsion-compatible modifiers. Midwest manufacturing centers and Southeast construction markets split demand between automotive and building applications.
Japan
METI chemical substance reporting requirements layer compliance complexity for electronics and automotive coatings. Polyurethane additives dominate thermal stability specifications in clearcoat bake cycles. The Nagoya automotive manufacturing zone and Osaka-Kobe industrial corridor concentrate high-performance formulation demand.
India
Residential and commercial construction activity concentrates waterborne acrylic demand in Maharashtra and Gujarat. The Production Linked Incentive scheme for specialty chemicals creates domestic manufacturing incentives. Mumbai-Pune and Ahmedabad-Vadodara industrial belts attract regional distributor technical service investments.
Anti-Sagging Agents Market Competitive Landscape
On the supply side, the industry is tiered between integrated chemical conglomerates and specialized additive suppliers. BASF SE and Dow Inc. anchor the upper tier with polymer backbone integration, while mid-sized specialists occupy formulation-specific niches. Three archetypes dominate: integrated polymer producers, performance additive specialists, and regional technical service distributors. Competitive moves center on portfolio diversification into waterborne-compatible architectures and geographic expansion through distributor technical service consolidation.
Within the integrated chemical tier, BASF SE and Evonik Industries AG exemplify divergent strategic positioning. BASF leverages its Ludwigshafen production complex to supply acrylic rheology modifiers directly to multinational coatings producers. Evonik anchors its market presence through polyurethane-based additive portfolios that occupy specification-grade automotive segments. Dow Inc. sits within the emulsion technology vector, competing on liquid delivery formats that reduce manufacturing complexity for mid-sized paint producers.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Dow Inc. |
| Clariant AG |
| Croda International Plc |
| The Lubrizol Corporation |
| Solvay S.A. |
| Ashland Inc. |
| BYK Additives & Instruments |
| Others |
Value Network & Pricing Analysis
Fumed silica supply concentration among European and Asian producers creates dual exposure to energy price volatility and tariff friction, compressing margin structures for mid-tier formulators while forcing premium additive suppliers to widen price spreads between specification-grade and commodity offerings. This input dependency reshapes procurement toward long-term offtake contracts with integrated polymer producers.
Pricing Analysis
Volume-discount tiering structures separate multinational coatings producers securing direct supply agreements from mid-sized paint manufacturers purchasing through regional distributors. Price differentiation hinges on thermal stability certification grade and after-sales technical service bundling. Cost compression in the acrylic emulsion segment is intensifying as waterborne regulatory mandates expand compliant formulation requirements. Construction end-users in emerging markets exhibit highest price sensitivity, while automotive OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Extended payment terms from integrated chemical conglomerates to regional distributors are financing inventory carrying costs across Asia-Pacific formulation markets. Supply concentrates in Germany, China, and Japan for polyurethane backbone chemistries, while fumed silica production draws from limited European and Asian pyrogenic silica facilities. Single-source vulnerability in organoclay modifier feedstocks exposes formulators to logistics chokepoints at Rotterdam and Shanghai port complexes. Distribution runs through technical service-integrated regional distributors capturing mid-sized paint producer accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne regulatory interoperability across EU REACH, EPA, and China's GB standards is creating platform-economics dynamics where additive suppliers with cross-jurisdictional technical dossiers capture disproportionate procurement share from multinational coatings producers.
For Market Incumbents: Insulate specification-grade positioning by deepening captive supply of acrylic polymer backbones and accelerating METI-compliant technical dossier investments. Organoclay thermal performance limitations in automotive bake cycles threaten legacy product lines; redirect R&D toward polyurethane-acrylic hybrid architectures. For New Entrants and Emerging Players: Build out technical service laboratories in India's Maharashtra and Gujarat industrial corridors to capture PLI-linked domestic manufacturing incentives. India's fragmented paint producer base resists direct multinational engagement, creating distributor partnership white space. Target waterborne acrylic formulation support as the most penetrable entry vector. For Investors and Strategic Acquirers: EU REACH VOC limit enforcement reshapes the acquisition landscape toward additive suppliers with documented automotive OEM qualification histories. Five-to-ten-year viability favors performance specialists with backward integration into emulsion polymerization capacity. Monitor divergence between EPA Safer Choice and EU Green Deal chemical sustainability thresholds as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Polymer Production | Captive supply of rheology modifier backbones secures margin control against fumed silica volatility. |
| Long-term Supply Agreement with Automotive OEMs | Documented thermal stability dossiers under EU REACH lock in specification-grade procurement volumes. |
| Joint Venture with Asia-Pacific Technical Distributors | On-site formulation laboratories capture mid-sized paint producers previously served through layered channels. |
| Green Manufacturing Transition to Waterborne Emulsions | Low-VOC additive architectures align with China's GB standards and India's BIS compliance timelines. |
| Acquisition of Regional Organoclay Specialist | Granule-based modifier capabilities fill cost-optimized construction segment gaps in emerging markets. |
Research Methodology
A spread of perspectives from coatings formulators, automotive OEM procurement officers, specialty chemical distributors, and regulatory affairs directors converged on the working assumptions underlying this analysis. Primary field engagement combined with secondary validation from SEC 10-K filings, Cefic industry reports, customs trade data, and EPA regulatory dockets. Bottom-up segment sizing and top-down macroeconomic triangulation anchored volume and value estimates.
Demand-supply-balance framing modeled additive consumption against coatings production capacity across chemistry type, application segment, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from segment-level growth rate reconciliation with macroeconomic drivers. Forecast inputs incorporated construction intensity indices for China and India, automotive OEM bake cycle specification evolution, and waterborne regulatory mandate adoption curves.
Stress conditions across energy price volatility, fumed silica supply disruption, and regulatory divergence scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about compliance timeline acceleration and distributor channel evolution. Macroeconomic contraction, regulatory harmonization failure, or breakthrough solvent-borne formulation technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Frying Shortening Market
Food Enhancers and Additives
Australia & New Zealand Food Flavors and Enhancers Market
Food Enhancers and Additives
Cake Softener Market
Food Enhancers and Additives
Instant Whipping Agents Market
Food Enhancers and Additives
Veratrole Market
Food Enhancers and Additives
Emulsifier Enhancers Market
Food Enhancers and Additives
Germany Food Flavor and Enhancer Market
Food Enhancers and Additives
Brazzein Market
Food Enhancers and Additives
Africa Water Enhancer Market
Food Enhancers and Additives
Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
Flavonoid Phytogenic Feed Additive Market
Food Enhancers and Additives
Australia Water Enhancer Market
Food Enhancers and Additives
Thaumatin Market
Food Enhancers and Additives
Raising Agents Market
Food Enhancers and Additives
Flour Improvers Market