
 Global Non-Cocoa Confectionery Market | 2026-2036
Global Non-Cocoa Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Cocoa Confectionery Market Foresight
Single-serve pouch configurations is decoupling bulk candy purchasing from traditional seasonal buying cycles. Mars Wrigley leverages its manufacturing scale to dominate multi-pack formats across convenience channels. Ferrero differentiates through premium gifting assortments that occupy specialty retail positioning. Perfetti Van Melle navigates regional taste preferences with localized flavor portfolios spanning sour and fruity ranges.
Non-cocoa confectionery comprises sugar-based or alternative-sweetener products—gummy bears, hard candies, marshmallows, licorice, and jelly beans—manufactured through starch molding, depositing, or aeration processes with moisture targets typically below five percent for shelf-stable distribution. These products serve impulse consumption, portion-controlled snacking, and ceremonial gifting functions across retail and foodservice channels. Gummy bears and hard candies anchor volume throughput in mature Western markets where manufacturing infrastructure is depreciated and margin pools favor scale players. Online retailers represent the fastest-growing distribution channel as direct-to-consumer bundling reduces intermediary costs and enables subscription-based replenishment models for repeat-purchase households.
The FDA governs added-sugar disclosure and serving-size regulations in the United States, while EFSA evaluates novel sweetener approvals and health claim substantiation across European markets, and Japan's Ministry of Health, Labour and Welfare administers positive-list systems for food additives including sugar alcohols used in reduced-calorie formulations. Compliance with these frameworks determines product access, reformulation investment cycles, and labeling architecture for cross-border trade. Stakeholders must monitor evolving sweetener approval pipelines and front-of-pack labeling mandates to anticipate formulation cost shifts and regional competitive entry barriers.
Market Dynamics
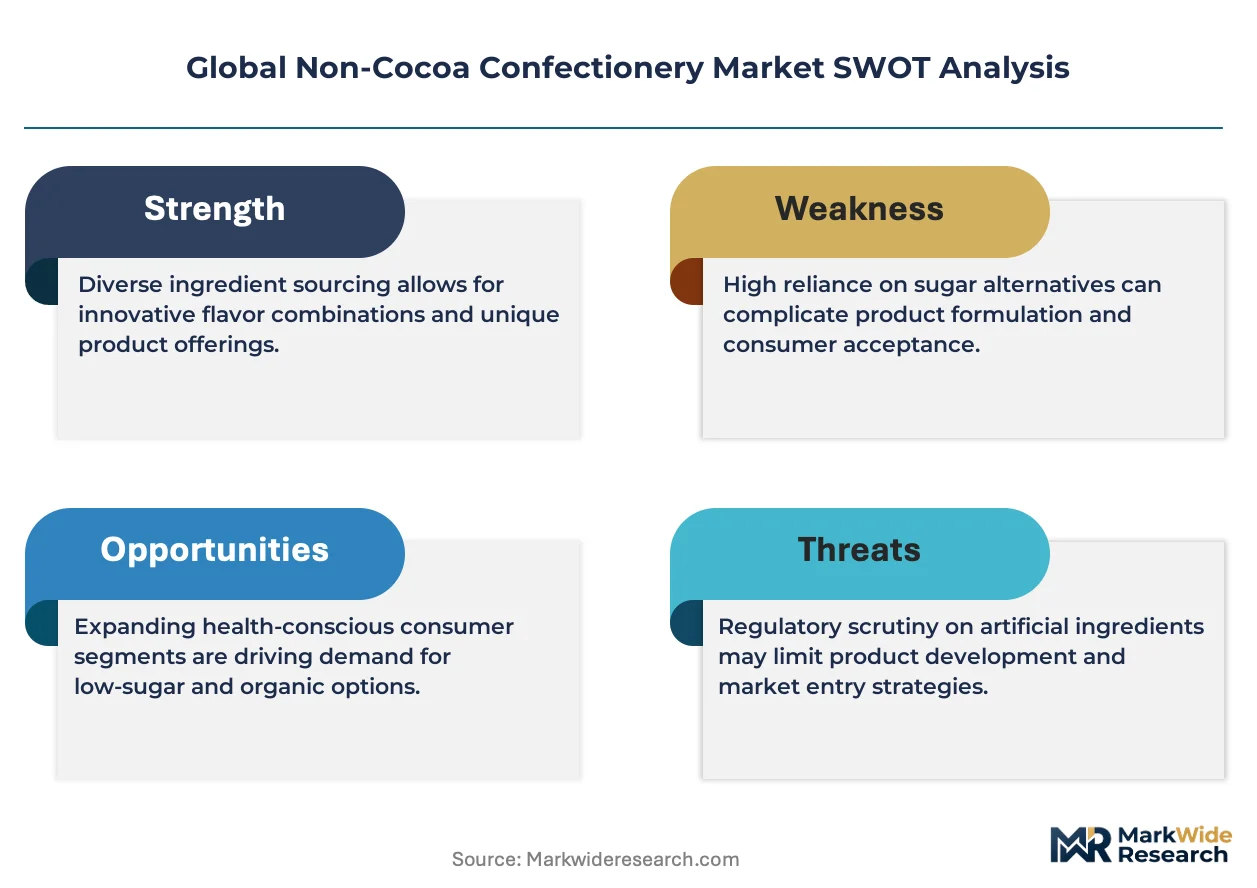
Sugar reduction mandates from the FDA and EFSA are compressing reformulation timelines and forcing manufacturers to rebuild their sweetener supply chains around approved alternatives.
Growth Catalysts
- Functional ingredient expansion:Manufacturers are fortifying gummy formats with vitamins and probiotics to capture wellness-oriented consumers seeking dual-purpose snacking options.
- EFSA novel sweetener approvals:Accelerated clearance pathways for sugar alcohols and rare sugars are enabling faster product launches across European retail channels.
- Japan:Premium gifting culture and ceremonial consumption patterns sustain demand for artisanal hard candy assortments in specialty retail positioning.
Market Restraints
- Input cost volatility:Gelatin and pectin prices fluctuate with livestock and citrus harvest cycles, squeezing margin pools for starch-molding operations.
- Supply concentration risk:Specialty flavor houses in southern Germany dominate proprietary fruit profiles, creating single-source dependencies for global brands.
- Technical limitation:Five-percent moisture targets for shelf-stable distribution constrain water-activity reduction without texture degradation in aerated marshmallow systems.
Strategic Opportunities
- India:Underpenetrated modern trade formats in tier-two cities offer white space for portion-controlled pouch introductions.
- Subscription channel innovation:Direct-to-consumer bundling models bypass traditional wholesale markups and capture repeat-purchase household data.
- EU Green Deal packaging mandates:Biodegradable film requirements create first-mover advantages for converters with certified home-compostable structures.
Industry Challenges
- Reformulation skill scarcity:Food scientists with expertise in bulking agent replacement and texture modulation command premium compensation.
- Clean-label certification timelines:Non-GMO Project and organic audits extend go-to-market schedules by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Cocoa Confectionery Market |
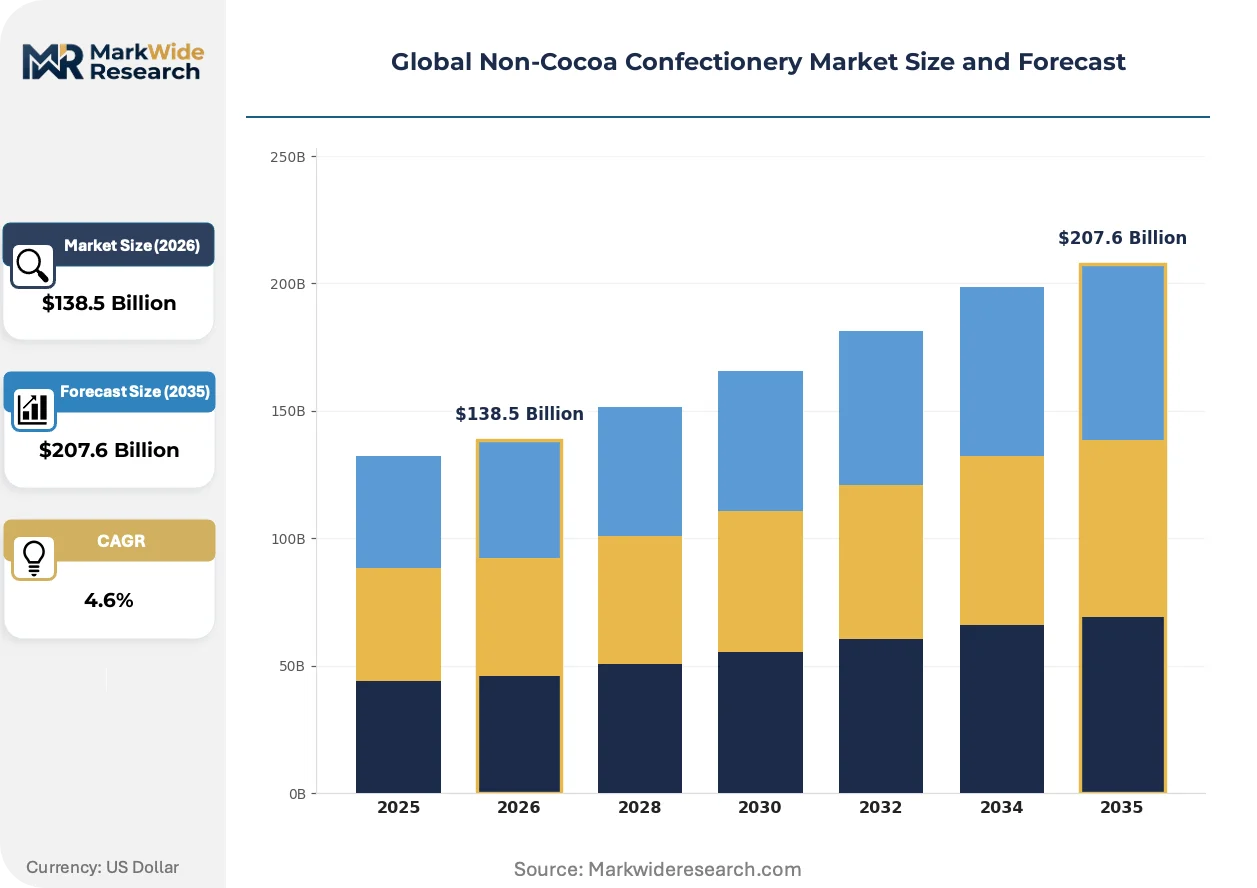
| Market Size in 2026 | $138.5 Billion |
| Market Size in 2035 | $207.6 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gummy Bears, Marshmallows, Licorice, Hard Candies, Jelly Beans Distribution Channel: Supermarkets, Convenience Stores, Specialty Shops, Online Retailers, Vending Machines End User: Children, Teenagers, Adults, Seniors, Gift Buyers Flavor Profile: Fruity, Minty, Spicy, Sour, Sweetened, Herbal |
| Companies Covered | Mars Wrigley, Mondelez International, Ferrero, Nestle, Haribo, Perfetti Van Melle, The Hershey Company, Cloetta, Trolli, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Cocoa Confectionery Market Shifts & Advancements
Reformulation science and digital distribution are converging to reshape how manufacturers develop, certify, and deliver reduced-sugar confectionery to fragmented consumer segments.
Continuous starch molding systems are integrating real-time moisture sensors and automated depositing controls to maintain sub-five-percent targets across variable ambient humidity conditions. Mid-sized manufacturers in the United States and Germany are retrofitting legacy lines with these sensor arrays to reduce manual testing labor and reject rates. This integration is compressing batch-to-batch variation and enabling just-in-time production schedules for private-label retail programs.
EFSA front-of-pack Nutri-Score mandates are forcing label architecture redesigns that visually penalize high-sugar formulations in continental European supermarkets. Manufacturers must now balance sensory performance against algorithmic scoring thresholds that determine shelf placement premiums. Hard candy and licorice segments in France and Germany face the steepest reformulation investment cycles as retailers delist SKUs failing B-grade thresholds.
Impulse purchasing is fragmenting from checkout counters toward micro-fulfillment centers and quick-commerce dark stores in dense urban clusters. Convenience retailers in Tokyo and New York are reducing planned seasonal displays in favor of algorithmic replenishment tied to localized consumption signals. This behavioral rotation favors single-serve pouch formats with extended ambient stability over bulk seasonal assortments requiring forward inventory commitment.
Global Non-Cocoa Confectionery Market Segmentation
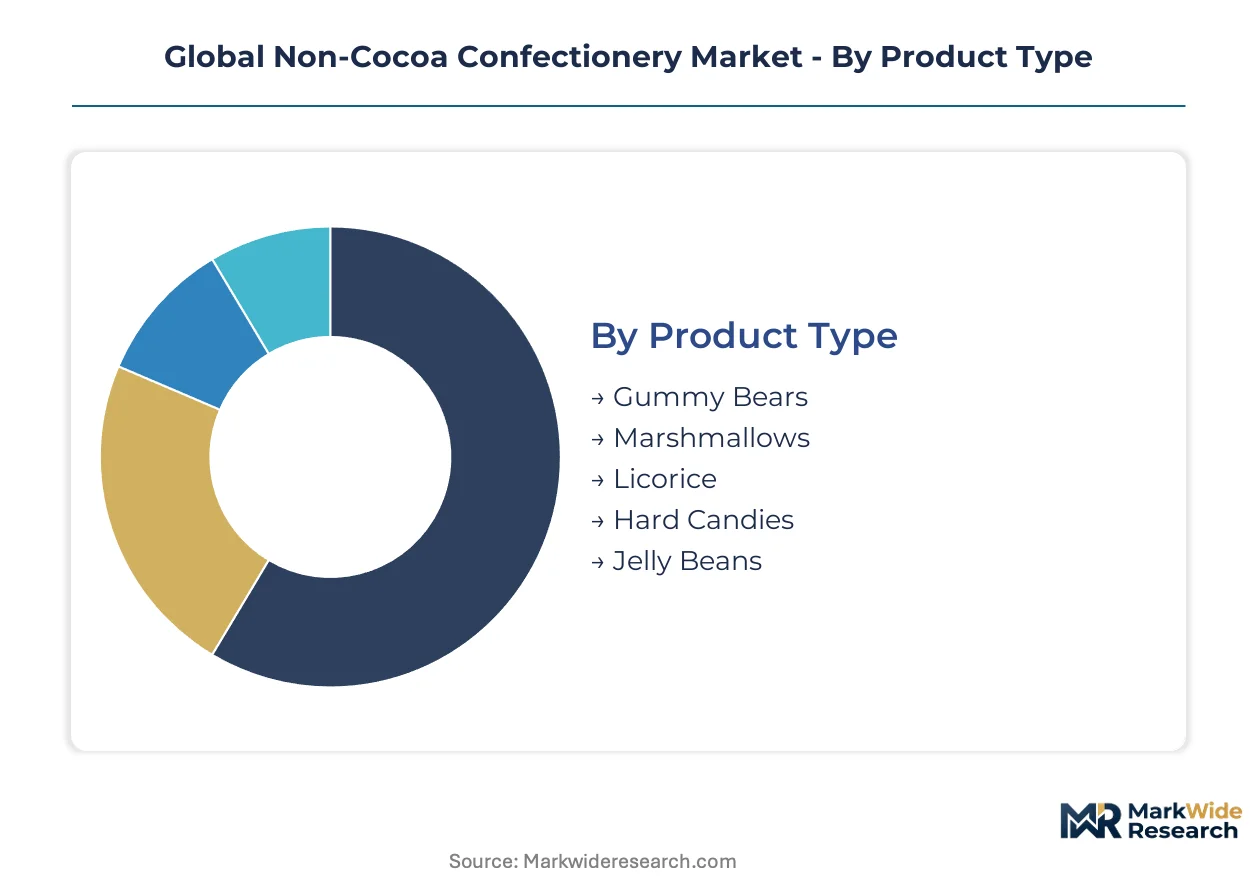
Product heterogeneity in non-cocoa confectionery demands granular segmentation to align formulation investments with distinct consumption occasions and channel economics. Manufacturers configure equipment lines, moisture targets, and packaging formats around specific segment requirements rather than pursuing one-size-fits-all production.
Product Type:
Upgrade cycles in manufacturing equipment favor segments with depreciated infrastructure and proven margin pools over emerging formats requiring capital-intensive line conversions.
- Gummy Bears:Starch-molded gelatin or pectin-based formulations achieve sub-five-percent moisture targets through controlled drying tunnels. Demand concentrates in the United States and Germany where private-label retail chains expand single-serve pouch configurations. Sugar reduction mandates from the FDA and EFSA compress reformulation timelines for this volume anchor.
- Hard Candies:High-boiled sugar syrups deposited into precision molds create glassy amorphous structures with extended ambient stability. Japan's ceremonial gifting culture sustains demand for artisanal assortments in specialty retail positioning. Deposit-based manufacturing scales efficiently across depreciated equipment bases in mature Western markets.
- Marshmallows:Aerated sucrose or glucose systems whipped to specific overrun targets.
- Licorice:Wheat flour and molasses-based extruded products with distinct regional taste polarizations.
- Jelly Beans:Panned sugar shells surrounding soft centers requiring multi-day coating processes.
Volume placements concentrate in Gummy Bears; the faster expansion belongs to Hard Candies.
Distribution Channel:
Channel selection determines packaging format, margin structure, and inventory velocity requirements for manufacturers.
- Supermarkets:Multi-pack formats dominate shelf space with seasonal display economics driving forward inventory commitment.
- Convenience Stores:Impulse-oriented single-serve pouches with extended ambient stability suit algorithmic replenishment in dense urban clusters.
- Specialty Shops:Premium gifting assortments command price premiums through artisanal positioning and localized flavor curation.
- Online Retailers:Direct-to-consumer bundling reduces intermediary costs and enables subscription-based replenishment models for repeat-purchase households.
- Vending Machines:Compact heat-stable formats with extended shelf life suit unattended retail in transit hubs and workplace clusters.
Transaction density peaks in Supermarkets; the steepest expansion trajectory belongs to Online Retailers.
End User:
Demographic targeting shapes formulation intensity, portion sizing, and functional ingredient integration.
- Children:Bright colorants and familiar fruit profiles dominate with strict regulatory limits on artificial additives in the United States and European Union.
- Teenagers:Sour flavor ranges and novelty textures drive trial-oriented purchasing with social media amplification effects.
- Adults:Wellness-oriented dual-purpose snacking with vitamin fortification and probiotic integration commands shelf space in Germany and Japan.
- Seniors:Reduced-calorie formulations with approved sugar alcohols address dietary restriction compliance.
- Gift Buyers:Premium assortments with ceremonial packaging sustain demand in Japan's specialty retail channels.
Purchase frequency concentrates in Adults; the most rapid share gain belongs to Gift Buyers.
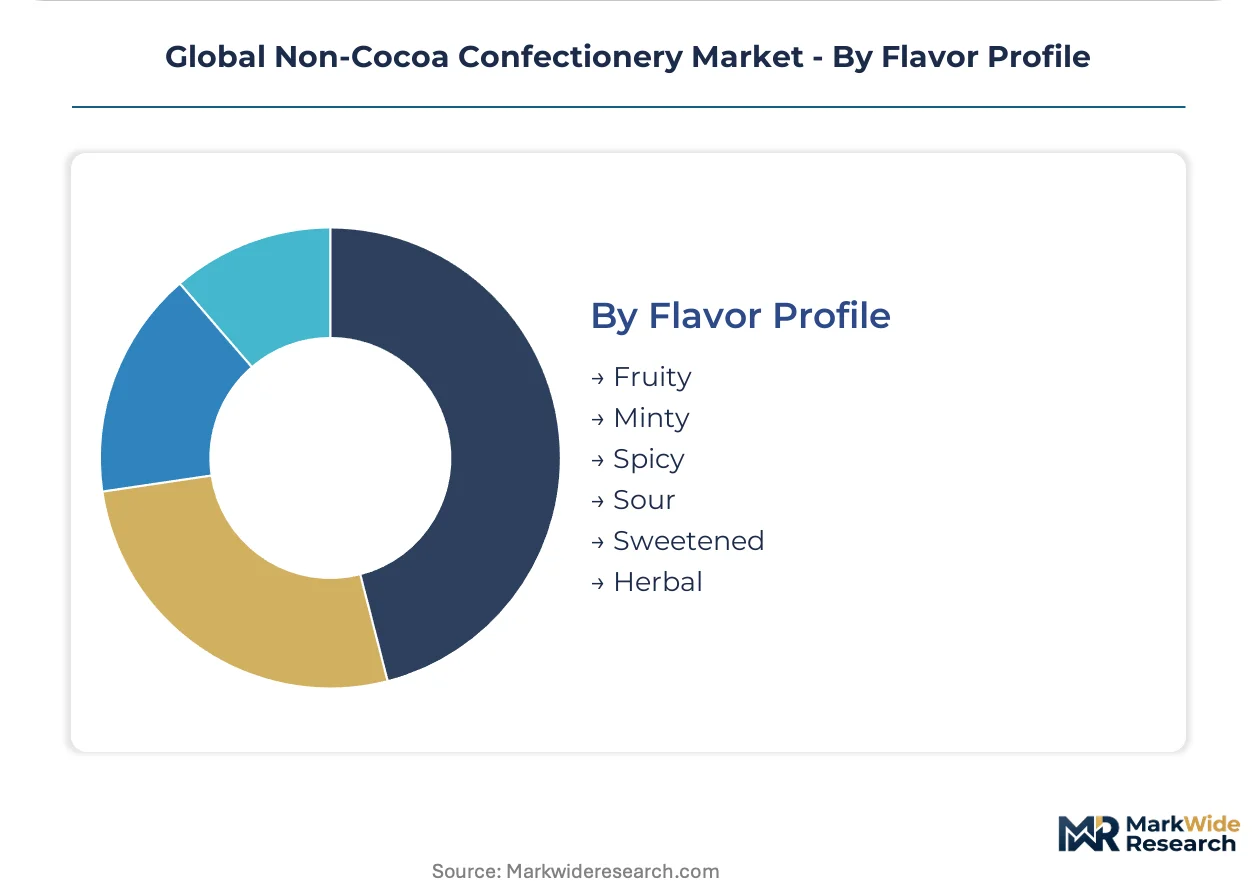
Flavor Profile:
Flavor innovation cycles determine raw material procurement patterns and proprietary compound dependencies.
- Fruity:Citrus and berry profiles from southern German flavor houses dominate global brand formulations.
- Minty:Cooling compound integration suits breath-freshening functional positioning in convenience channels.
- Spicy:Cinnamon and ginger variants align with seasonal consumption patterns in North American markets.
- Sour:Acidulated coatings and pH-adjusted centers target teenage trial purchasing with immediate sensory impact.
- Sweetened:Traditional sucrose-dominant profiles face reformulation pressure under EFSA Nutri-Score mandates.
- Herbal:Botanical extracts and functional ingredients integrate wellness positioning into conventional formats.
Formulation investment concentrates in Fruity; the most aggressive expansion belongs to Herbal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and the United States while consumption concentrates in Japan's ceremonial gifting channels and India's emerging modern trade. This production-consumption asymmetry shapes cross-border shipment patterns and regional formulation strategies.
United States
FDA added-sugar disclosure mandates compress reformulation timelines for gummy and hard candy formats. Private-label retail chains expand single-serve pouch configurations through convenience channel partnerships. Chicago and New Jersey manufacturing corridors host depreciated starch-molding infrastructure serving North American distribution networks.
Germany
EFSA Nutri-Score front-of-pack labeling visually penalizes high-sugar formulations in continental supermarkets. Southern German flavor houses dominate proprietary fruit profiles for global brand supply. Bavaria's specialty confectionery clusters sustain artisanal hard candy production for premium gifting export markets.
Japan
Ministry of Health, Labour and Welfare positive-list systems govern sugar alcohol approvals for reduced-calorie formulations. Ceremonial consumption patterns sustain demand for artisanal hard candy assortments in Tokyo specialty retail. Kanto region distribution hubs algorithmically replenish quick-commerce dark stores with heat-stable single-serve formats.
India
FSSAI food additive regulations frame sugar reduction pathways for domestic manufacturers. Tier-two city modern trade formats offer white space for portion-controlled pouch introductions. Maharashtra and Gujarat processing corridors retrofit legacy equipment for localized flavor portfolios targeting regional taste preferences.
United Kingdom
Competition and Markets Authority scrutiny of retail pricing practices constrains margin expansion for branded confectionery. Clean-label certification demand extends go-to-market schedules for organic and non-GMO product lines. Midlands manufacturing bases supply depreciated depositing capacity for hard candy export programs.
Global Non-Cocoa Confectionery Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation intensity tiers. Market structure concentrates around scale-driven multi-format manufacturers and premium gifting specialists with distinct channel positioning. Strategic archetypes include global brand houses with depreciated infrastructure, regional flavor-curators with localized portfolios, and private-label converters serving retail chain programs. Dominant competitive moves encompass M&A-driven portfolio diversification and geographic expansion into underpenetrated modern trade formats.
Among scale-driven manufacturers, Mars Wrigley and Mondelez International occupy positions exemplifying multi-format dominance across convenience and supermarket channels. Ferrero represents the premium gifting archetype through specialty retail positioning. These three entities anchor competitive dynamics in mature Western markets where manufacturing scale and brand equity determine shelf access.
| Leading Market Players |
|---|
| Mars Wrigley |
| Mondelez International |
| Ferrero |
| Nestle |
| Haribo |
| Perfetti Van Melle |
| The Hershey Company |
| Cloetta |
| Trolli |
| Others |
Supply & Pricing Matrix
Gelatin futures and citrus pectin spot markets cascade through non-cocoa confectionery supply chains into three distinct pricing tiers. Raw material volatility from livestock harvest cycles and Brazilian orange crop conditions compresses margin pools for starch-molding operators, forcing tiered pricing stratification across premium artisanal, standard private-label, and economy bulk formats.
Pricing Analysis
Margin tightening in standard-tier gummy formats reflects gelatin price volatility and EFSA-mandated reformulation costs. Three-tier pricing structure across premium, standard, and economy levels separates certified organic SKUs from conventional private-label and unbranded bulk offerings. Pricing pressure intensifies in economy tiers as retail chains consolidate private-label volumes. Gift buyers in Japan exhibit lowest price sensitivity; budget-conscious households in India's tier-two cities drive hardest bargain hunting.
Supply Chain Analysis
Single-source vulnerability sits with southern German flavor houses dominating proprietary fruit compound formulations for global brand supply. Manufacturing capacity clusters in Germany, the United States, and Japan, drawing from Brazilian citrus, Chinese gelatin, and Indian sugar alcohol feedstocks. Supply chain risk centers on tariff exposure for pectin imports from citrus-belt regions. Distribution runs through depreciated North American and European warehousing networks into algorithmically replenished convenience channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-cocoa confectionery operates as a supply-constrained market where reformulation skill scarcity props pricing power for qualified manufacturers. Gelatin and pectin input bottlenecks limit rapid capacity expansion, sustaining margin premiums for incumbent scale players.
For Market Incumbents: Cement formulation expertise advantages through captive supply of certified sugar alcohols and backward integration into pectin extraction partnerships. Acquire distressed flavor house assets in southern Germany to neutralize single-source vulnerability. Lock in multi-year private-label contracts with convenience channel partners before EFSA Nutri-Score delisting pressures accelerate.
For New Entrants and Emerging Players: Capture white space in India's tier-two modern trade through portion-controlled pouch formats priced below Mars Wrigley and Mondelez International shelf rates. Target subscription-channel bundling models that bypass wholesale markups and harvest repeat-purchase household data. Enter via direct-to-consumer wellness positioning with probiotic-fortified gummy SKUs.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier private-label converters in the United States Midwest with depreciated starch-molding lines and established retail chain relationships. Long-term viability hinges on reformulation capability depth and EFSA compliance infrastructure. Watch EFSA novel sweetener approval velocity as inflection signal for portfolio repositioning timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation Science Investment | EFSA Nutri-Score compliance determines continental European shelf access and premium positioning. |
| Direct-to-Consumer Channel Launch | Subscription bundling bypasses wholesale markups and captures repeat-purchase household data streams. |
| Certified Organic Tier Introduction | Clean-label certification extends go-to-market schedules but commands 20-40% shelf price premiums. |
| Backward Integration into Sweetener Supply | Captive sugar alcohol production insulates margin pools from FDA and EFSA approval pipeline delays. |
| Regional Flavor Portfolio Localization | Perfetti Van Melle's sour-range success in Asian markets demonstrates taste-adaptation payoff. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this non-cocoa confectionery analysis. Primary interviews with brand managers, category buyers at retail chains, starch-molding equipment suppliers, and food science R&D directors combined with FDA added-sugar disclosure databases, EFSA novel food approval registries, and Japanese Ministry of Health positive-list filings. Bottom-up SKU-level volume builds and top-down trade flow reconciliations triangulated market sizing.
Data-stream reconciliation across shipment records, retail audit panels, and manufacturing capacity surveys informed the analytical framework. Segmentation dimensions spanned product type, distribution channel, end-user demographic, and flavor profile across the projection horizon. CAGRs derived from volume trajectory modeling against price index movements. Forecast inputs incorporated EFSA sweetener approval pipelines and private-label expansion rates at convenience retailers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory approval timelines for bulk-agent replacements and gelatin price volatility from livestock disease cycles. Deviation in EFSA Nutri-Score enforcement strictness or FDA serving-size recalibration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Sugar Free Lollipops Market
Confectionery
Organic Chocolate Confectionery Market
Confectionery
Chocolate Flavors Market
Confectionery
United States Caramel Chocolate Market
Confectionery
Chocolate Couverture Market
Confectionery
South America Compound Chocolate Market
Confectionery
Global Industrial Chocolate Market
Confectionery
Middle East Chocolate Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
China Chocolate Market
Confectionery
North America Marshmallow Market
Confectionery
Ruby Chocolate Market
Confectionery
Infused Fruits Jellies Market
Confectionery
Sugar Free White Chocolate Market
Confectionery
Pralines Market
Confectionery
Premium Chocolate Market