
 Sugar-Free Sweets Market | 2026-2036
Sugar-Free Sweets Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar-Free Sweets Market Analytics
The EU Green Deal is hardening sugar-reduction mandates across European food manufacturing. Mondelez International leverages its R&D infrastructure to reformulate legacy chocolate lines with polyol blends. Lindt & Sprüngli anchors premium positioning through bean-to-bar traceability that extends to sugar-free dark chocolate collections. Mars competes on manufacturing scale, operating dedicated sugar-free production lines across multiple European facilities.
Sugar-free sweets comprise confectionery products formulated without sucrose, typically employing sugar alcohols such as maltitol or erythritol, natural extracts like stevia glycosides, or synthetic high-intensity sweeteners including sucralose to achieve equivalent sensory profiles with reduced glycemic impact. These products serve diabetic management protocols, weight-control regimens, and dental-health programs across retail and clinical nutrition channels. Chocolate dominates current value pools due to premium pricing tolerance, while gummies represent the fastest-expanding format as gelatin-free and pectin-based innovations attract vegan-adjacent buyers. Health food stores command disproportionate margin capture compared with supermarket and online retail channels, reflecting the ingredient-type premium attached to natural sweetener positioning.
EMA guidelines on nutritional health claims intersect with EFSA sweetness additive approvals to define permissible label language across the European market. REACH chemical safety protocols govern residual solvent limits in stevia extraction processes, while EU Green Deal carbon-accounting rules press suppliers toward renewable energy in sweetener production. Stakeholders must monitor evolving EFSA opinions on novel sweetener candidates and calibrate formulation pipelines against shifting regulatory thresholds before committing capital to new product platforms.
Market Dynamics
EU Green Deal carbon-accounting rules press stevia and allulose suppliers toward renewable energy in sweetener production, redirecting capital flows across European confectionery manufacturing. The EU's Sugar Reduction Targets and front-of-pack nutrition labeling regulations tighten formulation standards, forcing reformulation of legacy product lines.
Growth Catalysts
- EU Sugar Reduction Targets:Mandatory reformulation deadlines compel manufacturers to eliminate sucrose from existing confectionery portfolios, accelerating R&D investment in polyol and natural sweetener alternatives.
- Stevia Glycoside Processing:Advances in enzymatic bioconversion reduce bitter aftertaste profiles, enabling broader application in premium chocolate formulations previously resistant to natural sweetener substitution.
- Diabetic Management Protocols:Clinical nutrition channels in Germany and France expand shelf space for glycemic-index-certified confections, creating dedicated distribution infrastructure for sugar-free sweets.
Market Restraints
- Allulose Supply Concentration:Production capacity clusters in North American biorefineries, exposing European formulators to transatlantic shipping cost volatility and currency fluctuation risk.
- Erythritol Crystallization Limitations:Technical constraints in achieving smooth mouthfeel at high replacement ratios restrict application in soft-centered pralines and fondant-based confections.
- REACH Residual Solvent Protocols:Strict limits on extraction solvents in stevia processing elevate compliance costs for suppliers sourcing from non-EU extraction facilities.
Strategic Opportunities
- Pectin-Based Gummy Innovation:Gelatin-free formulations capture vegan-adjacent buyers in United Kingdom health food channels, expanding addressable market beyond diabetic and weight-control segments.
- Health Food Store Premium Positioning:Natural sweetener certification commands disproportionate margin capture compared to supermarket retail, rewarding dedicated ingredient-type marketing investment.
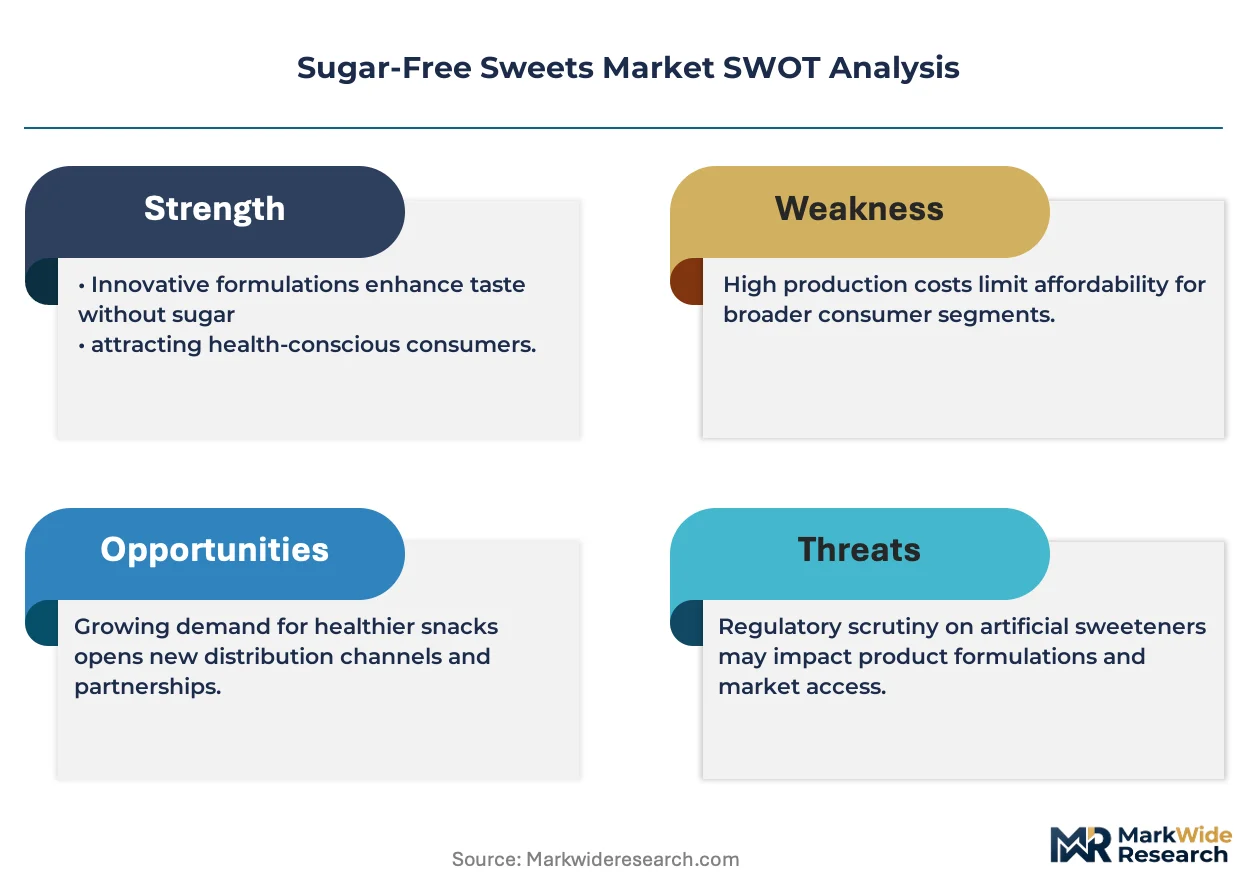
- EFSA Novel Sweetener Pipeline:Pending approvals for next-generation high-intensity candidates create first-mover advantage windows for manufacturers with pre-positioned formulation capabilities.
Industry Challenges
- Clean-Label Sensory Matching:Formulation chemists face acute scarcity in professionals capable of balancing polyol cooling effects with cocoa butter crystallization behavior.
- Dual Certification Timeline Compression:Parallel EFSA additive approval and national health claim authorization processes extend product launch cycles by 18-24 months.
- Legacy Equipment Retrofit Requirements:Existing chocolate tempering lines require humidity-controlled modifications to handle hygroscopic maltitol-based masses without bloom defects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar-Free Sweets Market |
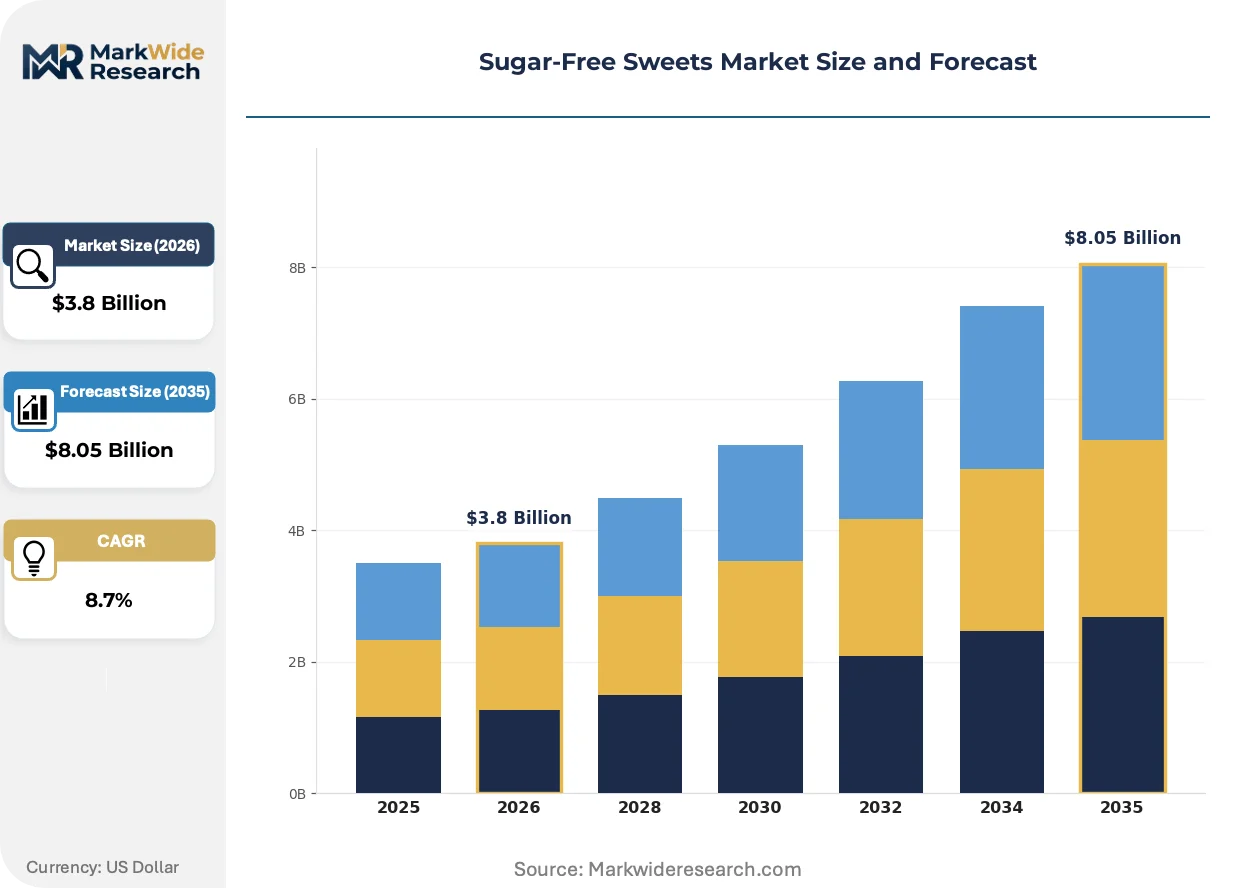
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Candies, Chocolate, Baked Goods, Gummies End User: Health-Conscious Consumers, Diabetics, Fitness Enthusiasts, Children Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops Ingredient Type: Sugar Alcohols, Natural Sweeteners, Artificial Sweeteners, Others |
| Companies Covered | Mondelez International, Russell Stover, The Hershey Company, Haribo, SmartSweets, Mars, Lindt & Sprüngli, Ferrero, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar-Free Sweets Market Evolving Landscape
Natural sweetener innovation redirects R&D investment toward clean-label alternatives as health-conscious consumers reject synthetic high-intensity options. Processing technology advances and regulatory tightening converge to reshape competitive positioning across European confectionery.
Enzymatic bioconversion of stevia leaf extracts is automating the removal of bitter-tasting rebaudioside fractions, enabling sensory parity with sucrose in dark chocolate applications. Premium manufacturers in Belgium and Switzerland adopt these refined glycoside blends at accelerated pace, compressing the premium gap between conventional and sugar-free dark chocolate collections. The technology is automating quality consistency previously achievable only through synthetic sweetener formulations.
EU Green Deal carbon-accounting rules now govern renewable energy verification across stevia extraction and allulose fermentation supply chains. Industrial consequence mandates supplier disclosure of Scope 2 emissions, elevating energy sourcing to a procurement criterion alongside price and purity. German and French confectionery manufacturers most affected are consolidating supplier relationships with biorefineries holding certified renewable power purchase agreements.
Health food stores now command disproportionate margin capture through ingredient-type premium positioning that supermarkets cannot replicate. The channel is consolidating shelf space around bean-to-bar traceability claims extending to sugar-free lines, displacing conventional retail as the launch platform for premium novelties. This rotation is most visible in United Kingdom urban centers where dedicated free-from retailers cluster.
Sugar-Free Sweets Market Segmentation
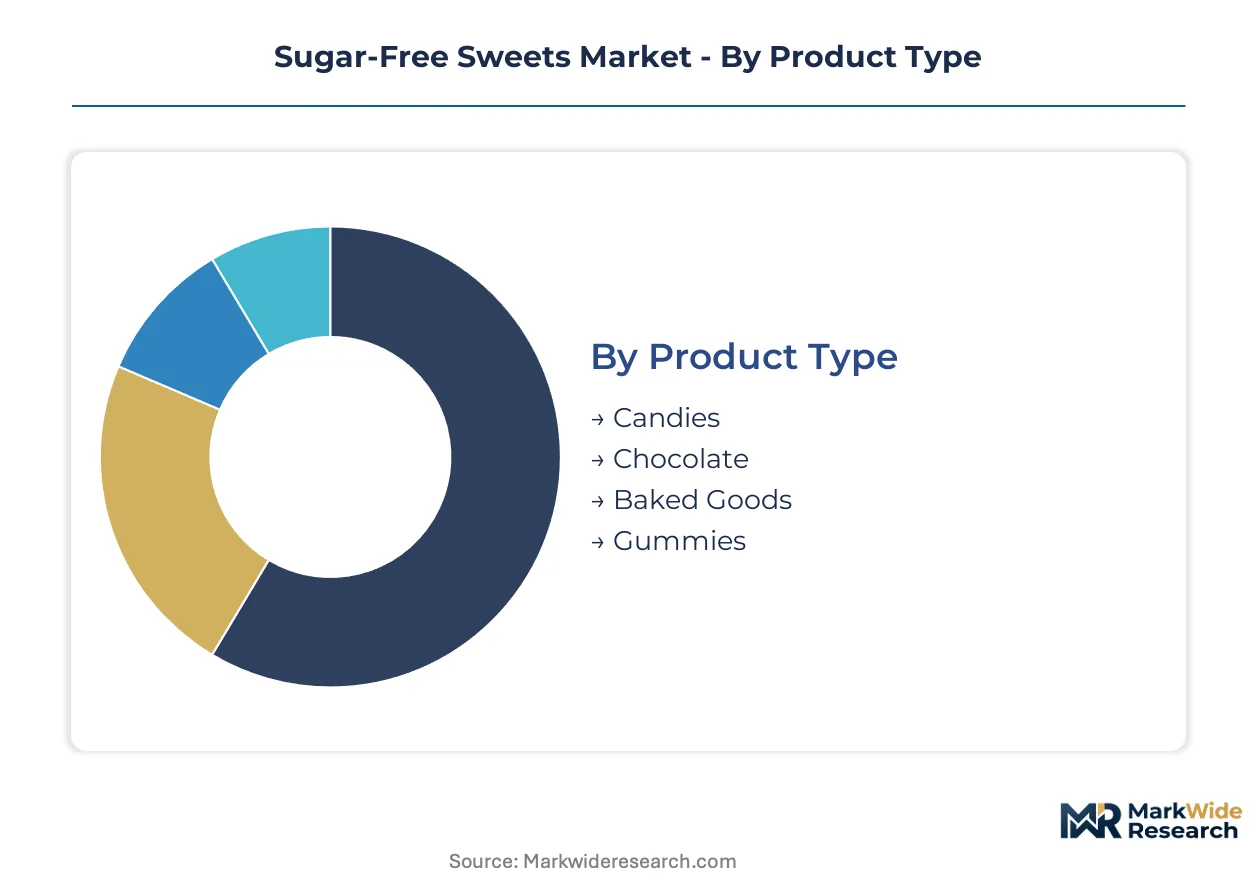
Sugar-free sweets manufacturers calibrate formulation pipelines and channel strategies against distinct demand profiles. Each segment boundary carries regulatory, margin, and sensory implications that reshape competitive positioning.
Product Type:
Upgrade cycles in European confectionery accelerate as reformulation mandates force portfolio renewal across legacy chocolate and candy lines.
- Chocolate:Dark chocolate formulations dominate premium value pools through cocoa butter crystallization techniques adapted for maltitol and erythritol masses. Belgian and Swiss manufacturers anchor bean-to-bar traceability claims in sugar-free collections, capturing health-conscious consumers in Germany and France willing to absorb price premiums for glycemic-index-certified products.
- Gummies:Pectin-based gelatin-free innovations attract vegan-adjacent buyers in United Kingdom health food channels, expanding addressable market beyond diabetic management protocols. Enzymatic processing advances reduce setting-time constraints, enabling scaled production previously limited by starch mold throughput.
- Candies:Hard-boiled and soft-centered varieties employ isomalt and xylitol for dental-health positioning in clinical nutrition channels.
- Baked Goods:Cookies and biscuits face technical constraints in achieving Maillard browning without sucrose, restricting application in premium positioning.
Chocolate sits at the top of the volume ranking, with gummies climbing the fastest.
End User:
Cost-tier stratification separates clinical nutrition positioning from mass-market wellness claims across European retail channels.
- Health-Conscious Consumers:Clean-label preference redirects procurement toward stevia and allulose formulations, rejecting synthetic high-intensity options. This cohort commands disproportionate shelf space in United Kingdom and German health food stores, where ingredient-type certification justifies 30-40% price elevation over supermarket equivalents.
- Diabetics:Glycemic-index-certified confections serve clinical nutrition protocols in France and Germany, with pharmacy channel distribution creating dedicated infrastructure. EFSA health claim authorization requirements compress marketing language to tightly specified glucose-management statements.
- Fitness Enthusiasts:Protein-enriched sugar-free chocolates target post-workout recovery positioning in specialty sports nutrition retail.
- Children:Dental-health formulations with xylitol face strict EFSA labeling constraints on caries-reduction claims.
Health-conscious consumers anchor volume concentration, with fitness enthusiasts gaining share fastest.
Distribution Channel:
Margin capture varies sharply by channel control over ingredient-type certification and traceability verification.
- Health Food Stores:Natural sweetener positioning and bean-to-bar traceability claims command premium pricing unavailable in conventional retail. United Kingdom urban clusters of dedicated free-from retailers consolidate shelf space around EFSA-approved novel sweeteners, displacing supermarkets as launch platforms for premium novelties.
- Online Retail:Direct-to-consumer subscriptions for diabetic management protocols bypass pharmacy markups, building recurring revenue in German and French markets.
- Supermarkets:Private-label sugar-free lines compete on price, with front-of-pack nutrition labeling regulations compressing formulation differentiation.
- Specialty Shops:Belgian praline houses and Swiss confiseries maintain artisan positioning through small-batch polyol experimentation.
Health food stores lead margin capture, with online retail expanding most quickly.
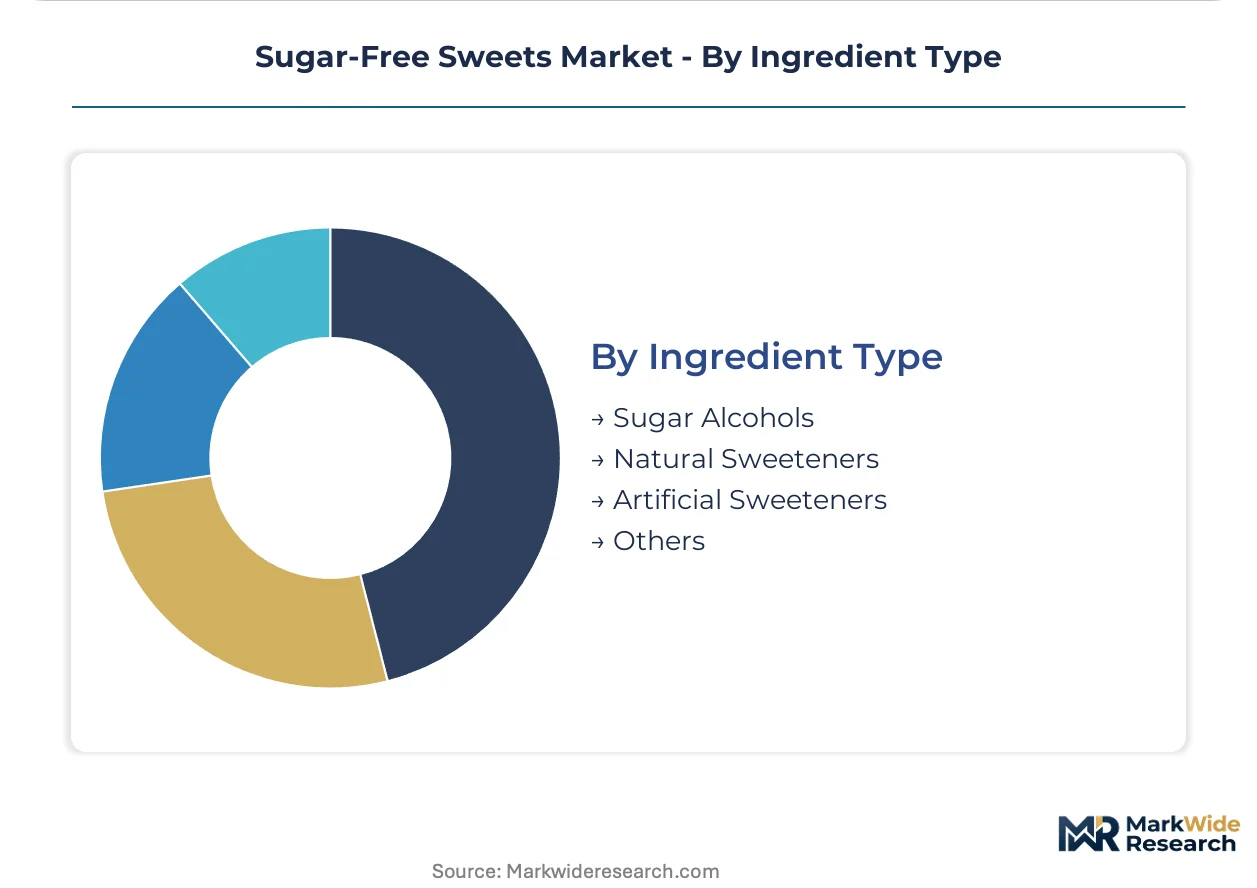
Ingredient Type:
Supply concentration in stevia extraction and allulose fermentation governs procurement strategy and carbon-accounting compliance under EU Green Deal rules.
- Sugar Alcohols:Maltitol and erythritol dominate current formulation volumes due to established EFSA approval and sensory familiarity. REACH residual solvent protocols elevate compliance costs for European manufacturers sourcing from non-EU extraction facilities, consolidating supplier relationships with certified renewable energy biorefineries.
- Natural Sweeteners:Enzymatic bioconversion of stevia glycosides automates removal of bitter rebaudioside fractions, enabling sensory parity with sucrose in premium chocolate applications. German and French manufacturers prioritize suppliers holding renewable power purchase agreements to satisfy Scope 2 disclosure mandates.
- Artificial Sweeteners:Sucralose and aspartame face clean-label rejection in premium positioning, retaining volume in economy-tier supermarket lines.
- Others:Rare sugar candidates including allulose await EFSA novel food approvals, with production capacity concentrated in North American facilities exposing European formulators to currency and shipping volatility.
Sugar alcohols dominate current volume, with natural sweeteners on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chocolate confectionery first achieved industrial scale in Switzerland during the nineteenth century, establishing the alpine corridor as the foundational cluster for sugar-free innovation. Modern formulation expertise now distributes across European manufacturing centers, with regulatory pressure from Brussels accelerating reformulation timelines.
Germany
Pharmacy distribution networks for glycemic-index-certified confections create dedicated infrastructure unavailable in mass retail. EFSA health claim authorizations govern permissible glucose-management language on packaging. Cologne and Frankfurt clusters host reformulation laboratories serving pan-European brand portfolios.
United Kingdom
Free-from retail consolidation in London and Manchester urban centers displaces supermarkets as the launch platform for premium sugar-free novelties. Front-of-pack nutrition labeling regulations compress formulation differentiation for private-label lines. Birmingham manufacturing facilities specialize in pectin-based gummy production for vegan-adjacent segments.
France
Clinical nutrition channels expand shelf space for diabetic management protocols, creating institutional demand distinct from wellness positioning. ANSM labeling constraints intersect with EFSA additive approvals to define marketing boundaries. Lyon and Paris basin production facilities prioritize bean-to-bar traceability certification.
Belgium
Praline houses anchor artisan positioning through small-batch polyol experimentation resistant to scaled manufacturing. REACH residual solvent protocols elevate compliance costs for stevia extraction sourcing. Brussels-Antwerp corridor facilities temper maltitol-based masses with humidity-controlled modifications.
Switzerland
Dark chocolate premium value pools concentrate in Zurich and Vevey manufacturing centers leveraging cocoa butter crystallization expertise. Swissmedic nutritional health claim guidelines intersect with EMA protocols to constrain permissible label language. Biorefinery supplier relationships consolidate around renewable power purchase agreements.
Sugar-Free Sweets Market Competitive Landscape
Capital-heavy producers with dedicated sugar-free manufacturing lines compete with asset-light brand licensors outsourcing formulation to third-party confectioners. The market structure consolidates around three tiers: multinational scale players operating pan-European facilities, premium specialists commanding bean-to-bar traceability premiums, and agile insurgents capturing vegan-adjacent segments through rapid format innovation. Strategic moves center on portfolio diversification into natural sweetener positioning and backward integration into stevia extraction supply chains.
Among Swiss-anchored premium specialists, Lindt & Sprüngli exemplifies the traceability-certification archetype, while Mondelez International represents multinational scale infrastructure. Mars occupies a position between these poles with dedicated production lines across multiple European facilities.
| Leading Market Players |
|---|
| Mondelez International |
| Russell Stover |
| The Hershey Company |
| Haribo |
| SmartSweets |
| Mars |
| Lindt & Sprüngli |
| Ferrero |
| Nestlé |
| Others |
Value Network & Pricing Analysis
Belgian formulation chemists with cocoa butter crystallization expertise command wage premiums that compress margin spreads between artisan praline tiers and mass-market chocolate lines. Labor-cost differentials between alpine corridor specialists and Eastern European contract manufacturers feed directly into three-tier pricing stratification across premium, standard, and economy levels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates bean-to-bar certified collections from private-label supermarket lines. Price differentiation rests on EFSA health claim authorization status and renewable energy certification under EU Green Deal carbon-accounting rules. Cost compression in economy tiers is intensifying because REACH residual solvent compliance elevates stevia extraction costs for non-EU suppliers. Health-conscious consumers in United Kingdom health food stores exhibit lowest price sensitivity, while supermarket private-label buyers absorb margin pressure fastest.
Supply Chain Analysis
Certification gating through EFSA novel food approvals and REACH residual solvent protocols concentrates stevia extraction in France, Germany, and Switzerland. Raw material dependencies center on stevia leaf supply from China and Paraguay, maltitol feedstock from European corn refiners, and allulose from North American biorefineries. Single-source vulnerability in allulose fermentation exposes European formulators to transatlantic shipping cost volatility. Distribution runs through health food store networks in United Kingdom urban clusters, pharmacy channels in Germany and France, and direct-to-consumer subscriptions for diabetic management protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise scarcity in Belgium and Switzerland against regulatory compliance cost advantages in Eastern European manufacturing creates geographic-arbitrage potential for portfolio reconfiguration. The spread between EFSA approval timelines in Brussels and national health claim authorization in Paris generates location-sensitive launch sequencing.
For Market Incumbents: To counter clean-label insurgents capturing vegan-adjacent gummy segments, Mondelez International and Lindt & Sprüngli should deepen backward integration into enzymatic stevia bioconversion supply chains. Capacity addition in humidity-controlled tempering facilities across the Brussels-Antwerp corridor defends against bloom defect risks in maltitol-based mass production. For New Entrants and Emerging Players: Capture pectin-based gummy white space in United Kingdom free-from retail clusters where gelatin-free positioning commands shelf space premiums. The most penetrable segment combines diabetic management protocols with fitness enthusiast post-workout positioning in German sports nutrition channels. Direct-to-consumer subscription models bypass pharmacy markup structures in French clinical nutrition distribution. For Investors and Strategic Acquirers: Mid-cap confectioners with captive stevia extraction capabilities and renewable power purchase agreements are the most active acquirer targets in this space for multinational scale players seeking carbon-accounting compliance. Long-term viability across the analysis window hinges on pre-positioned formulation pipelines for pending EFSA novel sweetener approvals. Watch for allulose EFSA authorization timeline compression as the inflection signal triggering consolidation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stevia Extraction | Captures carbon-accounting compliance advantage under EU Green Deal Scope 2 disclosure mandates. |
| Pectin-Based Gummy Line Extension | Penetrates vegan-adjacent demand in United Kingdom health food channels beyond diabetic segments. |
| Humidity-Controlled Tempering Retrofit | Enables defect-free maltitol mass production without legacy equipment replacement. |
| Direct-to-Consumer Subscription Launch | Bypasses pharmacy markups in German and French diabetic management distribution. |
| Renewable Energy Certification Program | Satisfies EFSA-aligned procurement criteria for premium health food store positioning. |
Research Methodology
Direct dialogue with formulation chemists at Belgian praline houses, procurement leads at German health food retail chains, EFSA regulatory affairs specialists, and plant managers at Swiss chocolate manufacturing facilities grounded qualitative insights. Secondary validation drew from EMA guideline documents, EFSA novel food approval registers, REACH compliance databases, and EU Green Deal carbon-accounting protocols. Bottom-up volume modeling across ingredient type and distribution channel segments triangulated against top-down value projections from national confectionery trade associations.
Bottom-up unit economics for stevia glycoside processing and allulose fermentation fed into top-down market sizing across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, distribution channel control, and ingredient certification tier. CAGRs were derived from elasticity-adjusted demand curves incorporating reformulation mandate compliance deadlines and EFSA approval pipeline status. Industry-specific forecast inputs encompassed enzymatic bioconversion yield improvements and pectin-based gummy setting-time reductions.
EFSA novel sweetener approval delays, REACH residual solvent threshold revisions, and EU Green Deal carbon-accounting rule expansions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about regulatory timeline stability and supply chain energy sourcing verification. A model refresh is warranted upon material change in EFSA opinions regarding next-generation high-intensity sweetener candidates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Confectionery Fillings Market
Confectionery
Salted Caramel Products Market
Confectionery
Middle-East and Africa Compound Chocolate Market
Confectionery
Asia-Pacific Cocoa Products Market
Confectionery
Global Chocolate Market
Confectionery
Global Confectionery Market
Confectionery
North America Dark Chocolate Market
Confectionery
India Chocolate Market
Confectionery
White Chocolate Market
Confectionery
Jellies and Gummies Market
Confectionery
South America Chocolate Market
Confectionery
North America Sugar-Free Chewing Gum Market
Confectionery
Global Non-Cocoa Confectionery Market
Confectionery
Coffee Gummy Market
Confectionery
Mooncake Market
Confectionery
Black Treacle Market