
 United States Caramel Chocolate Market | 2026-2036
United States Caramel Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
United States Caramel Chocolate Market Intelligence
Cocoa butter alternatives are pivoting toward shea and palm oil blends as manufacturers manage input costs without sacrificing mouthfeel. Mars Incorporated leverages vertical integration from bean sourcing through retail distribution to protect margin structures. The Hershey Company sustains dominant shelf presence in mass retail through proprietary caramel formulations. Mondelez International anchors its position via R&D intensity in enrobing technology and seasonal limited editions.
Caramel chocolate denotes a confection wherein caramel filling or caramelized sugar inclusions are enrobed in or combined with chocolate matrices, typically requiring controlled moisture activity below 0.65 to prevent sugar bloom and ensure shelf stability. The product serves commercial purposes spanning impulse retail, seasonal gifting, and industrial ingredient supply to bakeries and foodservice operators. Milk chocolate variants occupy the largest volume share due to established consumer preference and lower bitterness profiles that complement caramel sweetness. Dark chocolate segments attract premium positioning and cleaner-label formulations. Artisan chocolate sub-categories command disproportionate margin pools through small-batch positioning and local sourcing narratives despite smaller absolute volumes.
FDA food labeling regulations, USDA organic certification standards, and state-level sugar-sweetened beverage tax frameworks collectively shape permissible health claims and formulation thresholds across the United States. Compliance with FDA allergen disclosure requirements and evolving California Proposition 65 guidance on heavy metals directly impacts product labeling costs and reformulation cycles. Stakeholders must monitor state legislative divergence on sugar taxation and federal front-of-package labeling proposals to anticipate margin compression and channel-specific demand shifts.
Market Dynamics
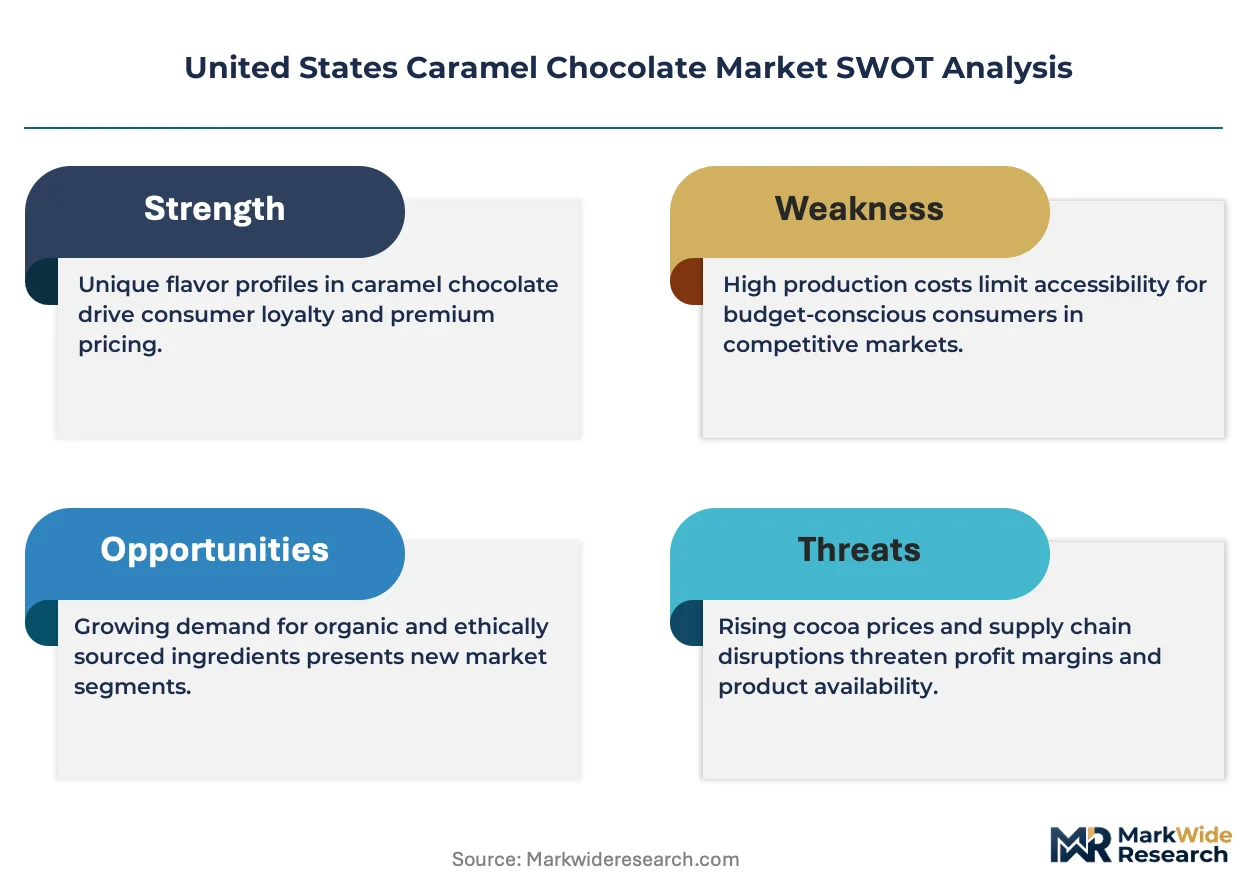
State-level sugar-sweetened beverage tax frameworks and FDA front-of-package labeling proposals are compressing formulation margins while forcing rapid reformulation cycles across US caramel chocolate production.
Growth Catalysts
- Experiential gifting expansion:Premium confectionery brands target gift buyers with artisan positioning and local sourcing narratives, expanding average transaction values in specialty retail channels.
- California Proposition 65 guidance evolution:Heavy metals disclosure requirements accelerate cleaner supply chain sourcing, creating first-mover advantages for compliant manufacturers.
- Enrobing technology advancement:Controlled moisture activity systems below 0.65 water activity enable extended shelf stability without artificial preservatives, opening cleaner-label positioning.
Market Restraints
- Cocoa butter input volatility:Price swings in cocoa derivatives force shea and palm oil blend substitution, altering mouthfeel profiles and consumer acceptance thresholds.
- Northeast corridor retail concentration:Specialty chocolate density in urban coastal markets limits geographic diversification for artisan producers dependent on foot traffic.
- USDA organic certification cost burden:Small-batch producers face disproportionate compliance expenses relative to volume, constraining margin recovery.
Strategic Opportunities
- Industrial ingredient supply expansion:Bakery and foodservice operator demand for caramel chocolate inclusions remains underpenetrated relative to retail channels.
- California specialty retail density:Los Angeles and San Francisco clusters support premium price realization for bean-to-bar caramel chocolate positioning.
- Seasonal limited edition velocity:Holiday and occasion-based product rotations command shelf space premiums and social media amplification.
Industry Challenges
- Allergen disclosure complexity:FDA labeling requirements for milk, soy, and tree nuts demand dedicated production line segregation, inflating capital intensity for multi-SKU portfolios.
- Sugar bloom prevention expertise:Controlled crystallization and tempering skill gaps constrain workforce scalability for premium enrobing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Caramel Chocolate Market |
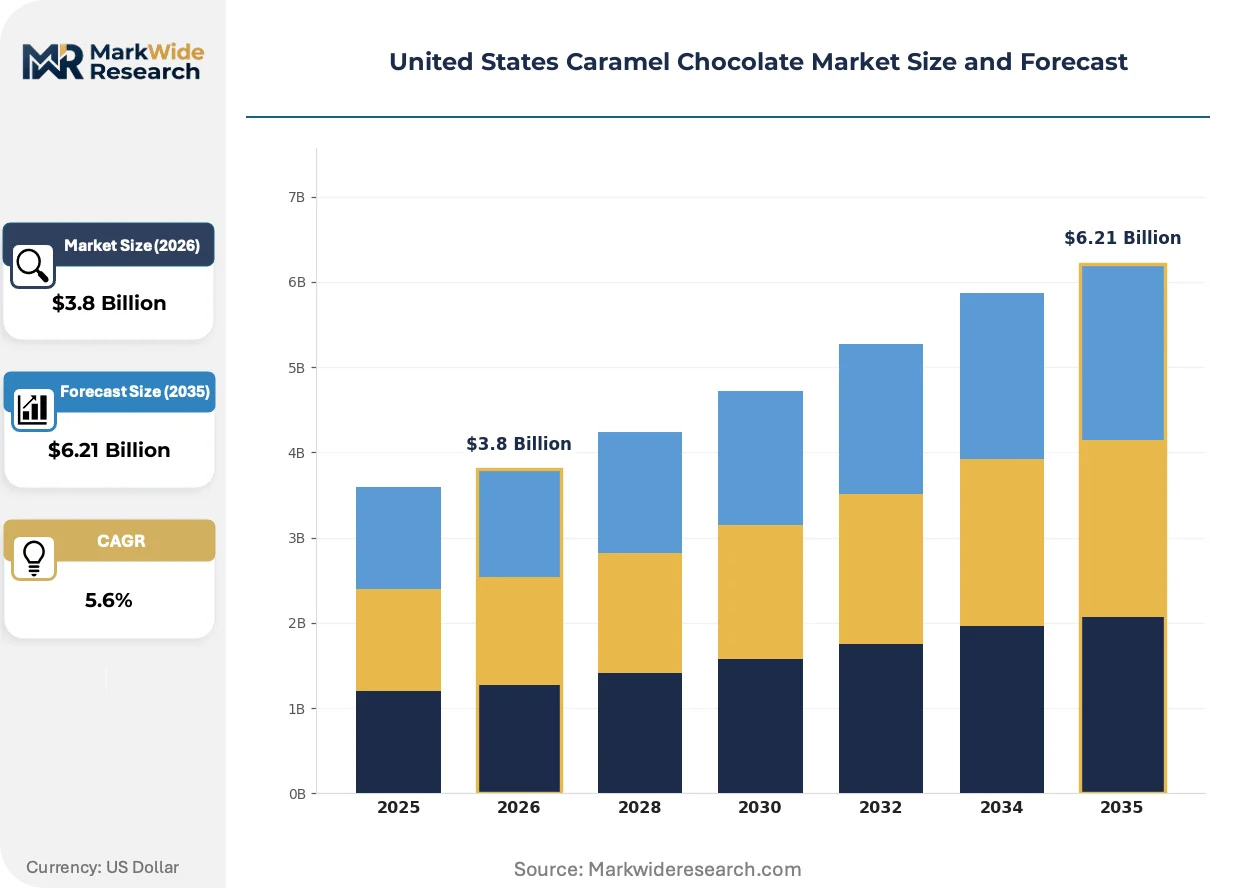
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Chocolate, Dark Chocolate, White Chocolate, Artisan Chocolate Packaging Type: Bags, Bars, Boxes, Cups Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Shops End User: Adults, Children, Baking Industry, Gift Buyers |
| Companies Covered | Mars Incorporated, The Hershey Company, Mondelez International, Ferrero Group, Nestlé, Lindt & Sprüngli, Barry Callebaut, Ghirardelli Chocolate Company, Godiva Chocolatier, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Caramel Chocolate Market Strategic Shifts & Innovations
Reformulation pressure from sugar taxation and clean-label demand is accelerating ingredient substitution and process automation across US caramel chocolate manufacturing.
Precision enrobing systems with real-time moisture monitoring is rewriting quality consistency standards for caramel-filled confections. Mid-tier manufacturers adopt these systems to reduce manual tempering labor and shrink defect rates. The technology is compressing the quality gap between artisan and scaled production, forcing premium brands to differentiate through sourcing narratives rather than technical execution alone.
FDA front-of-package labeling proposals are mandating added sugar disclosure prominence that reshapes permissible health claims. Manufacturers reformulate to reduce total sugar content while maintaining caramel sweetness perception through flavor modulation. Dark chocolate caramel segments face disproportionate impact as their premium positioning relies heavily on perceived health halo effects.
Direct-to-consumer subscription models disrupt traditional grocery and specialty retail distribution for regional artisan brands. California and Pacific Northwest consumers lead adoption of monthly chocolate clubs that bypass shelf-space competition. This channel rotation enables margin capture previously surrendered to distributor markups and slotting fees.
United States Caramel Chocolate Market Segmentation
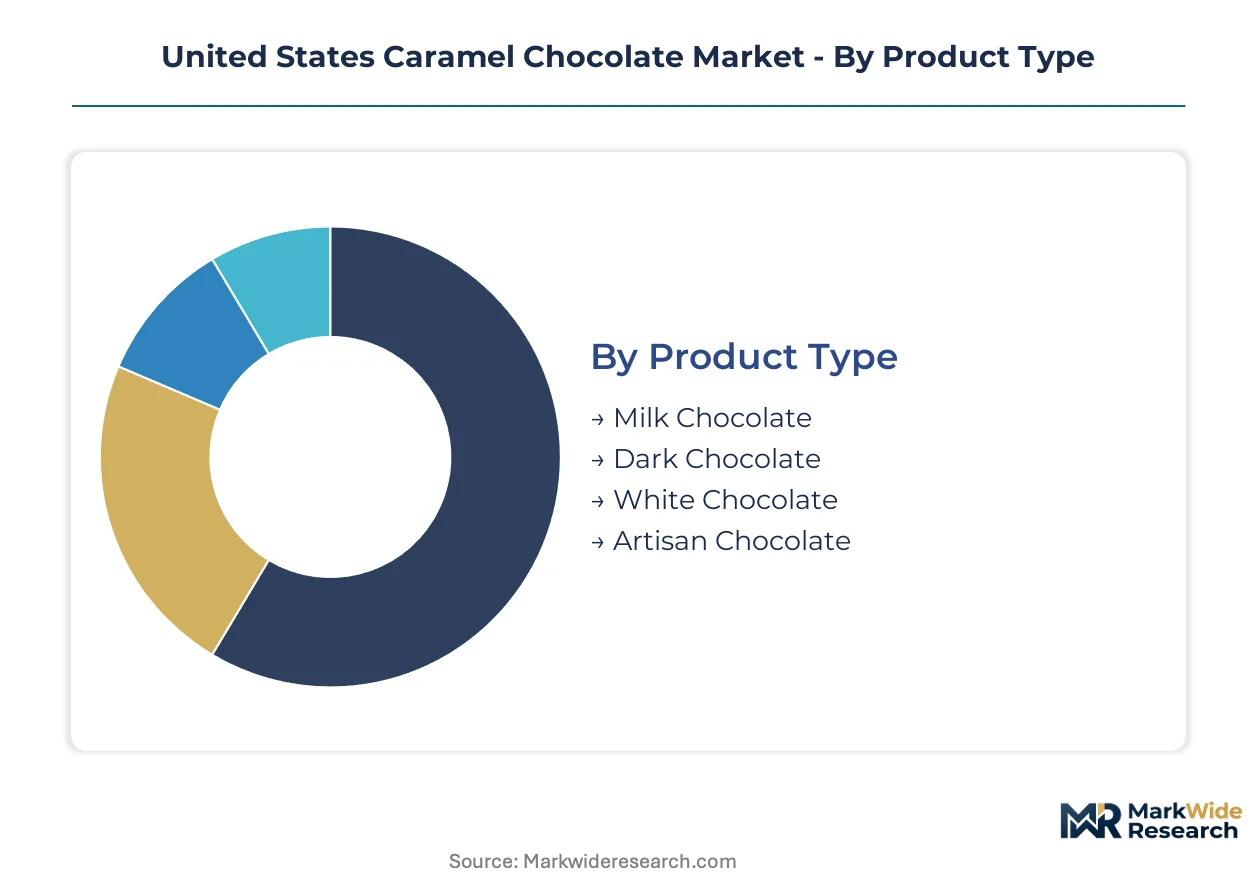
Caramel chocolate manufacturers calibrate portfolio depth across four intersecting dimensions. Product type and packaging format decisions cascade through distribution channel selection and end-user targeting.
Product Type:
Upgrade cycles in caramel chocolate track shifting bitterness tolerance and clean-label priorities among repeat purchasers.
- Milk Chocolate:Lower cocoa solid matrices between 10-50% temper caramel sweetness without aggressive bitterness. Mass retail placement in California and Northeast corridor supermarkets sustains volume leadership through established household penetration.
- Dark Chocolate:Cocoa content exceeding 50% enables premium positioning and antioxidant health claims. FDA front-of-package labeling proposals on added sugar disproportionately pressure this segment's perceived wellness halo.
- White Chocolate:Cocoa butter-dominant formulations without cocoa solids carry higher fat content and distinct sweetness profiles. Seasonal limited editions exploit its visual contrast in gift assortments.
- Artisan Chocolate:Small-batch production with bean-to-bar sourcing narratives commands shelf space premiums in specialty retail clusters.
Volume placements concentrate in Milk Chocolate; the faster expansion belongs to Artisan Chocolate.
Packaging Type:
Packaging cost tiers separate impulse convenience formats from occasion-driven premium presentations.
- Bars:Single-serve and multi-serve formats dominate checkout lane impulse placement. Convenience store distribution maximizes velocity through grab-and-go accessibility.
- Boxes:Assortment packaging supports experiential gifting with partitioned caramel varieties. Specialty shops in Los Angeles and San Francisco clusters realize price premiums through visual merchandising.
- Bags:Flexible pillow and stand-up pouch formats reduce per-unit material cost for value-tier positioning. Supermarket seasonal displays drive periodic volume spikes.
- Cups:Individual portion cups with peelable foil lids target foodservice and bakery ingredient applications. Industrial supply contracts favor this format for portion control consistency.
Production runs concentrate in Bars; the steepest expansion trajectory belongs to Boxes.
Distribution Channel:
Channel selection determines margin capture versus volume throughput trade-offs for caramel chocolate portfolios.
- Supermarkets:Mass retail shelf space competition demands slotting fee investments and promotional velocity. Northeast corridor density supports regional brand consolidation.
- Specialty Shops:Curated assortment and staff expertise enable storytelling around sourcing and craftsmanship. California bean-to-bar producers leverage direct relationships with independent retailers.
- Online Retail:Direct-to-consumer subscription models bypass distributor markups for artisan brands. Pacific Northwest consumers show highest adoption of monthly chocolate clubs.
- Convenience Stores:Limited SKU count and rapid inventory turns favor established national brands with proven velocity metrics.
Transaction volume concentrates in Supermarkets; gaining share fastest is Online Retail.
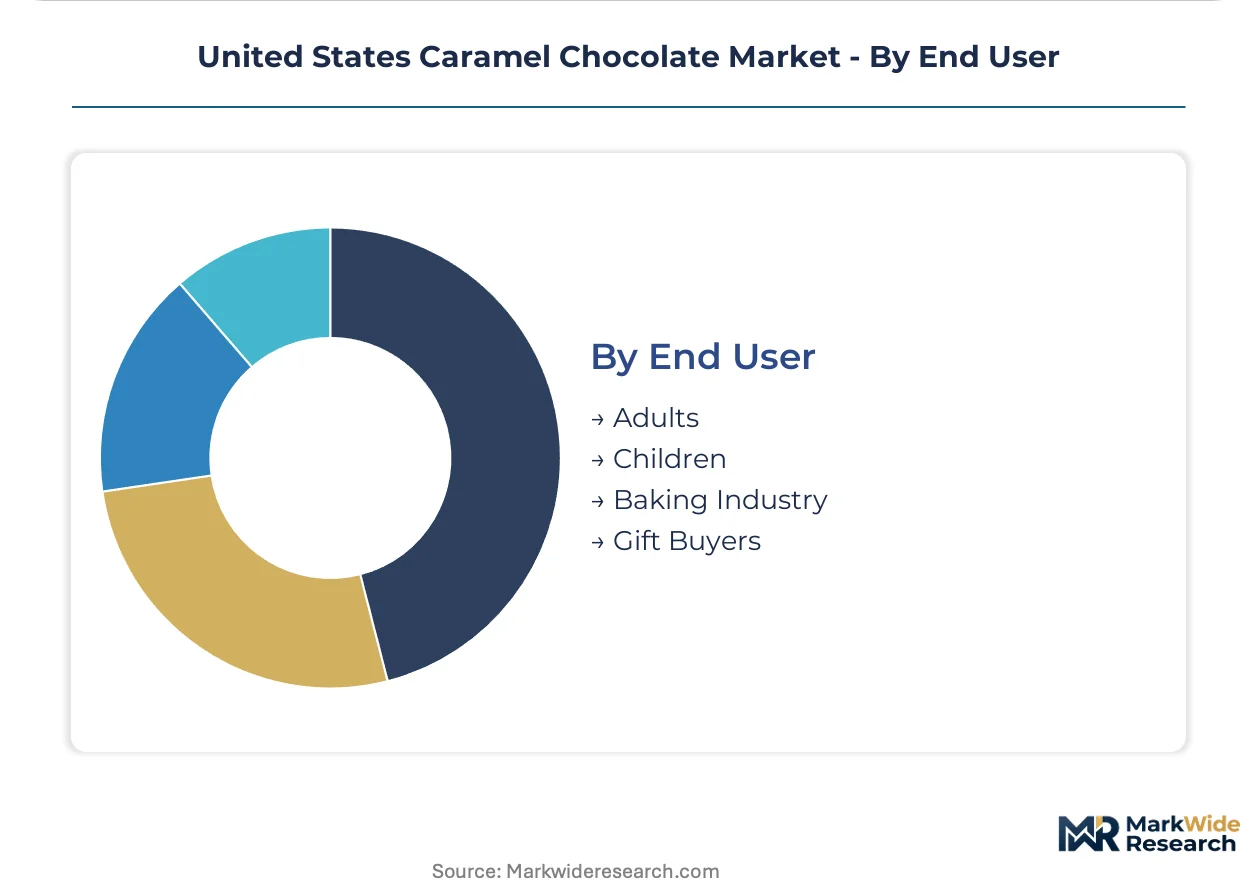
End User:
End-user targeting shapes formulation sweetness, portion sizing, and occasion messaging for caramel chocolate deployment.
- Adults:Sophisticated palates drive dark chocolate and sea salt caramel combinations. Clean-label and reduced-sugar variants align with FDA labeling disclosure trends.
- Gift Buyers:Experiential gifting expansion elevates artisan packaging and local sourcing narratives. Holiday and occasion-based rotations command social media amplification.
- Children:Milk chocolate dominance and character licensing partnerships sustain this segment. State-level sugar-sweetened beverage tax frameworks indirectly pressure permissible formulation thresholds.
- Baking Industry:Industrial ingredient demand for caramel chocolate chips and chunks remains underpenetrated relative to retail channels. Foodservice operators seek controlled moisture activity specifications below 0.65 for shelf-stable inclusions.
Current consumption concentrates in Adults; climbing the fastest is Gift Buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in distressed urban census tracts concentrate specialty chocolate manufacturing investments through capital gains tax deferrals, anchoring production clusters in historically underutilized commercial districts.
California
Los Angeles and San Francisco specialty retail density supports premium bean-to-bar caramel chocolate positioning. FDA Proposition 65 heavy metals disclosure requirements accelerate cleaner supply chain sourcing for compliant West Coast producers. San Francisco's Ferry Building Marketplace and Los Arts District host concentrated artisan chocolate retail clusters where direct-to-consumer subscription models bypass traditional distributor markups.
Northeast Corridor
New York Metro and Greater Boston gift buyer concentration drives experiential gifting velocity for premium assortment packaging. State-level sugar-sweetened beverage tax frameworks in Connecticut and New York reshape permissible formulation thresholds for mass-market distribution. Brooklyn's Industry City and Boston's Seaport District warehouse conversions house small-batch caramel chocolate producers leveraging local sourcing narratives.
Pacific Northwest
Portland and Seattle consumers show highest adoption rates of monthly chocolate club subscriptions. Oregon and Washington state organic certification cost-sharing programs reduce USDA compliance burden for small-batch producers. Portland's Pearl District chocolate collective and Seattle's Fremont artisan food hub concentrate regional specialty manufacturing capacity.
Southeast
Florida and Georgia convenience store channel expansion creates impulse retail placement opportunities for single-serve caramel chocolate formats. Georgia's film production tax credits indirectly support confectionery product placement and co-marketing campaigns. Atlanta's Westside Provisions District and Miami's Wynwood Arts District host emerging specialty chocolate retail and tasting room concepts.
Midwest
Illinois and Michigan industrial ingredient demand from bakery and foodservice operators remains underpenetrated relative to retail channels. Michigan's Good Food Fund provides catalytic capital for food manufacturing startups including caramel chocolate specialists. Chicago's Fulton Market and Detroit's Eastern Market food halls anchor regional specialty food distribution networks.
United States Caramel Chocolate Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with mass retail shelf space consolidating around vertically integrated national portfolios while artisan channels fragment across regional bean-to-bar producers. Three archetypes dominate: multinational confectionery conglomerates with captive cocoa supply chains; mid-tier regional manufacturers leveraging co-packing relationships; and micro-scale artisan specialists dependent on direct-to-consumer subscription velocity. Competitive moves concentrate on M&A-driven portfolio diversification into cleaner-label positioning and strategic partnerships with specialty retail distributors to secure shelf space premiums.
Within the multinational conglomerate tier, Mars Incorporated and The Hershey Company exemplify scale-driven supply chain control, while Mondelez International occupies a position emphasizing R&D intensity in enrobing technology. These three entities anchor the mass-market caramel chocolate segment through distinct strategic postures: Mars through backward integration into bean sourcing, Hershey through proprietary caramel formulation dominance, and Mondelez through seasonal limited edition velocity.
| Leading Market Players |
|---|
| Mars Incorporated |
| The Hershey Company |
| Mondelez International |
| Ferrero Group |
| Nestlé |
| Lindt & Sprüngli |
| Barry Callebaut |
| Ghirardelli Chocolate Company |
| Godiva Chocolatier |
| Others |
Cost & Logistics Intelligence
California Proposition 65 heavy metals disclosure requirements gate both qualified supply and premium-tier pricing access for caramel chocolate manufacturers, as compliant West Coast producers command shelf space premiums while non-compliant competitors face reformulation cost compression or market exclusion.
Pricing Analysis
Short lead-time premiums separate artisan bean-to-bar producers from mass-market inventory liquidators in the United States caramel chocolate market. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and local sourcing narrative intensity. Pricing pressure stems from FDA front-of-package labeling proposals forcing sugar reduction without caramel sweetness perception loss. Mass retail buyers exhibit highest price sensitivity; gift buyers in California specialty clusters show lowest.
Supply Chain Analysis
Cocoa butter supply rests on West African and Southeast Asian agricultural output subject to climate volatility and political instability. Shea and palm oil blend substitution draws from Malaysian and Indonesian processing capacity. Single-source vulnerability concentrates in Ghana and Ivory Coast cocoa bean origination. Distribution runs through vertically integrated national conglomerates, regional co-packing networks, and direct-to-consumer subscription fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States caramel chocolate market functions as a cost-of-compliance story where FDA allergen disclosure requirements and state-level sugar-sweetened beverage tax frameworks erect barrier-to-entry moats favoring capitalized incumbents with dedicated production line segregation and reformulation R&D capacity.
For Market Incumbents: Cement shelf space dominance through proprietary enrobing technology acquisition and seasonal limited edition velocity acceleration. Counter direct-to-consumer subscription disruption by acquiring regional artisan brands with established California and Pacific Northwest subscriber bases. FDA front-of-package labeling proposals demand preemptive sugar reduction investment to preserve health claim permissibility. For New Entrants and Emerging Players: Begin with industrial ingredient supply contracts to bakeries and foodservice operators, the most penetrable segment relative to saturated retail channels. Target Midwest bakery clusters in Illinois and Michigan where caramel chocolate inclusion demand remains underpenetrated. Pursue USDA organic certification cost-sharing programs in Oregon and Washington to offset compliance burden. For Investors and Strategic Acquirers: California specialty retail density expansion is the leading indicator that bean-to-bar caramel chocolate positioning commands sustainable margin pools. Over the medium-term horizon, acquisition targets include vertically integrated regional producers with captive cocoa sourcing and established direct-to-consumer subscription velocity. Watch for FDA finalization of front-of-package labeling rules as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cleaner-Label Reformulation | FDA added sugar disclosure proposals force rapid ingredient substitution without caramel sweetness perception degradation. |
| Direct-to-Consumer Subscription Launch | Pacific Northwest consumer adoption of monthly chocolate clubs bypasses distributor markups and slotting fee compression. |
| Industrial Ingredient Supply Expansion | Bakery and foodservice operator demand for controlled moisture activity inclusions remains underpenetrated relative to retail. |
| Precision Enrobing Technology Acquisition | Real-time moisture monitoring systems below 0.65 water activity enable extended shelf stability without artificial preservatives. |
| California Proposition 65 Compliance Investment | Heavy metals disclosure requirements accelerate cleaner supply chain sourcing, creating first-mover advantages for compliant West Coast producers. |
Research Approach
Multi-period observation of FDA labeling proposal evolution, state sugar tax adoption patterns, and specialty retail cluster formation anchored the trend analysis, supplemented by interviews with caramel chocolate brand managers, category buyers at Northeast corridor supermarkets, USDA organic certification consultants, and enrobing technology equipment suppliers. Secondary validation drew from FDA docket submissions, California Office of Environmental Health Hazard Assessment guidance documents, state legislative records, and Nielsen retail audit data. Bottom-up volume modeling and top-down value triangulation ensured cross-verification.
Segment-weighting across product type, packaging format, distribution channel, and end-user dimensions structured the analytical framework over the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Cocoa butter price volatility indices and enrobing equipment deployment rates served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; mass retail transaction volume carries tighter precision than artisan subscription velocity. Forecasts reflect assumptions on regulatory timeline finalization and consumer bitterness tolerance evolution. State legislative divergence on sugar taxation and FDA rulemaking pace warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
US Confectionery Market
Confectionery
Jellies and Gummies Market
Confectionery
Global Sugar Free Chewing Gums Market
Confectionery
United States and Europe Macarons Market
Confectionery
Liquorice Shellac Market
Confectionery
Premium Chocolate Market
Confectionery
Middle East and Africa Confectionery Market
Confectionery
Global Chocolate Sprinkles Market
Confectionery
Asia-Pacific Cocoa Products Market
Confectionery
South America Chocolate Market
Confectionery
Low Calorie Keto Desserts Market
Confectionery
Asia Pacific Sugar Confectionery Market
Confectionery
Saudi Arabia Chocolate Market
Confectionery
Salted Caramel Products Market
Confectionery
North America Sugar Confectionery Market
Confectionery
Chocolate Inclusions and Decorations Market