
 Licorice Candy Market | 2026-2036
Licorice Candy Market Size, Share, and Industry Trends Forecast 2026-2036
Licorice Candy Market Outlook
Premium licorice tiering is bifurcating the competitive landscape as consumers trade up toward artisanal and clean-label variants. Perfetti Van Melle leverages its pan-European distribution infrastructure to sustain shelf dominance across multiple quality tiers. Haribo GmbH & Co. KG anchors its position through specialized black licorice formulations that dominate German-speaking markets. Katjes Fassin GmbH & Co. KG differentiates via plant-based and reduced-sugar recipes that occupy the premium-natural intersection.
Licorice candy denotes confectionery products formulated from liquorice root extract (Glycyrrhiza glabra), typically containing glycyrrhizin concentrations between 2-8% by weight, combined with sweeteners, binders, and flavor modifiers through extrusion or casting processes. Black Licorice commands the mature volume base in Northern Europe while Red Licorice captures faster growth in North American and Australasian markets where anise-free profiles dominate. Online Shoppers represent the fastest-expanding end-user channel as direct-to-consumer platforms reshape traditional Wholesale Distributor intermediation.
EFSA glycyrrhizin intake guidelines and FDA GRAS oversight for licorice extract constrain formulation thresholds and label claims across European and American markets. REACH chemical registration requirements and EU Food Information to Consumers (FIC) regulations further standardize cross-border ingredient transparency. Stakeholders must monitor evolving glycyrrhizin threshold debates and adapt sourcing strategies before regulatory tightening accelerates reformulation costs.
Market Dynamics
Clean-label reformulation mandates under EFSA and FDA frameworks are compressing glycyrrhizin thresholds and forcing ingredient substitution across European and North American manufacturing bases. This regulatory compression is redrawing competitive advantage toward vertically integrated extract processors with captive licorice root supply chains.
Growth Catalysts
- EFSA Glycyrrhizin Guidance:Tightening intake thresholds are accelerating premium-tier demand as manufacturers reformulate toward reduced-glycyrrhizin and deglycyrrhizinated licorice (DGL) variants that command higher per-unit pricing.
- Specialty Retail Channel Expansion:Artisanal confectionery shops and gourmet food halls in Germany, the Netherlands, and Denmark are creating dedicated shelf space for small-batch licorice with provenance labeling and single-origin root sourcing.
- Plant-Based Binder Technologies:Pectin and tapioca starch extrusion systems are displacing gelatin-based processes, unlocking vegan certification access and expanding addressable consumer bases in flexitarian demographics.
Market Restraints
- Licorice Root Supply Concentration:Over 70% of global Glycyrrhiza glabra cultivation clusters in Azerbaijan, Uzbekistan, and Turkmenistan, exposing processors to geopolitical disruption and climate-induced harvest volatility.
- REACH Chemical Registration Burden:European flavor compound importers face escalating compliance costs for extract purity documentation and novel food additive dossier preparation under ECHA oversight.
- Natural Sweetener Price Volatility:Stevia and monk fruit extract costs fluctuate with agricultural yields in Guangxi and Yunnan provinces, compressing margin stability for reduced-sugar product lines.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:Curated licorice clubs and quarterly flavor releases via Shopify and WooCommerce platforms are bypassing traditional wholesale distributor markups and capturing full retail margin.
- Functional Confectionery Positioning:Adaptogenic licorice formulations incorporating ashwagandha or L-theanine are penetrating wellness-oriented retail channels in California and New South Wales where botanical-infused candies carry premium positioning.
- EU Farm-to-Fork Strategy Alignment:Sustainability certification and organic root sourcing under the European Green Deal are qualifying producers for green procurement tenders and public sector vending contracts.
Industry Challenges
- Extract Standardization Expertise Gap:Qualified analytical chemists capable of glycyrrhizin potency validation and HPLC method development remain scarce in contract manufacturing organizations across Central and Eastern Europe.
- Legacy Equipment Retrofit Costs:Continuous extrusion lines designed for high-glycyrrhizin formulations require capital-intensive die and cooling tunnel modifications to process DGL and alternative binder matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Licorice Candy Market |
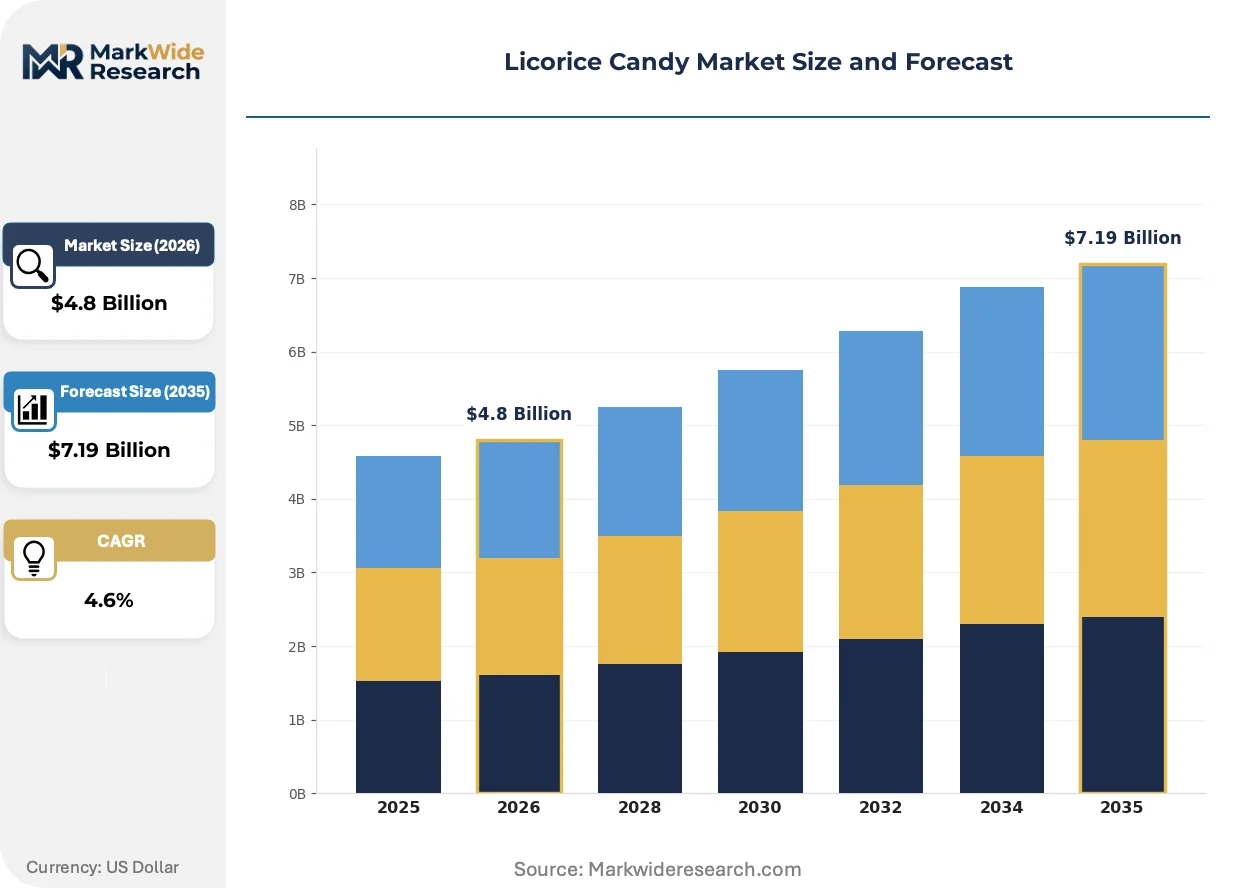
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Licorice, Black Licorice, Twists, Pieces End User: Retail Consumers, Wholesale Distributors, Online Shoppers, Confectionery Manufacturers Flavor Profile: Sweet, Salty, Herbal, Spicy Packaging Type: Bags, Boxes, Bulk, Individual Wraps |
| Companies Covered | Perfetti Van Melle, Trolli, The Hershey Company, Ferrara Candy Company, Cloetta, Mondelez International, Katjes Fassin GmbH & Co. KG, Australian Licorice Company, Haribo GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Licorice Candy Market Strategic Shifts
Extrusion and coating technologies are converging with precision flavor delivery systems, enabling micro-encapsulation of volatile anise and herbal notes that previously degraded during thermal processing. These advances are expanding the sensory palette available to product developers.
Micro-encapsulation spray-drying technology using modified starch and gum arabic wall systems is miniaturizing flavor particle size to sub-50-micron distributions. Premium artisanal producers in Copenhagen and Amsterdam are adopting these systems to layer complex botanical profiles within single candy pieces. This capability is compressing the innovation cycle between concept and commercial launch from 18 months to under 8 months.
REACH authorization requirements for glycyrrhizin-containing preparations are tightening purity thresholds and migration limits for food-contact materials. German and Dutch manufacturers are responding by investing in in-house extraction and purification capacity rather than relying on third-party compounders. The black licorice segment faces the steepest compliance burden due to higher extract loadings in traditional formulations.
Subscription-based replenishment models are displacing impulse-driven supermarket purchases among core licorice consumers. Specialty e-commerce platforms in Sweden and Finland are capturing recurring revenue through curated monthly boxes featuring regional variants and limited-edition releases. This shift is most pronounced among consumers aged 35-55 with established brand loyalties and higher lifetime value profiles.
Licorice Candy Market Segmentation
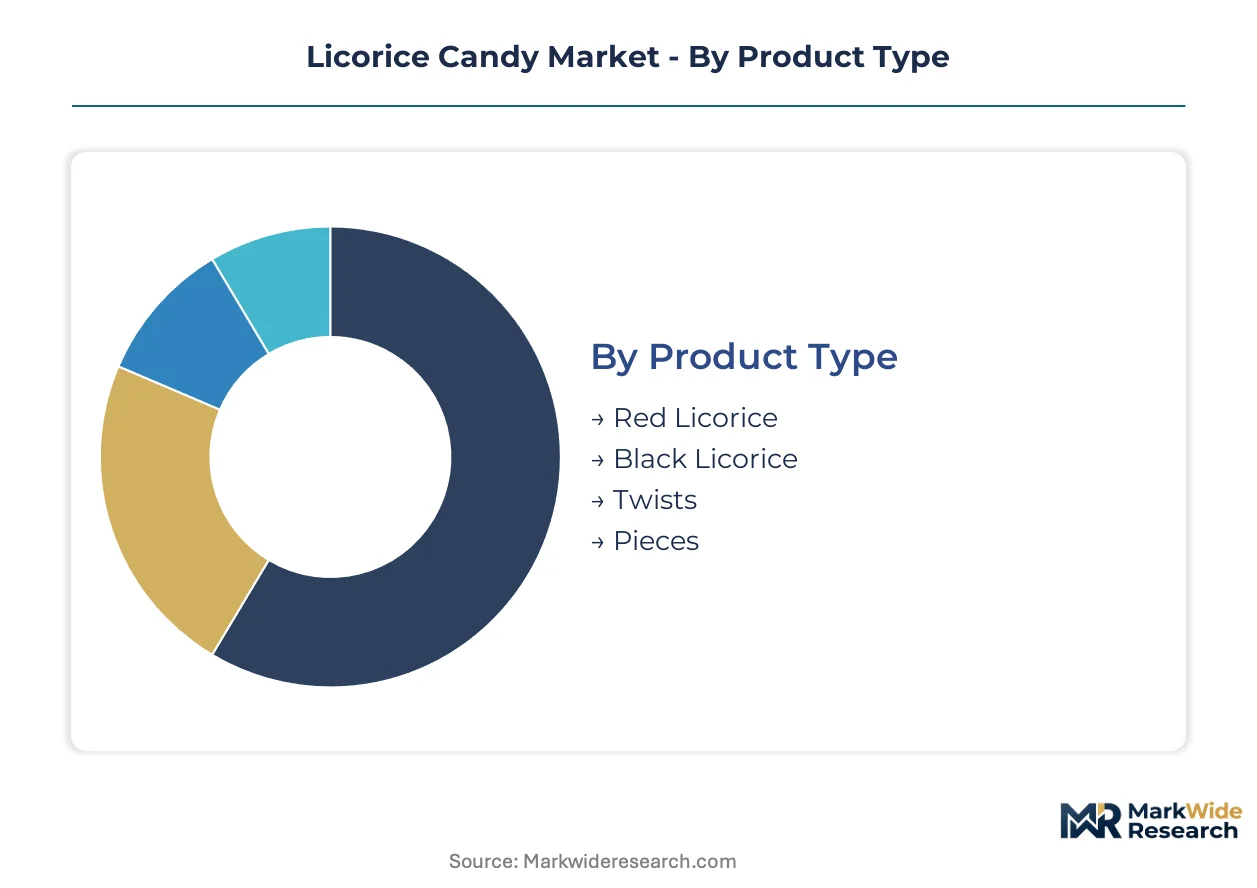
Segmentation in licorice candy reveals how formulation chemistry and channel economics create divergent margin profiles. Understanding where substitution pressure concentrates helps processors allocate R&D budgets across glycyrrhizin-modified and anise-free product lines.
Product Type:
Substitute pressure from fruit-flavored chewy candies and sour confectionery hits red licorice variants hardest, while black licorice maintains defensive positioning through cultural habituation in Northern European markets.
- Black Licorice:Formulated with Glycyrrhiza glabra extract at 2-8% glycyrrhizin concentration, this segment anchors volume in Germany, the Netherlands, and the Nordic countries where consumption remains culturally embedded. EFSA intake thresholds are accelerating reformulation toward deglycyrrhizinated variants that command premium shelf positioning.
- Red Licorice:Anise-free formulations using strawberry, cherry, or raspberry flavoring systems dominate North American and Australasian markets where traditional licorice notes face rejection. Plant-based pectin binders are displacing gelatin to unlock vegan certification access in California and New South Wales flexitarian demographics.
- Twists:Extruded rope formats with twisted geometry enable portion control messaging and extended consumption occasions.
- Pieces:Bite-sized formats suit vending machine distribution and impulse checkout placement in German railway stations and Dutch convenience stores.
Black Licorice retains volume leadership; Red Licorice holds the steepest expansion curve.
End User:
Channel cost structures determine margin capture, with direct-to-consumer platforms compressing wholesale distributor economics through disintermediation.
- Online Shoppers:Shopify and WooCommerce subscription models bypass traditional markups and capture full retail margin through curated quarterly releases. Swedish and Finnish platforms are pioneering recurring revenue boxes featuring regional variants and limited-edition botanical infusions.
- Retail Consumers:Supermarket and specialty confectionery purchases concentrate in German-speaking markets where Haribo and Katjes maintain shelf dominance through multi-tier distribution agreements.
- Wholesale Distributors:Traditional intermediation faces compression as manufacturers build direct relationships with artisanal shops in Copenhagen and Amsterdam gourmet food halls.
- Confectionery Manufacturers:Industrial buyers source licorice extract for inclusion in composite products, driving demand for standardized glycyrrhizin potency and REACH-compliant documentation.
Online Shoppers are expanding most quickly; Retail Consumers maintain the deepest revenue base.
Flavor Profile:
Palate diversification through micro-encapsulation technology is fragmenting traditional sweet-dominant formulations across multiple sensory-positioned tiers.
- Sweet:Conventional sucrose or glucose-syrup formulations with balanced glycyrrhizin bitterness masking remain the default in mass-market German retail.
- Salty:Ammonium chloride (salmiakki) variations dominate Finnish and Dutch markets where saline-herbal profiles constitute a distinct sub-category with dedicated consumer loyalty.
- Herbal:Botanical infusions incorporating fennel, anise, or mint are penetrating wellness-oriented California retail channels through adaptogenic positioning.
- Spicy:Capsicum or ginger heat variants occupy niche premium positioning in experimental artisanal lines from Amsterdam and Berlin producers.
Sweet formulations retain volume leadership; Herbal profiles claim the steepest expansion curve.
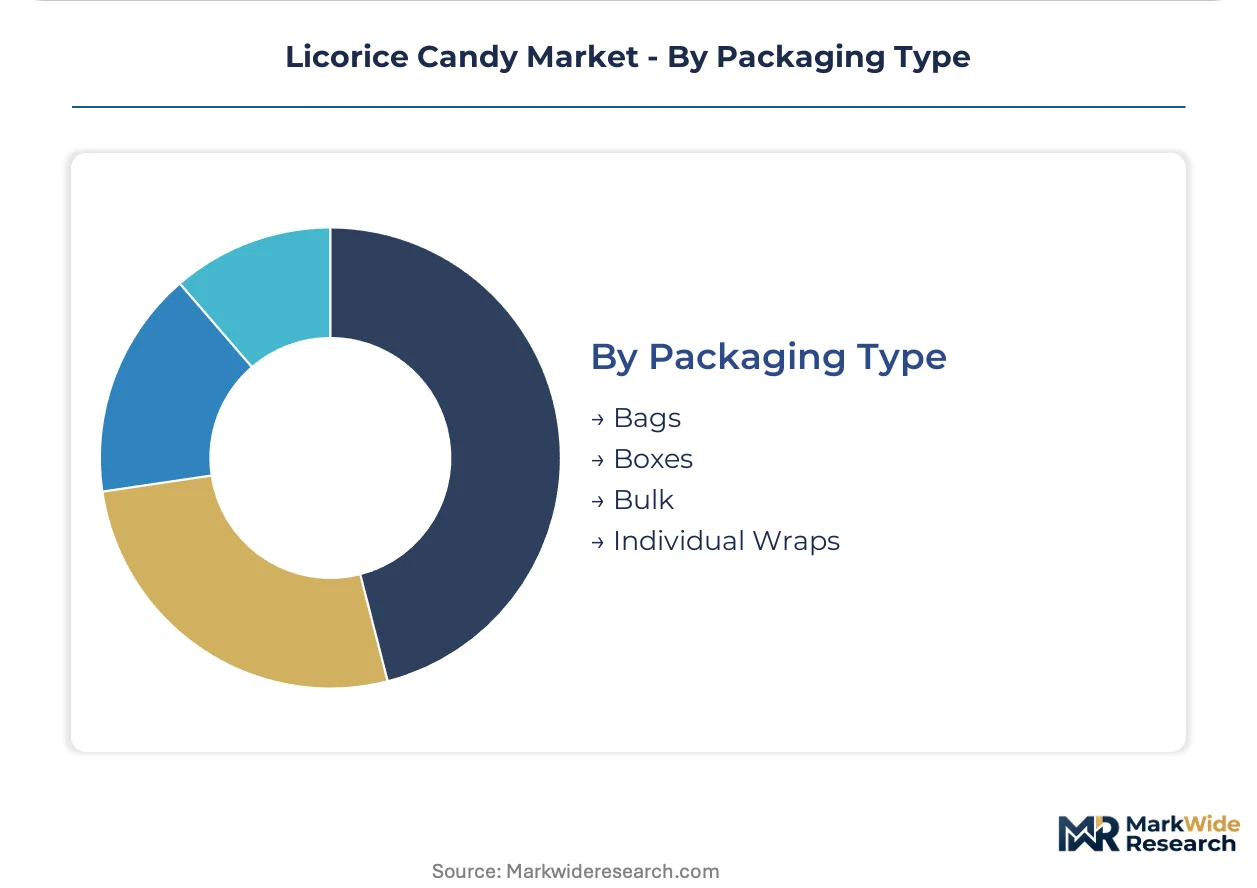
Packaging Type:
Sustainability mandates under EU Farm-to-Fork Strategy are reshaping material selection and format economics across all packaging tiers.
- Bags:Flexible film pouches with reseal features dominate supermarket multiples in Germany and the Netherlands, with mono-material structures qualifying for green procurement tenders.
- Boxes:Rigid cartons support gift positioning and premium provenance labeling in Danish and Swedish specialty retail.
- Bulk:Food-service formats supply artisanal confectionery shops in Amsterdam and Copenhagen with unpackaged product for behind-counter weighing.
- Individual Wraps:Single-piece packaging enables vending machine placement and portion-controlled distribution in German transit hubs.
Bags retain volume leadership; Boxes hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains a substantial licorice trade surplus driven by specialized extrusion capacity serving adjacent European markets. Import dependency for raw Glycyrrhiza glabra extract concentrates in Central Asian supply corridors, exposing processors to transit disruption through Caucasus routing alternatives.
Germany
Per-capita licorice consumption exceeds 2 kilograms annually in northern federal states, sustaining dedicated manufacturing clusters around Solingen and Bergisch Gladbach. EFSA glycyrrhizin intake guidelines force continuous reformulation of traditional black licorice recipes toward deglycyrrhizinated variants. The Rhine-Ruhr industrial corridor hosts precision extrusion equipment suppliers serving confectionery producers across Benelux markets.
Netherlands
Double-salted ammonium chloride variants command premium shelf positioning in Rotterdam and Amsterdam specialty retail channels. REACH chemical registration requirements for extract importers elevate compliance costs for smaller compounders without in-house regulatory affairs capacity. The Randstad urban agglomeration concentrates distribution infrastructure linking North Sea port terminals to German and Belgian wholesale networks.
United States
Red licorice formulations dominate mass-market volume through strawberry and cherry flavor profiles absent glycyrrhizin content. FDA GRAS oversight for licorice extract constrains label claims and glycyrrhizin thresholds in traditional black formulations. California flexitarian demographics drive plant-based pectin binder substitution in Los Angeles and San Francisco Bay Area manufacturing facilities.
Sweden
Subscription-based direct-to-consumer platforms capture recurring revenue through curated quarterly releases targeting 35-55 age cohorts. EU Food Information to Consumers regulations standardize cross-border ingredient transparency for Stockholm and Gothenburg e-commerce operators. The Øresund region integrates Danish and Swedish supply chains through Malmö-Copenhagen cross-border logistics corridors.
Finland
Salmiakki variants constitute a distinct sub-category with dedicated consumer loyalty in Helsinki and Tampere retail channels. National food safety authority oversight aligns with EFSA guidance on glycyrrhizin exposure limits for regular consumers. Turku packaging equipment manufacturers supply mono-material flexible film systems qualifying for EU Farm-to-Fork green procurement tenders.
Licorice Candy Market Competitive Environment
Concentration sits with pan-European confectionery conglomerates holding multi-tier distribution agreements across German-speaking markets. Mid-sized specialists occupy the premium-natural intersection through plant-based and reduced-sugar formulations. Three strategic archetypes dominate: vertically integrated extract processors with captive root supply chains; artisanal producers leveraging micro-encapsulation for botanical flavor layering; and direct-to-consumer platforms bypassing traditional wholesale markups. Competitive moves center on backward integration into licorice root cultivation partnerships and retrofitting extrusion lines for alternative binder matrices.
Within the diversified conglomerate tier, Perfetti Van Melle and Mondelez International occupy positions spanning multiple quality tiers through established pan-European shelf presence. Among specialized German producers, Haribo GmbH & Co. KG and Katjes Fassin GmbH & Co. KG exemplify contrasting formulation strategies—one anchoring traditional black licorice dominance, the other representing plant-based and reduced-sugar premium positioning. These entities illustrate how regulatory compression on glycyrrhizin thresholds is redrawing competitive advantage toward upstream control over extract processing capabilities.
| Leading Market Players |
|---|
| Perfetti Van Melle |
| Trolli |
| The Hershey Company |
| Ferrara Candy Company |
| Cloetta |
| Mondelez International |
| Katjes Fassin GmbH & Co. KG |
| Australian Licorice Company |
| Haribo GmbH & Co. KG |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory buffers for licorice root extract have become standard across German and Dutch processors, compressing working capital flexibility while amplifying price volatility pass-through when Central Asian harvests underperform. This lead-time structure concentrates purchasing power with vertically integrated extract processors who control captive cultivation in Azerbaijan and Uzbekistan, allowing them to extract premium margins during supply disruptions while spot-market buyers absorb cost spikes.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the licorice candy market. Price differentiation rests on glycyrrhizin potency certification and organic root sourcing status, with EFSA-compliant DGL variants commanding substantial premiums over conventional formulations. Pricing pressure stems from natural sweetener cost volatility in Guangxi and Yunnan provinces, which squeezes margin stability for reduced-sugar product lines. Contract manufacturing organizations exhibit highest price sensitivity due to limited reformulation budgets, while direct-to-consumer artisanal brands absorb premiums through subscription loyalty.
Supply Chain Analysis
Strategic stockpile preferences dominate among Northern European processors who maintain six-month extract reserves against Central Asian supply disruption. Geographic supply concentration clusters in Azerbaijan, Uzbekistan, and Turkmenistan, where over seventy percent of global Glycyrrhiza glabra cultivation faces climate-induced harvest volatility. Raw material dependencies center on licorice root extract, pectin binders, and natural sweetener inputs. Single-source vulnerability from Caucasus transit chokepoints elevates risk profiles. Distribution runs through Rotterdam and Hamburg port terminals into specialized confectionery wholesalers across German-speaking markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified analytical chemists capable of glycyrrhizin potency validation and HPLC method development remain scarce across Central and Eastern European contract manufacturing organizations, creating a persistent capability bottleneck that constrains quality-tier expansion.
For Market Incumbents: Consolidate extract processing capabilities through backward integration into licorice root cultivation partnerships in Central Asia, securing captive supply against geopolitical disruption. Defend shelf positioning by retrofitting extrusion lines for DGL and alternative binder matrices before EFSA threshold tightening accelerates compliance costs. Channel control through direct-to-consumer subscription platforms offers margin protection against wholesale distributor compression. For New Entrants and Emerging Players: Differentiate on functional confectionery positioning by penetrating wellness-oriented retail channels in California and New South Wales with adaptogenic formulations incorporating ashwagandha or L-theanine. Target the premium-natural intersection through plant-based pectin binders and reduced-sugar recipes that occupy white space between mass-market Haribo dominance and artisanal micro-producers. A curated quarterly release model via Shopify platforms captures full retail margin while building brand loyalty. For Investors and Strategic Acquirers: Long-term, this sits as a vertical integration play because regulatory compression on glycyrrhizin thresholds is redrawing competitive advantage toward upstream extract processing control. Acquisition targets should prioritize mid-sized specialists with in-house HPLC validation capabilities and established Central Asian root supply relationships. The signal to watch is EFSA guidance evolution on daily intake thresholds, which would accelerate reformulation demand and premium-tier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Root Cultivation | Captive supply from Azerbaijan and Uzbekistan mitigates geopolitical disruption risk for German processors. |
| DGL Reformulation Investment | Deglycyrrhizinated variants command premium shelf positioning under tightening EFSA intake guidelines. |
| Direct-to-Consumer Platform Launch | Subscription models bypass traditional wholesale markups and capture full retail margin in Nordic markets. |
| Plant-Based Binder Transition | Pectin extrusion systems unlock vegan certification access in California flexitarian demographics. |
| Micro-Encapsulation Technology Adoption | Spray-drying systems in Copenhagen and Amsterdam compress innovation cycles for botanical flavor layering. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with licorice extract processors, confectionery R&D directors, specialty retail buyers, and regulatory affairs specialists; and secondary validation through EFSA guidance documents, FDA GRAS filings, REACH registration databases, and customs trade records for Glycyrrhiza glabra imports. Bottom-up triangulation across extract volume flows and top-down reconciliation against confectionery production data ensured cross-verification.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation by product type, flavor profile, end-user channel, and packaging format, with regional regulatory clusters as an overlay dimension. CAGRs were derived from trend extrapolation anchored in historical consumption patterns and policy trajectory assumptions. Industry-specific inputs included glycyrrhizin threshold evolution scenarios and pectin binder substitution elasticity estimates.
The analysis sits within stated boundaries; outcomes outside sustained EFSA regulatory tightening or stable Central Asian supply conditions would require recalibration. Forecasts reflect documented assumptions regarding reformulation cost trajectories and subscription platform adoption rates. Revision becomes warranted when glycyrrhizin guidance thresholds or Caucasus transit stability cross material inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Sugar Confectionery Market
Confectionery
Germany Chocolate Market
Confectionery
Organic Chocolate Confectionery Market
Confectionery
Cocoa and Chocolate Market
Confectionery
Low-Calorie Dark Chocolate Market
Confectionery
China Chocolate Market
Confectionery
Middle East and Africa Chocolate Market
Confectionery
Truffle Chocolate Market
Confectionery
Low Calorie Treats Market
Confectionery
Mooncake Market
Confectionery
Diet Candy Market
Confectionery
Low Calorie Hard Candy Market
Confectionery
Low Calorie Sweets Market
Confectionery
Jellies and Gummies Market
Confectionery
United States and Europe Macarons Market
Confectionery
Vegan Gummy Candy Market