
 Sugar Market | 2026-2036
Sugar Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Market Intelligence
Buyer concentration in the sugar market is broadening as food manufacturers consolidate procurement while specialty ingredient startups fragment demand for organic and fair-trade grades. Südzucker AG leverages its beet sugar infrastructure across Central Europe to sustain volume leadership in industrial supply. Tereos anchors its position through integrated ethanol and sugar operations in Brazil and France. Cosan competes via Raízen's cane crushing scale and bioenergy co-generation in São Paulo state.
Sugar denotes crystalline sucrose extracted from sugarcane or sugar beet through diffusion, purification, evaporation, and centrifugation, yielding white crystals with minimum purity of 99.85 percent for refined grades and serving as a bulk sweetener, preservative, and fermentation substrate across food and industrial applications. Granulated sugar dominates volume flows into beverage manufacturing, where standardization and solubility command premium contract terms. Powdered sugar occupies higher-margin niches in confectionery and bakery finishing, where particle size distribution determines functional performance. Liquid sugar is gaining share in large-scale food processing, as manufacturers eliminate dissolving steps and reduce handling costs.
The USDA and EPA shape US sugar policy through loan rate programs and renewable fuel standards that divert cane and beet supplies toward ethanol production. The EU Green Deal and REACH framework impose sustainability and chemical safety requirements on processing aids and packaging throughout the European supply chain. India's CEA and state-level cane pricing boards set procurement floors that directly determine mill operating economics and export availability. Stakeholders must monitor how biofuel mandates in major producing countries reshape the allocation of cane and beet crops between food and energy markets.
Market Dynamics
Biofuel mandates across major cane-producing nations are redirecting agricultural output from food-grade sugar to ethanol channels, tightening refined sugar availability for beverage and confectionery manufacturers.
Growth Catalysts
- Ethanol Blending Mandates:India's government-directed ethanol programs are absorbing surplus cane crush capacity, creating structural demand pull for industrial sugar derivatives.
- EU F-Gas Regulation:Processing equipment upgrades across member states are improving energy recovery rates in beet sugar refineries, lowering unit production costs.
- Liquid Sugar Conversion:Large-scale food processors are eliminating crystallization stages, reducing handling costs and accelerating batch cycle times in beverage manufacturing.
Market Restraints
- Cane Price Volatility:State-administered floor pricing in Maharashtra and Uttar Pradesh compresses mill margins when international refined sugar prices drop below procurement costs.
- Beet Supply Concentration:Central European growing regions face yield compression from soil moisture variability, concentrating supply risk across Südzucker's core sourcing territories.
- Alternative Sweetener Substitution:Stevia and monk fruit extracts are capturing clean-label beverage formulations, displacing sucrose in premium positioning segments.
Strategic Opportunities
- Specialty Organic Grades:Fair-trade and organic certification premiums are expanding addressable margins in European and North American retail channels.
- Cogeneration Revenue Streams:Bagasse-fired power sales to national grids in São Paulo state diversify revenue beyond commodity sugar.
- Carbon Border Adjustments:EU CBAM implementation is creating compliance-based differentiation for low-carbon intensity beet sugar against imported cane competitors.
Industry Challenges
- Harvest Mechanization Skills:Brazilian mills face operator shortages for automated cane cutter fleets, delaying crushing season starts.
- REACH Compliance Timelines:European processors must complete chemical safety dossiers for processing aids under compressed registration deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Market |
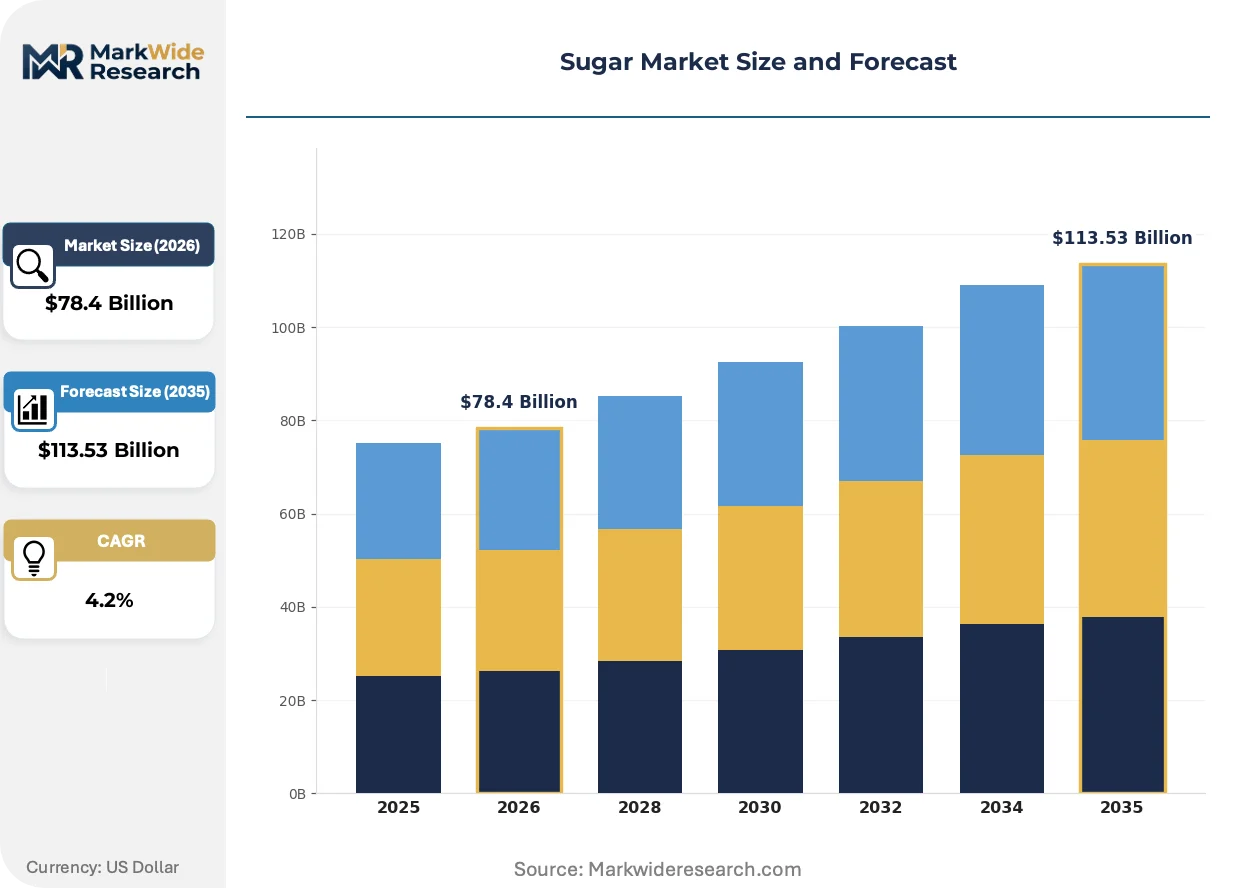
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $113.53 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated Sugar, Brown Sugar, Powdered Sugar, Liquid Sugar Application: Beverages, Bakery Products, Confectionery, Sauces End User: Food Manufacturers, Retail Consumers, Restaurants, Catering Services Distribution Channel: Wholesale, Direct Sales, E-commerce, Retail |
| Companies Covered | Südzucker AG, Tereos, Cosan, Mitr Phol Group, Associated British Foods, Nordzucker AG, Wilmar International, Raízen, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Market Strategic Shifts & Innovations
Digital process control and sustainability certification are converging to reshape how sugar moves from field to formulation, with automation and traceability becoming baseline procurement requirements.
Diffusion-optimized extraction systems are automating juice recovery rates in Brazilian cane mills, pushing pol extraction above 98 percent while reducing water and energy inputs per ton of cane crushed. Major processors in São Paulo state are retrofitting existing trains with real-time brix monitoring and automated temperature modulation. The technology is automating labor-intensive process stages that previously required constant manual adjustment.
REACH framework amendments are tightening chemical safety documentation for processing aids used in European beet sugar refineries, forcing reformulation of clarification and decolorization chemistries. Manufacturers are shifting toward enzymatic and membrane-based alternatives to synthetic flocculants. Organic and specialty grade producers in France and Germany face accelerated compliance timelines compared to standard industrial suppliers.
Direct mill-to-beverage-plant liquid sugar contracts are displacing traditional bagged refined sugar procurement in North American and European large-scale manufacturing. Coca-Cola and PepsiCo bottling networks are installing dedicated liquid receiving infrastructure at concentrate plants. This channel compression is most visible in southeastern US states where cane refiners operate adjacent to beverage manufacturing clusters.
Sugar Market Segmentation
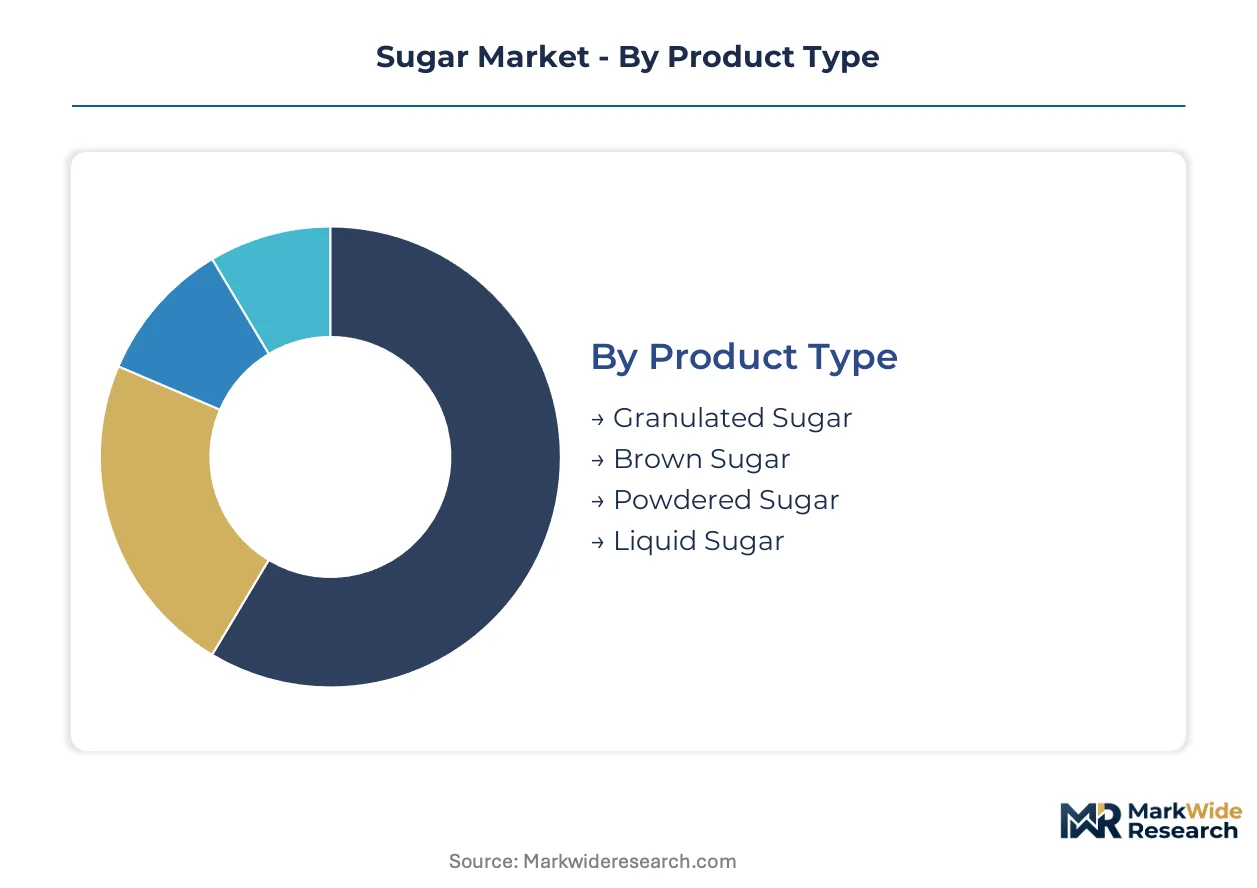
Sugar procurement patterns diverge sharply between industrial buyers seeking bulk standardization and specialty channels chasing certification premiums. Understanding these segment boundaries clarifies where margin pools concentrate and which specifications command pricing power.
Product Type:
Buyers select crystalline form based on dissolution speed requirements and downstream handling economics.
- Granulated Sugar:Standard refined crystals with 99.85% minimum sucrose purity serve as the baseline sweetener for high-volume beverage manufacturing. Demand concentrates in Coca-Cola and PepsiCo bottling networks across the southeastern US, where direct mill-to-plant liquid conversion is displacing bagged procurement.
- Liquid Sugar:Inverted sucrose solutions eliminate crystallization stages and reduce batch cycle times for large-scale food processors. Growth tilts toward North American and European beverage manufacturing clusters installing dedicated receiving infrastructure.
- Powdered Sugar:Finely milled crystals with added cornstarch flow freely for confectionery finishing and bakery decoration.
- Brown Sugar:Molasses-coated crystals retain moisture and caramel notes for premium cookie and sauce formulations.
Volume sits with granulated grades; growth tilts toward liquid sugar conversion.
Application:
Functional requirements vary by thermal processing intensity and shelf stability demands.
- Beverages:Carbonated and still drink formulations require rapid solubility and consistent brix levels for flavor standardization. Demand concentrates in Brazil, where cane-based ethanol programs are redirecting food-grade supplies and tightening refined sugar availability for bottlers.
- Confectionery:Hard candies and fondants demand precise thermal behavior and crystallization control. European manufacturers face REACH compliance timelines forcing reformulation of processing aids toward enzymatic clarification.
- Bakery Products:Yeast fermentation and Maillard browning depend on reducing sugar content and moisture retention.
- Sauces:Viscosity modification and preservative function drive sucrose inclusion in tomato and condiment processing.
Volume concentrates in beverages; confectionery claims the steepest margin expansion trajectory.
End User:
Procurement scale and specification tolerance separate industrial buyers from fragmented retail channels.
- Food Manufacturers:Integrated processors contract directly with mills for liquid sugar delivery at tanker scale. Demand concentrates in São Paulo state, where Raízen's cane crushing operations supply adjacent beverage and dairy plants.
- Retail Consumers:Supermarket and specialty store purchasers seek organic and fair-trade certification premiums in European and North American markets.
- Restaurants:Foodservice operators balance cost control with menu consistency across multiple locations.
- Catering Services:Event-based volume spikes require flexible procurement without long-term contract commitments.
Volume flows through food manufacturers; retail organic grades expand most quickly.
Distribution Channel:
Logistics infrastructure and buyer scale determine channel selection and working capital requirements.
- Direct Sales:Mill-to-processor contracts bypass intermediaries for liquid sugar and bulk granulated shipments. Südzucker AG leverages Central European beet infrastructure to sustain direct supply relationships with industrial bakery and confectionery accounts.
- Wholesale:Regional distributors aggregate smaller food manufacturer orders and manage inventory for mid-scale processors.
- E-commerce:Specialty organic and fair-trade grades reach direct-to-consumer channels in premium positioning segments.
- Retail:Supermarket and hypermarket chains stock standardized granulated and brown sugar for household consumption.
Volume moves through direct sales; e-commerce gains share fastest in specialty certification segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's cane fields anchor Brazilian sugar production, while European beet cultivation clusters around Central European plains. Indian crushing capacity concentrates in Maharashtra and Uttar Pradesh, where state pricing boards govern mill economics.
Brazil
Raízen's cane crushing operations in São Paulo state supply adjacent beverage and dairy plants with direct liquid sugar contracts. ANVISA, Brazil's national health regulator, oversees food-grade processing standards for export-bound refined sugar. The São Paulo industrial corridor hosts co-generation facilities selling bagasse-fired power to the national grid, diversifying mill revenue beyond commodity sugar.
India
Maharashtra and Uttar Pradesh mills face margin compression when international refined sugar prices drop below state-administered cane procurement floors. The CEA directs ethanol blending programs that redirect surplus cane crush capacity toward industrial derivatives. Crushing operations in western Maharashtra supply both food-grade refineries and distillery channels under government-mandated blending quotas.
Germany
Südzucker AG leverages beet sugar infrastructure across Central European plains to sustain direct supply relationships with industrial bakery and confectionery accounts. REACH framework amendments force reformulation of clarification and decolorization chemistries toward enzymatic alternatives. Processing clusters in Lower Saxony and Bavaria face compressed compliance timelines for chemical safety dossiers on processing aids.
United States
Southeastern states host cane refiners operating adjacent to Coca-Cola and PepsiCo bottling networks, enabling direct mill-to-plant liquid sugar conversion. The USDA and EPA shape sugar policy through loan rate programs and renewable fuel standards diverting supplies toward ethanol production. Florida and Louisiana crushing facilities supply beverage manufacturing clusters with tanker-scale liquid delivery contracts.
Thailand
Mitr Phol Group anchors cane processing in the central plains region, supplying export markets across Asia-Pacific. The country's Board of Investment incentivizes ethanol capacity expansion that competes with food-grade sugar for cane allocation. Crushing operations in Suphan Buri and Kanchanaburi provinces face growing diversion pressure from government-backed biofuel mandates.
Sugar Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialty certification and organic grade positioning. The market structure consolidates around integrated beet and cane processors with captive agricultural supply, while mid-scale operators fragment across regional distribution channels. Three archetypes dominate: vertically integrated agricultural-industrial conglomerates controlling crushing through retail; cooperative-backed European beet processors; and Asian trading houses leveraging origination scale. Competitive moves concentrate on backward integration into cane and beet farming, plus geographic expansion into ethanol-adjacent processing.
Among European cooperative-backed processors, Südzucker AG and Nordzucker AG exemplify the beet-specialist archetype with centralized European sourcing infrastructure. Tereos occupies a position spanning both cane and beet processing across Brazilian and French territories. Asian-originated trading and processing operations include Wilmar International, representing the origination-scale model with integrated supply chain presence across multiple producing regions. These three anchors illustrate how geographic diversification and feedstock flexibility differentiate competitive positioning.
| Leading Market Players |
|---|
| Südzucker AG |
| Tereos |
| Cosan |
| Mitr Phol Group |
| Associated British Foods |
| Nordzucker AG |
| Wilmar International |
| Raízen |
| Cargill |
| Others |
Cost & Logistics Intelligence
Beverage bottler procurement consolidation in southeastern US states anchors contract pricing to liquid sugar tanker-scale offtake terms, compressing margins for bagged refined sugar distributors while rewarding integrated cane refiners with dedicated pipeline infrastructure.
Pricing Analysis
Volume concentrates in standard granulated grades traded on commodity spot and annual contract terms, while margin pools accrue to specialty organic and fair-trade certified segments. Price differentiation hinges on certification tier and volume scale, with FSSAI and EU organic standards commanding premiums. Pricing pressure stems from ethanol blending mandates in India and Brazil redirecting cane supplies toward industrial channels. Food manufacturers exhibit highest price sensitivity due to standardized input specifications, whereas retail organic buyers accept premium positioning.
Supply Chain Analysis
EU F-Gas Regulation and farm-to-fork sustainability mandates are reshaping sourcing requirements across member states, forcing clarification chemistry reformulation toward enzymatic alternatives. Supply concentrates in Brazil, India, and Thailand for cane-based output, with Germany and France anchoring beet sugar production. Raw material flows draw from sugarcane crush capacity, beet harvest yields, and molasses availability for brown sugar grades. Single-source vulnerability runs through Maharashtra and Uttar Pradesh state-administered cane pricing boards. Distribution runs through direct mill-to-processor contracts for liquid sugar, with wholesale channels aggregating smaller food manufacturer orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with players pursuing backward control over cane and beet farming to secure crush capacity and co-generation feedstock.
For Market Incumbents: Anchor crushing capacity utilization through long-term cane supply agreements in São Paulo state and Central European beet territories. Defend against specialty organic entrants by accelerating fair-trade certification across existing refining infrastructure. Prioritize bagasse-fired co-generation revenue streams to diversify beyond commodity sugar margins. For New Entrants and Emerging Players: The premium-to-economy price-point gap in European retail organic segments offers white-space entry. Target North American specialty foodservice channels where clean-label positioning displaces standard refined grades. Pursue direct-to-bakery liquid sugar contracts as an alternative to beverage bottler concentration. For Investors and Strategic Acquirers: The window for entry favors cooperative-backed European beet processors with captive agricultural supply and carbon intensity advantages under EU CBAM. Long-term viability rests on ethanol-adjacent processing flexibility and low-carbon certification pipelines. Watch Indian state-level cane pricing board announcements as inflection indicators for export availability compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cane Farming | Raízen and Cosan secure crush capacity and bagasse supply for São Paulo co-generation facilities. |
| Organic Certification Program | Südzucker and Nordzucker capture retail premium margins under EU Green Deal sustainability mandates. |
| Liquid Sugar Infrastructure Investment | Coca-Cola and PepsiCo bottling networks eliminate crystallization stages and reduce handling costs. |
| Ethanol Capacity Expansion | Tereos and Mitr Phol diversify revenue streams under government-directed blending programs in Brazil and Thailand. |
| Enzymatic Clarification Transition | European beet refiners reformulate processing aids to meet REACH framework chemical safety deadlines. |
Research Approach
Independent corroboration across mill operations executives, beverage procurement directors, and agricultural commodity traders underwrites the qualitative findings. Secondary validation draws from USDA loan rate program disclosures, EU ECHA chemical safety registrations, and Indian CEA ethanol blending directives. Bottom-up volume estimates from crushing capacity and harvest yield data triangulate against top-down demand aggregation from food manufacturer procurement patterns.
Rate-of-change decomposition separates volume growth from price trajectory across the projection horizon. Segmentation modeling incorporates product type crystalline form, application functional requirements, end-user procurement scale, and regional regulatory framework clusters. CAGRs derive from trend extrapolation of crush capacity utilization, ethanol diversion rates, and certification premium persistence. Forecast inputs include state-administered cane floor pricing announcements and EU CBAM carbon intensity benchmarking.
Inputs from ANVISA processing standards filings and FSSAI organic certification registries were available through the study window; gaps in real-time crush capacity utilization data from private Brazilian mills introduce uncertainty bands. Forecasts reflect documented assumptions on ethanol mandate enforcement timelines and REACH compliance completion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Saccharin Market
Sweeteners
Australia Food Sweetener Market
Sweeteners
Europe Low-Calorie Sweeteners Market
Sweeteners
Germany Food Sweetener Market
Sweeteners
Global Plant-Derived and Synthetic Sugar Market
Sweeteners
Gluten-Free Sugar Syrup Market
Sweeteners
Asia-Pacific Cane Sugar Market
Sweeteners
Agave Nectar Market
Sweeteners
Saudi Arabia Allulose Market
Sweeteners
Raw Beetroot Sugar Market
Sweeteners
Corn Syrup Market
Sweeteners
Crystalline Fructose Market
Sweeteners
Nutritive Sweeteners Market
Sweeteners
Brazil Food Sweetener Market
Sweeteners
Digestion Resistant Maltodextrin Market
Sweeteners
Sorbitol Market