
 Chocolate Inclusions and Decorations Market | 2026-2036
Chocolate Inclusions and Decorations Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Inclusions and Decorations Market Outlook
Specialty ingredient distribution through artisan bakery supply channels is narrowing as consolidated distributors prioritize volume commitments from scaled manufacturers. Barry Callebaut leverages its integrated cocoa processing network to secure preferential shelf space in European food service channels. Cargill Cocoa & Chocolate competes through direct-to-manufacturer contracts that bypass traditional wholesale tiers entirely. Dawn Foods anchors North American availability with regional production hubs calibrated to just-in-time bakery schedules.
Chocolate inclusions and decorations comprise formulated chocolate pieces—typically 30-70% cocoa solids—manufactured through controlled tempering, extrusion, or enrobing processes for textural and visual integration into finished foods. These components serve primarily as flavor carriers, moisture barriers, and aesthetic differentiators across industrial and artisan production environments. Chunks and chips dominate volume within the product type dimension, though shavings command premium positioning in plated dessert and patisserie applications. The application split favors baked goods and confectionery as mature demand centers, while ice cream and dairy represent faster-growth outlets where freeze-thaw stability requirements filter supplier eligibility.
EFSA novel food evaluations and FDA GRAS determinations govern ingredient approval timelines for new inclusion formats entering commercial channels. REACH compliance for processing aids and EU deforestation regulation traceability mandates add compliance layers to cocoa sourcing strategies. Stakeholders must monitor evolving EUDR implementation thresholds and emerging state-level packaging waste rules in California and New York that could reshape primary packaging specifications for bulk decoration shipments.
Market Dynamics
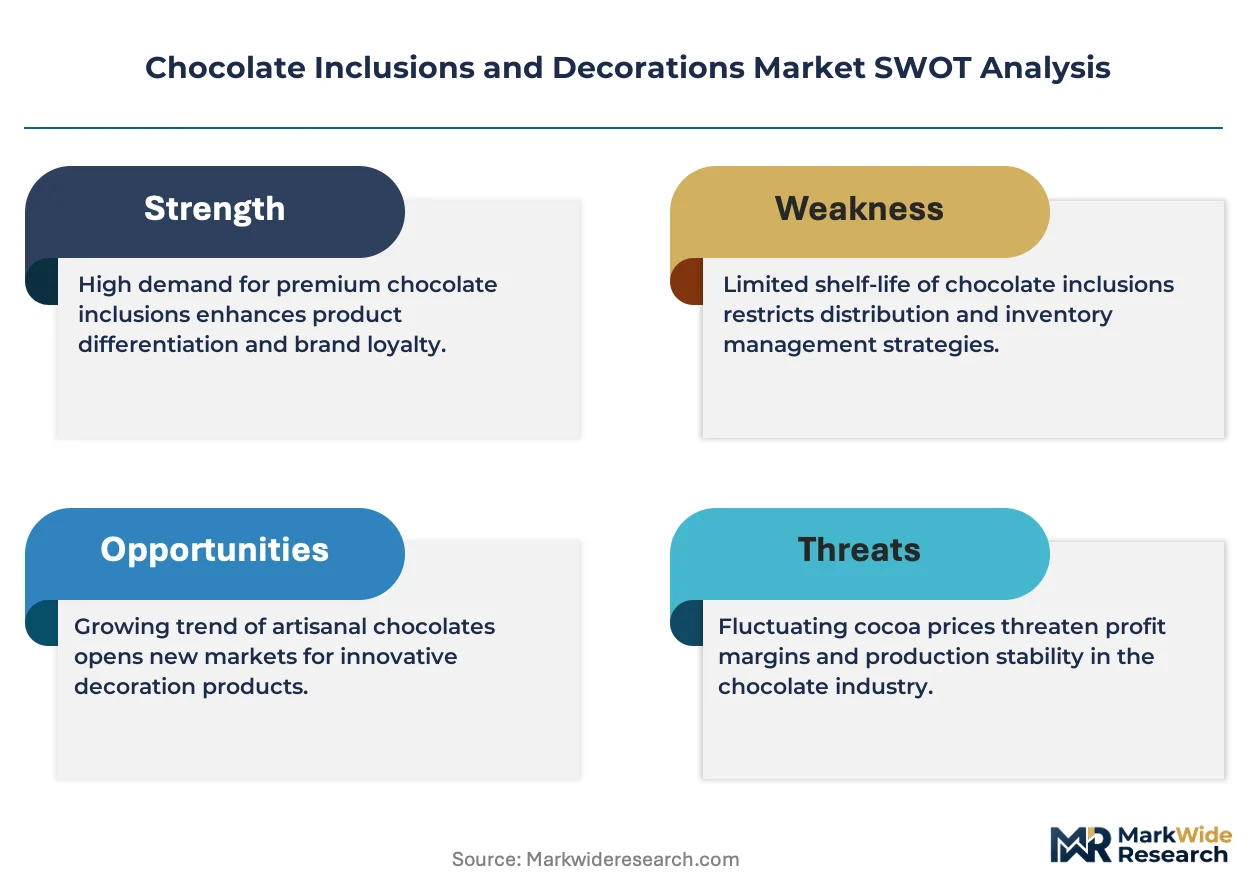
Consolidated distributor networks are squeezing specialty ingredient access for artisan-scale buyers, while EUDR traceability mandates force cocoa sourcing restructuring across European supply chains.
Growth Catalysts
- Clean-label mandates:EFSA novel food evaluations and FDA added-sugar labeling requirements are accelerating reformulation toward minimal-ingredient chocolate inclusions in premium confectionery and bakery segments.
- Freeze-thaw stability demand:Ice cream and dairy applications are filtering supplier eligibility toward technical specialists capable of delivering functional performance across temperature cycling.
- Heritage processing clusters:Germany, Switzerland, and Belgium anchor concentrated cocoa expertise that channels investment toward specialty decoration capacity expansion.
Market Restraints
- Cocoa price volatility:Input cost swings in raw cocoa beans compress margin predictability for formulated chocolate piece manufacturers serving price-locked food service contracts.
- Supply concentration risk:European regulatory compliance capacity concentrates among integrated processors with in-house sustainability verification, excluding smaller compounders from EUDR-eligible sourcing pools.
- Technical limitation:Moisture barrier performance in high-humidity bakery applications remains uneven across non-tempered inclusion formats, restricting deployment in certain industrial bread lines.
Strategic Opportunities
- Underpenetrated patisserie channels:Plated dessert and fine dining segments in France and Italy show capacity for premium shaving and curl formats currently underserved by bulk-focused distributors.
- Regulatory tailwind:EU deforestation regulation implementation creates first-mover advantage for suppliers with established geolocation traceability systems in cocoa origin countries.
- Channel innovation:Direct-to-manufacturer contracting models are bypassing traditional wholesale tiers entirely, enabling technical collaboration on custom inclusion development.
Industry Challenges
- Tempering skill scarcity:Artisan-scale production environments face recruitment gaps for technicians capable of maintaining crystallization control across variable batch sizes.
- Capex intensity:EUDR-compliant traceability infrastructure requires substantial investment in farm-level geolocation systems and chain-of-custody documentation platforms.
- Certification timeline compression:REACH compliance for new processing aids and GRAS determinations for novel inclusion formats extend product development cycles beyond seasonal launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Inclusions and Decorations Market |
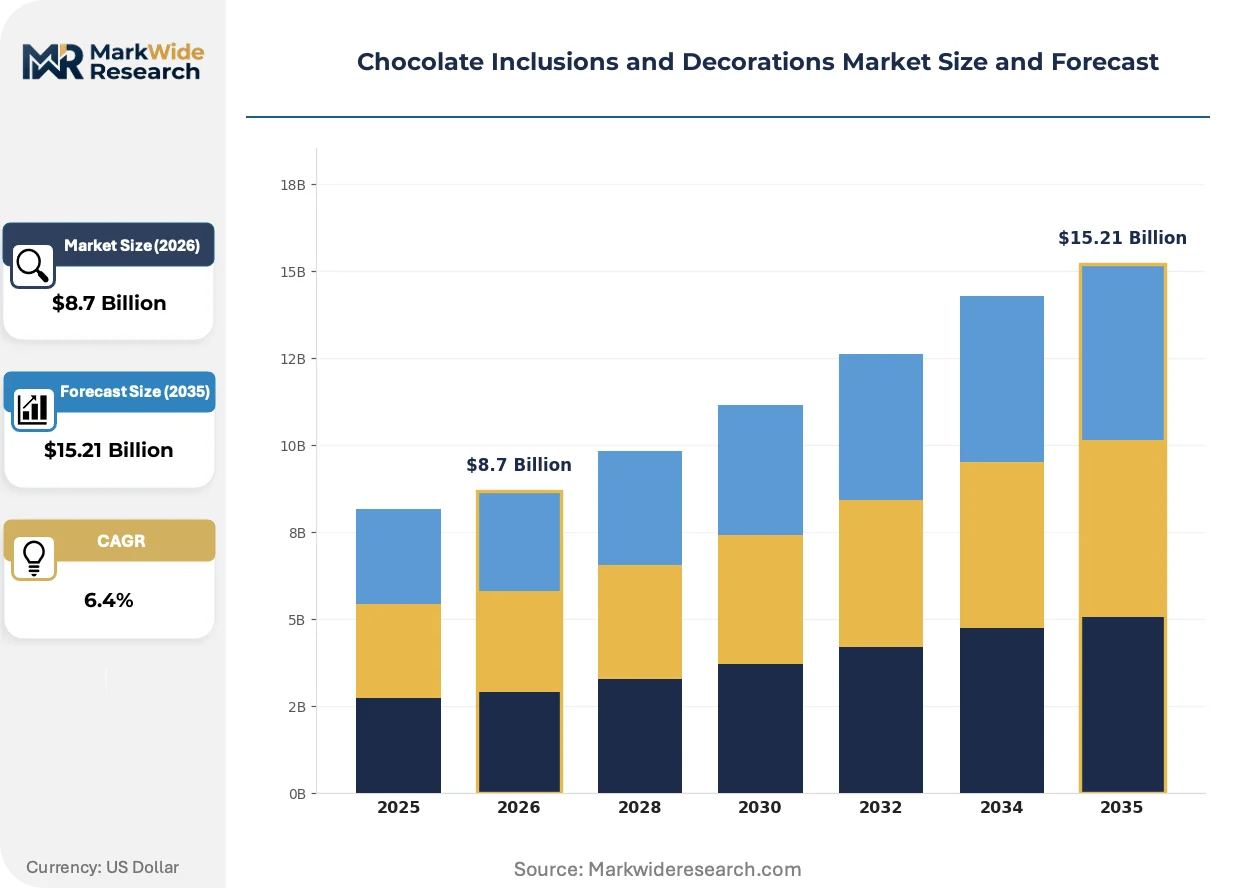
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chunks, Chips, Sprinkles, Shavings Form: Solid, Liquid, Powder, Coating Application: Baked Goods, Confectionery, Ice Cream, Dairy Customer Type: Retailers, Manufacturers, Food Service, Wholesalers |
| Companies Covered | Barry Callebaut, Cargill Cocoa & Chocolate, Dawn Foods, Chocolate Smet Canada Inc., Kanegrade Limited, Nimbus Foods, Carroll Industries NZ Ltd, ifiGOURMET, Orchard Valley Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Inclusions and Decorations Market Strategic Shifts
Precision tempering automation and blockchain-verified sourcing are compressing technical differentiation timelines while reshaping procurement criteria for industrial buyers.
Continuous tempering systems with real-time beta-crystal detection are rendering obsolete batch-wise manual tempering in mid-scale confectionery operations. Artisan producers adopting these systems reduce skilled labor dependency while achieving consistency previously reserved for industrial compounders. The technology is rendering obsolete traditional apprenticeship-based quality control in facilities below 500-ton annual throughput.
EU deforestation regulation traceability mandates are forcing geolocation documentation from farm to first processing point across all cocoa-derived ingredients entering European channels. Integrated processors with captive origin operations capture compliance advantage while non-integrated compounders face supplier requalification costs. Swiss and Belgian heritage processors with established West African sourcing infrastructure are consolidating position as preferred partners for EUDR-affected buyers.
Direct technical collaboration between inclusion manufacturers and finished goods R&D teams is displacing specification-based purchasing in premium bakery and ice cream segments. Category managers in Germany and the Netherlands are embedding supplier personnel within product development cycles to co-design texture and melt profiles. This pattern concentrates volume with technically capable suppliers while marginalizing distributors lacking formulation support capacity.
Chocolate Inclusions and Decorations Market Segmentation
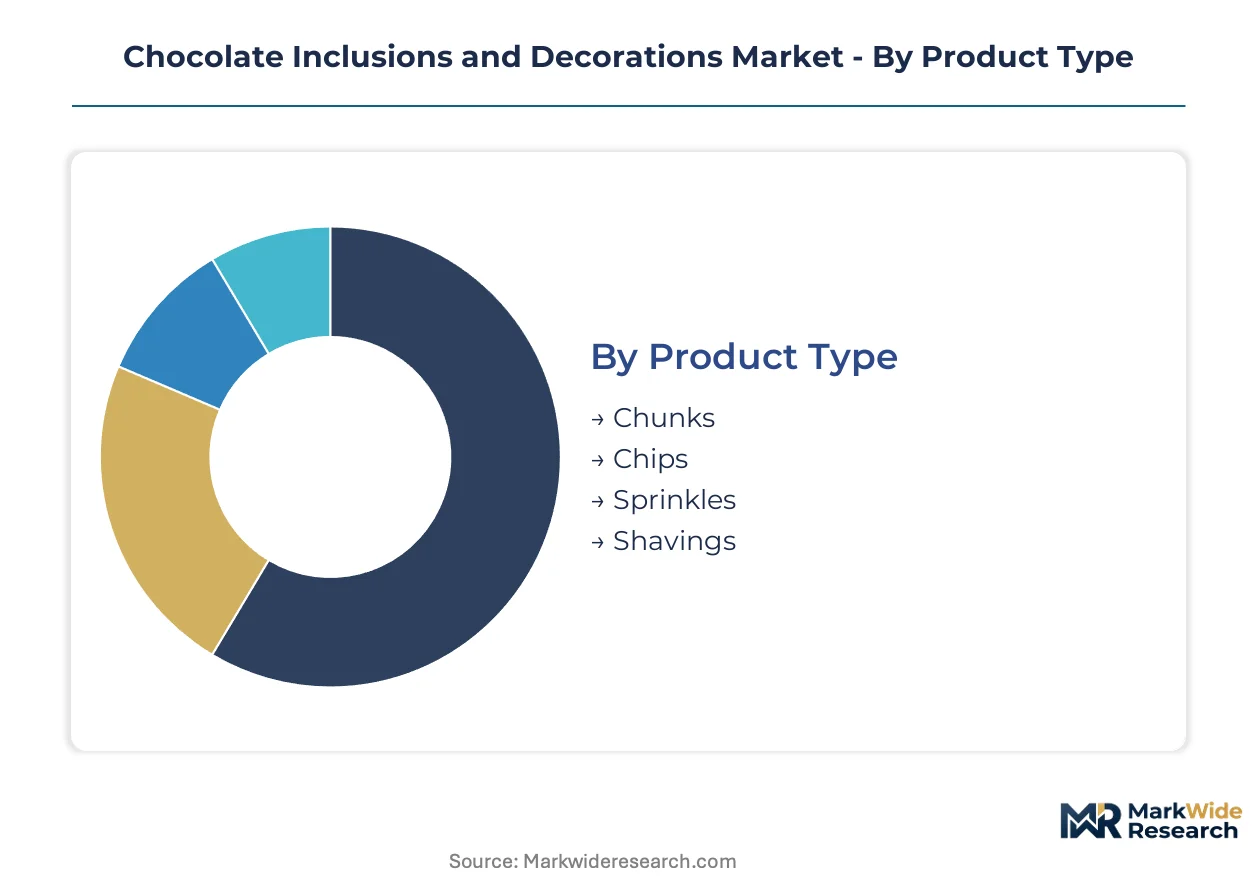
Segmentation in the chocolate inclusions and decorations market reveals how technical specifications, application requirements, and procurement channels create distinct competitive arenas. Each dimension carries unique margin profiles and regulatory exposure that shape supplier strategy.
Product Type:
Industrial bakers demand robust structural integrity under mechanical mixing, while patisserie chefs prioritize visual finesse and controlled melt behavior.
- Chunks:Large-format pieces ranging 10-20mm with dense cocoa mass content deliver pronounced textural contrast in cookies and brownies. German industrial bakeries anchor volume demand here, driven by freeze-thaw stability requirements in frozen dough applications.
- Chips:Standardized 6-9mm drops with controlled fat bloom resistance dominate automated depositing lines across North American cookie manufacturing. The segment concentrates procurement through direct manufacturer contracts that bypass distributor markups.
- Sprinkles:Micro-format decorative elements engineered for color retention and humidity resistance serve premium cake decoration and seasonal confectionery.
- Shavings:Thin-curl formats produced through precision blade cutting command premium positioning in plated dessert applications across French and Italian fine dining channels.
The dominant share belongs to chips, while shavings is closing the gap fastest.
Form:
Processing temperature and equipment compatibility determine form selection, with liquid and coating formats requiring specialized handling infrastructure that filters supplier eligibility.
- Solid:Tempered or compound chocolate pieces in discrete formats enable direct mechanical integration across ambient-temperature production lines. Swiss heritage processors maintain technical leadership through crystallization control expertise.
- Liquid:Pumpable chocolate masses held at controlled viscosity serve enrobing and injection applications in industrial confectionery. The form demands continuous tempering systems that concentrate adoption among scaled manufacturers.
- Powder:Spray-dried or milled cocoa preparations provide dry-blend compatibility for bakery premixes and beverage applications.
- Coating:Compound fat systems with snap-setting properties enable high-speed panning and ice cream bar dipping without tempering requirements.
Solid formats command the volume base, though coating is expanding most quickly in ice cream and frozen dessert channels.
Application:
End-use specifications diverge sharply on moisture exposure, thermal cycling tolerance, and visual presentation standards.
- Baked Goods:Inclusion formats must survive oven temperatures exceeding 180°C while maintaining shape definition and preventing fat bleed into surrounding matrix. Belgian suppliers specialize in high-heat-stable compound pieces for industrial bread and cookie lines.
- Confectionery:Tempered chocolate decorations require precise crystallization control for gloss and snap, with EFSA novel food evaluations governing new ingredient introductions. The application anchors premium pricing through technical complexity barriers.
- Ice Cream:Freeze-thaw stability and resistance to ice crystal damage filter supplier pools toward technical specialists with lipid modification capabilities.
- Dairy:Chocolate inclusions in yogurt and dairy desserts face pH stability challenges and regulatory scrutiny on added sugar declarations under evolving FDA labeling requirements.
Baked goods holds the installed demand base, with ice cream generating the steepest expansion trajectory through premium product proliferation.
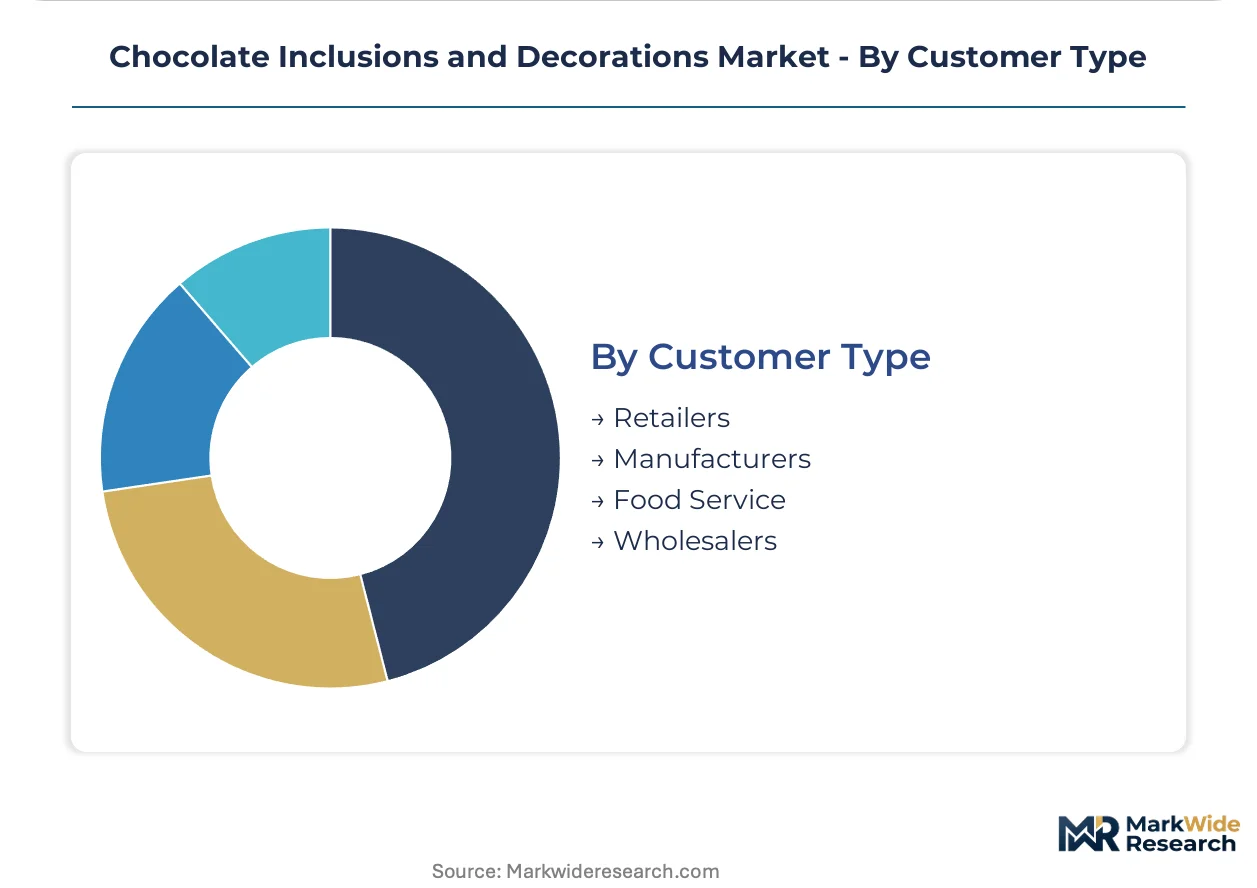
Customer Type:
Procurement scale and technical support requirements stratify the customer base across divergent channel economics.
- Retailers:Private-label and branded finished goods producers source inclusions through consolidated distributors with just-in-time logistics capabilities. Dawn Foods anchors North American availability through regional production hubs calibrated to bakery schedules.
- Manufacturers:Direct technical collaboration on custom inclusion development displaces specification-based purchasing among premium bakery and ice cream producers in Germany and the Netherlands.
- Food Service:Artisan bakeries and restaurant chains demand smaller batch flexibility with formulation support, a segment narrowing as distributors prioritize volume commitments from scaled accounts.
- Wholesalers:Traditional tier-one distribution faces margin compression from manufacturer-direct contracting models and integrated processor captive sourcing networks.
Manufacturers capture the dominant procurement volume, while food service is gaining share fastest through premium channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium decoration formats command 40-60% price premiums in Switzerland and Belgium versus commodity chip pricing in North American industrial channels. This asymmetry reflects heritage processing expertise concentration and divergent regulatory compliance costs across Atlantic supply chains.
United States
FDA added-sugar labeling mandates are accelerating reformulation toward minimal-ingredient inclusions in premium bakery and ice cream segments. The agency's GRAS determination timelines for novel chocolate formats extend product development cycles beyond seasonal launch windows. Chicago and Minneapolis anchor North American production clusters where Dawn Foods operates regional hubs calibrated to just-in-time bakery schedules.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia anchor European volume demand for freeze-thaw-stable chunks in frozen dough applications. EFSA novel food evaluations govern ingredient approval timelines for new inclusion formats entering commercial channels. Cologne and Hamburg concentrate distribution infrastructure where consolidated networks are squeezing specialty ingredient access for artisan-scale buyers.
Switzerland
Heritage chocolate processing clusters in Zurich and Vevey channel investment toward specialty decoration capacity expansion for patisserie and fine dining channels. Swissmedic and federal food safety frameworks maintain stringent purity standards that reinforce premium positioning. Barry Callebaut leverages integrated cocoa processing networks to secure preferential shelf space in European food service channels from this base.
Belgium
High-heat-stable compound pieces for industrial bread and cookie lines originate from Antwerp and Brussels processing corridors. EU deforestation regulation traceability mandates force geolocation documentation from farm to first processing point across all cocoa-derived ingredients. Belgian suppliers specialize in moisture barrier performance for high-humidity bakery applications where non-tempered formats face deployment restrictions.
France
Plated dessert and fine dining segments in Paris and Lyon show capacity for premium shaving and curl formats currently underserved by bulk-focused distributors. ANSM and national food safety frameworks align with EFSA standards while maintaining additional artisan production facility inspections. French patisserie channels remain underpenetrated relative to technical capability, creating first-mover opportunities for suppliers with established geolocation traceability systems.
Chocolate Inclusions and Decorations Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower technical scope. The market exhibits tiered concentration where integrated cocoa processors with captive origin operations capture compliance advantage under EUDR mandates. Three archetypes dominate: heritage European processors with sustainability verification infrastructure, North American distributors with regional just-in-time logistics, and technical specialists serving freeze-thaw stability requirements. Capacity expansion and direct-to-manufacturer contracting represent the dominant competitive moves, displacing traditional wholesale tiers.
Within the integrated processor tier, Barry Callebaut and Cargill Cocoa & Chocolate exemplify platform-scale players with upstream cocoa control. Dawn Foods anchors North American availability through regional production infrastructure. These three occupy positions spanning the value chain from origin sourcing through finished inclusion manufacturing, representing archetypes of compliance-ready European heritage processing, agricultural commodity integration, and continent-scaled distribution logistics respectively.
| Leading Market Players |
|---|
| Barry Callebaut |
| Cargill Cocoa & Chocolate |
| Dawn Foods |
| Chocolate Smet Canada Inc. |
| Kanegrade Limited |
| Nimbus Foods |
| Carroll Industries NZ Ltd |
| ifiGOURMET |
| Orchard Valley Foods |
| Others |
Value Chain & Pricing Dynamics
West African cocoa origin concentration channels margin capture toward integrated processors with captive farm networks, while European EUDR compliance costs filter supplier pools and reshape downstream pricing power. Heritage processors in Switzerland and Belgium extract premium positioning through sustainability verification infrastructure that compounders lacking origin control cannot replicate.
Pricing Analysis
Configured-to-order pricing for custom inclusion development commands substantial premiums over standard chip and chunk formats, with three-tier pricing structure across premium, standard, and economy levels anchoring procurement negotiations. Price differentiation hinges on certification grade and volume scale, with artisan bakery buyers showing highest sensitivity to per-kilogram differentials while industrial manufacturers absorb premiums for freeze-thaw stability guarantees. Pricing pressure stems from cocoa bean cost volatility compressing margins on long-term food service contracts. Industrial bakers in North America exhibit greatest price elasticity, whereas patisserie channels in France and Italy tolerate premium positioning for visual-grade shavings.
Supply Chain Analysis
Tariff exposure between West African origin countries and European processing hubs dominates supply chain risk calculations for cocoa-derived inclusions. Geographic supply concentration centers on Côte d'Ivoire, Ghana, and Indonesia for raw bean sourcing, while Germany, Switzerland, and Belgium anchor formulated chocolate piece manufacturing. Raw material dependencies draw from cocoa butter, cocoa liquor, and compound fat systems with snap-setting properties. Single-source vulnerability intensifies around geolocation traceability systems required for EUDR compliance. Distribution runs through consolidated distributor networks in North America and direct-to-manufacturer contracting channels accelerating across European premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among scaled manufacturers and consolidated distributors, squeezing margin capture for mid-tier suppliers lacking technical differentiation or captive origin infrastructure.
For Market Incumbents: Harden EUDR-compliant traceability systems through farm-level geolocation investments in Côte d'Ivoire and Ghana, securing preferential access to European channels as regulatory thresholds tighten. Deepen technical collaboration capabilities with R&D teams at premium ice cream and bakery manufacturers to displace specification-based purchasing. Capacity expansion in Swiss and Belgian heritage clusters reinforces positioning against emerging compounders lacking sustainability verification infrastructure. For New Entrants and Emerging Players: Pursue underpenetrated patisserie channels in France and Italy where premium shaving and curl formats face supply gaps from bulk-focused incumbents. Target direct-to-manufacturer contracting models in German and Dutch premium bakery segments, embedding formulation support personnel within customer product development cycles. Position around freeze-thaw stability specialization for ice cream applications, where technical barriers filter incumbent eligibility. For Investors and Strategic Acquirers: Capital is best deployed toward integrated processors with established West African sourcing infrastructure and in-house sustainability verification, capturing compliance advantage as EUDR implementation thresholds harden. Long-term viability across the analysis window favors suppliers with backward integration into origin operations over non-integrated compounders facing supplier requalification costs. The signal to watch is consolidation velocity among distributors prioritizing volume commitments from scaled accounts.| Strategic Initiative | Industry Significance |
|---|---|
| EUDR Traceability Infrastructure Investment | Farm-level geolocation systems in Côte d'Ivoire secure European market access against regulatory exclusion. |
| Direct-to-Manufacturer Contracting Expansion | Technical collaboration with German bakery R&D teams displaces distributor-mediated procurement patterns. |
| Freeze-Thaw Stability Capacity Addition | Lipid modification capabilities filter supplier pools toward technical specialists in ice cream applications. |
| Heritage Processing Cluster Consolidation | Swiss and Belgian origin infrastructure reinforces premium positioning through crystallization control expertise. |
| Continuous Tempering Automation Deployment | Real-time beta-crystal detection reduces skilled labor dependency in mid-scale confectionery operations. |
Study Parameters
Initial hypotheses were tested against primary input from chocolate inclusion product managers, artisan bakery procurement leads, ice cream R&D directors, and cocoa sustainability officers and refined through secondary validation against EFSA novel food evaluation databases, FDA GRAS determination filings, EU deforestation regulation implementation documents, and customs trade data for cocoa-derived ingredients. Bottom-up volume modeling across product type, form, application, and customer type dimensions was triangulated with top-down market sizing from processor capacity disclosures and distributor revenue patterns.
Demand-supply-balance framing anchored the analytical framework, with segmentation across product type, form, application, and customer type dimensions modeled throughout the forecast period. CAGRs were derived from trajectory analysis of historical volume movements and elasticity-adjusted demand projections. Industry-specific forecast inputs included EUDR compliance timeline assumptions and freeze-thaw stability adoption curves in premium ice cream channels.
Sensitivities concentrate around cocoa price volatility, EUDR implementation threshold adjustments, and tempering automation adoption rates in artisan production environments. Forecasts reflect assumptions on regulatory enforcement intensity and technical capability diffusion timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Europe Dark Chocolate Market
Confectionery
Gum Base Candy Market
Confectionery
India Industrial Chocolate Market
Confectionery
UK Chocolate Market
Confectionery
Sugar-Free Sweets Market
Confectionery
Carob Chocolate Market
Confectionery
Low-Fat Sweets Market
Confectionery
Global Candy Market
Confectionery
North America Chocolate Market
Confectionery
Crunchy Chocolate Market
Confectionery
Italy Chocolate Market
Confectionery
North-American Industrial Chocolate Market
Confectionery
Jellies and Gummies Market
Confectionery
UK Compound Chocolate Market
Confectionery
Liquorice Shellac Market
Confectionery
Sugar Free Lollipops Market