
 Vegan Candies Market | 2026-2036
Vegan Candies Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Candies Market Analytics
Specialty store demand is decoupling from conventional grocery distribution as premium vegan confectionery builds dedicated shelf space. Lindt & Sprüngli anchors European premium chocolate alternatives through its dedicated vegan lines. No Whey Foods specializes in allergen-free formulations that dominate the free-from confectionery niche. YumEarth Organic leverages USDA Organic certification to control the North American natural channel.
Vegan candies are confectionery products formulated without animal-derived ingredients such as gelatin, dairy, beeswax, or carmine, relying instead on plant-based gelling agents like pectin or agar and alternative proteins for texture. These products serve consumers with dietary restrictions, ethical preferences, and sustainability concerns across retail and food service channels. Gummy candies lead volume due to pectin substitution maturity, while chocolate alternatives capture the highest margin pools through cocoa butter and oat milk formulations. Fruit-based ingredient types are expanding fastest as clean-label expectations intensify among retail consumers.
FDA labeling requirements and EU REACH standards on food contact materials shape ingredient transparency and packaging compliance across the vegan candies supply chain. EFSA novel food assessments slow but do not block innovation in emerging plant proteins and fermentation-derived sweeteners. Stakeholders must monitor evolving definitions of vegan claims under draft EU harmonization rules and decide whether to front-run stricter certification requirements.
Market Dynamics
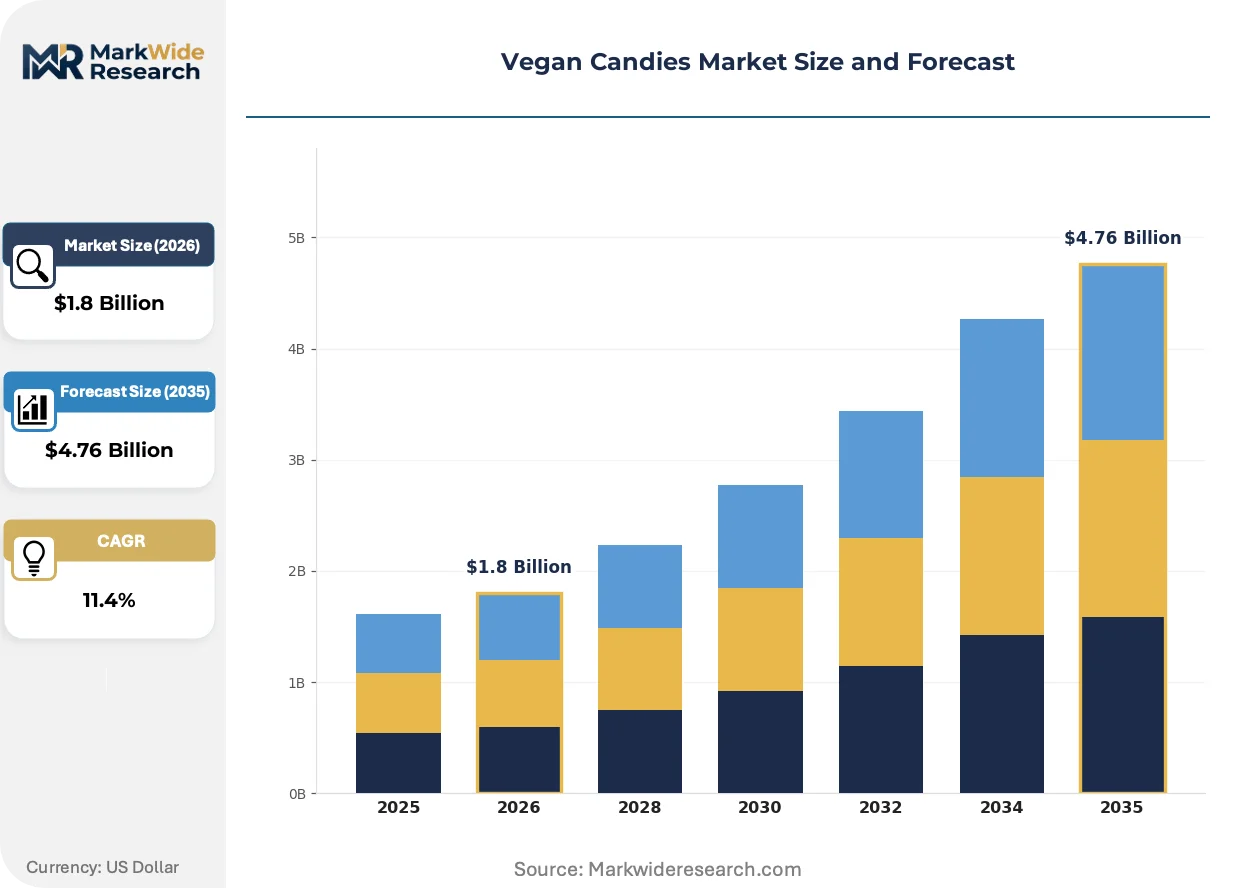
Pectin-based gelling technology maturity is compressing formulation timelines while EU clean-label regulations force ingredient transparency upgrades across the vegan confectionery supply chain. Specialty retail channels are capturing margin pools that conventional grocery once dominated.
Growth Catalysts
- REACH food contact standards:ECHA compliance requirements are accelerating packaging material transitions toward plant-based films and barrier coatings.
- Pectin substitution maturity:Advanced extraction methods from citrus peel and apple pomace are eliminating texture gaps that previously limited gummy candy applications.
- Germany consumer penetration:Mainstream vegan lifestyle adoption among millennial parents is creating dedicated shelf space in premium confectionery retail.
Market Restraints
- Cocoa butter price volatility:Weather-driven supply fluctuations in West African growing regions compress margin stability for chocolate-alternative formulations.
- EFSA novel food assessments:Fermentation-derived sweetener approvals face 18-24 month evaluation timelines that delay product launches.
- Beeswax substitution limitations:Carnauba and candelilla wax supply concentration in Brazil creates input bottlenecks for coating applications.
Strategic Opportunities
- Food service channel expansion:Airline, hotel, and corporate catering procurement is opening bulk vegan confectionery contracts previously locked by conventional suppliers.
- Fruit-based clean-label convergence:Whole-fruit puree integration with natural color extraction is capturing parent purchasers seeking simplified ingredient panels.
- EU harmonized vegan certification:Draft standardization rules create first-mover advantage for brands that front-run mandatory claim definitions.
Industry Challenges
- Food technologist specialization gaps:Formulation expertise spanning plant-based gelling agents, alternative proteins, and sensory masking remains scarce in European labor markets.
- Dual certification complexity:Simultaneous organic, vegan, and allergen-free audits strain quality assurance bandwidth and extend go-to-market timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Candies Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gummy Candies, Chocolates, Hard Candies, Lollipops End User: Retail Consumers, Food Service, Bulk Buyers, Specialty Stores Ingredient Type: Fruit-Based, Nuts, Chocolate Alternatives, Sweeteners Packaging Type: Bags, Boxes, Bulk Containers, Individual Wrappers |
| Companies Covered | SmartSweets, Surf Sweets, Lindt & Sprüngli, Haribo, Jelly Belly, No Whey Foods, YumEarth Organic, Taza Chocolate, Endangered Species Chocolate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Candies Market Evolving Landscape
Precision fermentation and enzymatic modification are converging to expand the functional ingredient toolkit available to vegan confectionery formulators. These advances are compressing the performance gap between plant-derived and animal-derived texture agents.
Cell-cultured dairy protein analogs synthesized through precision fermentation are electrifying texture replication in chocolate alternatives and caramel formulations. Premium chocolate manufacturers in Switzerland and Belgium are piloting these ingredients for mouthfeel matching. This technology is electrifying premium segment expansion by enabling claims that satisfy both ethical purists and sensory-focused consumers.
EU Green Deal Farm-to-Fork targets are mandating 25% reduction in chemical pesticide use by 2030, forcing fruit ingredient suppliers toward integrated pest management and regenerative orchard practices. Confectionery brands sourcing European strawberry, raspberry, and citrus concentrates must verify supply chain compliance. German and French retail buyers are now requiring documented Farm-to-Fork alignment as a listing prerequisite.
Subscription-based direct-to-consumer sampling is displacing traditional trade-show and in-store trial models for emerging vegan candy brands. Millennial parents in urban UK and Scandinavian markets are discovering niche products through curated monthly boxes before mainstream retail stocking. This channel shift concentrates early revenue for insurgent brands while reducing slotting fee dependence.
Vegan Candies Market Segmentation
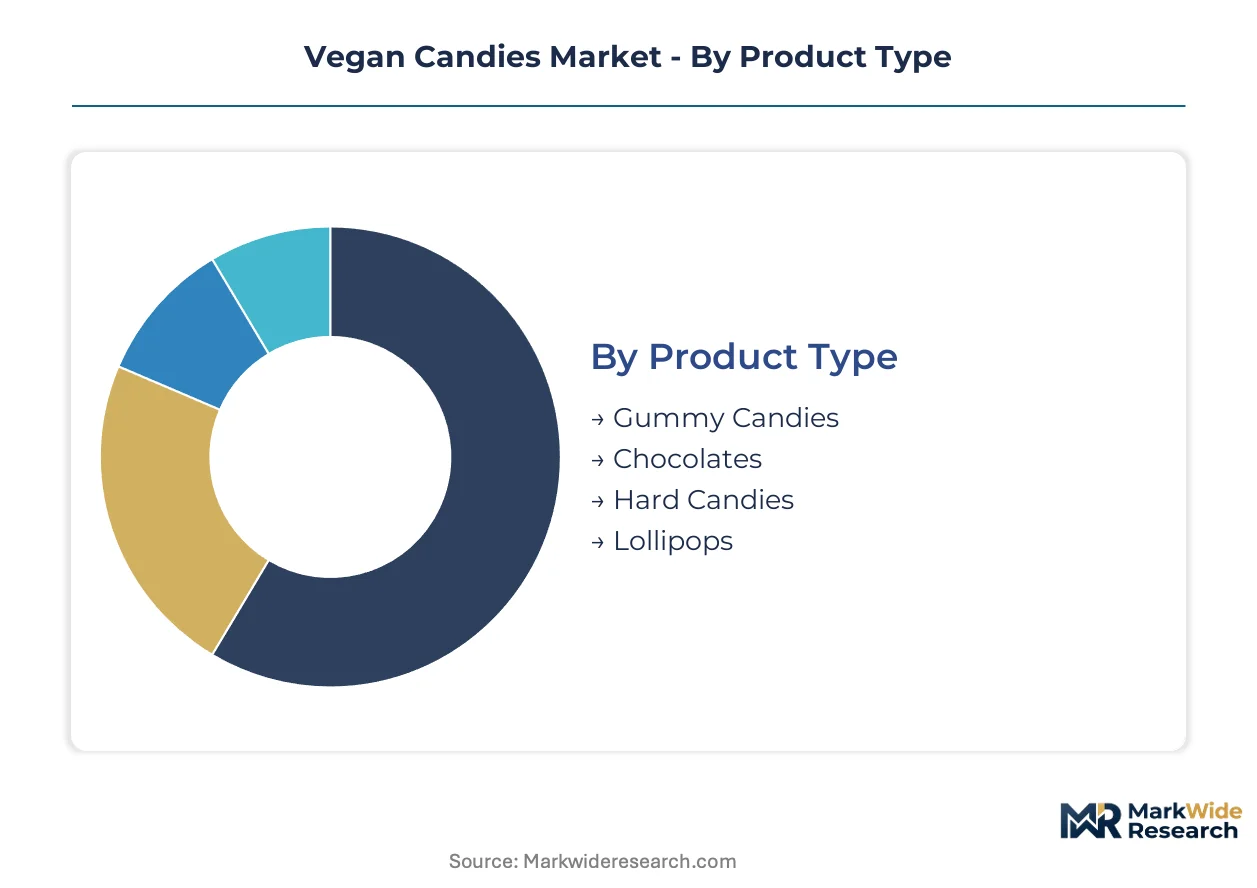
Vegan confectionery segmentation reveals how certification burdens and formulation complexity concentrate margin pools across distinct product architectures. Each dimension carries unique compliance obligations that reshape competitive positioning.
Product Type:
Certification intensity varies sharply across formats, with chocolate alternatives facing the most demanding dual vegan-organic audits while hard candies navigate simpler additive disclosures.
- Gummy Candies:Pectin-based formulations using citrus peel and apple pomace extraction have eliminated texture gaps that previously limited plant-based gelling. Demand concentrates in Germany where millennial parents prioritize clean-label confectionery for children, with EFSA novel food assessments creating 18-24 month approval timelines for emerging gelling innovations.
- Chocolates:Cocoa butter and oat milk formulations capture premium margin pools through precision fermentation advances in cell-cultured dairy protein analogs. Swiss and Belgian manufacturers pilot these ingredients for mouthfeel replication, though West African supply volatility compresses margin stability.
- Hard Candies:Simple sugar-isomalt matrices require minimal certification beyond standard vegan claim verification.
- Lollipops:Stick material compliance with REACH food contact standards drives packaging transition costs.
Gummy Candies sits at the top of the volume ranking, with Chocolates climbing the fastest.
End User:
Channel economics diverge sharply, with food service procurement opening bulk contracts previously locked by conventional suppliers while specialty retail captures premium shelf space.
- Retail Consumers:Urban millennial parents in UK and Scandinavian markets discover niche products through subscription-based direct-to-consumer sampling before mainstream retail stocking, concentrating early revenue for insurgent brands.
- Food Service:Airline, hotel, and corporate catering procurement is opening bulk vegan confectionery contracts previously locked by conventional suppliers, with EU Green Deal Farm-to-Fork alignment now required by German and French retail buyers.
- Bulk Buyers:Procurement shifts toward documented regenerative orchard practices for fruit ingredient verification.
- Specialty Stores:Dedicated shelf space builds margin pools that conventional grocery once dominated.
Retail Consumers holds the largest addressable base, with Food Service expanding most quickly.
Ingredient Type:
Supply concentration risks concentrate in beeswax substitutes, with carnauba and candelilla wax bottlenecks in Brazil creating coating application constraints.
- Fruit-Based:Whole-fruit puree integration with natural color extraction captures parent purchasers seeking simplified ingredient panels, with EU Green Deal mandates forcing 25% pesticide reduction by 2030 and regenerative orchard verification requirements.
- Chocolate Alternatives:Cocoa butter price volatility from West African weather patterns compresses formulation economics despite oat milk texture advances.
- Nuts:Allergen-free dual certification extends quality assurance timelines.
- Sweeteners:Fermentation-derived options face EFSA evaluation delays.
Fruit-Based leads current formulation trends, with Chocolate Alternatives gaining share fastest.
Packaging Type:
ECHA compliance requirements are accelerating material transitions toward plant-based films and barrier coatings across all formats.
- Bags:Flexible packaging dominates retail velocity with compostable film pilots.
- Boxes:Premium gifting formats require FSC-certified board verification.
- Bulk Containers:Food service channel expansion drives reusable container standardization.
- Individual Wrappers:Single-serve formats face highest unit cost pressure from barrier coating transitions.
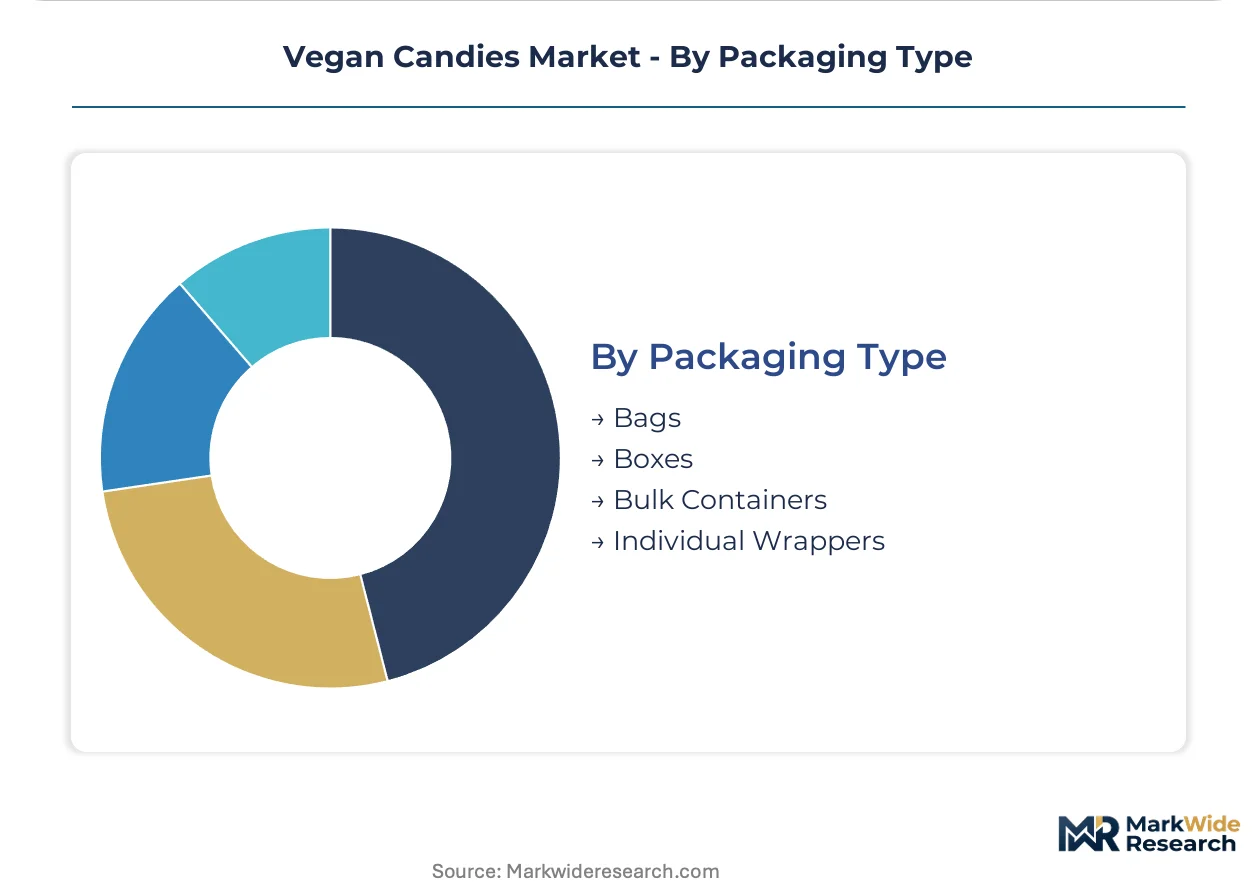
Bags maintains volume leadership, with Bulk Containers showing steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr Valley and Bavaria industrial clusters anchor European vegan confectionery production, with precision fermentation facilities and pectin extraction plants concentrated near Cologne and Munich. Specialty retail channels in Berlin and Hamburg drive premium product velocity ahead of broader continental adoption.
Germany
Millennial parents in Hamburg and Berlin prioritize clean-label confectionery for children, creating dedicated shelf space in premium retail. EFSA novel food assessments govern emerging gelling agent approvals with 18-24 month timelines. Bavaria's ingredient technology cluster near Munich hosts pectin extraction facilities serving pan-European formulation demand.
United States
Urban coastal consumers in California and New York discover niche brands through subscription sampling before mainstream retail stocking. FDA labeling requirements enforce ingredient transparency across interstate commerce. Pacific Northwest food technology corridors near Seattle pilot precision fermentation for cell-cultured dairy protein analogs.
United Kingdom
Scandinavian-influenced urban markets in London and Manchester accelerate plant-based confectionery trial through curated direct-to-consumer channels. REACH food contact standards mandate packaging material transitions toward plant-based films. Midlands manufacturing zones near Birmingham specialize in allergen-free production lines.
Switzerland
Premium chocolate heritage in Zurich and Geneva drives precision fermentation pilot programs for mouthfeel replication in dairy alternatives. Swissmedic food safety protocols align with EU standards while maintaining independent approval pathways. Lake Geneva biotech cluster hosts cell-cultured protein research facilities serving confectionery applications.
France
Île-de-France retail buyers now require documented EU Green Deal Farm-to-Fork alignment as a listing prerequisite for fruit-based confectionery. ANSM food contact material regulations enforce barrier coating compliance for packaging. Provence-Alpes-Côte d'Azur citrus orchards supply pectin feedstock under regenerative agriculture verification.
Vegan Candies Market Competitive Landscape
Portfolio diversification dominates the current landscape as established confectionery houses and insurgent specialists reposition around certification intensity. The vendor base spans three tiers: heritage chocolate manufacturers with dedicated vegan lines, allergen-free specialists controlling niche distribution, and organic-certified insurgents capturing natural channel velocity. Two archetypes define competitive positioning: scale-driven incumbents leveraging existing cocoa supply relationships, and agility-focused challengers exploiting direct-to-consumer discovery channels. M&A activity concentrates on pectin technology acquisition and regional specialty brand consolidation.
Within the heritage manufacturer tier, Lindt & Sprüngli and Haribo exemplify divergent strategic postures toward plant-based transition. Among allergen-free specialists, No Whey Foods occupies a position defined by dual vegan-allergen certification complexity. At the organic-certified challenger end, YumEarth Organic represents the natural channel velocity archetype built on USDA certification control.
| Leading Market Players |
|---|
| SmartSweets |
| Surf Sweets |
| Lindt & Sprüngli |
| Haribo |
| Jelly Belly |
| No Whey Foods |
| YumEarth Organic |
| Taza Chocolate |
| Endangered Species Chocolate |
| Others |
Value Network & Pricing Analysis
Cocoa butter cost volatility from West African weather patterns cascades through chocolate-alternative pricing tiers, compressing margins at the premium end while pectin extraction advances stabilize gummy candy economics across mid-market segments. Specialty retail markups absorb upstream input swings more effectively than conventional grocery channels, creating divergent pricing power by distribution archetype.
Pricing Analysis
Retailer markup layers stratify across premium, standard, and economy tiers based on certification intensity and channel positioning. Price differentiation hinges on dual vegan-organic audit burden and precision fermentation ingredient premiums. Pricing pressure stems from cocoa butter supply instability forcing reformulation trade-offs. Food service buyers exhibit highest price sensitivity due to bulk contract structures, while specialty store consumers accept premium positioning for clean-label claims.
Supply Chain Analysis
Returns and refurbishment flows remain minimal in confectionery, though packaging material transitions toward compostable films create reverse-logistics complexity for EU REACH compliance. Pectin feedstock concentrates in Brazil and Spain, with citrus peel extraction anchored in Mediterranean orchards. Supply chain risk centers on carnauba wax single-source vulnerability from Brazilian harvest fluctuations. Distribution runs through specialty retail channels capturing margin pools that conventional grocery once dominated.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vegan confectionery offers margin expansion through pectin substitution cost-down curves and precision fermentation premium-tier adoption, with clean-label certification creating pricing power insulation.
For Market Incumbents: Acquire pectin extraction technology capabilities to secure gummy candy formulation control against insurgent specialists. Defend shelf position by front-running EU harmonized vegan certification requirements before mandatory claim definitions finalize. Capacity addition in Bavaria's ingredient technology cluster reinforces proximity to German retail buyer concentration. For New Entrants and Emerging Players: Begin with food service channel white-space targeting, where airline and hotel procurement opens bulk contracts previously locked by conventional suppliers. Subscription-based direct-to-consumer sampling in UK and Scandinavian urban markets offers lowest customer acquisition friction before mainstream retail slotting fee exposure. For Investors and Strategic Acquirers: Consolidation pressure builds where dual certification complexity strains quality assurance bandwidth at mid-scale specialists. Long-term viability favors precision fermentation technology holders and pectin extraction asset owners. Watch EFSA novel food approval velocity as inflection signal for fermentation-derived sweetener platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Cell-cultured dairy protein analogs enable premium chocolate texture replication for Swiss manufacturers. |
| Pectin Extraction Facility Acquisition | Citrus peel and apple pomace processing secures gummy candy formulation independence from gelatin supply. |
| EU Harmonized Certification Front-Running | Draft vegan claim standardization creates first-mover listing advantage with German retail buyers. |
| Food Service Channel Expansion | Airline and hotel catering procurement opens bulk contract volumes previously inaccessible to insurgent brands. |
| Regenerative Orchard Supply Verification | Farm-to-Fork alignment documentation satisfies French and German retailer listing prerequisites for fruit-based lines. |
Research Methodology
Bottom-up retail channel modeling reconciled against top-down ingredient supply tracking forms the analytical core of this study. Primary interviews with vegan confectionery brand managers, specialty retail category buyers, food service procurement officers, and pectin extraction plant managers combined with secondary validation from FDA labeling guidance, EFSA novel food registers, EU REACH compliance databases, and Nielsen retail audit data. Triangulation between demand-side velocity indicators and supply-side capacity announcements ensures cross-verified output integrity.
Input-output matrices segment volume and value projections across product type, end user, ingredient category, and packaging format dimensions throughout the forecast period. CAGRs derive from regression analysis of historical adoption curves calibrated against regulatory milestone impacts. Forecast inputs incorporate EFSA approval timeline assumptions for fermentation-derived ingredients and EU Green Deal pesticide reduction compliance trajectories for fruit-based feedstock suppliers.
Several conditions sit outside the modeled scope, including geopolitical trade disruption scenarios and accelerated precision fermentation cost curves beyond current pilot scale. Forecasts reflect documented assumptions about clean-label regulatory harmonization timing and specialty retail shelf space expansion rates. Practitioners should monitor EFSA novel food assessment velocity and German retail buyer Farm-to-Fork documentation requirements for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Chocolate Confectionery Market
Confectionery
North America Sugar-Free Chewing Gum Market
Confectionery
Dark Chocolate Market
Confectionery
UK Chocolate Market
Confectionery
Sugar Free Candy Market
Confectionery
Global Confectionery Market
Confectionery
Ruby Chocolate Market
Confectionery
South America Confectionery Market
Confectionery
Carob Chocolate Market
Confectionery
Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market
Confectionery
Global Chocolate Sprinkles Market
Confectionery
Vegan Gummy Candy Market
Confectionery
Europe Chocolate Market
Confectionery
South Africa Confectionery Market
Confectionery
CBD-Infused Confectionery Market
Confectionery
North America Gummy Market