
 Low-Calorie Candy Market | 2026-2036
Low-Calorie Candy Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Calorie Candy Market Analytics
Asset-light contract manufacturing and co-packing arrangements is reconfiguring competitive entry barriers for emerging low-calorie candy brands. SmartSweets leverages direct-to-consumer channel control to bypass traditional retail gatekeepers. Russell Stover anchors its position through specialized sugar-free chocolate production capabilities. Mars competes through scaled R&D infrastructure that accelerates reformulation timelines.
Low-calorie candy comprises confectionery products formulated with reduced caloric density through substitution of sucrose with sugar alcohols, high-intensity sweeteners, or soluble fibers, typically achieving 25-40% fewer calories per serving than standard equivalents while maintaining comparable sensory profiles through modified manufacturing processes including controlled crystallization and lipid matrix engineering. The product type dimension shows gummies capturing disproportionate innovation investment due to their compatibility with soluble fiber enrichment and clean-label positioning, while hard candies remain a mature margin pool sustained by diabetic consumer loyalty. End user segmentation reveals health-conscious consumers as the fastest-expanding cohort, though weight watchers retain the highest per-capita consumption frequency and brand premium tolerance.
FDA nutrition labeling requirements for added sugars disclosure directly shape product formulation decisions and package claim permissibility, while USDA school nutrition standards influence permissible retail placement for child-targeted variants. The European Food Safety Authority's ongoing evaluations of high-intensity sweetener safety profiles create regulatory uncertainty that constrains formulation flexibility for exporters. Stakeholders must monitor evolving sweetener approval trajectories and retail pharmacy channel expansion as dual indicators of category legitimacy and access expansion.
Market Dynamics
FDA added-sugar disclosure mandates are forcing wholesale reformulation across confectionery portfolios, compressing development timelines and elevating sugar alcohol expertise from niche capability to core competitive infrastructure.
Growth Catalysts
- Sugar Alcohol Expertise:Erythritol and allulose processing capabilities now determine contract manufacturing access for emerging brands seeking clean-label positioning without glycemic impact.
- Retail Pharmacy Channel Expansion:CVS and Walgreens shelf resets for diabetic-friendly SKUs create dedicated merchandising real estate previously unavailable to reduced-calorie confectionery.
- Soluble Fiber Enrichment:Prebiotic fiber integration in gummy matrices satisfies dual demand for satiety signaling and gut health claims among health-conscious millennial buyers.
Market Restraints
- Input Cost Volatility:Erythritol supply concentrates in Chinese fermentation facilities, exposing formulators to tariff and shipping disruptions without viable secondary sourcing.
- Technical Limitation:Sugar alcohols retain cooling aftertaste and laxative threshold constraints that limit dosage in chocolate applications versus hard candy or gummy formats.
- Regulatory Friction:EFSA's pending re-evaluation of high-intensity sweetener safety profiles blocks European market entry for stevia-rebaudioside blends approved in the United States.
Strategic Opportunities
- Pediatric School Nutrition:USDA Smart Snacks in School standards create institutional procurement pathways for portion-controlled, reduced-sugar candy meeting competitive food criteria.
- Direct-to-Consumer Subscriptions:Monthly replenishment models bypass slotting fee barriers while capturing consumption data for rapid flavor optimization.
- Allulose Regulatory Tailwind:FDA's 2019 exclusion of allulose from added sugars declaration invites reformulation investment ahead of anticipated European approvals.
Industry Challenges
- Flavor Chemist Scarcity:Specialized expertise in masking sugar alcohol aftertaste and optimizing lipid mouthfeel commands premium compensation that strains emerging brand budgets.
- Certification Timeline Compression:Non-GMO Project and keto certification processes extend launch schedules by 8-14 months, delaying revenue recognition against fixed R&D burn rates.
- Legacy Equipment Retrofit:Controlled crystallization parameters for sugar alcohols require humidity-controlled environments incompatible with standard sucrose production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Calorie Candy Market |
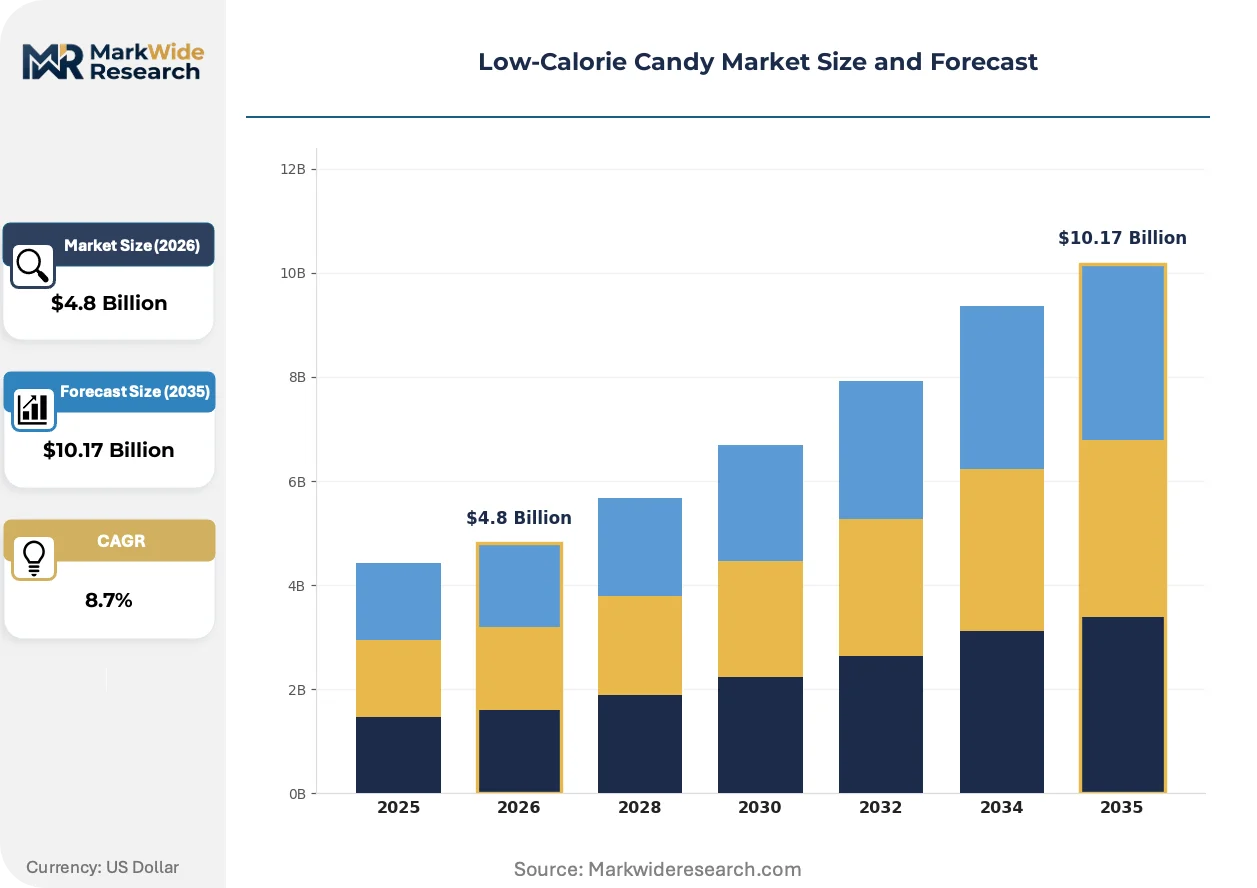
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chewy Candies, Hard Candies, Gummies, Chocolates End User: Health-Conscious Consumers, Diabetics, Weight Watchers, Children Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores Ingredient Type: Natural Sweeteners, Artificial Sweeteners, Sugar Alcohols, Fiber Enriched |
| Companies Covered | Nestle, The Hershey Company, Mars, Russell Stover, SmartSweets, Tootsie Roll, Jelly Belly, TruJoy Sweets, Lotte, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Calorie Candy Market Evolving Landscape
Reformulation chemistry is migrating from sucrose substitution toward matrix engineering that preserves sensory fidelity. Three converging developments are compressing competitive differentiation timelines across the category.
Allulose is migrating from premium positioning to mass-market penetration as Cargill and Ingredion expand domestic fermentation capacity. Mid-tier private label manufacturers are adopting the sweetener for mainstream grocery SKUs. The technology is enabling calorie reduction claims without the digestive tolerance warnings required for polyol-heavy formulations.
EFSA's systematic review of steviol glycoside acceptable daily intakes is reshaping European formulation roadmaps ahead of anticipated 2026 guidance updates. Manufacturers are pre-emptively diversifying sweetener portfolios to avoid single-point-of-failure exposure. Chocolate and compound coating segments face the steepest reformulation costs given stevia's incompatibility with Maillard browning requirements.
Health-conscious buyers are consolidating purchase decisions around third-party certification marks rather than manufacturer claims. Keto-certified and diabetic-association-endorsed SKUs command shelf preference in specialty retail channels. United States coastal metro markets exhibit the fastest certification-driven switching behavior, with Midwest and Southern regions trailing by 18-24 months in adoption velocity.
Low-Calorie Candy Market Segmentation
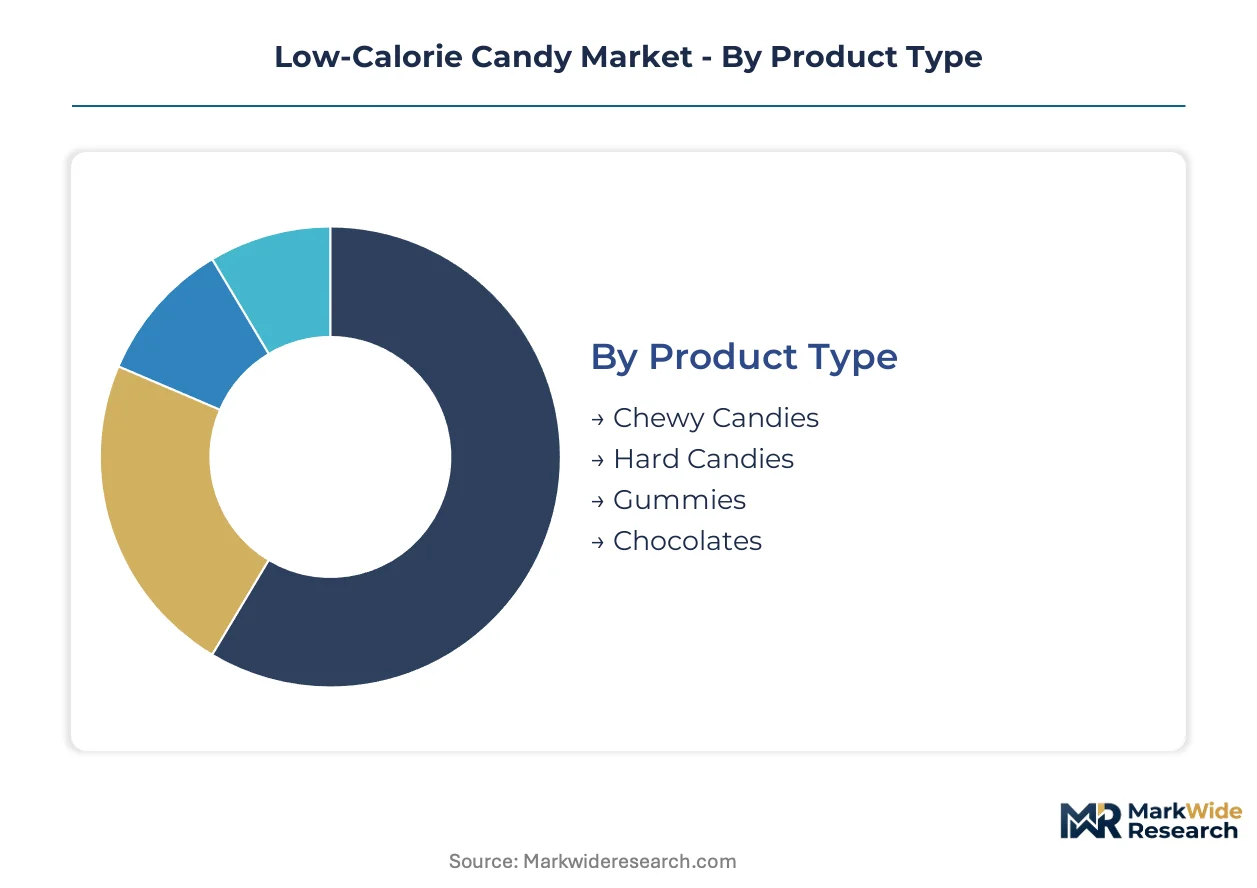
Low-calorie candy segmentation reveals how formulation chemistry, distribution economics, and consumer health positioning intersect. Manufacturers must align R&D investment with channel-specific velocity and end-user tolerance for sweetener systems.
Product Type:
Chewy formulations span the widest use-case spectrum from diabetic-friendly hard candies to prebiotic-enriched functional gummies targeting gut health positioning.
- Gummies:Soluble fiber matrices enable clean-label satiety claims while accommodating allulose and erythritol blends without crystallization defects. Coastal United States metro buyers show disproportionate preference for keto-certified gummy SKUs in specialty retail.
- Chocolates:Lipid matrix engineering masks sugar alcohol cooling effects through cocoa butter crystallization control. European market entry faces EFSA stevia re-evaluation barriers that constrain reformulation timelines for chocolate applications.
- Hard Candies:Diabetic consumer loyalty sustains this mature segment through pharmacy channel placement at CVS and Walgreens.
- Chewy Candies:Taffy and caramel variants leverage isomalt for texture retention with reduced hygroscopicity.
Established volume favors hard candies; emerging adoption favors gummies.
End User:
Customer type determines pricing tolerance, certification requirements, and channel access—health-conscious millennials pay premiums for third-party marks that diabetic segments treat as baseline hygiene.
- Health-Conscious Consumers:Prebiotic fiber integration and non-GMO Project certification drive purchase decisions. United States coastal markets exhibit certification-driven switching behavior 18-24 months ahead of Midwest adoption curves.
- Weight Watchers:Highest per-capita consumption frequency and brand premium tolerance among all cohorts. Direct-to-consumer subscription models capture this segment through portion-controlled replenishment.
- Diabetics:Pharmacy channel dependence and glycemic index verification requirements shape SKU selection.
- Children:USDA Smart Snacks in School standards create institutional procurement pathways for portion-controlled variants meeting competitive food criteria.
Weight watchers deliver margin concentration; health-conscious consumers are climbing the fastest.
Distribution Channel:
Channel selection determines slotting fee exposure, data capture capabilities, and certification mark visibility.
- Online Retail:Direct-to-consumer control enables rapid flavor optimization through consumption data capture. SmartSweets and emerging brands bypass traditional retail gatekeepers via subscription replenishment models.
- Supermarkets:Mainstream grocery shelf resets for reduced-calorie confectionery expand access but demand trade spend discipline.
- Health Food Stores:Keto-certified and diabetic-association-endorsed SKUs command shelf preference with certification mark consolidation.
- Convenience Stores:Impulse-driven velocity favors single-serve portion control without premium pricing.
Supermarkets anchor volume scale; online retail gains share fastest.
Ingredient Type:
Sweetener system selection shapes regulatory permissibility, digestive tolerance labeling, and manufacturing equipment requirements.
- Sugar Alcohols:Erythritol and allulose processing capabilities determine contract manufacturing access for emerging brands. Chinese fermentation facility concentration exposes formulators to tariff and shipping disruptions.
- Natural Sweeteners:Stevia-rebaudioside blends face EFSA pending re-evaluation blocking European entry for US-approved formulations.
- Artificial Sweeteners:Sucralose and aspartame retain cost advantage in value-tier private label manufacturing.
- Fiber Enriched:Prebiotic integration satisfies dual demand for satiety signaling and gut health claims among millennial buyers.
Sugar alcohols dominate current formulation; fiber enriched shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States consumers absorb a 15-20% price premium for keto-certified SKUs versus equivalent formulations in Germany, where retailer private labels compress branded positioning power. This pricing-power asymmetry reflects divergent certification mark penetration and pharmacy channel development trajectories between North American and European markets.
United States
Health-conscious millennials in coastal metros drive certification-driven switching behavior 18-24 months ahead of Midwest adoption curves. FDA added-sugar disclosure mandates force wholesale portfolio reformulation, compressing development timelines for manufacturers. Chicago and New Jersey host specialized sugar alcohol processing clusters where contract manufacturers retrofit humidity-controlled environments for erythritol crystallization.
Germany
Diabetic consumer loyalty sustains pharmacy channel placement for hard candy variants with glycemic index verification. EFSA's pending re-evaluation of steviol glycoside acceptable daily intakes blocks market entry for stevia-rebaudioside blends approved in the United States. Cologne and Hamburg anchor private label manufacturing concentration where mid-tier producers adopt allulose for mainstream grocery SKUs.
Japan
Weight watcher cohorts exhibit highest per-capita consumption frequency and brand premium tolerance among Asian markets. METI standards for functional food claims shape permissible gut health and satiety signaling language on packaging. Tokyo and Osaka metropolitan areas concentrate direct-to-consumer subscription fulfillment infrastructure for portion-controlled replenishment models.
United Kingdom
Health food store channel expansion creates dedicated merchandising real estate for third-party certified SKUs previously confined to specialty retail. FSA guidance on sugar reduction targets influences manufacturer reformulation roadmaps ahead of anticipated mandatory thresholds. London and Manchester host emerging brand headquarters leveraging asset-light contract manufacturing to bypass traditional retail gatekeepers.
Canada
Cross-border e-commerce penetration enables United States direct-to-consumer brands to capture health-conscious consumers without domestic manufacturing presence. Health Canada labeling requirements for sugar alcohols align closely with FDA frameworks, reducing regulatory friction for exporters. Toronto and Vancouver metropolitan clusters concentrate retail pharmacy shelf resets for diabetic-friendly confectionery placement.
Low-Calorie Candy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in sugar alcohol fermentation and prebiotic fiber supply. The market structure fragments across three distinct capability layers: scaled multinationals with captive R&D infrastructure, mid-tier private label manufacturers with flexible contract capacity, and emerging direct-to-consumer brands with channel control but manufacturing dependence. Two strategic archetypes dominate competitive positioning: asset-light brand builders leveraging co-packing arrangements, and vertically integrated producers with in-house sugar alcohol processing. Capacity expansion in domestic allulose fermentation and strategic partnerships for pharmacy channel access represent the dominant competitive moves compressing differentiation timelines.
Within the scaled multinational tier, Nestle and Mars occupy positions defined by reformulation infrastructure depth and retail relationship breadth. Mars exemplifies the R&D-heavy archetype where accelerated timeline capabilities for sugar alcohol matrix engineering sustain portfolio renovation velocity. Among confectionery specialists, The Hershey Company and Russell Stover sit within differentiated positioning around chocolate applications and sugar-free production capabilities respectively. SmartSweets represents the asset-light brand builder archetype, channeling direct-to-consumer control into rapid flavor optimization without captive manufacturing investment. Tootsie Roll occupies a position bridging traditional manufacturing scale with emerging health-positioned line extensions.
| Leading Market Players |
|---|
| Nestle |
| The Hershey Company |
| Mars |
| Russell Stover |
| SmartSweets |
| Tootsie Roll |
| Jelly Belly |
| TruJoy Sweets |
| Lotte |
| Others |
Value Network & Pricing Analysis
Undercapacity in domestic allulose fermentation capacity drives supplier pricing power while forcing reformulation decisions toward higher-cost erythritol blends. This utilization squeeze concentrates margin pressure on mid-tier private label manufacturers lacking long-term offtake agreements with Cargill or Ingredion.
Pricing Analysis
The customization-premium spread separates keto-certified direct-to-consumer SKUs from standard grocery private label formulations. Three-tier pricing structure across premium, standard, and economy levels reflects certification mark density and channel control intensity. Price differentiation hinges on third-party certification investment and vertical integration into sugar alcohol processing. Pricing pressure stems from Chinese erythritol tariff exposure, with contract manufacturers absorbing margin compression rather than passing through to shelf price. Weight watcher segments exhibit lowest price sensitivity; convenience store impulse buyers face highest elasticity.
Supply Chain Analysis
Contract-manufacturing concentration sits with specialized sugar alcohol processors in Chicago and New Jersey humidity-controlled facilities. Geographic supply concentration centers on Chinese fermentation plants for erythritol, United States corn-belt allulose capacity, and Indian prebiotic fiber extraction. Raw material dependencies include corn-derived dextrose for allulose feedstock, fermentation-grade glucose for erythritol, and chicory root inulin for fiber enrichment. Single-source vulnerability runs through Chinese erythritol supply exposed to tariff and shipping disruption. Distribution runs through retail pharmacy resets at CVS and Walgreens, mainstream grocery slotting, and direct-to-consumer fulfillment infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
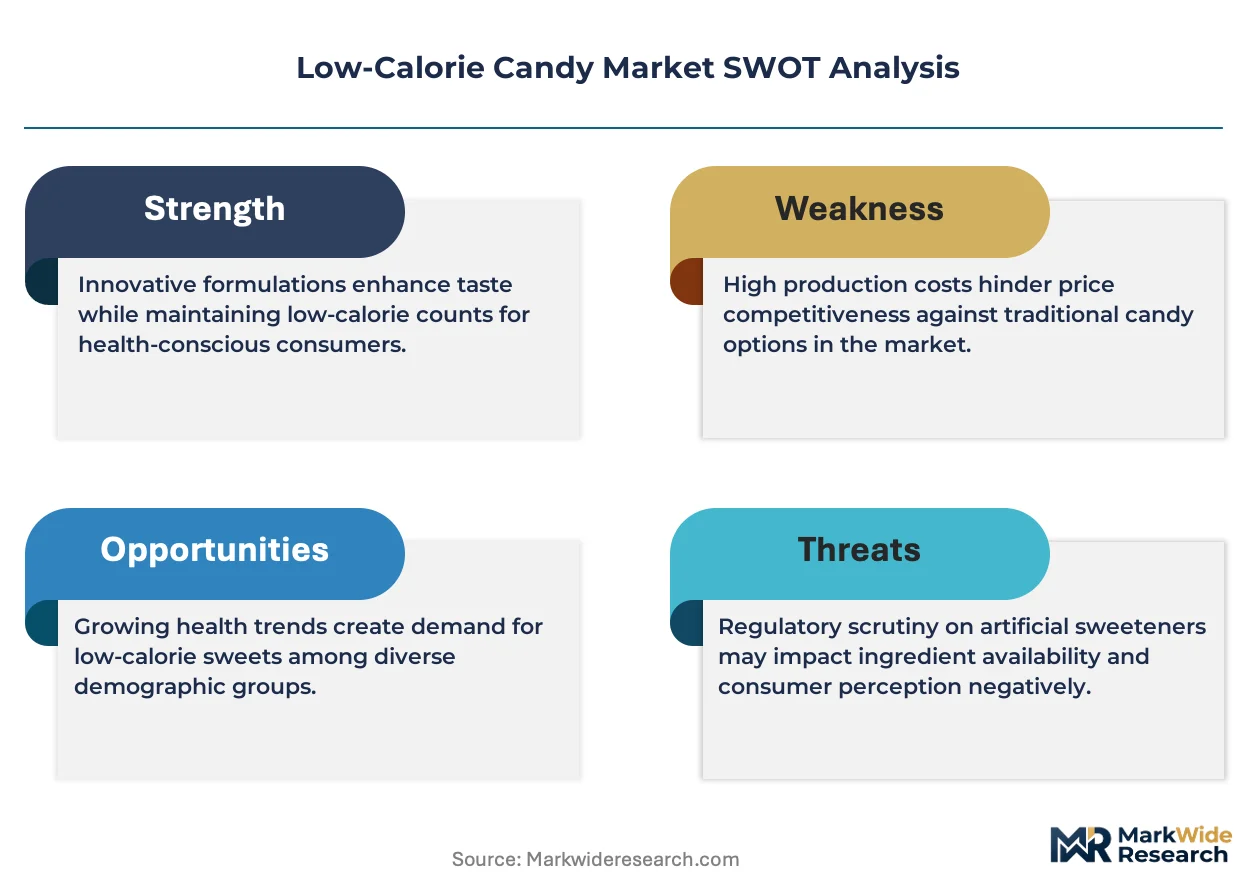
The low-calorie candy market presents a defensive-moat story anchored in regulatory entrenchment. FDA added-sugar disclosure mandates and EFSA pending re-evaluations create formulation barriers that favor incumbents with established compliance infrastructure.
For Market Incumbents: Pre-empt emerging brand encroachment by locking exclusive pharmacy channel resets at CVS and Walgreens before contract manufacturing capacity tightens further. Accelerate in-house allulose processing capability to reduce dependence on Cargill and Ingredion supply allocations. Defensive consolidation through certification mark accumulation—Non-GMO Project and keto certification—raises emerging brand launch costs by 8-14 months.
For New Entrants and Emerging Players: Pursue direct-to-consumer subscription white space in weight watcher cohorts where per-capita consumption frequency and brand premium tolerance peak. Target health-conscious millennial segments in United States coastal metros ahead of Midwest adoption curves. Go-to-market leverage rests on rapid flavor optimization through consumption data capture bypassing traditional retail slotting fee barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sugar alcohol processing infrastructure as humidity-controlled crystallization environments become mandatory. Long-term viability favors asset-light brand builders with channel control over vertically integrated manufacturers facing legacy equipment retrofit burdens. Acquisition target archetype: emerging direct-to-consumer brands with established subscription velocity and co-packing relationships. Signal to monitor: domestic allulose fermentation capacity expansion announcements as inflection indicator for input cost trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses CVS and Walgreens slotting fees while capturing consumption data for flavor optimization velocity. |
| Allulose Reformulation Investment | Exploits FDA exclusion from added sugars declaration ahead of anticipated European approvals. |
| Third-Party Certification Accumulation | Non-GMO Project and keto marks command shelf preference in health food store channel expansion. |
| Pharmacy Channel Shelf Reset Capture | CVS and Walgreens diabetic-friendly SKU placement creates dedicated merchandising real estate. |
| Prebiotic Fiber Integration | Satisfies dual demand for satiety signaling and gut health claims among millennial buyers. |
Research Methodology
Operator-level perspectives from brand managers, category buyers at retailers, contract manufacturing operations heads, and flavor chemist specialists anchored the qualitative base. Primary interviews with supply planners and channel sales heads combined with secondary validation from FDA labeling guidance documents, USDA Smart Snacks standards, EFSA sweetener safety evaluations, and Nielsen retail audit data. Bottom-up volume triangulation across product type, end user, distribution channel, and ingredient type segmentation intersected with top-down market sizing.
Scenario-bracketing framed demand projections across the analysis window through sensitivity testing of regulatory approval trajectories and sweetener substitution elasticities. Segmentation dimensions modeled include product type, end user cohort, distribution channel, and ingredient system chemistry. CAGRs derived from trend extrapolation of reformulation adoption curves and pharmacy channel penetration rates. Industry-specific forecast inputs incorporated EFSA steviol glycoside re-evaluation timeline uncertainty and domestic allulose capacity expansion schedules.
Sensitivities concentrate around EFSA guidance updates, Chinese erythritol supply disruptions, and certification timeline compression effects. Forecasts reflect assumptions on regulatory permissibility trajectories and consumer tolerance for sugar alcohol digestive effects. Quarterly review of pharmacy channel shelf reset announcements, contract manufacturing capacity utilization signals, and sweetener approval filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Low-Calorie Chocolate Market
Confectionery
Europe Premium Chocolate Market
Confectionery
Germany Chocolate Market
Confectionery
Carob Chocolate Market
Confectionery
India Industrial Chocolate Market
Confectionery
Europe Compound Chocolate Market
Confectionery
Asia-Pacific Sugar Free Mints Market
Confectionery
Low-Fat Dark Chocolate Market
Confectionery
Low Calorie Nutella Market
Confectionery
Dietary Chocolate Products Market
Confectionery
Ruby Chocolate Market
Confectionery
Low-Calorie Dark Chocolate Market
Confectionery
Confectionery Fillings Market
Confectionery
North America Compound Chocolate Market
Confectionery
Macarons Market
Confectionery
UK Confectionery Market