
 North America Confectionery Market | 2026-2036
North America Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Confectionery Market Outlook
Precision fermentation for cocoa butter alternatives is rewriting ingredient sourcing economics in confectionery manufacturing. Mars Incorporated leverages its vertical supply chain from bean to bar to sustain cost discipline across volatile cocoa markets. The Hershey Company anchors its position through dominant control of the North American chocolate aisle in mass retail channels. Mondelēz International competes aggressively in snacking-confectionery hybrids, extending its portfolio beyond traditional sweets into permissible indulgence formats.
Confectionery encompasses sugar-based and cocoa-based products formulated with specified moisture content, fat percentages, and shelf-stability parameters, manufactured through conching, tempering, depositing, or starch molding processes for human consumption as indulgence or functional foods. Chocolate commands the largest value pool due to premium pricing and brand loyalty, while gummy candy represents the fastest-expanding segment driven by vitamin fortification and adult-targeted positioning. E-commerce distribution channels are capturing disproportionate growth as direct-to-consumer subscription models bypass traditional grocery slotting fees and build recurring revenue streams.
The FDA governs ingredient safety and nutrition fact panel disclosures, while USDA oversees dairy-derived components in milk chocolate through its grading and inspection protocols. Health Canada and PMRA regulate cross-border trade through pesticide residue limits on imported cocoa and sugar crops, shaping supplier qualification requirements for brands operating binational supply chains. Stakeholders must monitor evolving sugar taxation proposals at the state and provincial level, as these could abruptly reshape price architecture and channel profitability across the continent.
Market Dynamics
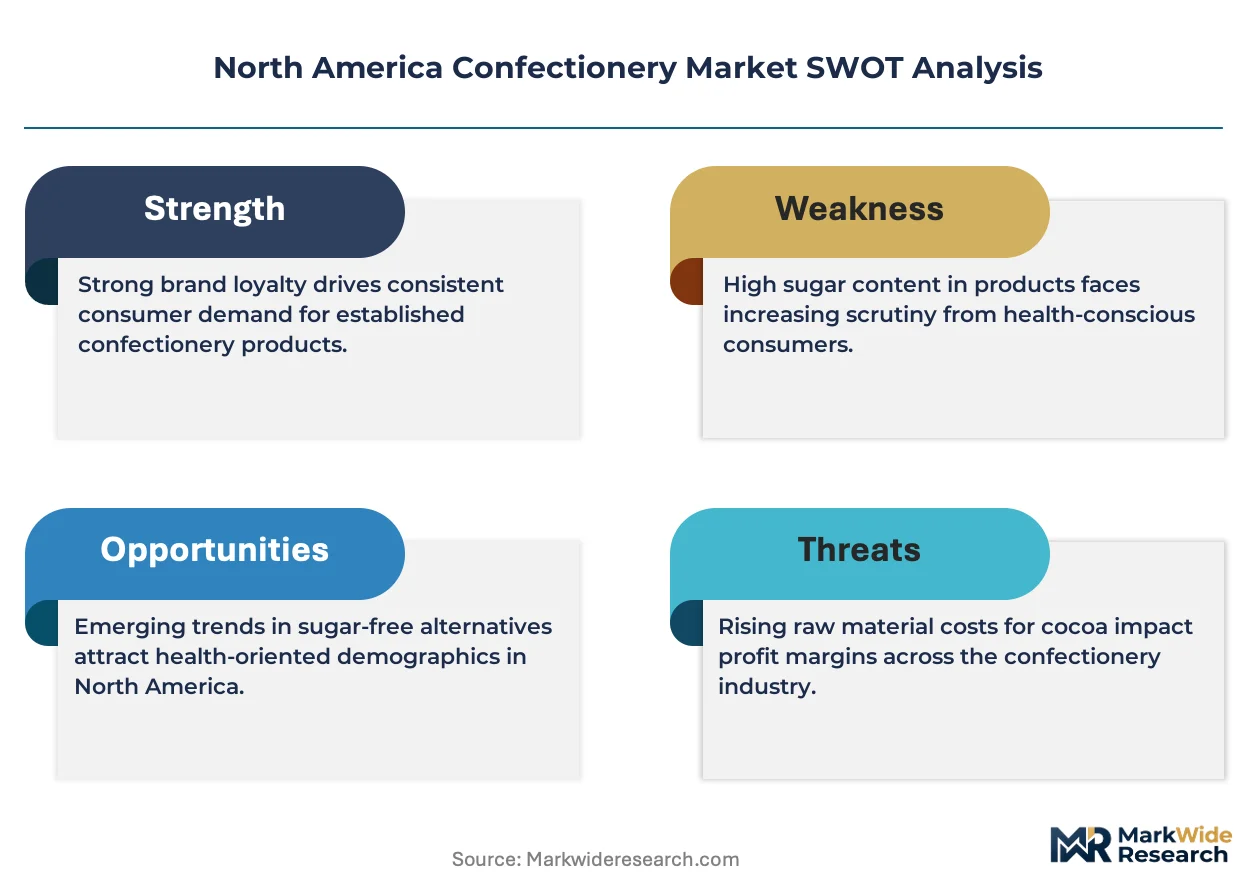
The FDA's updated nutrition labeling requirements for added sugars are forcing reformulation across North American confectionery portfolios, while precision fermentation for cocoa butter alternatives is compressing traditional ingredient sourcing economics.
Growth Catalysts
- Functional ingredient demand:Adult consumers in the United States and Canada are pulling premium chocolate with vitamin fortification and adaptogenic positioning into mainstream retail channels.
- Direct-to-consumer subscription models:E-commerce platforms are bypassing traditional grocery slotting fees and building recurring revenue streams for artisan and mid-tier brands.
- USDA dairy grading protocols:Milk chocolate producers leveraging USDA-inspected dairy components are securing preferential placement in convenience store channels.
Market Restraints
- Cocoa price volatility:West African supply concentration exposes North American manufacturers to weather-driven input cost swings and currency fluctuations.
- Sugar taxation proposals:State-level legislative initiatives in California and New York threaten abrupt price architecture changes and channel profitability compression.
- Technical shelf-life limitations:Clean-label formulations without artificial preservatives face distribution radius constraints and retail rejection rates.
Strategic Opportunities
- Underpenetrated Canadian provinces:Quebec and British Columbia present whitespace for premium positioning and localized flavor innovation.
- Health Canada regulatory tailwind:Natural health product licensing pathways for fortified gummies are accelerating vitamin-confectionery hybrid launches.
- Convenience channel digitization:Self-checkout and mobile-order integration in US c-store networks are enabling impulse purchase data capture and personalization.
Industry Challenges
- Confectionery technologist shortage:Specialized expertise in tempering, conching, and starch molding is aging out faster than vocational programs replenish talent pipelines.
- Legacy ERP integration friction:Real-time traceability mandates for FDA compliance are colliding with decades-old manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Confectionery Market |
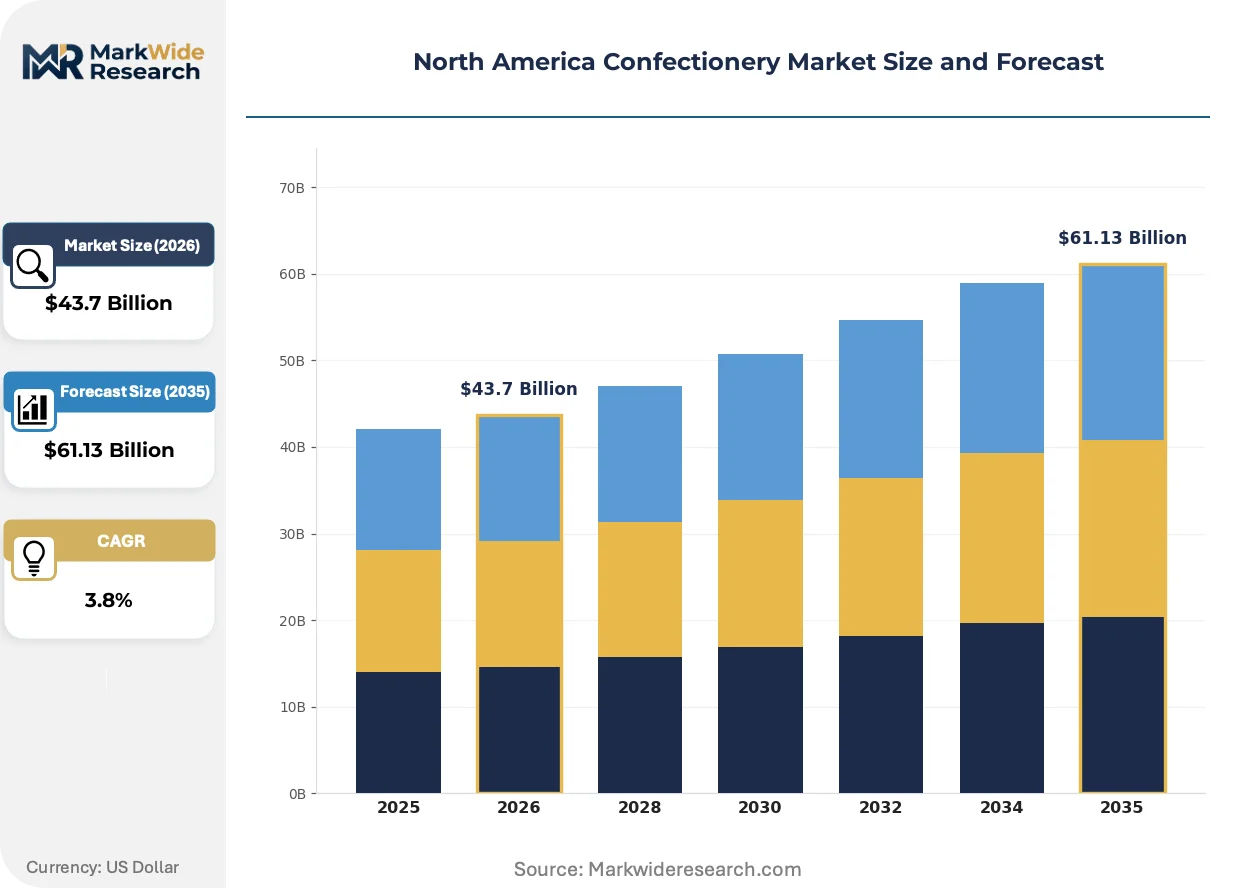
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $61.13 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Hard Candy, Gummy Candy, Pastries Ingredient Type: Sugar, Corn Syrup, Cocoa, Artificial Flavor Distribution Channel: Grocery Stores, Convenience Stores, E-commerce, Specialty Shops Consumer Age Group: Children, Teenagers, Adults, Seniors |
| Companies Covered | Mars Incorporated, The Hershey Company, Mondelēz International Inc., Ferrero International SA, Chocoladefabriken Lindt & Sprüngli AG, Nestlé SA, Perfetti Van Melle BV, HARIBO Holding GmbH & Co. KG, General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Confectionery Market Strategic Shifts
Digital twin modeling is virtualizing product development cycles across North American confectionery operations, compressing time-to-market for seasonal and limited-edition launches.
Precision fermentation technology for cocoa butter alternatives is virtualizing the ingredient sourcing layer of chocolate manufacturing. Mid-tier producers in the United States are adopting these biosynthetic lipids to decouple from volatile commodity cocoa markets. The technology is virtualizing cost structures that previously anchored competitive positioning to supply chain geography.
The FDA's updated nutrition labeling requirements for added sugars are mandating gram-level disclosure on front-of-pack and nutrition fact panels. Reformulation teams are replacing sucrose with allulose and monk fruit extract to maintain sweetness perception while complying. Milk chocolate and sugar confectionery segments are absorbing the highest compliance costs and reformulation complexity.
Subscription-based procurement is consolidating household purchasing into curated monthly boxes delivered direct from manufacturer or specialty retailer. Traditional grocery impulse fixtures and seasonal aisle displays are losing volume to these locked-in replenishment cycles. This behavioral shift is most visible in affluent US coastal metro markets where convenience premiumization commands highest willingness-to-pay.
North America Confectionery Market Segmentation
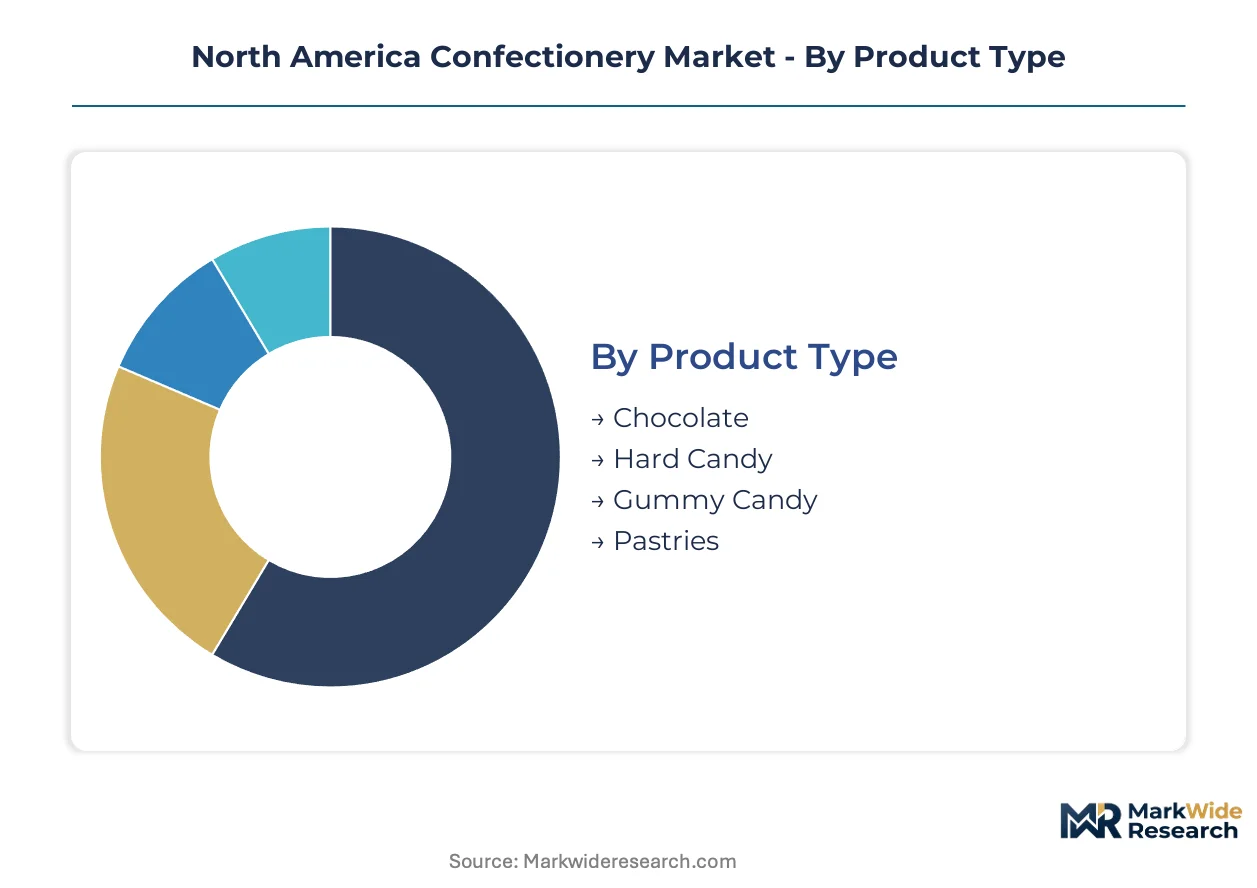
Segmentation reveals how formulation choices, channel access, and demographic targeting fragment competitive opportunity across North American confectionery. Manufacturers align R&D spend and trade marketing against specific segment economics rather than pursuing undifferentiated scale.
Product Type:
Cost tier stratification separates commodity sugar confectionery from premium cocoa-based formats with radically different margin profiles and shelf positioning requirements.
- Chocolate:Cocoa butter and cocoa mass formulations command premium pricing through specified fat percentages and conching protocols. United States mass retail channels concentrate demand for milk chocolate variants, though dark chocolate with elevated cacao content is pulling adult consumers from standard offerings. FDA added-sugar labeling mandates are forcing reformulation complexity in this segment.
- Gummy Candy:Starch-molded gelatin or pectin matrices enable vitamin fortification and functional positioning at accessible price points. Health Canada natural health product licensing pathways are accelerating hybrid launches targeting adult wellness segments in Canadian provinces.
- Hard Candy:High-boiled sucrose or isomalt formulations deliver extended shelf stability through low water activity specifications. Sugar taxation proposals in California and New York threaten margin compression for traditional sucrose-based varieties.
- Pastries:Moisture-sensitive baked shells with confectionery fillings face distribution radius constraints due to shorter shelf life. Convenience store channel digitization in US metropolitan markets is enabling localized fresh delivery models.
Chocolate commands the established base. The steepest expansion runs through Gummy Candy.
Ingredient Type:
Application requirements in specific product formats dictate ingredient selection, with clean-label momentum displacing artificial additives in premium-positioned lines.
- Sugar:Sucrose remains the reference standard for sweetness perception and bulking function across hard candy and chocolate categories. State-level legislative initiatives threaten abrupt cost architecture changes for manufacturers dependent on traditional sweeteners.
- Cocoa:Specified butter content and origin-designated bean sourcing differentiate premium chocolate tiers. West African supply concentration exposes North American processors to weather-driven input volatility and currency fluctuation risk.
- Corn Syrup:High-fructose and glucose syrup variants provide humectancy and crystallization control in chewy confectionery formats. USDA dairy grading protocols intersect with corn syrup usage in milk chocolate production for convenience store channel placement.
- Artificial Flavor:Synthetic esters and aldehydes deliver cost-effective taste replication in economy-tier offerings. Precision fermentation technology for natural flavor alternatives is compressing the cost gap with artificial equivalents.
Cocoa anchors premium positioning. The fastest volume shift is occurring in Corn Syrup as manufacturers navigate sugar taxation exposure.
Distribution Channel:
Customer type and purchase occasion vary sharply across channels, with impulse frequency and basket composition driving divergent packaging and pricing strategies.
- Grocery Stores:Seasonal aisle displays and checkout lane fixtures sustain volume for established brands through planned and unplanned purchase integration. Slotting fee structures disadvantage mid-tier entrants without vertical scale.
- E-commerce:Direct-to-consumer subscription models bypass traditional grocery trade spending and build recurring revenue through curated monthly boxes. Affluent coastal metro markets in the United States show highest willingness-to-pay for convenience premiumization.
- Convenience Stores:Self-checkout and mobile-order integration are enabling impulse purchase data capture and personalization in US c-store networks. USDA-inspected dairy components secure preferential placement for milk chocolate variants.
- Specialty Shops:Artisan positioning and localized flavor innovation command price premiums through experiential retail formats. Quebec and British Columbia present whitespace for premium concepts in underpenetrated Canadian markets.
Grocery Stores retain the volume base. E-commerce is climbing the fastest as subscription behavior consolidates household purchasing.
Consumer Age Group:
Maturity of consumption patterns and regulatory exposure shape targeting strategies, with adult segments offering functional positioning premiums and children's segments facing marketing restriction risk.
- Adults:Vitamin fortification and adaptogenic ingredient acceptance enables premium pricing through wellness-positioned chocolate and gummy formats. Precision fermentation cocoa butter alternatives appeal to ethically motivated purchasers in this cohort.
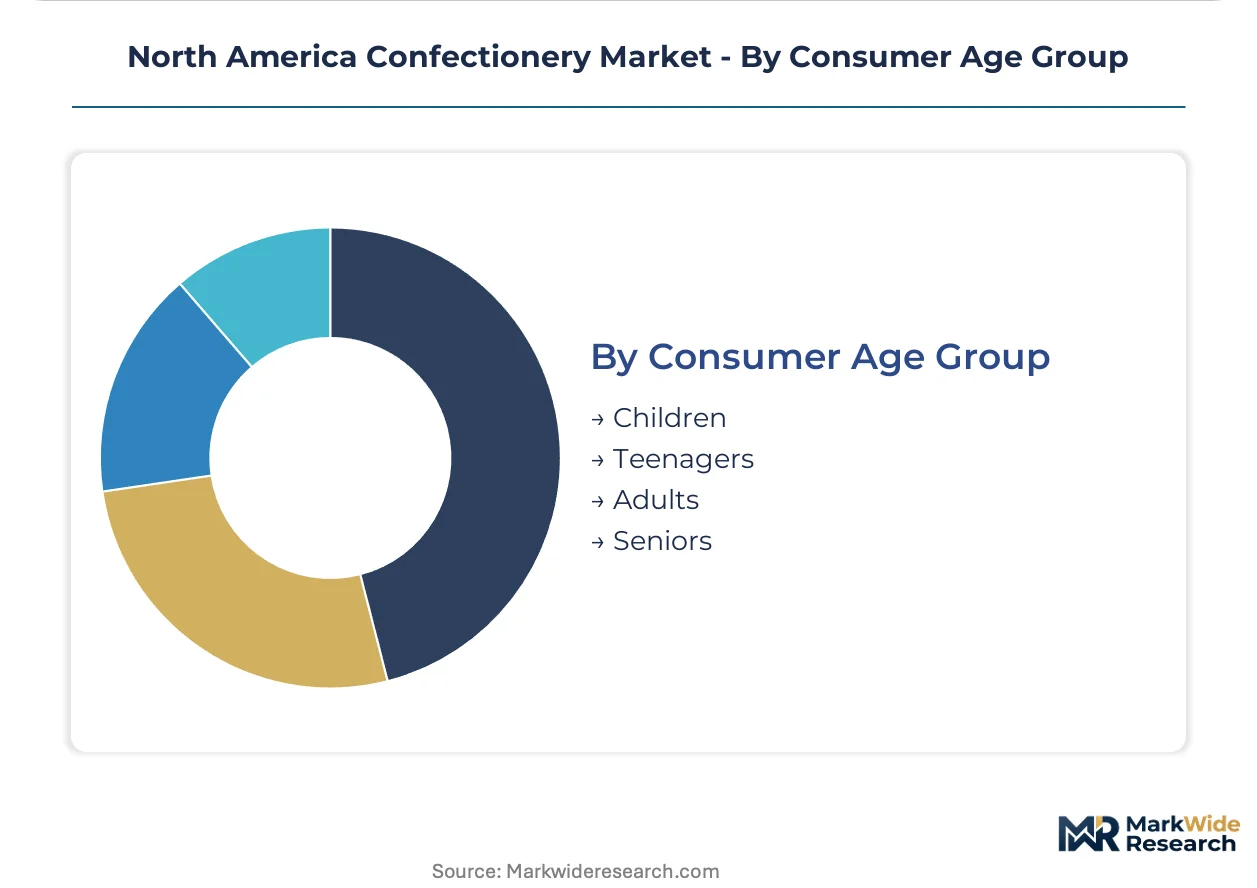
- Children:Sugar confectionery in portion-controlled formats remains the core volume driver despite school nutrition policy constraints. FDA nutrition labeling requirements for added sugars are pressuring reformulation in products targeting this segment.
- Teenagers:Snacking-confectionery hybrid formats and social media-native brand discovery patterns concentrate demand in digital-first channels. E-commerce platforms with influencer integration capture disproportionate engagement.
- Seniors:Texture-modified and sugar-reduced formulations address chewing difficulty and glycemic management requirements. Functional ingredient claims accelerate trial in this health-motivated demographic.
Adults command the established base. The steepest expansion runs through Seniors as aging demographics expand the addressable market for health-positioned formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian cocoa butter alternatives flow southward into United States manufacturing plants, while Mexican sugar derivatives support cross-border confectionery formulation. This trinational trade corridor sustains integrated North American supply chains.
United States
Convenience store digitization and seasonal gifting traditions drive volume concentration in the Southeast and Midwest. FDA added-sugar labeling mandates force reformulation across milk chocolate portfolios. Pennsylvania's chocolate manufacturing corridor anchors bean-to-bar processing capacity for domestic mass retail channels.
Canada
Quebec and British Columbia present whitespace for premium positioning and localized flavor innovation targeting adult wellness segments. Health Canada natural health product licensing pathways accelerate vitamin-fortified gummy launches. Toronto's food technology cluster incubates precision fermentation startups for cocoa butter alternatives.
Mexico
Cross-border sugar and cocoa derivative exports supply United States confectionery manufacturers with cost-advantaged inputs. Mexican federal food safety regulations align with FDA import requirements for seamless northbound trade. Monterrey's industrial corridor concentrates contract manufacturing for private-label chocolate brands.
North America Confectionery Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated cocoa processors and diversified snacking conglomerates with confectionery divisions. Three archetypes dominate: bean-to-bar chocolate specialists controlling upstream supply, mass-market portfolio players leveraging retail slotting power, and snacking-confectionery hybrid innovators capturing permissible indulgence occasions. Competitive moves center on precision fermentation technology licensing and direct-to-consumer subscription platform acquisitions.
Within the integrated chocolate tier, Mars Incorporated and The Hershey Company exemplify divergent scale strategies. Mars Incorporated represents captive supply chain control from West African sourcing through North American manufacturing. The Hershey Company anchors mass retail channel dominance through century-old distributor relationships and seasonal aisle fixtures. Mondelēz International occupies the snacking-confectionery hybrid position, extending portfolio reach beyond traditional sweets into permissible indulgence formats.
| Leading Market Players |
|---|
| Mars Incorporated |
| The Hershey Company |
| Mondelēz International Inc. |
| Ferrero International SA |
| Chocoladefabriken Lindt & Sprüngli AG |
| Nestlé SA |
| Perfetti Van Melle BV |
| HARIBO Holding GmbH & Co. KG |
| General Mills Inc. |
| Others |
Value Chain & Pricing Dynamics
West African cocoa bean concentration in Ghana and Côte d'Ivoire anchors input cost volatility that cascades into margin pool distribution across North American chocolate tiers. Manufacturers with captive supply chains capture differential pricing power against spot-market dependent competitors.
Pricing Analysis
Precision fermentation-derived cocoa butter alternatives are compressing the technology-generation pricing gap between biosynthetic and commodity-derived inputs. Three-tier pricing structure across premium bean-to-bar, standard mass-market, and economy private-label tiers persists, with certification grade and vertical integration serving as primary differentiation drivers. Cost compression in the standard tier is intensifying because FDA added-sugar reformulation mandates are layering compliance expenses onto already thin margins. Convenience store buyers exhibit highest price sensitivity, while direct-to-consumer subscription purchasers show lowest elasticity.
Supply Chain Analysis
Contract manufacturing concentration in Monterrey's industrial corridor and Toronto's food technology cluster holds capacity for private-label and precision fermentation scale-up. Geographic supply draws from West African cocoa, Mexican sugar derivatives, and Canadian dairy components processed under USDA-inspected protocols. Single-source vulnerability in West African bean sourcing exposes the chain to weather-driven disruption and currency fluctuation. Distribution runs through mass retail grocery channels, though e-commerce subscription platforms are capturing fastest growth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American confectionery is cycling through a recovery phase as post-reformulation compliance costs stabilize and precision fermentation inputs reach cost parity. Cocoa price normalization following supply chain investments provides the cyclical driver.
For Market Incumbents: Build captive supply moats through backward integration into precision fermentation capacity and West African origin partnerships. Mars Incorporated's bean-to-bar model demonstrates defensibility against commodity volatility. Secure FDA-compliant reformulation pipelines to preempt sugar taxation exposure in California and New York.
For New Entrants and Emerging Players: Build out direct-to-consumer subscription infrastructure targeting affluent coastal metros where convenience premiumization commands highest willingness-to-pay. Quebec and British Columbia present whitespace for premium positioning with localized flavor innovation. Health Canada natural health product licensing offers a regulatory-fast-tracked go-to-market angle for vitamin-fortified gummies.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation-enabled manufacturing as equipment costs amortize and yield curves improve. Long-term viability favors platforms with hybrid manufacturing capabilities spanning biosynthetic and traditional inputs. Acquisition targets should demonstrate subscription revenue traction or Health Canada licensing progress. Monitor cocoa futures spreads against precision fermentation input costs as the key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Biosynthetic cocoa butter alternatives from Toronto startups are decoupling production from West African commodity volatility. |
| Direct-to-Consumer Platform Launch | Subscription models bypass grocery slotting fees and lock in recurring revenue through curated monthly boxes. |
| Health Canada Licensing Pathway | Natural health product approvals accelerate vitamin-fortified gummy launches targeting adult wellness segments. |
| Convenience Channel Digitization | Self-checkout and mobile-order integration in US c-stores enables impulse purchase data capture and personalization. |
| Backward Integration into Origin Supply | Captive West African sourcing secures preferential bean access and hedges against weather-driven price spikes. |
Study Parameters
A standing panel of confectionery R&D directors, retail category buyers, supply chain planners, and regulatory affairs specialists provided ongoing calibration across the study period. Primary interviews with formulation scientists at bean-to-bar manufacturers and procurement leads at mass-market brands were cross-referenced against secondary validation from FDA guidance documents, USDA dairy grading protocols, Health Canada natural health product databases, and Nielsen retail audit data. Bottom-up volume modeling and top-down value reconciliation were triangulated to ensure consistency.
Scenario-bracketing around cocoa price volatility bands and sugar taxation implementation timelines framed the analytical envelope across the projection horizon. Segmentation dimensions modeled include product type, ingredient sourcing strategy, distribution channel, and consumer age cohort. CAGRs were derived from trend extrapolation against historical elasticity patterns, with precision fermentation adoption curves and FDA compliance cost trajectories serving as industry-specific forecast inputs.
Stress conditions across West African supply disruption, California sugar tax passage, and precision fermentation yield shortfalls were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timelines and technology cost curves. Quarterly review of cocoa futures spreads, Health Canada licensing velocity, and c-store digitization adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Vegan Gummy Candy Market
Confectionery
Low Calorie Sweets Market
Confectionery
Mooncake Market
Confectionery
Green Tea Chocolate Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
South Africa Confectionery Market
Confectionery
Diet Candy Market
Confectionery
Global Confectionery Market
Confectionery
Brazil Chocolate Market
Confectionery
North America Chocolate Confectionery Market
Confectionery
Gum Base Candy Market
Confectionery
India Industrial Chocolate Market
Confectionery
Milk Chocolate Market
Confectionery
Cocoa and Chocolate Market
Confectionery
Low-Calorie Chocolate Market
Confectionery
Organic Chocolate Confectionery Market