
 Low Calorie Keto Desserts Market | 2026-2036
Low Calorie Keto Desserts Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Keto Desserts Market Analytics
Precision fermentation and enzymatic modification of alternative proteins is reconfiguring how manufacturers achieve creamy textures without lactose or excess carbohydrates. Halo Top leverages its distributed manufacturing footprint to sustain rapid replenishment cycles in conventional grocery freezers. ChocZero anchors its competitive position through in-house production of monk fruit-sweetened chocolate coatings, bypassing commodity cocoa supply volatility.
Low calorie keto desserts constitute formulated food products containing fewer than 150 calories per serving while maintaining net carbohydrate content below 5 grams, typically achieved through sugar alcohol blends, resistant starches, and high-fat dairy or coconut-based carriers designed to sustain ketosis. The category serves consumers managing metabolic health, weight, or glycemic response through carbohydrate restriction. Ice cream and bakes currently occupy the largest volume positions, though puddings demonstrate the steepest growth trajectory as single-serve formats penetrate meal prep services and subscription channels. Sweeteners command disproportionate margin attention as erythritol supply constraints and monk fruit extraction bottlenecks create pricing power for vertically integrated ingredient suppliers.
The FDA governs net carbohydrate disclosure and sugar alcohol metabolization claims under Nutrition Facts panel regulations, while the USDA Organic certification shapes premium positioning for dairy alternative and coconut-derived ingredient streams. State-level cottage food laws and commercial kitchen licensing requirements create fragmented market access barriers for emerging brands seeking direct-to-retail distribution. Stakeholders must monitor evolving FDA guidance on allulose caloric valuation and emerging state legislation around ultra-processed food taxation, as these regulatory vectors will determine which ingredient platforms retain cost-competitive formulation viability.
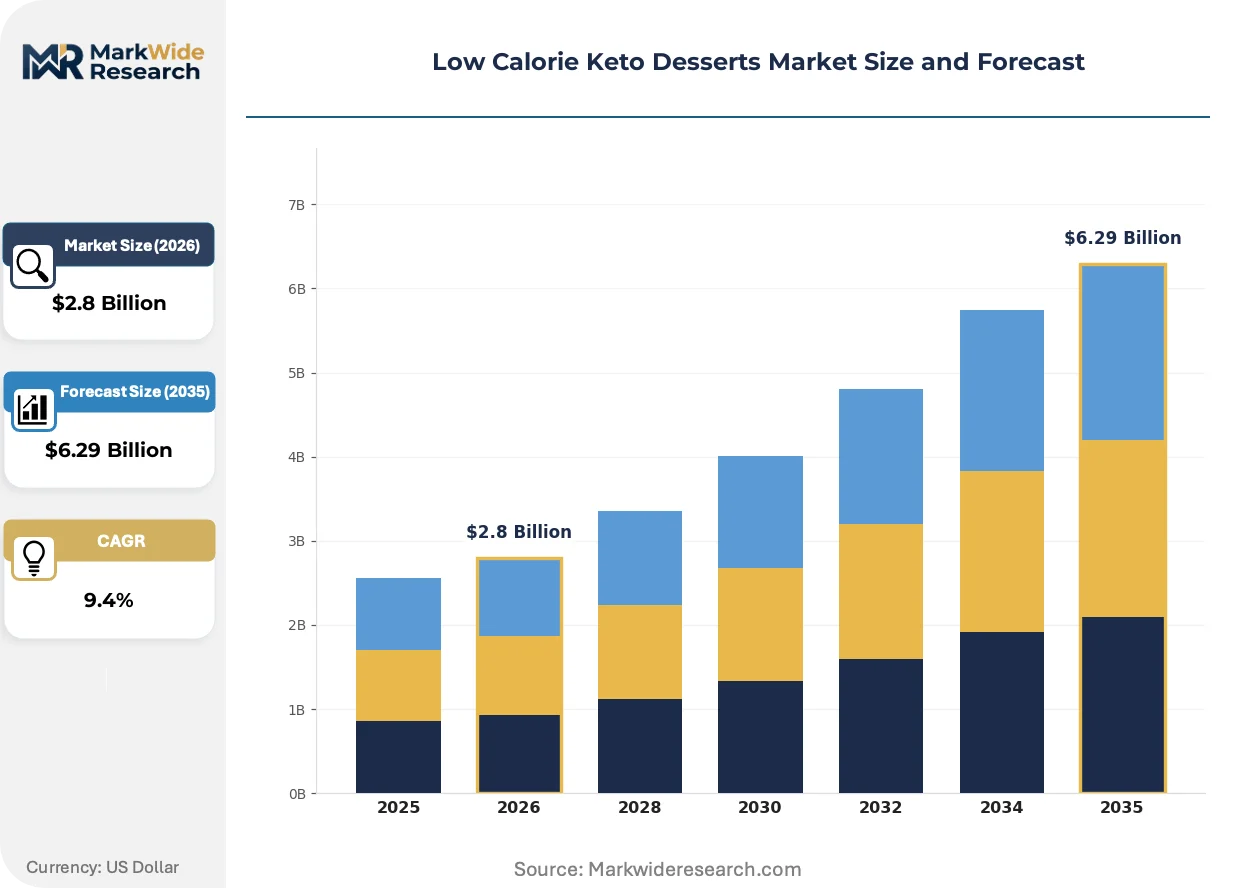
Market Dynamics
The FDA's updated Nutrition Facts labeling requirements for added sugars and net carbohydrates have forced systematic reformulations across the category, compressing formulation cycles and reshaping ingredient sourcing priorities for manufacturers.
Growth Catalysts
- Meal Prep Services:Subscription-based nutrition platforms now represent the fastest-expanding end-use channel as consumers prioritize convenience-aligned dietary adherence.
- Precision Fermentation:Enzymatic modification of alternative proteins enables creamy textures without lactose or excess carbohydrates, opening new formulation possibilities.
- US Ketogenic Diet Penetration:Specialty retail shelf space and consumer adherence rates in the United States outpace other national markets, concentrating demand visibility.
Market Restraints
- Erythritol Supply Constraints:Sugar alcohol supply bottlenecks create input cost volatility and limit production scale-up for mid-tier manufacturers.
- Monk Fruit Extraction Bottlenecks:Vertically integrated ingredient suppliers command pricing power due to concentrated extraction capacity in specific growing regions.
- FDA Allulose Guidance Uncertainty:Evolving caloric valuation rules for alternative sweeteners create regulatory friction and formulation risk.
Strategic Opportunities
- Pudding Single-Serve Formats:This segment demonstrates the steepest growth trajectory as penetration into meal prep services and subscription channels accelerates.
- USDA Organic Certification:Premium positioning for dairy alternative and coconut-derived ingredient streams creates margin expansion potential in certified product lines.
- State Cottage Food Law Variation:Fragmented commercial kitchen licensing requirements create white space for direct-to-retail distribution in permissive jurisdictions.
Industry Challenges
- Refrigerated Supply Chain Reconfiguration:Rapid replenishment cycles in conventional grocery freezers demand capital-intensive cold-chain infrastructure investments.
- Net Carbohydrate Disclosure Compliance:FDA Nutrition Facts panel regulations require specialized analytical capabilities and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Keto Desserts Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bakes, Ice Cream, Puddings, Cookies End User: Retail Consumers, Bakeries, Cafes, Meal Prep Services Ingredient Type: Sweeteners, Flours, Dairy Alternatives, Flavorings Packaging Type: Boxes, Pouches, Single Servings, Containers |
| Companies Covered | SlimFast, Atkins, Lily's Sweets, Halo Top, Bhu Foods, ChocZero, Russell Stover, Keto Pint, Rebel Creamery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Keto Desserts Market Evolving Landscape
Enzymatic processing and alternative protein engineering are compressing traditional formulation timelines while regulatory pressure on sugar disclosure accelerates ingredient platform turnover.
Precision fermentation of dairy-identical proteins is rendering obsolete conventional high-fat dairy carriers in keto dessert formulations. Mid-size manufacturers are adopting these platforms at accelerating pace to bypass lactose supply constraints. The technology is rendering obsolete legacy reliance on coconut cream and heavy cream bases that previously dominated texture engineering.
REACH regulations in Europe and FDA guidance evolution in the United States are tightening disclosure requirements for sugar alcohol metabolization claims. Industrial consequence includes mandatory reformulation of products relying on undisclosed polyol blends. Ice cream and frozen dessert categories are most affected, with European manufacturers accelerating clean-label transitions ahead of compliance deadlines.
Direct-to-consumer subscription models are displacing conventional retail stocking agreements as the primary volume pathway for emerging brands. Meal kit aggregators and specialized nutrition platforms are capturing shelf-space decision-making power from traditional grocery buyers. This shift concentrates most visibly in United States metropolitan markets where ketogenic diet adherence correlates with digital-native purchasing behavior.
Low Calorie Keto Desserts Market Segmentation
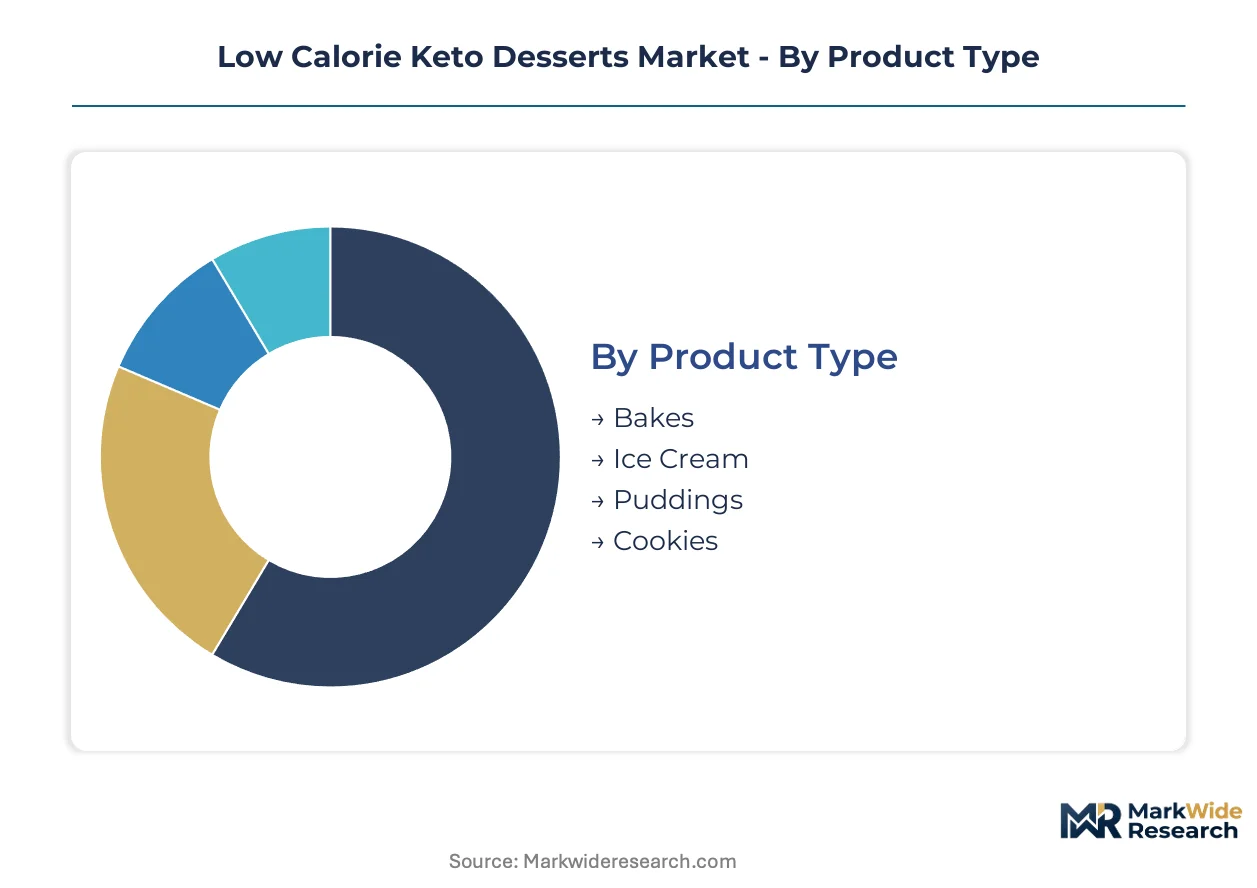
Segmentation in low calorie keto desserts determines formulation priorities, cold-chain requirements, and regulatory compliance pathways. Product architecture and packaging format choices directly shape shelf stability, net carbohydrate disclosure precision, and distribution channel viability.
Product Type:
After-sales service intensity varies sharply across product formats, with frozen categories demanding temperature-controlled logistics support and baked goods requiring freshness guarantees.
- Ice Cream:High-fat emulsions stabilized with erythritol and allulose blends dominate this segment. US specialty retail freezers allocate disproportionate shelf space to single-serve pints as ketogenic diet adherence concentrates in metropolitan markets.
- Puddings:Single-serve cups leveraging resistant starches and precision-fermented proteins are penetrating meal prep services fastest. Subscription channel volume is climbing as consumers prioritize convenience-aligned portion control.
- Bakes:Almond flour and coconut flour bases with monk fruit sweetening serve bakery and cafe wholesale accounts.
- Cookies:Portion-controlled formats with sugar alcohol blends target direct-to-consumer ecommerce.
By volume, Ice Cream leads. By growth pace, Puddings is ahead.
End User:
Cost tier stratification separates premium subscription platforms from conventional retail, with ingredient certification grade and packaging sophistication determining price positioning.
- Meal Prep Services:Subscription-based nutrition platforms specify exacting macronutrient ratios and portion consistency. This channel is expanding most quickly as digital-native consumers prioritize automated dietary adherence.
- Retail Consumers:Conventional grocery and ecommerce purchases concentrate in US coastal metropolitan areas with highest ketogenic diet penetration rates.
- Bakeries:Wholesale accounts demand bulk formats with extended ambient stability for pastry case display.
- Cafes:Grab-and-go dessert specifications emphasize visual appeal and rapid thaw characteristics.
Meal Prep Services commands premium pricing. Retail Consumers delivers aggregate volume scale.
Ingredient Type:
Supply concentration for monk fruit extraction and erythritol fermentation capacity creates input cost volatility that cascades through finished product margins.
- Sweeteners:Erythritol, allulose, and monk fruit blends enable sub-5g net carbohydrate targets. FDA allulose caloric valuation uncertainty is forcing dual-sweetener formulations as risk mitigation.
- Flours:Almond, coconut, and resistant starch alternatives replace wheat-based carriers. USDA Organic certification for nut-derived inputs commands 15-25% ingredient cost premiums.
- Dairy Alternatives:Precision-fermented dairy-identical proteins are displacing coconut cream bases. Enzymatic modification enables creamy textures without lactose carbohydrates.
- Flavorings:Natural extract and in-house compound development differentiates premium positioning from commodity taste profiles.
Sweeteners absorb disproportionate R&D attention. Dairy Alternatives is gaining share fastest through biotechnology substitution.
Packaging Type:
Maturity gradients separate established box formats from emerging sustainable pouch innovations, with barrier properties and recyclability driving capital allocation.
- Single Servings:Portion-controlled cups and bars dominate meal prep service specifications. This format is expanding most quickly as subscription channels displace conventional retail stocking.
- Containers:Multi-serve tubs serve family households and foodservice accounts with cost-per-ounce efficiency.
- Boxes:Rigid formats protect fragile baked goods through direct-to-consumer shipping.
- Pouches:Flexible films with high oxygen barriers are emerging for cookie and bar formats seeking shelf-stable distribution.
Single Servings leads on growth trajectory. Containers retains volume concentration in conventional retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US manufacturers export precision-fermented dairy proteins and monk fruit sweeteners to European and Asia-Pacific formulators seeking clean-label keto bases. Canada and Mexico serve as secondary demand corridors for US-branded finished goods.
United States
Metropolitan coastal markets concentrate ketogenic diet adherence and specialty retail freezer allocation. FDA Nutrition Facts labeling mandates on net carbohydrates drive reformulation investments. Austin and Denver clusters host emerging precision-fermentation facilities supplying dairy-alternative bases to dessert manufacturers.
Germany
REACH regulations on sugar alcohol metabolization claims accelerate clean-label transitions ahead of compliance deadlines. EFSA guidance on novel food ingredients shapes allulose import and formulation decisions. Berlin and Munich house the largest European keto-focused direct-to-consumer subscription platforms.
United Kingdom
Meal prep service penetration correlates with London's digital-native consumer density and premium nutrition subscription growth. FSA enforcement of added-sugar disclosure tightens labeling requirements for imported US formulations. Manchester and Bristol emerging brands leverage cottage food law variations for direct retail access.
Canada
Health Canada novel food approvals for precision-fermented proteins lag FDA timelines, creating regulatory arbitrage for US ingredient imports. Toronto and Vancouver metropolitan areas concentrate specialty retail shelf space and ketogenic diet adherence. British Columbia's commercial kitchen licensing framework enables emerging brand market entry.
Australia
TGA novel ingredient assessments for alternative sweeteners create approval bottlenecks limiting product variety. Sydney and Melbourne clusters drive meal prep service demand and subscription channel growth. Queensland's monk fruit extraction investments aim to reduce Asia-Pacific supply concentration.
Low Calorie Keto Desserts Market Competitive Landscape
On the supply side, the industry is bifurcated between mass-market frozen dessert specialists and niche direct-to-consumer formulators. Tiered competitive dynamics separate premium precision-fermentation adopters from commodity coconut-cream reliant producers. Strategic archetypes include vertically integrated sweetener producers, distributed manufacturing networks, and subscription-native digital brands. Dominant competitive moves encompass captive supply of monk fruit extraction capacity and rapid replenishment cycle investments in conventional grocery cold chains.
Among US-based formulators, Halo Top and ChocZero exemplify divergent supply-side strategies. Halo Top occupies a position anchored in distributed manufacturing footprints enabling rapid retail replenishment. ChocZero represents backward integration into in-house monk fruit-sweetened chocolate production, insulating margin exposure to commodity cocoa volatility. SlimFast and Atkins sit within legacy weight-management brand architectures now pivoting toward ketogenic macronutrient specifications.
| Leading Market Players |
|---|
| SlimFast |
| Atkins |
| Lily's Sweets |
| Halo Top |
| Bhu Foods |
| ChocZero |
| Russell Stover |
| Keto Pint |
| Rebel Creamery |
| Others |
Value Network & Pricing Analysis
Refrigerated freight corridors connecting California's Central Valley monk fruit extraction facilities to Midwest distribution hubs impose cost dynamics that amplify supply concentration effects. These logistics premiums cascade into three-tier pricing structures separating USDA Organic certified premium lines from conventional formulations, while commodity sweetener spot markets exert downward pressure on economy-tier positioning.
Pricing Analysis
Precision-fermentation protein pricing gaps separate incumbent dairy-alternative adopters from legacy coconut-cream reliant producers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in standard tiers is intensifying because erythritol supply bottlenecks force dual-sweetener formulations. Meal prep services exhibit lowest price sensitivity due to macronutrient specification rigidity, while conventional retail consumers demonstrate highest elasticity.
Supply Chain Analysis
USDA and FDA novel-food approval frameworks function as de facto export controls limiting precision-fermented protein flows into Canada and Australia. Supply concentrates in United States precision-fermentation facilities, Chinese erythritol fermentation capacity, and Southeast Asian monk fruit extraction zones. Raw material dependencies span monk fruit concentrate, erythritol granules, and precision-fermented dairy-identical proteins. Single-source vulnerability in monk fruit extraction creates structural risk. Distribution runs through cold-chain logistics networks serving conventional grocery freezers and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around FDA Nutrition Facts compliance creates durable barriers. Switching costs for reformulation and analytical documentation systems protect incumbent positions against agile challengers.
For Market Incumbents: Build captive supply moats through backward integration into monk fruit extraction capacity or precision-fermentation protein production. Secure rapid replenishment cycle agreements with conventional grocery freezer operators to defend shelf space against emerging digital-native brands. FDA allulose caloric valuation uncertainty demands dual-sweetener R&D investment as regulatory hedge. For New Entrants and Emerging Players: Build out direct-to-consumer subscription capabilities targeting metropolitan coastal markets with highest ketogenic diet adherence. Exploit state cottage food law variations in permissive jurisdictions for white-space retail access. White space concentrates in pudding single-serve formats penetrating meal prep services fastest. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy weight-management brand architectures pivoting toward ketogenic specifications. Five-to-ten year viability hinges on biotechnology substitution rates in dairy-alternative ingredient streams. Signal to monitor: FDA final allulose caloric valuation guidance as inflection trigger for formulation platform winners.| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Fermentation Protein Adoption | Enables creamy textures without lactose carbohydrates, displacing coconut cream bases. |
| Monk Fruit Extraction Backward Integration | Insulates margin exposure to concentrated Asia-Pacific supply bottlenecks. |
| Meal Prep Service Channel Expansion | Captures fastest-growing end-use segment with premium pricing power. |
| USDA Organic Certification Investment | Commands 15-25% ingredient cost premiums in certified product lines. |
| Single-Serve Pudding Format Development | Accelerates penetration into subscription channels displacing conventional retail. |
Research Methodology
The analysis maps ice cream, pudding, bakes, and cookies sub-sectors, each validated through product development directors, retail category buyers, meal prep service procurement leads, and precision-fermentation facility operators. Primary interview findings triangulate against FDA guidance documents, USDA Organic certification databases, Nielsen retail audit data, and customs import records for monk fruit and erythritol. Bottom-up volume modeling and top-down market sizing converge through iterative reconciliation.
Assumptions held fixed include FDA Nutrition Facts labeling requirements, state cottage food law frameworks, and precision-fermentation protein cost curves. Variables stress-tested span erythritol supply elasticity, monk fruit harvest yields, and allulose caloric valuation scenarios. Segmentation dimensions modeled encompass product type, end-user channel, ingredient platform, and packaging format across the projection horizon. CAGRs derive from regression analysis against ketogenic diet adherence indices and specialty retail freezer expansion rates.
Stress conditions across sweetener supply disruptions, regulatory approval delays, and cold-chain cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about biotechnology substitution timelines and subscription channel penetration curves. Material shifts in FDA allulose guidance or REACH sugar alcohol metabolization rules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
South Korea Chocolate Market
Confectionery
Gummy Market
Confectionery
White Chocolate Market
Confectionery
South America Compound Chocolate Market
Confectionery
UK Chocolate Market
Confectionery
Brain Mint Market
Confectionery
Chocolate, Cocoa Beans, Lecithin, Sugar and Vanilla Market
Confectionery
Middle East and Africa Chocolate Market
Confectionery
Global Confectionery Market
Confectionery
Europe Confectionery Market
Confectionery
Caramel Chocolate Market
Confectionery
North-American Industrial Chocolate Market
Confectionery
Middle-East and Africa Compound Chocolate Market
Confectionery
Mooncake Market
Confectionery
China Cakes, Pastries, & Sweet Pies Market
Confectionery
Europe Caramel Chocolate Market