
 Sugar-Free Chocolate Market | 2026-2036
Sugar-Free Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar-Free Chocolate Market Analysis
Premium single-origin cocoa specifications is reorganizing competitive dynamics across the sugar-free chocolate category. Barry Callebaut leverages its integrated bean-to-bar infrastructure to secure consistent supply of high-grade cocoa mass for reduced-sugar formulations. Lindt & Sprüngli anchors its positioning through Swiss manufacturing heritage and precision conching techniques that preserve flavor depth without sucrose. Russell Stover Chocolates competes on accessible price points while sustaining broad retail distribution across North American drug and grocery channels.
Sugar-free chocolate denotes confectionery products formulated with cocoa-derived lipids and solid fractions where sucrose is wholly or partially replaced by polyols, rare sugars, or high-intensity sweeteners, typically maintaining below 0.5 grams sugars per serving to comply with diabetic and low-glycemic labeling protocols. The production sequence involves alkalization, refining to particle sizes below 20 microns, and controlled tempering to achieve stable polymorph V crystal structures that deliver snap and gloss comparable to conventional chocolate. Bars and snack bites command the largest volume positions, though truffles carry disproportionate margin pools due to gift-oriented purchasing and artisanal positioning. Sugar substitutes as an ingredient segment is gaining fastest traction as allulose, monk fruit extract, and erythritol blends displace earlier maltitol-dominant formulations that carried laxation liabilities.
FDA nutrition labeling rules and EFSA health claims frameworks jointly pressure manufacturers to substantiate glycemic response assertions and net carbohydrate declarations. The EU Green Deal's deforestation due diligence requirements and REACH chemical safety standards further constrain cocoa sourcing and additive selection for products entering European markets. Stakeholders must monitor evolving sweetener approval pipelines and origin traceability mandates to preserve formulation flexibility and market access across regulatory jurisdictions.
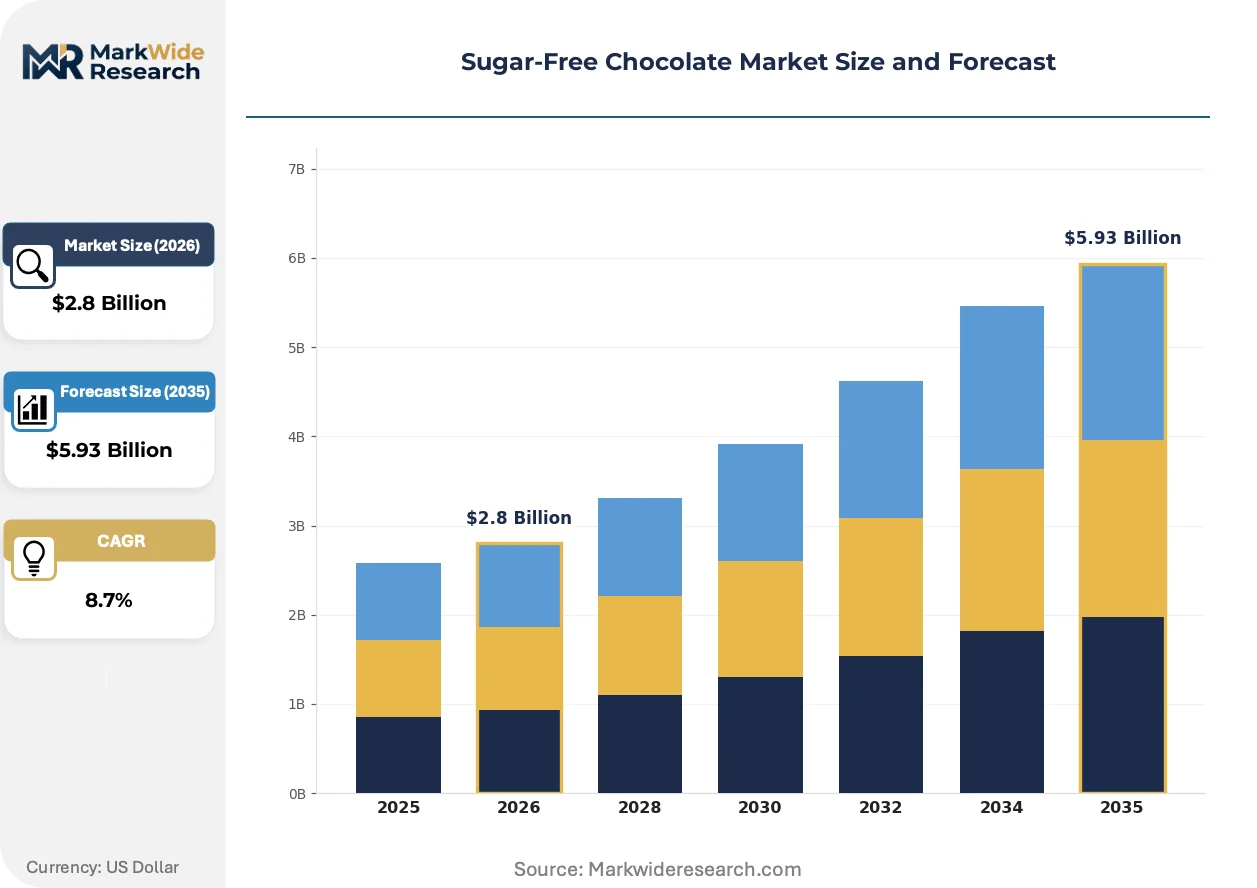
Market Dynamics
Clean-label sweetener approvals by FDA and EFSA are forcing rapid reformulation across the sugar-free chocolate category, compressing development cycles and redrawing competitive boundaries between polyol-dependent incumbents and rare-sugar innovators.
Growth Catalysts
- Diabetic Consumer Expansion:Rising prevalence of type 2 diabetes in Germany, Switzerland, and Belgium is pulling pharmaceutical retail channels toward dedicated sugar-free confectionery sections.
- EFSA Health Claims Framework:Validated low-glycemic indexing enables premium positioning and substantiated packaging claims that command shelf price premiums.
- Allulose Commercialization:FDA GRAS status for this rare sugar is displacing maltitol in North American formulations, eliminating laxation warnings that constrained repeat purchase.
Market Restraints
- Cocoa Butter Price Volatility:Concentrated West African supply exposes margins to weather-driven input cost spikes that resist pass-through in mass-market tiers.
- EU Deforestation Due Diligence:The EU Green Deal's traceability mandates impose compliance burdens on small-batch chocolatiers lacking bean-to-bar documentation systems.
- Polyol Digestive Tolerance Ceiling:Consumer sensitivity to erythritol and maltitol limits inclusion rates, constraining sweetness intensity without sucrose.
Strategic Opportunities
- Indian Urban Premium Retail:FSSAI's evolving standards for sugar claims create first-mover positioning in Mumbai and Delhi specialty food channels.
- Monk Fruit-Erythritol Convergence:Blending high-intensity natural extracts with bulk polyols achieves clean-label taste profiles unavailable through single-ingredient solutions.
- Direct-to-Consumer Subscription:Specialty chocolate clubs bypass conventional grocery slotting fees, capturing lifetime value from keto and diabetic lifestyle adherents.
Industry Challenges
- Confectionery Technologist Scarcity:Formulation expertise spanning cocoa chemistry and sweetener synergy remains concentrated among retiring European specialists.
- Polymorph V Tempering Capital Requirements:Precision tempering equipment for stable crystal formation demands seven-figure investment per production line.
- Multi-Jurisdiction Labeling Complexity:Divergent FDA and EFSA net carbohydrate calculation methods force SKU proliferation or lowest-common-denominator formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar-Free Chocolate Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bars, Truffles, Coated Nuts, Snack Bites Ingredient Type: Cocoa Solids, Sugar Substitutes, Dairy Ingredients, Emulsifiers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops End User: Fitness Enthusiasts, Diabetics, Health-Conscious Consumers, Gourmet Chocolatiers |
| Companies Covered | Barry Callebaut, Russell Stover Chocolates, The Hershey Company, Ferrero, Nestlé, Lindt & Sprüngli, Godiva Chocolatier, Ghirardelli Chocolate Company, Mondelēz International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar-Free Chocolate Market Emerging Trajectories
Formulation science is converging with precision fermentation and regulatory chemistry to redefine what sugar-free chocolate can deliver on taste, texture, and metabolic claim substantiation.
Allulose production via enzymatic conversion of fructose is displacing maltitol as the dominant bulk sweetener in North American sugar-free chocolate. Diabetic and keto-aligned consumers are migrating toward brands featuring this rare sugar on front-of-pack. The shift is compressing demand for traditional polyol suppliers while opening formulation latitude previously blocked by digestive tolerance limits.
REACH chemical safety standards and the EU Green Deal's deforestation due diligence are reshaping additive selection and cocoa sourcing protocols for European market entry. Manufacturers must now document supply chain provenance to the plantation level and substitute certain processing aids. Mid-tier brands lacking traceability infrastructure face exclusion or costly reformulation to maintain continental distribution.
Specialty pharmacy and diabetic clinic channels are emerging as high-margin alternatives to conventional grocery retail for premium sugar-free chocolate. These healthcare-adjacent venues validate products through professional endorsement rather than shelf placement fees. Germany and Switzerland exhibit the most developed pharmacy confectionery sections, with Belgium's apothecary networks expanding comparable assortments.
Sugar-Free Chocolate Market Segmentation
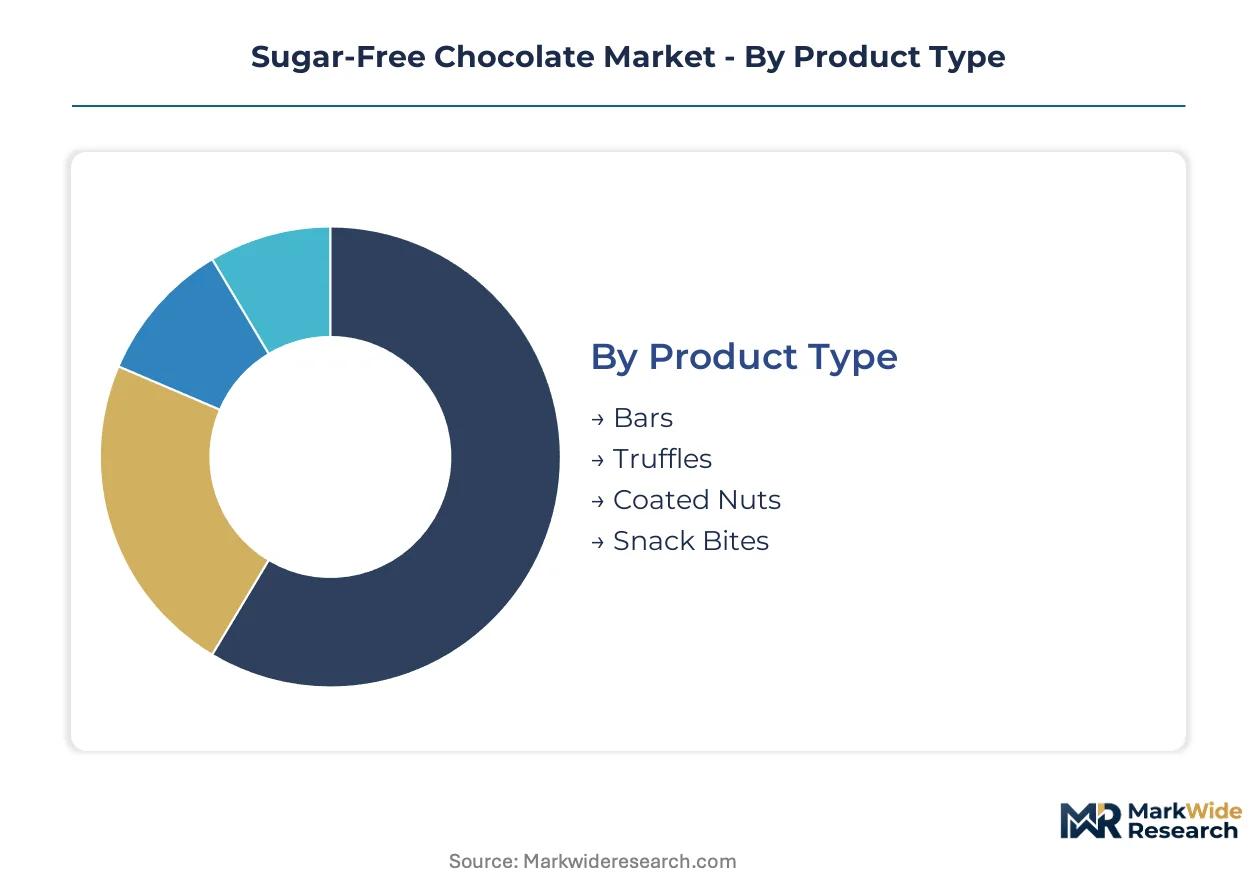
Sugar-free chocolate formulation varies sharply by regulatory jurisdiction, with FDA GRAS approvals and EFSA health claims frameworks dictating which sweetener systems qualify for specific product positionings. Segmentation clarity enables manufacturers to match technical specifications against channel requirements and metabolic labeling protocols.
Product Type:
FDA diabetic labeling thresholds and EFSA nutrition claims create divergent formulation targets across format categories, with serving-size regulations particularly constraining bite-sized portions.
- Bars:Standard 40-100 gram formats dominate retail shelf space and accommodate complete nutritional panels required for diabetic certification. German and Swiss supermarkets allocate dedicated planogram sections for clinically positioned bar formats. Established volume favors bars; emerging adoption favors truffles.
- Truffles:Ganache-centered spheres with cocoa butter shells achieve premium price multiples through gift-oriented purchasing and artisanal positioning. Belgian chocolatiers leverage truffle formats for pharmacy channel entry where professional endorsement validates metabolic claims.
- Coated Nuts:Almond and hazelnut substrates require modified tempering protocols to maintain polymorph V stability across irregular surfaces. Health food stores in Switzerland favor these for protein-positioned snacking.
- Snack Bites:Sub-10 gram portions navigate FDA single-serving rules but challenge net carbohydrate declaration precision. Keto subscription channels drive fastest volume expansion here.
Format selection directly determines which regulatory pathways—pharmacy endorsement versus mass retail—remain accessible to manufacturers.
Ingredient Type:
Cost tier stratification separates commodity bulk sweeteners from premium rare-sugar formulations, with price multiples of 3-5x between maltitol-dominant and allulose-based systems.
- Cocoa Solids:Alkalized and natural cocoa powders provide flavor foundation and antioxidant positioning. Swiss manufacturers specify Ghanaian and Ecuadorian origin for premium tier differentiation.
- Sugar Substitutes:Allulose, erythritol, and monk fruit extract blends displace legacy maltitol formulations, eliminating laxation warnings that constrained repeat purchase in North American diabetic segments. Steepest expansion trajectory sits here as FDA GRAS approvals accelerate.
- Dairy Ingredients:Milk powder and butterfat fractions require lactose-free verification for strict ketogenic positioning. German organic dairy supply chains command premium sourcing.
- Emulsifiers:Lecithin and polyglycerol polyricinoleate ensure viscosity control in reduced-sugar matrices where sucrose's bulk and water-binding functions are absent.
Ingredient portfolios are splitting between cost-optimized polyol systems for mass retail and rare-sugar formulations for premium positioning.
Distribution Channel:
Customer type concentration varies by channel, with healthcare-adjacent venues validating products through professional endorsement rather than shelf placement economics.
- Online Retail:Direct-to-consumer subscriptions capture lifetime value from keto and diabetic lifestyle adherents, bypassing conventional grocery slotting fees. Amazon and specialty health platforms dominate.
- Supermarkets:Conventional grocery requires trade spending for planogram placement, favoring scaled manufacturers with promotional budgets. German REWE and Swiss Migros operate dedicated sugar-free sections.
- Health Food Stores:Staff-curated assortments prioritize clean-label credentials and independent brand discovery. These channels tolerate higher price points for verified low-glycemic indexing.
- Specialty Shops:Bean-to-bar boutiques and pharmacy confectionery sections in Belgium and Switzerland emphasize provenance documentation and professional validation.
Channel mix determines margin structure, with specialty and online routes preserving premium positioning against supermarket price compression.
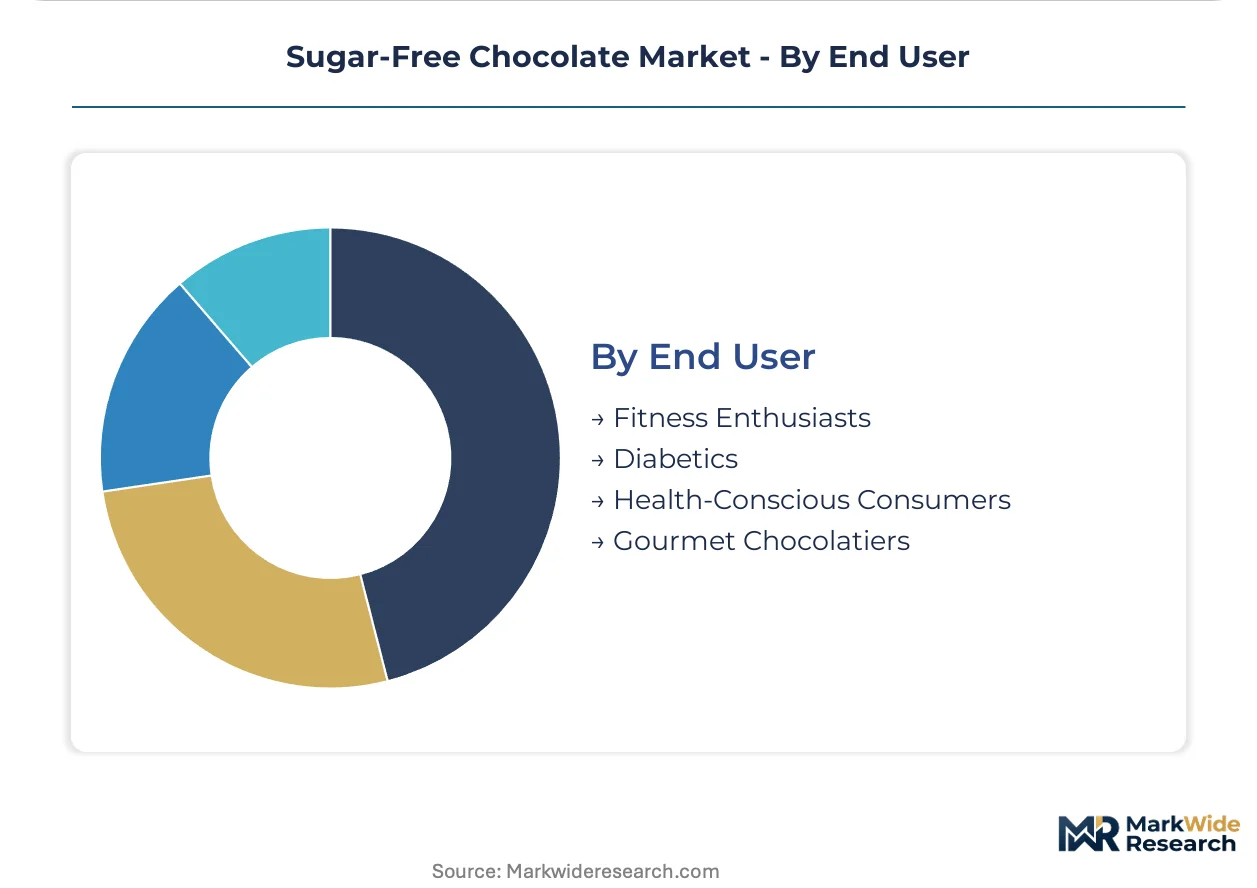
End User:
Maturity gradients separate clinically validated diabetic positioning from lifestyle-oriented wellness marketing, with regulatory substantiation requirements widening the gap.
- Fitness Enthusiasts:Protein-integrated and keto-aligned formats target macronutrient-tracking consumers through sports nutrition channels. This segment tolerates erythritol cooling effects for carbohydrate reduction.
- Diabetics:Clinically validated low-glycemic indexing enables pharmacy channel placement and healthcare professional recommendation. German and Belgian apothecary networks expand dedicated confectionery assortments.
- Health-Conscious Consumers:General wellness positioning emphasizes reduced sugar without strict metabolic protocols, competing in conventional retail against premium conventional chocolate.
- Gourmet Chocolatiers:Professional users source sugar-free couverture for artisanal applications, demanding tempering behavior parity with conventional chocolate.
User base is concentrating around diabetic clinical validation and keto lifestyle adherence, with general wellness positioning losing differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in sugar-free chocolate tilt toward net-importing developed markets where premium positioning commands shelf price premiums. Export capacity concentrates in established confectionery manufacturing clusters with integrated cocoa processing infrastructure. Regulatory divergence between FDA and EFSA frameworks fragments formulation standardization across Atlantic trade routes.
Germany
Pharmacy channel expansion and diabetic consumer density pull sugar-free chocolate into apothecary confectionery sections. The EU Green Deal's deforestation due diligence mandates traceability documentation to plantation level. Cologne and Hamburg harbor zones anchor cocoa bean import and alkalization processing for reduced-sugar formulations distributed across REWE and Aldi Süd networks.
United States
Keto lifestyle adherence and diabetic population scale sustain direct-to-consumer subscription growth bypassing grocery slotting economics. FDA GRAS approvals for allulose displace maltitol in reformulation cycles across North American portfolios. Pennsylvania's heritage chocolate corridor and California's precision food-tech cluster split manufacturing gravity between traditional conching and enzymatic rare-sugar conversion.
Switzerland
Precision conching heritage and Swissmedic-aligned quality protocols preserve premium positioning in pharmacy and specialty channels. REACH chemical safety standards constrain additive selection for formulations entering continental European distribution. Zurich and Vevey manufacturing basins supply Migros and Coop dedicated sugar-free planogram sections with bean-to-bar documentation.
Belgium
Gift-oriented truffle demand and artisanal positioning command margin multiples through pharmacy channel validation. EFSA health claims frameworks enable substantiated low-glycemic indexing on packaging for diabetic consumer segments. Brussels and Liège chocolate districts leverage EU regulatory proximity to shape formulation standards for continental market entry.
India
Urban premium retail expansion in Mumbai and Delhi creates first-mover positioning as FSSAI evolves sugar claim standards. Central bank liquidity measures and PLI scheme extensions indirectly support food processing infrastructure investment. Maharashtra and Karnataka specialty food channels trial imported sugar-free formats ahead of domestic manufacturing scale-up.
Sugar-Free Chocolate Market Vendor Landscape
Concentration sits with integrated cocoa processors and heritage confectionery houses that command bean-to-bar documentation systems. The vendor base splits between mass-market polyol-dependent formulators and rare-sugar innovators compressing development cycles. Three archetypes dominate: Swiss-German precision manufacturers with pharmacy channel access, North American scale players with retail distribution breadth, and bean-to-bar boutiques with traceability premiums. Competitive moves center on clean-label sweetener patent licensing and deforestation-compliant sourcing certification acquisition.
Within the integrated processor tier, Barry Callebaut anchors supply security for reduced-sugar formulations through captive cocoa mass infrastructure. Lindt & Sprüngli occupies the precision heritage position with Swiss manufacturing lineage and conching expertise. Russell Stover Chocolates represents accessible price-point penetration across North American drug and grocery channels. These three exemplify how geographic origin and corporate structure map onto divergent competitive vectors—Belgian-Swiss integration, Swiss precision heritage, and American retail scale.
| Leading Market Players |
|---|
| Barry Callebaut |
| Russell Stover Chocolates |
| The Hershey Company |
| Ferrero |
| Nestlé |
| Lindt & Sprüngli |
| Godiva Chocolatier |
| Ghirardelli Chocolate Company |
| Mondelēz International |
| Others |
Supply Flow & Price Mechanics
Ninety-day cocoa bean inventory cycles at European alkalization facilities compress margin buffers when West African harvest disruptions strike, binding pricing power to origin-traceability infrastructure and bean-to-bar documentation systems that command shelf price premiums in pharmacy and specialty channels.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in sugar-free chocolate procurement. Premium tiers extract multiples through Swissmedic-aligned certification and rare-sweetener formulations featuring allulose or monk fruit-erythritol blends. Price differentiation rests on clean-label credentialing and deforestation-compliant sourcing documentation. Cost compression in mass-market polyol-dependent tiers intensifies as maltitol formulations face consumer tolerance constraints. Diabetic clinic channels exhibit lowest price sensitivity; conventional grocery retail shows highest.
Supply Chain Analysis
Abidjan and Tema port congestion underwrites supply vulnerability for European sugar-free chocolate manufacturers dependent on Ghanaian and Ivorian cocoa bean flows. Raw material sourcing draws from West African cocoa cooperatives, Malaysian palm kernel fractions for cocoa butter equivalents, and Chinese erythritol fermentation capacity. Single-source vulnerability concentrates in alkalized cocoa powder supply where German and Swiss processors dominate. Distribution runs through integrated bean-to-bar processors, regional couverture distributors, and direct-to-consumer subscription platforms bypassing conventional retail slotting economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA GRAS acceleration for rare sugars and EFSA health claims validation are compressing formulation cycles, creating high-growth disruption as clean-label sweeteners displace legacy polyol systems.
For Market Incumbents: Fortify bean-to-bar traceability infrastructure to satisfy EU Green Deal deforestation due diligence mandates before compliance deadlines exclude mid-tier competitors. Secure captive allulose supply agreements through enzymatic conversion partnerships to defend margin position against rare-sugar supply bottlenecks.
For New Entrants and Emerging Players: Pharmacy channel curation gaps in North American diabetic retail present white-space entry points where professional endorsement substitutes for trade spending. Direct-to-consumer subscription models bypass grocery slotting fees while capturing lifetime value from keto lifestyle adherents through personalized formulation trials.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational confectionery parents seeking to divest non-core sugar-free portfolios lacking clean-label reformulation capabilities. Five-to-ten year viability favors rare-sweetener patent holders with FDA and EFSA approval pipelines. Monitor EFSA novel food authorization timelines as inflection indicator for formulation standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Sweetener Patent Licensing | Allulose and monk fruit extraction patents command formulation exclusivity in North American diabetic segments. |
| Bean-to-Bar Traceability Certification | EU Green Deal compliance documentation preserves continental market access for European pharmacy channels. |
| Direct-to-Consumer Subscription Launch | Keto and diabetic lifestyle clubs bypass conventional grocery slotting economics while building recurring revenue. |
| Precision Conching Capacity Expansion | Swiss manufacturing heritage investments sustain premium positioning through polymorph V crystal stability. |
| Pharmacy Channel Partnership | German and Belgian apothecary network placement validates metabolic claims through healthcare professional endorsement. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA GRAS notifications, EFSA novel food opinions, and cocoa trade customs data. Primary interviews engaged confectionery technologists, pharmacy category buyers, cocoa procurement directors, and regulatory affairs specialists across German, Swiss, Belgian, and North American markets. Secondary validation drew from EFSA health claims registers, EU deforestation due diligence guidance documents, and specialty chocolate retail audit panels. Bottom-up volume modeling triangulated against top-down value projections across ingredient type and distribution channel segments.
Segmentation dimensions modeled span product format, sweetener system composition, end-user metabolic positioning, and regional regulatory cluster across the projection horizon. CAGRs derive from growth rate convergence analysis applied to historic volume trajectories and forward-looking adoption curves for rare-sugar formulations. Forecast inputs incorporate FDA approval pipeline velocity for novel sweeteners and pharmacy channel expansion rates in German-speaking markets.
Forecasts assume regulatory continuity in FDA GRAS and EFSA novel food regimes; material policy shifts would require re-modeling. Cocoa price volatility, sweetener approval delays, and deforestation enforcement intensity constitute primary revision triggers. Revision becomes warranted when clean-label sweetener cost parity against polyols crosses threshold acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Crunchy Chocolate Market
Confectionery
Asia Pacific Sugar Confectionery Market
Confectionery
North-American Industrial Chocolate Market
Confectionery
Sugar-Free Gumballs Market
Confectionery
Mints Market
Confectionery
Saudi Arabia Chocolate Market
Confectionery
UK Compound Chocolate Market
Confectionery
Dark Chocolate Market
Confectionery
Asia-Pacific Sugar Free Chewing Gum Market
Confectionery
Middle East and Africa Premium Chocolate Market
Confectionery
Global Non-Cocoa Confectionery Market
Confectionery
Truffle Chocolate Market
Confectionery
Low-Calorie Dark Chocolate Market
Confectionery
Boiled-Cooked Icing Market
Confectionery
Vegan Gummy Candy Market
Confectionery
Ice Cream Coating Market