
 Mints Market | 2026-2036
Mints Market Size, Share, and Industry Trends Forecast 2026-2036
Mints Market Outlook
Convenience store distribution is tilting toward front-of-store placement and checkout-adjacent displays for impulse mint purchases. Wrigley leverages its refrigerated rack systems and cooler partnerships to sustain visibility in high-traffic retail zones. Ferrero International S.A. anchors its Tic Tac brand through compact format dominance in travel retail and vending channels. Perfetti Van Melle Holding B.V. competes on flavor innovation density, rolling limited-edition releases across multiple regional markets simultaneously.
Mints comprise compressed or molded confectionery products, typically incorporating sugar alcohols such as sorbitol or xylitol alongside natural or synthetic flavoring agents, designed primarily for oral refreshment and breath odor control. Manufacturing employs high-shear mixing, tablet compression, or deposited candy processes with controlled cooling curves to achieve hardness and dissolution profiles. Hard Candies and Breath Fresheners command the largest volume positions, though Soft Mints capture expanding margin pools through premium texture positioning and clean-label formulations. Pouch and Tin packaging formats are gaining structural share as portability and reusability align with on-the-go consumption patterns.
FDA food additive regulations and EFSA novel food assessments shape sweetener approval pathways and label claims across North American and European markets. FSSAI in India enforces maximum residue limits and packaging material standards that constrain import flexibility and local formulation choices. Stakeholders must monitor evolving sugar-tax legislation and front-of-pack labeling mandates, as these frameworks increasingly determine product viability and shelf placement economics in key retail channels.
Market Dynamics
Clean-label ingredient mandates and sugar-tax legislation are compressing formulation flexibility while front-of-pack labeling requirements reshape retail shelf economics across developed markets.
Growth Catalysts
- Front-of-pack labeling mandates:EU Green Deal nutrition scoring systems reward low-sugar formulations, incentivizing manufacturers to accelerate xylitol and stevia transitions in European markets.
- Travel retail channel expansion:Airport duty-free zones and high-speed rail concessions are dedicating expanded fixture space to impulse confectionery formats in Germany and Japan.
- Functional ingredient pipelines:Probiotic and zinc-infused breath freshener formulations are capturing oral-care crossover positioning in United States pharmacy channels.
Market Restraints
- Sugar alcohol supply concentration:Xylitol production clusters in Chinese corn-processing hubs, exposing formulators to input volatility and tariff friction.
- Novel food approval timelines:EFSA assessments for emerging sweeteners stretch 18-24 months, freezing pipeline launches for European market entrants.
- Plastic packaging restrictions:Single-use directive implementations across EU member states are forcing tin and paper format migrations that inflate unit costs.
Strategic Opportunities
- Indian modern trade penetration:Reliance Retail and DMart expansion into tier-2 cities creates underexploited distribution infrastructure for pouch-format mints.
- CBD and adaptogen convergence:Stress-relief positioning through ashwagandha and L-theanine infusions is opening wellness-adjacent category space in United States natural channels.
- Deposit-return scheme alignment:Germany's DRS expansion rewards reusable metal tin formats with preferential retail placement and reduced waste fees.
Industry Challenges
- Flavor stability shelf-life gaps:Natural citrus and herbal extracts degrade faster than synthetic alternatives, compressing distribution window assumptions.
- Co-manufacturer capacity constraints:Compressed tablet capacity at third-party facilities is extending lead times for limited-edition launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mints Market |
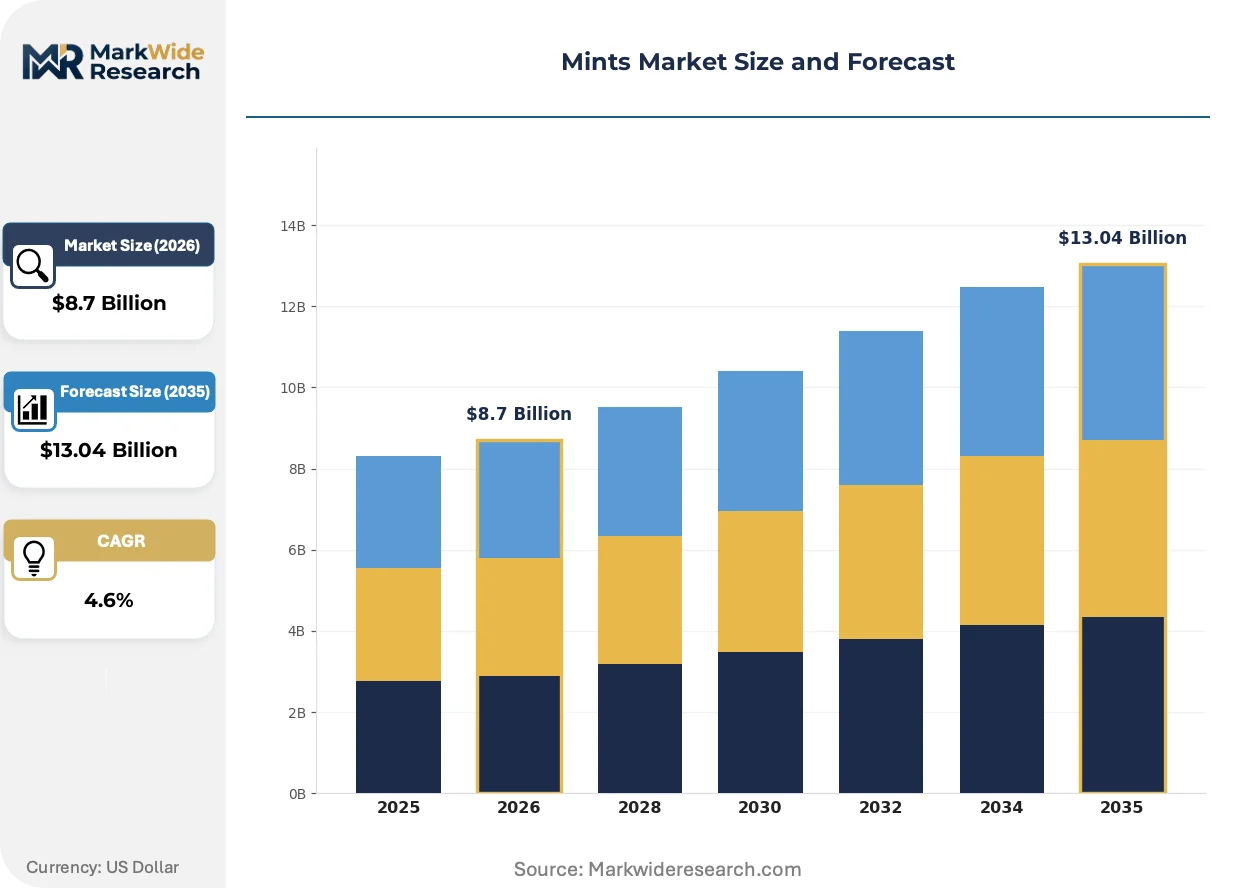
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Candies, Soft Mints, Breath Fresheners, Chewing Gums Flavor: Mint, Peppermint, Spearmint, Wintergreen Packaging Type: Bottles, Pouches, Tins, Sachets Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Vending Machines |
| Companies Covered | Perfetti Van Melle Holding B.V., Wrigley, Ferrero International S.A., Cloetta, Hershey, Mondelez International, Nestlé S.A., Haribo, Mars, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mints Market Strategic Shifts
Formulation transparency and packaging reusability are converging to redefine competitive differentiation, with digital traceability and on-demand production emerging as operational differentiators.
Direct compression tableting with continuous manufacturing is collapsing batch-to-batch variability while enabling real-time formulation adjustments. Mid-tier manufacturers are adopting these systems to compress new product introduction cycles from months to weeks. The technology is collapsing minimum viable scale thresholds, fragmenting production geography.
EFSA's 2023 updated guidance on sugar replacer health claims is tightening substantiation requirements for dental benefit positioning. Manufacturers must now commission clinical trials to maintain enamel protection claims on xylitol products. German and Dutch retail buyers are delisting SKUs that fail the new evidentiary standard.
Subscription replenishment models for home and office delivery are displacing traditional impulse-only purchase patterns. Amazon Subscribe & Save and HelloFresh add-on mechanics are capturing recurring mint consumption in United States households. Urban professionals in London and New York are driving the channel shift through workplace wellness program integrations.
Mints Market Segmentation
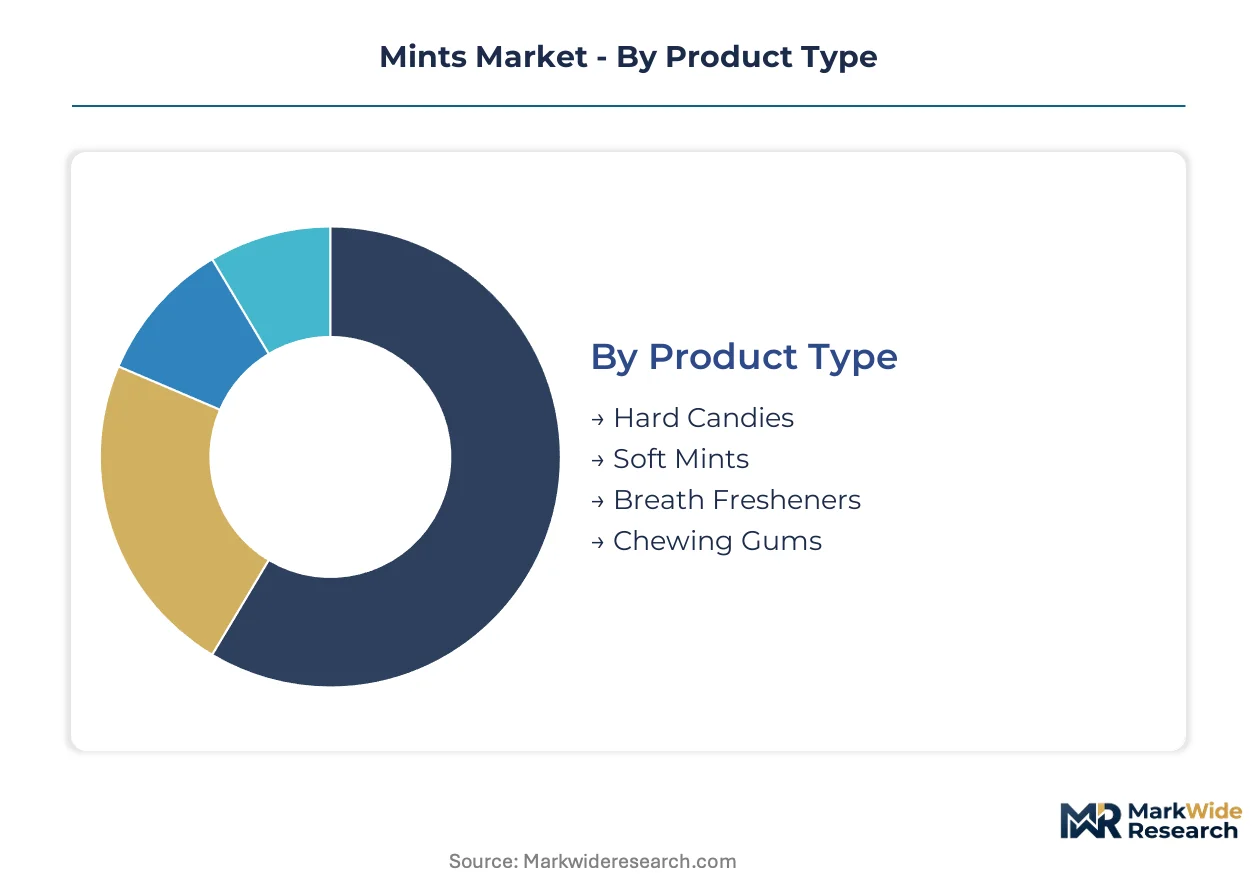
Mints manufacturers configure production lines around dissolution speed and impulse-versus-planned purchase patterns. Segment-level cycle times dictate inventory velocity, with checkout-adjacent formats turning over faster than pantry-stocking sizes.
Product Type:
Hard Candies and Soft Mints compress manufacturing cycles to weeks, while Breath Fresheners and Chewing Gums stretch pipeline timelines due to active ingredient stability testing.
- Hard Candies:Compressed sugar alcohol matrices with controlled crystallization deliver extended shelf stability and slow dissolution. Pharmacy chains in Germany stock these for enamel-protection positioning under EFSA's tightened health claim rules. Their formulation rigidity limits flavor innovation frequency.
- Soft Mints:Deposited or molded confections with higher moisture content create premium texture differentiation. Clean-label transitions in the United States favor these for natural sweetener compatibility, though shorter distribution windows strain retail replenishment systems.
- Breath Fresheners:Functional strips and sprays with zinc or probiotic actives targeting oral-care crossover segments.
- Chewing Gums:Elastic gum base formulations requiring specialized extrusion equipment and longer mixing cycles.
Hard Candies dominate installed base. Soft Mints is where expansion concentrates.
Flavor:
Flavor selection stratifies across cost tiers, with synthetic mint oils anchoring economy positioning and natural extracts commanding premium shelf placement.
- Mint:Generic menthol-synthetic blends serve as the category's volume foundation. Convenience stores in Japan rotate these through seasonal promotions tied to commute patterns and workplace consumption rituals.
- Peppermint:Higher menthofuran concentration delivers sharper sensory impact preferred in pharmacy and travel retail channels.
- Spearmint:Milder carvone-dominant profiles appeal to younger demographics and clean-label formulations in United States natural channels.
- Wintergreen:Methyl salicylate-derived profiles concentrated in North American markets with established medicinal positioning heritage.
Peppermint commands the largest volume position. Spearmint is climbing the fastest as natural positioning gains shelf space.
Packaging Type:
Packaging economics hinge on reusability mandates and single-use directive compliance, with metal and paper formats inflating unit costs against plastic alternatives.
- Bottles:Bulk polyethylene containers for pantry-stocking and office replenishment segments. Amazon Subscribe & Save mechanics in the United States favor these for home delivery economics, though plastic content faces EU regulatory pressure.
- Pouches:Flexible laminates with resealable zippers capturing on-the-go consumption in Indian modern trade expansion. Reliance Retail and DMart tier-2 city penetration favors this format for price accessibility and shelf efficiency.
- Tins:Reusable metal formats aligned with Germany's deposit-return scheme expansion and reduced waste fee structures.
- Sachets:Single-serve foil packets for hospitality and airline amenity channels.
Bottles dominate installed base. Tins is where expansion concentrates.
Distribution Channel:
Channel mix determines margin capture, with impulse formats sacrificing unit economics for velocity and subscription models trading frequency for retention.
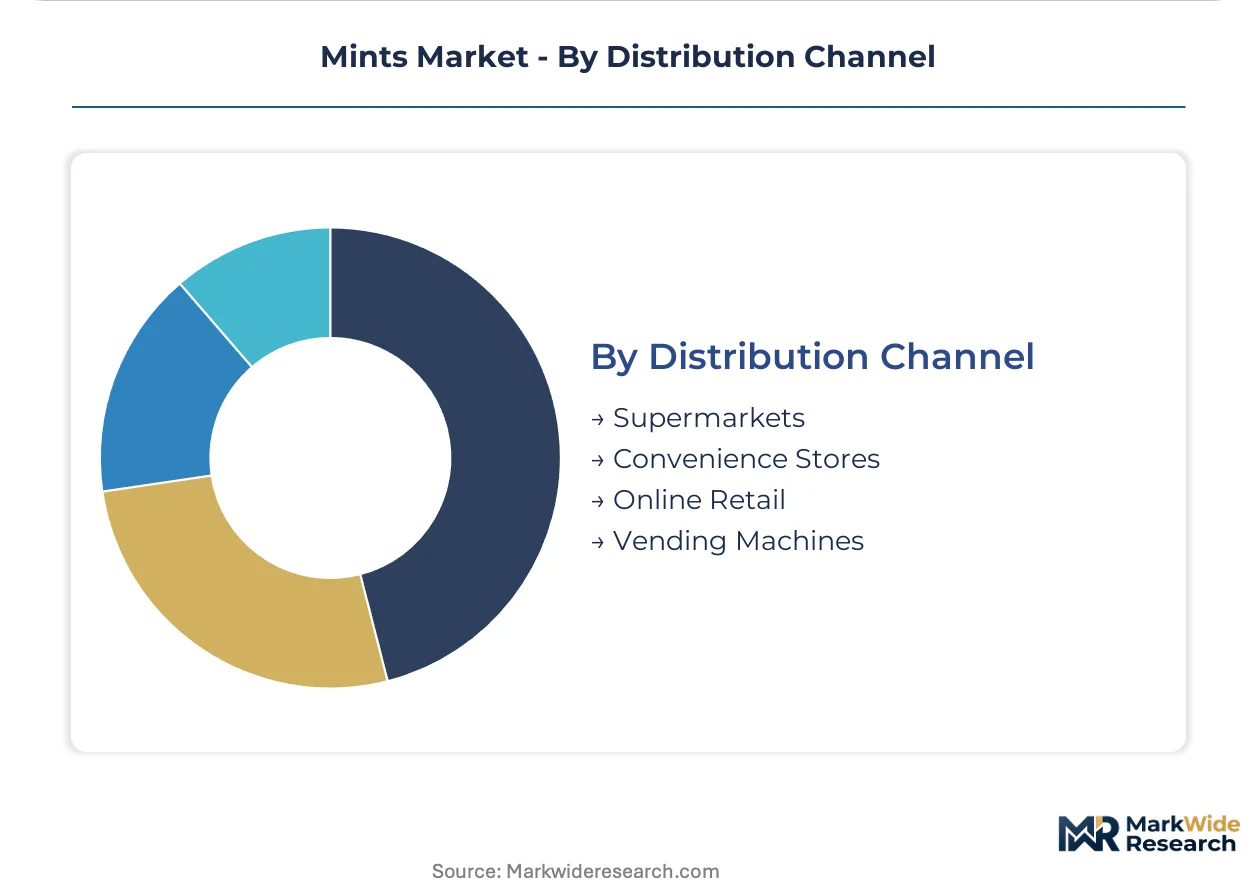
- Supermarkets:Planned purchase destination with expanded shelf space for functional and premium-positioned lines. EFSA nutrition scoring systems in European markets reward low-sugar SKUs with preferred placement.
- Convenience Stores:Front-of-store and checkout-adjacent fixtures driving impulse velocity. Wrigley's refrigerated rack systems sustain visibility in high-traffic United States retail zones.
- Online Retail:Amazon Subscribe & Save and direct-to-brand replenishment capturing recurring household consumption in London and New York workplace wellness integrations.
- Vending Machines:Compact format dominance in travel retail and rail concessions across Germany and Japan.
Supermarkets dominate installed base. Online Retail is gaining share fastest as subscription mechanics displace pure impulse patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food additive regulations anchor the United States as the dominant geography, with EFSA novel food assessments and FSSAI packaging standards creating parallel compliance frameworks across developed and emerging markets. Demand concentrates where on-the-go consumption patterns intersect with oral-care positioning and impulse retail infrastructure.
United States
Convenience store chains and pharmacy channels drive velocity through checkout-adjacent placement and workplace wellness program integrations. FDA enforcement of food additive regulations shapes sweetener approval pathways for xylitol and stevia formulations. Wrigley leverages refrigerated rack systems in high-traffic retail zones across metropolitan corridors.
Germany
Travel retail expansion in airport duty-free zones and high-speed rail concessions dedicates fixture space to impulse formats. EFSA's tightened health claim substantiation requirements under EU Green Deal nutrition scoring systems reward low-sugar SKUs with preferred supermarket placement. The country's deposit-return scheme expansion rewards reusable metal tin formats with reduced waste fees.
Japan
Commute patterns and workplace consumption rituals rotate seasonal promotions through convenience store networks. METI standards and consumer affairs agency labeling requirements govern functional ingredient claims for probiotic and zinc-infused breath fresheners. Tokyo and Osaka metropolitan areas concentrate vending machine density for compact format distribution.
India
Modern trade penetration by Reliance Retail and DMart into tier-2 cities creates underexploited distribution infrastructure for pouch-format mints. FSSAI enforces maximum residue limits and packaging material standards that constrain import flexibility and local formulation choices. Maharashtra and Gujarat industrial clusters host contract manufacturing capacity for flexible laminate production.
United Kingdom
Subscription replenishment models through Amazon Subscribe & Save and direct-to-brand mechanics capture recurring household consumption in London workplace wellness integrations. EFSA-aligned post-Brexit retained EU law maintains nutrition scoring systems that influence retail shelf economics. The Southeast England logistics corridor supports e-commerce fulfillment infrastructure for home delivery segments.
Mints Market Competitive Environment
Multinational confectionery conglomerates and regional specialists split the market between scale-driven formulation standardization and flavor innovation agility. The vendor base concentrates around parent company portfolio diversification rather than pure-play mint specialists. Three archetypes dominate: global FMCG majors leveraging cross-category distribution infrastructure, European heritage brands anchoring travel retail and premium positioning, and private-label manufacturers serving price-sensitive modern trade expansion. Competitive moves center on M&A for geographic footprint extension and strategic partnerships for co-manufacturer capacity access.
Within the multinational conglomerate tier, Perfetti Van Melle Holding B.V. and Ferrero International S.A. exemplify divergent strategic positioning. Perfetti Van Melle, a Dutch-Italian limited liability partnership, occupies a position emphasizing flavor innovation density through limited-edition release velocity across multiple regional markets simultaneously. Ferrero International S.A., a Luxembourg-based société anonyme, anchors compact format dominance in travel retail and vending channels through heritage brand architecture. Wrigley, a Delaware-incorporated subsidiary structure, represents the scale-driven end with refrigerated rack system deployments and cooler partnerships sustaining visibility in high-traffic United States retail zones.
| Leading Market Players |
|---|
| Perfetti Van Melle Holding B.V. |
| Wrigley |
| Ferrero International S.A. |
| Cloetta |
| Hershey |
| Mondelez International |
| Nestlé S.A. |
| Haribo |
| Mars, Incorporated |
| Others |
Value Chain & Pricing Dynamics
The Rotterdam-Antwerp petrochemical corridor's freight cost volatility compresses margin pools for European formulators while amplifying price spreads between standard sugar-alcohol formulations and premium natural-extract lines. Xylitol shipments from Chinese corn-processing hubs face tariff friction that forces downstream buyers into longer contract tenors or spot-market exposure, restructuring procurement economics across the category.
Pricing Analysis
The customization-premium spread separates configured-to-order clean-label SKUs from mass-market synthetic formulations by 40-60% at shelf. Three-tier pricing structure across premium, standard, and economy levels anchors the category: economy tiers rely on sorbitol and synthetic mint oils, standard tiers blend xylitol with natural flavoring, and premium tiers command stevia-allulose positioning with probiotic actives. Pricing pressure stems from EFSA's tightened health claim substantiation requirements, which force clinical trial investments that compress mid-tier margins. Pharmacy channel buyers in Germany exhibit lowest price sensitivity due to oral-care crossover positioning, while Indian modern trade purchasers in tier-2 cities drive aggressive pouch-format negotiation.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk profiles for xylitol-dependent formulators. Production gravity centers on Chinese corn-processing clusters, United States sorbitol refineries, and Indian flexible-laminate packaging corridors. Raw material flows draw from corn-derived polyols, natural mint oils from India and the United States, and specialty probiotic cultures from Danish and Dutch fermentation facilities. Single-source vulnerability concentrates in Chinese xylitol capacity, where environmental compliance shutdowns trigger 90-day replenishment gaps. Distribution runs through co-manufacturer networks for compressed tablets, with third-party facilities in Maharashtra and Gujarat extending lead times for limited-edition launches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription replenishment mechanics for home and office delivery represent a service-attach layer expanding faster than impulse-format hardware, capturing recurring revenue through Amazon Subscribe & Save and workplace wellness program integrations.
For Market Incumbents: Entrench pharmacy channel positioning by accelerating clinical trial investments for EFSA-compliant enamel protection claims before delisting deadlines hit. Secure co-manufacturer capacity through equity stakes or long-term offtake agreements in Maharashtra and Gujarat clusters to defend against lead-time extension for limited-edition velocity. Counter private-label encroachment in Indian modern trade by front-loading Reliance Retail and DMart shelf-space investments with promotional co-op funding.
For New Entrants and Emerging Players: Tier-2 Indian cities with underpenetrated Reliance Retail and DMart infrastructure represent the most penetrable entry point for pouch-format mints at price points 30% below multinational standard tiers. German deposit-return scheme alignment for reusable metal tins offers regulatory-arbitrage positioning with preferential retail placement and reduced waste fees. Direct-to-brand subscription mechanics bypassing Amazon's take rates capture London and New York workplace wellness integrations with higher lifetime value economics.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational confectionery conglomerates divesting non-core mint portfolios to focus on chocolate and gum core competencies. Five-to-ten-year viability hinges on clean-label transition completion and functional ingredient pipeline depth rather than impulse-format scale. Monitor EFSA novel food approval timelines for emerging sweeteners as inflection indicators: accelerated approvals signal formulation flexibility expansion, while extended 24-month assessments compress pipeline optionality for European market entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Formulation Transition | EFSA's tightened health claim rules reward natural sweetener investments with preferred pharmacy placement. |
| Subscription Replenishment Launch | Amazon Subscribe & Save mechanics capture recurring household consumption in London and New York workplace integrations. |
| Co-Manufacturer Capacity Lock-Up | Equity stakes in Maharashtra and Gujarat tablet-compression facilities secure limited-edition launch velocity. |
| Deposit-Return Scheme Alignment | Germany's DRS expansion rewards reusable metal tin formats with reduced waste fees and preferential retail fixture access. |
| Functional Ingredient Pipeline | Probiotic and zinc-infused formulations capture oral-care crossover positioning in United States pharmacy channels. |
Study Parameters
Cross-validation between Nielsen retail audit data and customs import records anchors the qualitative findings on channel mix and geographic demand concentration. Primary interviews with brand managers at multinational confectionery conglomerates, category buyers at Reliance Retail and DMart, supply planners at flexible-laminate manufacturers, and regulatory affairs leads navigating EFSA and FSSAI frameworks informed competitive positioning and compliance pathway assessments. Secondary sources include FDA food additive filings, EFSA novel food assessment databases, FSSAI packaging standard circulars, and SEC 10-K disclosures from listed parent companies. Bottom-up demand modeling triangulates against top-down category value estimates.
Calibration against historical volume trajectories and elasticity-adjusted price response curves shapes the analytical framework across the analysis window. Segmentation dimensions span product type (hard candies, soft mints, breath fresheners, chewing gums), packaging format (bottles, pouches, tins, sachets), distribution channel (supermarkets, convenience stores, online retail, vending machines), and flavor profile (mint, peppermint, spearmint, wintergreen). CAGRs derive from trend-line extrapolation with regulatory inflection adjustments and channel-shift coefficients. Industry-specific inputs include EFSA approval timeline distributions for novel sweeteners and co-manufacturer capacity utilization rates in Indian contract manufacturing clusters.
Practitioners should monitor EFSA enforcement patterns on health claim substantiation and Chinese environmental compliance shutdowns in corn-processing hubs for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Sugar-Free Gumballs Market
Confectionery
China Chocolate Market
Confectionery
Low Calorie Nutella Market
Confectionery
Middle East Chocolate Market
Confectionery
Liquorice Shellac Market
Confectionery
Premium Chocolate Market
Confectionery
Infused Fruits Jellies Market
Confectionery
Dark Chocolate Market
Confectionery
Black Treacle Market
Confectionery
Europe Confectionery Market
Confectionery
Sugar-Free Gummy Market
Confectionery
North America Compound Chocolate Market
Confectionery
Bangladesh Candy Market
Confectionery
North America Dark Chocolate Market
Confectionery
Bean-To-Bar Chocolate Market
Confectionery
Sugar Free Lollipops Market