
 Boiled-Cooked Icing Market | 2026-2036
Boiled-Cooked Icing Market Size, Share, and Industry Trends Forecast 2026-2036
Boiled-Cooked Icing Market Analytics
Aftermarket technical support for icing formulation troubleshooting is narrowing as manufacturers shift margin pools toward proprietary base mixes and concentrated stabilizer systems. Rich Products Corporation leverages its frozen dough and icing integration to control bakery supply chain touchpoints. CSM Bakery Solutions anchors European artisan and industrial bakery channels with specialized fat-based icing platforms. Dawn Food Products competes through extensive North American distribution and technical service infrastructure for commercial bakers.
Boiled-cooked icing comprises sugar syrup heated to precise temperature stages before incorporation into fat or egg-based matrices, yielding stable, glossy coatings with controlled crystallization and extended shelf stability. The process demands exact thermal management, typically reaching 112–116°C for thread-stage syrups that provide structural integrity in finished decorations. Buttercream formulations dominate commercial volume due to operational familiarity and cost efficiency across bakery and confectionery applications. Fondant segments command premium positioning in specialty cake decoration, while whipped cream variants face perishability constraints that limit broad food-service penetration despite home baking interest.
FDA food additive regulations and USDA dairy grading standards govern ingredient declarations and fat content classifications in the United States, directly affecting product labeling and interstate commerce eligibility. EU EFSA sweetness additive evaluations and F-Gas Regulation compliance requirements for cold-chain distribution shape formulation and logistics decisions across European markets. Stakeholders must monitor evolving clean-label enforcement thresholds and alternative sweetener approval pathways to anticipate reformulation costs and regional market access conditions.
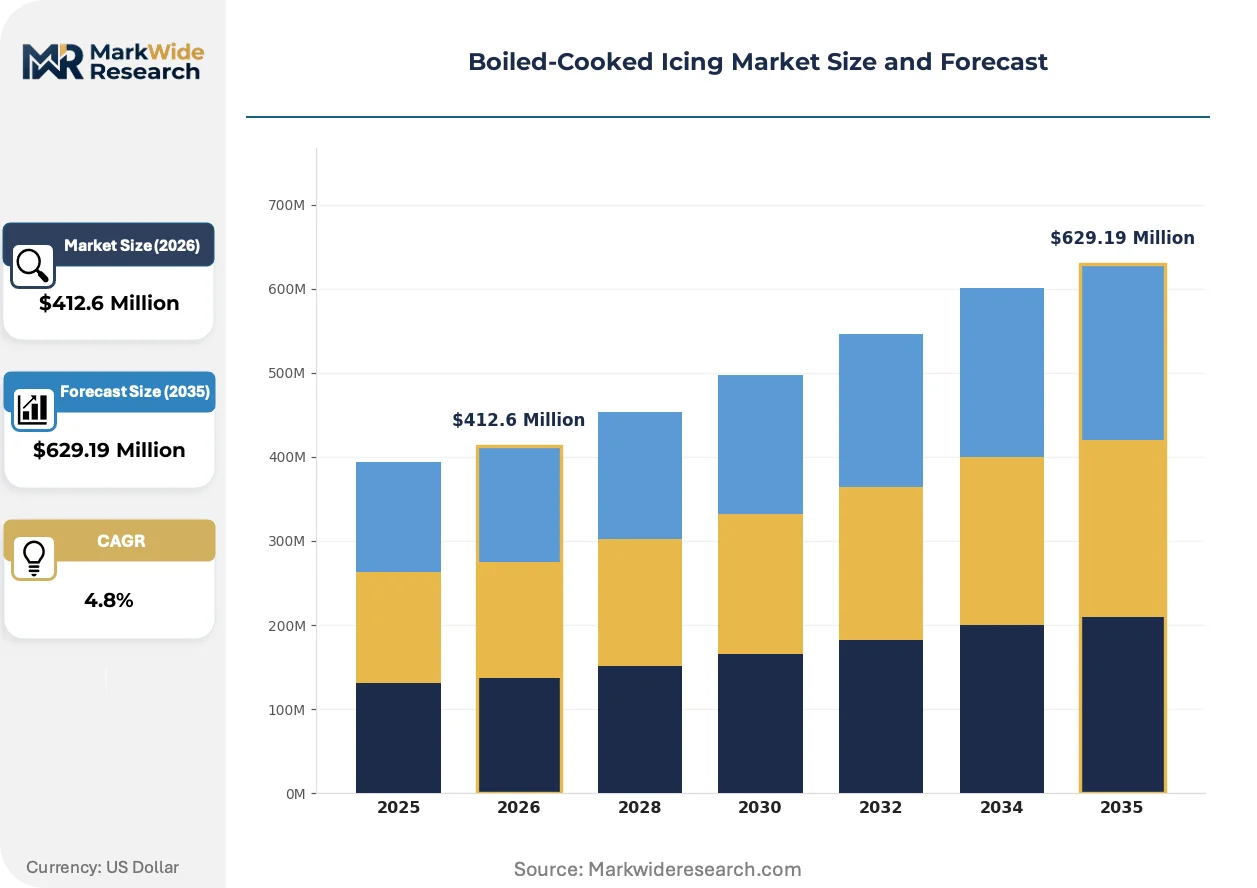
Market Dynamics
Bakery chains and pastry shops are consolidating procurement around proprietary base mixes and concentrated stabilizer systems, compressing margins for standalone icing suppliers while shifting technical support burdens upstream to ingredient manufacturers.
Growth Catalysts
- Clean-label mandates:FDA and EU EFSA requirements for simplified ingredient declarations are accelerating reformulation investments, opening premium positioning for stabilizer systems that eliminate artificial additives.
- Artisan bakery expansion:Germany, France, and the United States are witnessing concentrated demand growth in craft baking segments that prioritize scratch-quality finishes from prepared solutions.
- Frozen dough integration:Co-packing arrangements between icing suppliers and frozen bakery platforms are reducing distribution costs while ensuring formulation compatibility across cold-chain logistics.
Market Restraints
- Input cost volatility:Sugar and dairy fat price swings compress margins for manufacturers lacking long-term commodity hedging capabilities or backward integration into ingredient sourcing.
- Supply concentration risk:European stabilizer and specialty fat suppliers dominate high-performance icing formulations, creating vulnerability for North American manufacturers dependent on transatlantic ingredient flows.
- Perishability constraints:Whipped cream-based variants face inherent shelf-life limitations that restrict food-service penetration despite sustained home baking interest.
Strategic Opportunities
- Alternative sweetener pathways:EU EFSA evaluation timelines for novel sweeteners are creating first-mover windows for manufacturers prepared to submit dossiers ahead of competitive filings.
- Plant-based fat platforms:Convergence of enzymatic interesterification and oleogelation technologies is enabling clean-label alternatives to hydrogenated fats without compromising crystallization control.
- Direct-to-bakery digital channels:Specialized e-procurement platforms are disintermediating traditional ingredient distributors for mid-sized artisan operations seeking technical consultation alongside order fulfillment.
Industry Challenges
- Thermal process expertise gaps:Precise syrup-stage control demands skilled operators capable of managing 112–116°C thread-stage targets, creating hiring bottlenecks for scaled production facilities.
- Reformulation timeline compression:Accelerating clean-label enforcement thresholds from FDA and EU EFSA are forcing simultaneous label updates across multiple product lines without extended transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boiled-Cooked Icing Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Buttercream, Fondant, Meringue, Whipped Cream Application: Bakery, Confectionery, Catering, Home Baking Distribution Channel: Online, Supermarkets, Specialty Stores, Food Service End User: Bakers, Chefs, Consumers, Pastry Shops |
| Companies Covered | Rich Products Corporation, Betty Crocker, CSM Bakery Solutions, Dawn Food Products, Wilton Industries, Lawrence Foods, Pinnacle Foods, Macphie, Fruit Fillings Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boiled-Cooked Icing Market Evolving Landscape
Digital formulation tools and precision thermal management systems are compressing development cycles while regulatory pressure on ingredient transparency is reshaping competitive positioning across bakery supply chains.
Enzymatic interesterification is virtualizing traditional fat-blending operations by enabling precise control over triglyceride structure without chemical processing. Artisan and industrial bakeries alike are adopting these enzymatic systems to achieve clean-label credentials previously requiring premium-priced specialty fats. The technology is virtualizing capital-intensive hydrogenation infrastructure, allowing mid-scale manufacturers to compete on formulation sophistication rather than asset scale.
EU F-Gas Regulation compliance requirements are forcing cold-chain logistics providers to retrofit refrigeration systems, directly affecting frozen icing distribution economics across European markets. Manufacturers are responding by reformulating for ambient stability where possible and consolidating production footprints to minimize transport refrigeration exposure. Germany and France exhibit the most acute adjustment pressure given their concentration of artisan bakery cold-chain dependencies.
Home baking subscription services are fragmenting traditional food-service procurement patterns by delivering pre-portioned icing components directly to consumers. These direct-to-consumer channels are displacing conventional retail formats for specialty decoration products, particularly in the United States where digital-native bakery brands have established fulfillment infrastructure. The shift is most pronounced in fondant and decorative sugar categories where portion control and storage convenience outweigh bulk pricing advantages.
Boiled-Cooked Icing Market Segmentation
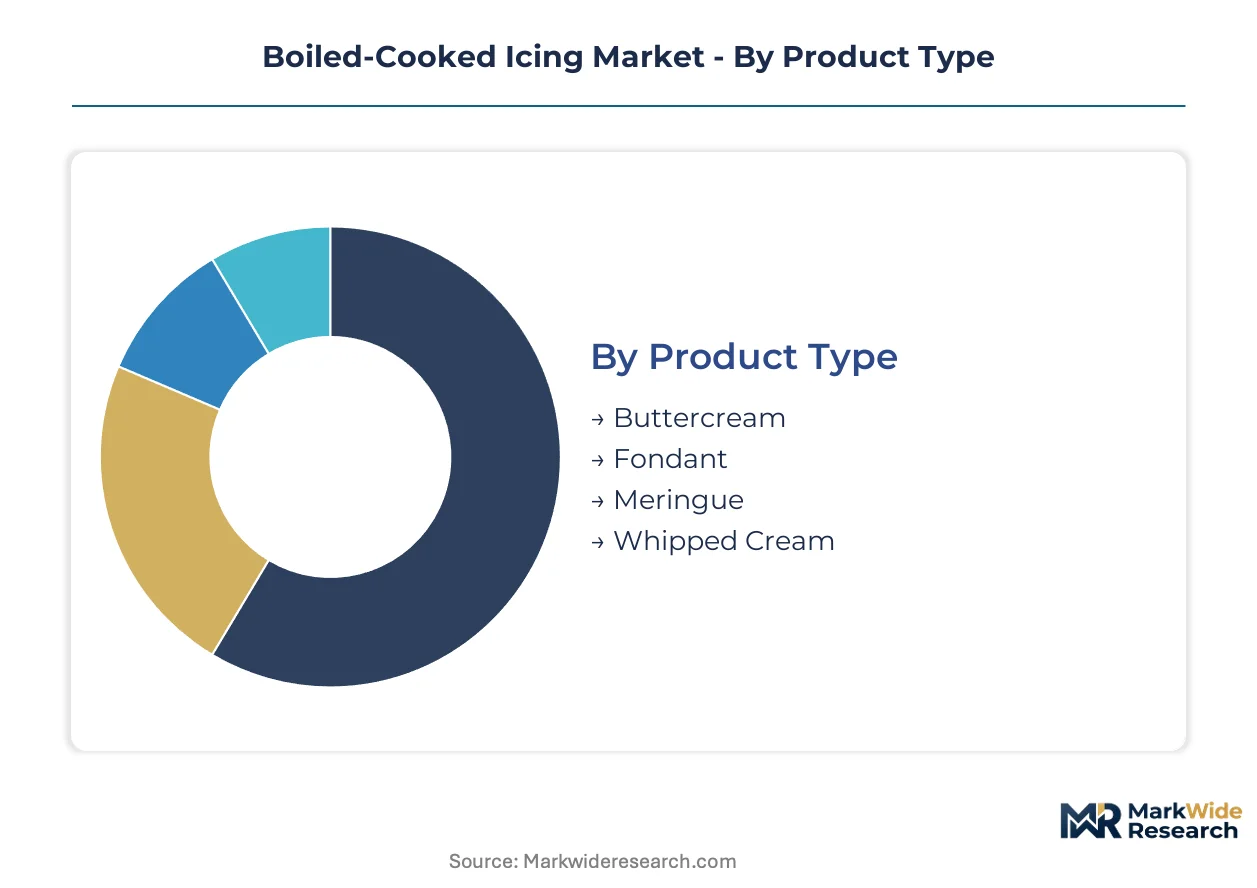
Boiled-cooked icing formulations diverge sharply across thermal processing requirements, end-use performance standards, and procurement channel economics. Manufacturers must align production capabilities with segment-specific crystallization control and shelf-stability demands to capture margin pools effectively.
Product Type:
Cost tier differentiation separates commodity formulations from precision-controlled premium variants requiring exact thermal stage management.
- Buttercream:Fat-sugar emulsions with controlled crystallization dominate commercial bakery procurement due to operational familiarity and cost efficiency. Demand concentrates in United States bakery chains seeking standardized finishes across multi-location operations with compressed labor training requirements.
- Fondant:Sugar-water-gelatin matrices rolled or poured for flawless surface coverage command premium positioning in specialty cake decoration. Germany and France exhibit concentrated artisan bakery demand for fondant systems delivering scratch-quality aesthetics from prepared bases.
- Meringue:Egg white-sugar foam structures require precise thermal incorporation for stability.
- Whipped Cream:Perishable dairy-fat foams face inherent shelf-life constraints limiting food-service penetration.
Buttercream commands the established base. The steepest expansion runs through Fondant.
Application:
Volume concentration patterns reflect divergent operational scale and technical sophistication requirements across end-use environments.
- Bakery:Industrial and artisan producers drive bulk procurement of stabilized icing systems compatible with automated depositing equipment. United States commercial bakeries prioritize formulations integrating seamlessly with frozen dough platforms to reduce distribution complexity.
- Confectionery:Precision coating applications for enrobed products and molded pieces demand exact viscosity control and thermal stability. European manufacturers face EU EFSA clean-label mandates accelerating reformulation toward enzymatically interesterified fat bases.
- Catering:Event-scale production requires ambient-stable formulations with extended holding capacity.
- Home Baking:Pre-portioned convenience formats are displacing bulk retail through digital-native subscription channels.
Bakery anchors volume concentration. Confectionery is climbing the fastest as clean-label premiums expand addressable margins.
Distribution Channel:
Customer type fragmentation is reshaping procurement pathways as digital platforms disintermediate traditional ingredient distributors.
- Online:Direct-to-bakery e-procurement platforms combine technical consultation with order fulfillment for mid-sized artisan operations. United States digital-native brands have established fulfillment infrastructure capturing home baking subscription growth.
- Supermarkets:Mass retail formats concentrate consumer-packaged goods volume for home baking applications.
- Specialty Stores:Professional baking supply channels serve artisan producers requiring technical support alongside ingredient procurement.
- Food Service:Broadline distributors face margin compression as bakery chains consolidate procurement around proprietary base mixes.
Supermarkets retain the volume base. Online channels are gaining share fastest through technical service bundling.
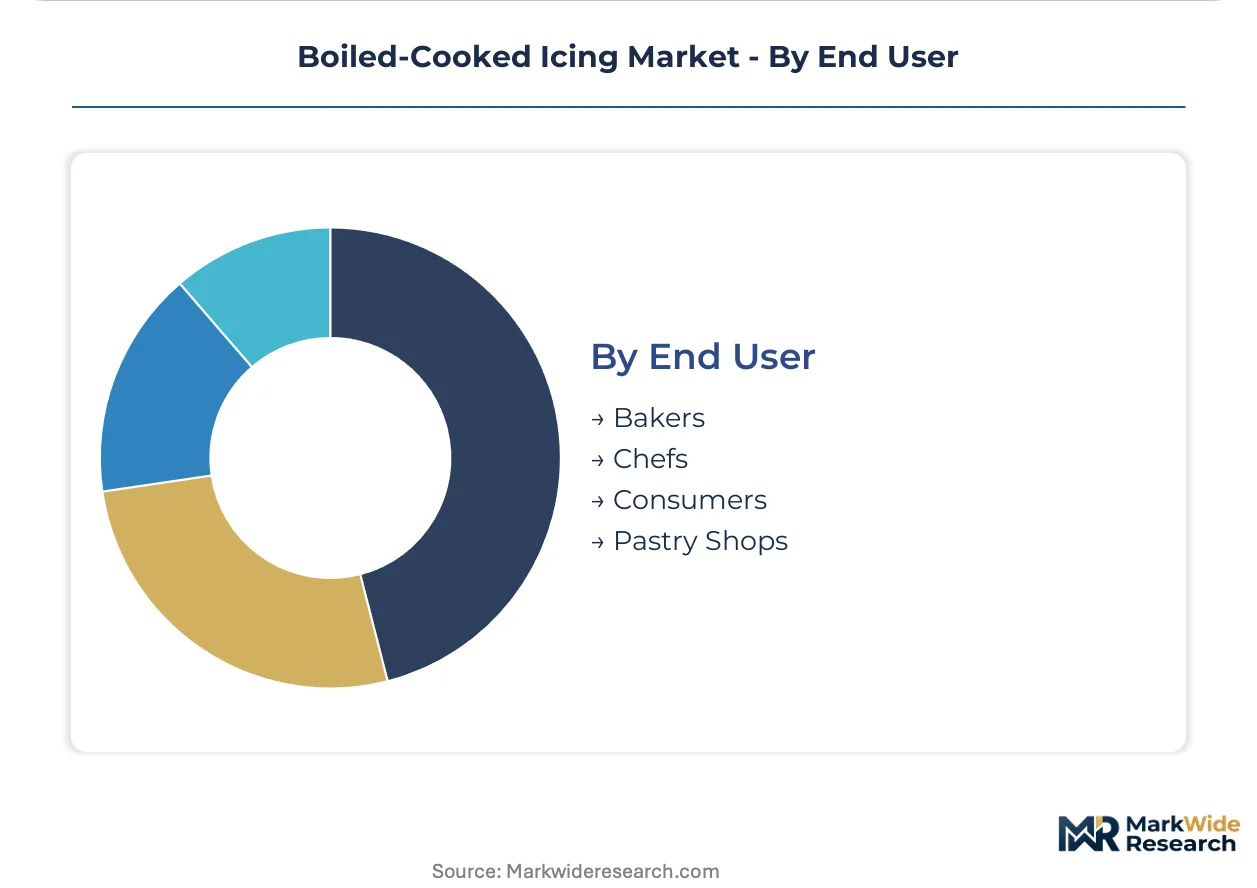
End User:
Margin structure varies sharply across technical sophistication requirements and procurement scale economics.
- Bakers:Industrial and artisan production facilities demand formulation consistency across batch scales with documented thermal process parameters. FDA food additive regulations govern ingredient declarations affecting interstate commerce eligibility for multi-state operations.
- Chefs:Fine dining and hotel pastry operations prioritize finishing flexibility and plate-up performance over unit cost.
- Consumers:Home baking segments exhibit price sensitivity but willingness to pay premiums for convenience and portion control.
- Pastry Shops:Specialty retail operations balance display aesthetics with production efficiency requirements.
Bakers represent the core revenue base. Pastry shops are expanding most quickly as artisan bakery formats proliferate in urban clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across major markets. German artisan bakers absorb premium formulation costs while United States bakery chains prioritize procurement standardization. Demand concentrates where frozen dough integration and clean-label mandates intersect.
United States
Frozen dough platform integration drives procurement consolidation among bakery chains seeking supply chain simplification. FDA food additive regulations and USDA dairy grading standards govern interstate commerce eligibility and fat content classifications. Chicago and New York metro areas anchor industrial bakery concentration with automated depositing equipment deployment.
Germany
Artisan bakery expansion prioritizes scratch-quality finishes from prepared fondant and buttercream bases. EU EFSA clean-label requirements and F-Gas Regulation compliance reshape cold-chain logistics and formulation standards. Munich and Stuttgart clusters exhibit concentrated demand for premium decoration systems in craft baking segments.
France
Specialty cake decoration demand concentrates in Paris and Lyon artisan retail formats. EU EFSA sweetness additive evaluations create reformulation timelines affecting regional market access. Bordeaux and Toulouse pastry shops drive fondant volume through display aesthetics requirements.
United Kingdom
Home baking subscription channels fragment traditional procurement through digital-native fulfillment infrastructure. UK Food Standards Agency labeling requirements intersect with evolving clean-label enforcement thresholds. London and Birmingham anchor commercial bakery scale operations with multi-location standardization needs.
Canada
Cross-border ingredient flows from United States suppliers dominate stabilizer and specialty fat procurement. Health Canada and PMRA govern additive declarations affecting product labeling compliance. Toronto and Montreal clusters balance artisan format growth with industrial bakery consolidation.
Boiled-Cooked Icing Market Competitive Landscape
Vertically integrated frozen bakery platforms and specialized ingredient manufacturers split the market between supply chain control and formulation expertise. Concentration is moderate with tiered competition across premium stabilizer systems and commodity buttercream bases. Three archetypes dominate: frozen dough integrators, European fat-based specialists, and North American distribution-heavy suppliers. Competitive moves center on proprietary base mix development and enzymatic fat technology licensing.
Among the frozen dough integrators, Rich Products Corporation exemplifies supply chain touchpoint control through captive icing and bakery platform coordination. CSM Bakery Solutions anchors European artisan and industrial channels with specialized fat-based formulation capabilities. Dawn Food Products occupies a position defined by extensive North American distribution infrastructure and technical service bundling for commercial bakers.
| Leading Market Players |
|---|
| Rich Products Corporation |
| Betty Crocker |
| CSM Bakery Solutions |
| Dawn Food Products |
| Wilton Industries |
| Lawrence Foods |
| Pinnacle Foods |
| Macphie |
| Fruit Fillings Inc |
| Others |
Value Network & Pricing Analysis
Transatlantic freight corridors between Rotterdam and New York Harbor govern landed cost differentials for European stabilizer imports, compressing margins for North American manufacturers while enabling premium pricing for EU-sourced specialty fat systems in artisan bakery segments.
Pricing Analysis
After-sales technical service contracts drive lifetime value capture for icing formulation suppliers, with three-tier pricing structure across premium enzymatic-fat platforms, standard buttercream bases, and economy commodity blends. Price differentiation rests on clean-label certification tiers and frozen dough integration compatibility, with cost compression in standard tiers intensifying due to bakery chain procurement consolidation. Industrial bakers exhibit highest price sensitivity; artisan pastry shops absorb premiums for scratch-quality finishes.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates input cost volatility for North American manufacturers dependent on transatlantic specialty fat flows. Supply concentrates in Germany, France, and the Netherlands for high-performance stabilizer systems, while sugar and dairy fat sourcing draws from domestic agricultural bases. Single-source vulnerability pervades enzymatic interesterification catalyst supply. Distribution runs through frozen dough co-packing networks and direct-to-bakery digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label regulatory mandates from FDA and EU EFSA are accelerating formulation disruption, creating first-mover windows for enzymatic fat technology adopters and compressing timelines for legacy hydrogenated-fat dependent suppliers.
For Market Incumbents: Insulate margin pools by backward integration into enzymatic interesterification catalyst production and captive stabilizer manufacturing in Germany or the Netherlands. Secure exclusive co-packing arrangements with frozen dough platforms before competitor consolidation locks out access. Regulatory shift toward F-Gas Regulation compliance in EU cold-chain logistics threatens distribution economics for non-reformulated product lines. For New Entrants and Emerging Players: Pursue white-space opportunities in direct-to-bakery digital procurement channels serving mid-sized United States artisan operations lacking technical support from incumbent distributors. Target home baking subscription segments with pre-portioned fondant and decorative sugar kits. Go-to-market through social-native bakery influencers bypassing traditional food-service distributor gatekeepers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food ingredient conglomerates with underperforming icing divisions lacking frozen dough integration capabilities. Long-term viability favors suppliers with enzymatic fat technology licensing positions and clean-label regulatory dossiers already filed. Watch EU EFSA novel sweetener approval timelines as inflection signal for reformulation cost spikes and competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Fat Technology Licensing | Enables clean-label positioning without hydrogenation infrastructure investment. |
| Frozen Dough Co-Packing Partnership | Reduces distribution complexity through integrated cold-chain logistics with bakery platforms. |
| Direct-to-Bakery Digital Platform Launch | Disintermediates traditional distributors for mid-sized artisan operations seeking technical consultation. |
| EU EFSA Dossier Pre-Submission | Captures first-mover advantage on novel sweetener approvals ahead of competitive filings. |
| Backward Integration into Stabilizer Production | Mitigates transatlantic supply concentration risk for North American manufacturers. |
Research Methodology
Cross-validation between primary interviews with bakery chain procurement directors, artisan pastry shop owners, frozen dough platform engineers, and stabilizer R&D specialists and secondary validation through FDA food additive filings, EU EFSA sweetness additive evaluations, USDA dairy grading standards, and customs trade data anchors the qualitative findings. Bottom-up segment sizing triangulates against top-down market value reconstruction.
Calibration against historical volume trajectories in buttercream, fondant, and whipped cream categories shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, application, distribution channel, and end-user archetype with regional regulatory cluster overlays. CAGRs derive from slope analysis of ingredient cost pass-through elasticities and frozen dough integration adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by enzymatic technology licensors or frozen dough integrators would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
CBD-Infused Confectionery Market
Confectionery
Middle East and Africa Chocolate Market
Confectionery
China Chocolate Market
Confectionery
Middle-East and Africa Compound Chocolate Market
Confectionery
Global Industrial Chocolate Market
Confectionery
Sugar Free White Chocolate Market
Confectionery
Low-Calorie Dark Chocolate Market
Confectionery
UK Confectionery Market
Confectionery
Fat Free Candy Market
Confectionery
Gummy Candy Market
Confectionery
Ruby Chocolate Market
Confectionery
Dark Chocolate Market
Confectionery
Asia Pacific Sugar Confectionery Market
Confectionery
Macarons Market
Confectionery
Chocolate Inclusions and Decorations Market
Confectionery
Mints Market